
 Animal Feed and Pet Food Market | 2026-2036
Animal Feed and Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed and Pet Food Market Analysis
Brazilian soybean meal exports is realigning global protein sourcing for compound feed mills. Mars Petcare Inc. leverages its veterinary prescription channel to sustain premium pricing power across therapeutic nutrition lines. Nestlé Purina PetCare anchors North American distribution through mass retail partnerships and dedicated e-commerce fulfillment networks. Hill's Pet Nutrition differentiates on clinical validation, competing directly with veterinary clinic dispensing models.
Animal feed and pet food encompasses formulated nutritional products designed to deliver complete or supplementary diets to livestock, poultry, aquaculture species, and companion animals, typically specified by minimum crude protein, fat, fiber, and moisture content alongside vitamin and mineral premix inclusion rates. Manufacturing employs extrusion for dry kibble, retort sterilization for wet canned products, and cold-press pelleting for ruminant forage supplements to achieve target digestibility coefficients and shelf stability. Kibble dominates volume throughput due to manufacturing efficiency and logistics economy, while wet food commands disproportionate margin pools from aging pet demographics and palatability-driven purchasing. Treats and supplements represent the fastest-expanding product type as functional health claims around joint support, digestive health, and anxiety management reshape household spending patterns.
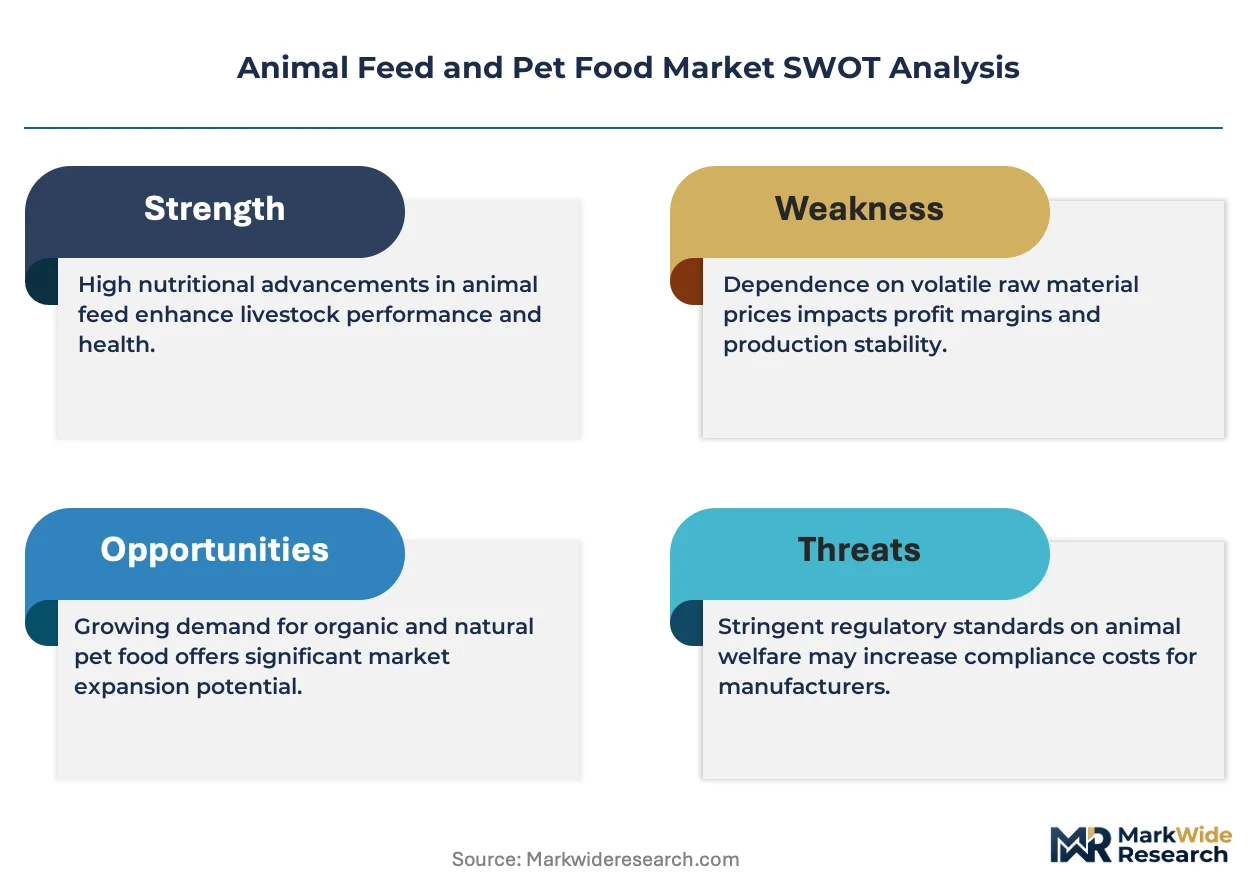
The FDA's Food Safety Modernization Act provisions for animal food, the EU's Feed Hygiene Regulation 183/2005, and China's GB standards for feed labeling collectively elevate barrier costs for new entrants while forcing incumbent reformulation cycles. These frameworks shape demand by mandating traceability systems, contaminant thresholds, and substantiated nutritional claims that favor capital-intensive producers with dedicated quality assurance infrastructure. Stakeholders must monitor emerging microbiome research and alternative protein regulatory classifications as these domains determine next-generation product registration pathways and consumer acceptance thresholds.
Market Dynamics
Protein sourcing concentration in Brazilian soybean meal is forcing compound feed mills to reconfigure procurement networks and absorb freight cost volatility into margin structures.
Growth Catalysts
- EU Feed Hygiene Regulation 183/2005:Mandatory traceability systems favor capital-intensive producers with dedicated quality infrastructure, consolidating market share among compliant operators.
- Insect protein cultivation:Black soldier fly larvae farming is scaling as a permitted feed ingredient class, reducing dependency on conventional fishmeal and soybean derivatives.
- China:Livestock consolidation into integrated protein complexes concentrates demand for precision-formulated compound feeds with premix inclusion rates above 5%.
Market Restraints
- Soybean meal price volatility:Brazilian export realignment exposes mills to currency fluctuation and port congestion risk, compressing formulation flexibility.
- Alternative protein regulatory lag:Cultivated meat and single-cell protein face prolonged novel food approval timelines under FDA and EFSA frameworks, delaying commercial feed integration.
- Phosphorus supply concentration:Moroccan and Chinese phosphate rock dominance creates input cost vulnerability for mineral premix manufacturers.
Strategic Opportunities
- India:Underpenetrated companion animal nutrition offers white space as pet humanization accelerates in tier-1 cities with disposable income growth.
- Microbiome modulation:Postbiotic and synbiotic feed additives command premium positioning as gut health claims substantiate through clinical validation.
- Veterinary dispensing channel:Prescription therapeutic nutrition bypasses price transparency of mass retail, sustaining margin pools for clinically validated formulations.
Industry Challenges
- Extrusion engineering talent scarcity:Specialized process engineers capable of optimizing digestibility coefficients and shelf stability command premium compensation, constraining capacity expansion.
- Dual certification burden:Simultaneous FDA FSMA compliance and EU 183/2005 alignment stretches quality assurance teams at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed and Pet Food Market |
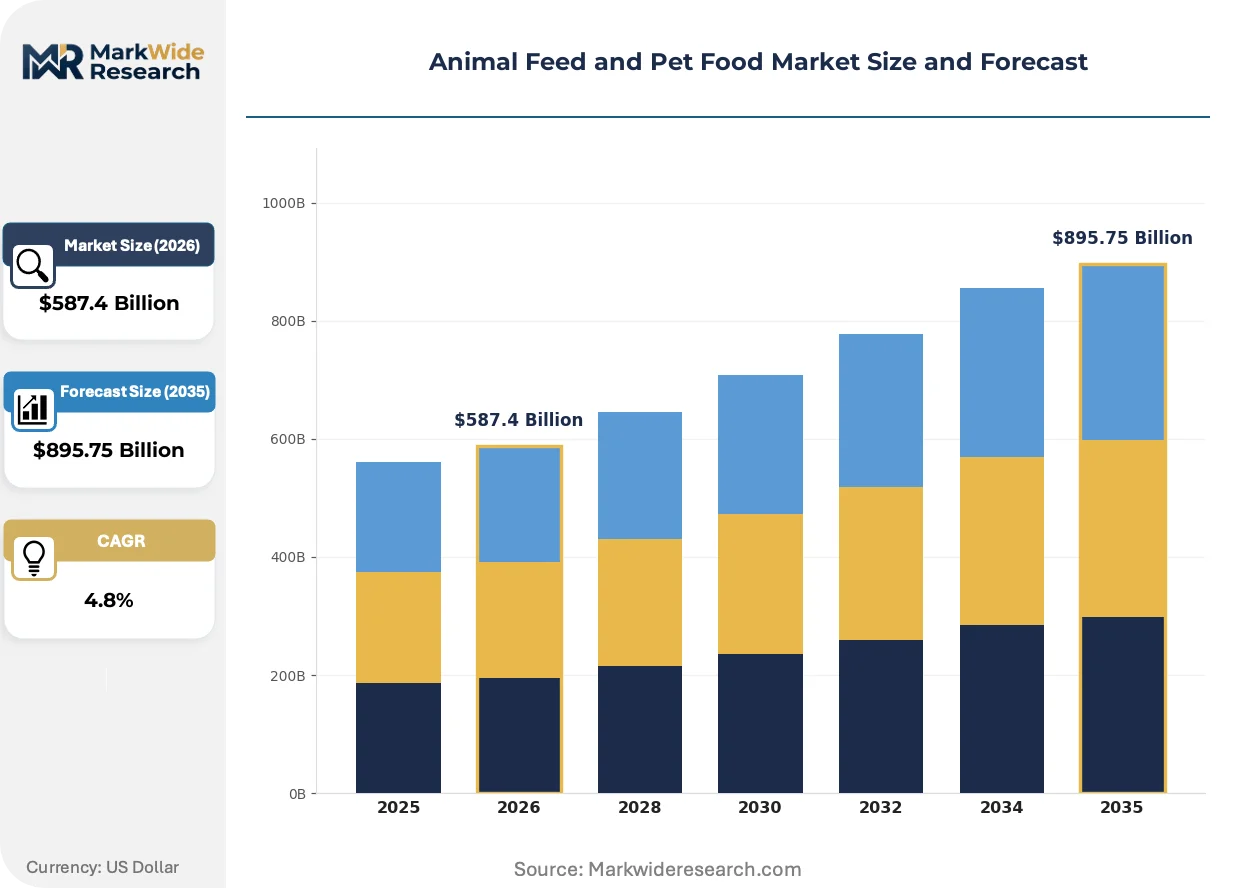
| Market Size in 2026 | $587.4 Billion |
| Market Size in 2035 | $895.75 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kibble, Wet Food, Treats, Supplements Ingredient Type: Meat, Grains, Vegetables, Additives End User: Households, Farms, Veterinary Clinics, Pet Retailers Packaging Type: Bags, Cans, Pouches, Bulk |
| Companies Covered | J.M. Smucker, Blue Buffalo, Mars Petcare Inc., WellPet, Diamond Pet Foods, Nestlé Purina PetCare, General Mills, Spectrum Brands/United Pet Group, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed and Pet Food Market Emerging Trajectories
Precision fermentation and cellular agriculture are absorbing capital allocation previously directed toward conventional ingredient processing, while regulatory frameworks race to classify novel protein sources.
Single-cell protein derived from methanotrophic bacteria is absorbing research investment from aquaculture feed formulators seeking to decouple fishmeal supply from wild-catch volatility. Norwegian salmon producers are piloting inclusion rates above 20% in grower diets. This absorption is compressing the addressable market for Peruvian anchovy meal traders.
REACH registration requirements for novel feed additives are forcing ingredient suppliers to front-load toxicology expenditure before commercial scale-up. The industrial consequence is a winnowing of innovation pipelines to well-capitalized multinationals. Aquaculture premix manufacturers in Northern Europe are responding by consolidating formulation partnerships to share registration costs.
Subscription-based pet food replenishment is displacing episodic retail purchasing among urban companion animal owners. Direct-to-consumer channels capture recurring revenue and first-party consumption data. This shift is most visible in United States coastal metropolitan markets where same-day fulfillment infrastructure penetrates densely.
Animal Feed and Pet Food Market Segmentation
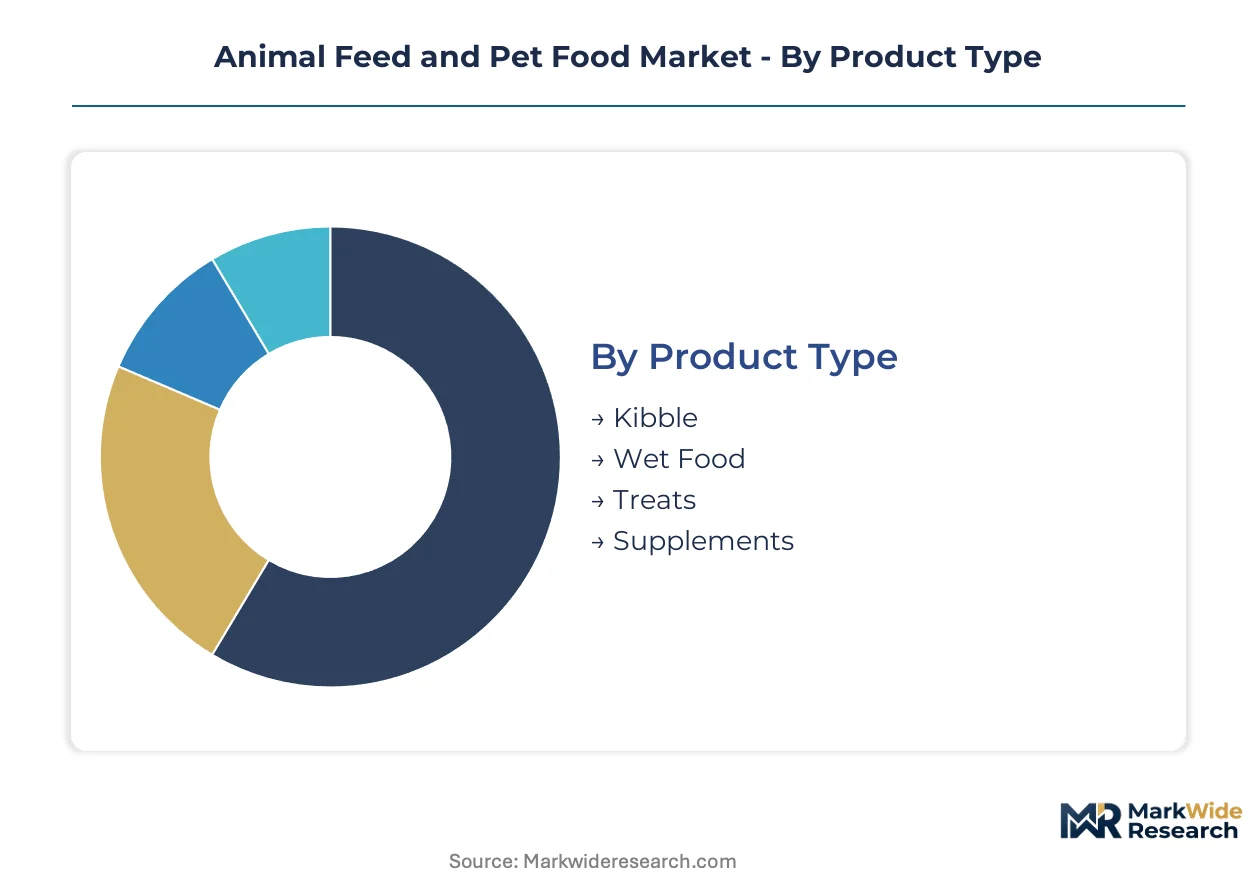
Product architecture in animal feed and pet food determines manufacturing capital allocation, shelf stability requirements, and margin capture. Specification choices cascade through ingredient procurement, processing technology selection, and distribution channel access.
Product Type:
Extrusion and retort sterilization technologies define the specification hierarchy across consumption formats.
- Kibble:Dry extruded formulations achieve 10-12% moisture content through high-pressure thermal processing, enabling 18-month shelf stability without refrigeration. Manufacturing throughput concentrates in industrial-scale facilities serving mass retail and farm supply channels, where logistics economy favors palletized bulk distribution.
- Wet Food:Retort-sterilized cans and pouches carry 75-80% moisture, requiring energy-intensive thermal processing and metal detection protocols. Demand clusters in aging pet demographics across United States coastal metropolitan markets and European urban centers, where palatability sensitivity overrides per-serving cost premiums.
- Treats:Baked, extruded, or freeze-dried formats occupy intermediate moisture bands with functional positioning around dental health, training reinforcement, and emotional bonding.
- Supplements:Powder, chewable, and liquid delivery systems target joint support, digestive modulation, and anxiety management with premix-level precision dosing.
Mature deployment sits with Kibble. Newer deployment is concentrated in Supplements.
Ingredient Type:
Raw material sourcing geography and protein conversion efficiency drive cost tier stratification.
- Meat:Rendered poultry meal, beef by-products, and fishmeal deliver amino acid completeness with digestibility coefficients above 85% in canine and feline formulations. Brazilian beef processing complexes and Thai fishmeal traders anchor supply, though black soldier fly larvae cultivation is absorbing venture allocation as a permitted novel protein class.
- Grains:Corn and wheat provide carbohydrate energy density and extrusion binding properties at the lowest cost-per-calorie tier. Procurement concentrates in United States Midwest elevator networks and Black Sea export corridors, exposing formulators to freight volatility and mycotoxin surveillance requirements.
- Vegetables:Pea protein, potato starch, and sweet potato formulations serve grain-free positioning and glycemic control claims in premium companion animal diets.
- Additives:Vitamin premixes, mineral chelates, organic acids, and colorants constitute sub-5% inclusion rates by mass but determine regulatory compliance and shelf-life extension.
Volume leadership resides with Grains. Margin expansion is climbing the fastest in Additives.
End User:
Customer type dictates pricing transparency, formulation complexity, and channel access requirements.
- Households:Direct-to-consumer subscription models and mass retail purchasing dominate companion animal nutrition, with e-commerce fulfillment penetrating United States and Chinese urban markets. Palatability trials and packaging aesthetics drive repeat purchase decisions.
- Farms:Integrated protein complexes and independent livestock operations procure compound feeds through distributor networks or direct mill relationships, with formulation precision tied to growth-stage optimization in poultry and swine operations.
- Veterinary Clinics:Prescription therapeutic nutrition bypasses price comparison through clinic dispensing models, sustaining premium positioning for renal, gastrointestinal, and weight management formulations.
- Pet Retailers:Specialty chains and independent stores curate premium and super-premium assortments with private-label development and in-store nutritional consultation services.
Transaction scale concentrates with Farms. Value-per-unit expansion is gaining share fastest in Veterinary Clinics.
Packaging Type:
Barrier properties and shelf-life extension technologies determine format selection across supply chain lengths.
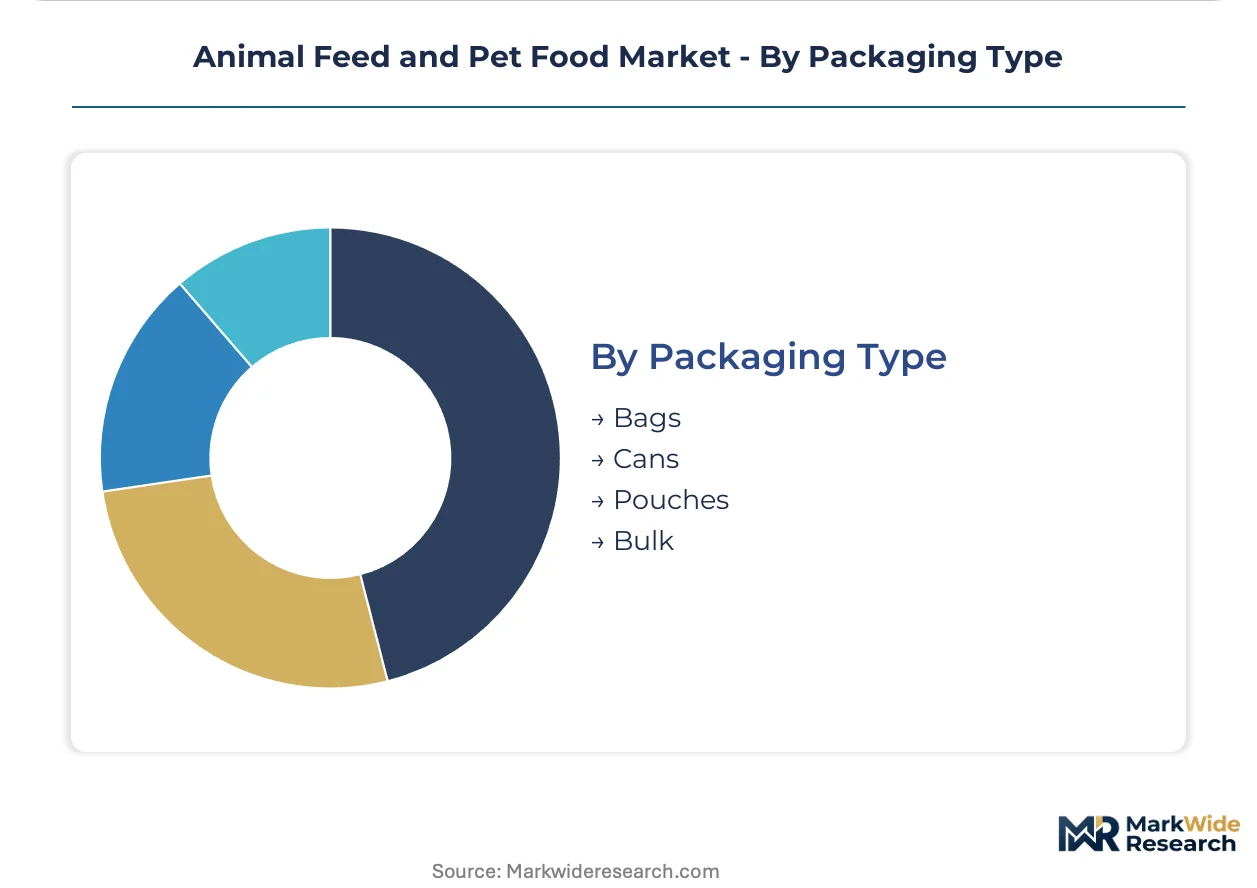
- Bags:Multi-wall paper and polyethylene laminates protect dry kibble from moisture ingress and pest contamination through distribution to farm and retail endpoints.
- Cans:Tinplate and aluminum containers provide hermetic sealing for retort-sterilized wet products, with recycling infrastructure varying by municipality.
- Pouches:Retortable flexible films reduce shipping cube and material weight versus cans, penetrating premium wet food and treat segments in European and North American markets.
- Bulk:Silo delivery and tote systems serve integrated livestock operations with formulation customization and minimal packaging overhead.
Logistics optimization favors Bulk in farm channels. Sustainability positioning is expanding most quickly in Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean meal exports anchor protein sourcing for compound feed mills worldwide. The United States, China, and Brazil concentrate livestock consolidation and pet humanization trends most intensely.
United States
Integrated poultry complexes in the Southeast and Midwest drive precision-formulated compound feed procurement at scale. FDA Food Safety Modernization Act provisions mandate traceability systems that favor capital-intensive producers with dedicated quality infrastructure. Omaha and Kansas City anchor distribution networks where extrusion engineering talent scarcity constrains capacity expansion.
China
Livestock consolidation into integrated protein complexes concentrates demand for compound feeds with premix inclusion rates above 5%. GB standards for feed labeling elevate barrier costs for new entrants while forcing incumbent reformulation cycles. Yangtze River Delta feed mills absorb freight cost volatility from Brazilian soybean meal realignment into margin structures.
Brazil
Beef processing complexes in Mato Grosso and São Paulo states supply rendered poultry meal and soybean derivatives to global formulators. Port congestion risk at Santos and Paranaguá exposes mills to currency fluctuation and compresses formulation flexibility. Black soldier fly larvae farming scales as a permitted novel protein class, reducing dependency on conventional fishmeal.
Germany
Aquaculture premix manufacturers in Northern Europe consolidate formulation partnerships to share REACH registration costs for novel feed additives. EU Feed Hygiene Regulation 183/2005 alignment stretches quality assurance teams at mid-scale producers. Hamburg anchors distribution for retort-sterilized wet products penetrating premium companion animal segments.
India
Tier-1 cities including Mumbai and Delhi exhibit accelerating pet humanization with disposable income growth driving underpenetrated companion animal nutrition demand. FSSAI feed safety standards remain less stringent than FDA or EU frameworks, creating white space for premium positioning. Maharashtra and Karnataka concentrate veterinary dispensing channel development for prescription therapeutic nutrition.
Animal Feed and Pet Food Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue microbiome modulation and alternative protein cultivation. The market structure consolidates around multinationals with dedicated quality assurance infrastructure and mass retail partnerships. Three archetypes dominate: vertically integrated agribusiness conglomerates, specialist therapeutic nutrition formulators, and direct-to-consumer subscription operators. Competitive moves concentrate on M&A for geographic expansion and strategic partnerships for registration cost sharing.
Within the therapeutic nutrition tier, Hill's Pet Nutrition and Mars Petcare Inc. exemplify clinic-dispensing models that bypass price transparency. Nestlé Purina PetCare anchors North American distribution through mass retail partnerships. These three occupy positions where clinical validation and e-commerce fulfillment networks sustain premium pricing power across prescription lines.
| Leading Market Players |
|---|
| J.M. Smucker |
| Blue Buffalo |
| Mars Petcare Inc. |
| WellPet |
| Diamond Pet Foods |
| Nestlé Purina PetCare |
| General Mills |
| Spectrum Brands/United Pet Group |
| Hill's Pet Nutrition |
| Others |
Supply Flow & Price Mechanics
Extrusion engineering talent scarcity in the United States Midwest and Northern Europe widens pricing-tier spreads between mass-market kibble and precision-formulated therapeutic nutrition. Labor-cost differentials between regions with qualified process engineers and those without compress margins for mid-scale compound feed mills attempting premium positioning.
Pricing Analysis
Warranty and service bundling separates clinic-dispensed prescription diets from unbundled mass retail kibble, with veterinary channel products carrying embedded nutritional counseling and guaranteed digestibility coefficients. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and clinical validation depth, with FDA FSMA-compliant producers commanding spreads above non-certified competitors. Cost compression in economy-tier grain-based formulations is intensifying because Brazilian soybean meal export realignment exposes mills to currency fluctuation. Households purchasing through direct-to-consumer subscription models exhibit lowest price sensitivity, while independent livestock operations procuring through distributor networks show highest sensitivity to per-ton compound feed quotes.
Supply Chain Analysis
Domestic-content mandates in China's GB standards for feed labeling and India's FSSAI frameworks are reshaping sourcing toward local premix manufacturers and away from imported mineral chelates. Geographic supply concentration centers on Brazil for soybean derivatives and rendered poultry meal, Morocco and China for phosphate rock, and Thailand for fishmeal. Raw material dependencies rest on Brazilian soybean meal, Peruvian anchovy fishmeal, and synthetic vitamin premixes from Chinese chemical complexes. Single-source vulnerability in Moroccan phosphate rock dominance creates input cost instability for mineral premix manufacturers. Distribution runs through farm supply cooperatives and veterinary clinic networks for companion animal nutrition, with bulk silo delivery serving integrated livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained due to extrusion engineering talent scarcity propping pricing power for producers with captive technical capabilities.
For Market Incumbents: Anchor quality assurance infrastructure investments to defend against microbiome-modulation entrants threatening premium positioning. Deepen backward integration into black soldier fly larvae cultivation to secure novel protein supply and reduce exposure to Brazilian soybean meal volatility. Prioritize certification investment for dual FDA FSMA and EU 183/2005 alignment to consolidate share among compliant operators.
For New Entrants and Emerging Players: Precision fermentation-derived single-cell protein offers a technology-first wedge against incumbent fishmeal dependency in aquaculture premix segments. Target India's tier-1 cities for companion animal nutrition white space, where pet humanization accelerates with disposable income growth. Pursue direct-to-consumer subscription models with same-day fulfillment infrastructure to capture recurring revenue and first-party consumption data.
For Investors and Strategic Acquirers: Re-rating potential sits with clinically validated therapeutic nutrition formulators given veterinary dispensing channel expansion sustaining margin pools. Long-term viability favors producers with dedicated quality assurance infrastructure and mass retail partnerships over commodity compound feed operators. Monitor REACH registration cost-sharing partnerships among Northern European aquaculture premix manufacturers as inflection signal for regulatory barrier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | FDA-compliant substantiation of gut health claims commands premium positioning in veterinary channels. |
| Alternative Protein Cultivation | Black soldier fly larvae farming reduces dependency on Peruvian anchovy meal and Brazilian soybean derivatives. |
| Direct-to-Consumer Launch | Subscription replenishment models capture recurring revenue in United States coastal metropolitan markets. |
| Regulatory Certification Alignment | Dual FDA FSMA and EU 183/2005 compliance consolidates market share among capital-intensive producers. |
| Microbiome Additive Development | Postbiotic and synbiotic formulations command premium positioning as clinical validation substantiates gut health claims. |
Methodological Framework
Document review covered FDA Food Safety Modernization Act guidance documents, EU Feed Hygiene Regulation 183/2005 implementation reports, and Chinese GB standards for feed labeling, complemented by interviews with extrusion engineering directors at compound feed mills, procurement leads at integrated poultry complexes, regulatory affairs managers at premix manufacturers, and category buyers at mass retail chains. Secondary validation drew from customs trade data on Brazilian soybean meal exports, SEC 10-K filings of publicly traded pet food producers, and aquaculture feed production databases. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with macroeconomic demand projections.
Segmentation outputs across product type, ingredient class, end-user archetype, and packaging format were modeled over the projection horizon, with CAGRs derived from historical volume trajectories and elasticity-adjusted demand curves. The analytical framework incorporated premix inclusion rate trends, livestock consolidation patterns into integrated protein complexes, and pet humanization indices for companion animal nutrition. Alternative protein regulatory approval timelines and REACH registration cost burdens for novel feed additives informed scenario-weighted projections.
Several conditions sit outside the modeled scope, including abrupt shifts in Brazilian export policy, novel food approval acceleration by FDA or EFSA, and phosphorus supply disruption from Moroccan or Chinese production constraints. Forecasts reflect assumptions around traceability system adoption rates and clinical validation substantiation timelines for microbiome claims. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Netherlands Cashew Market