
 Spain Alfalfa Hay Market | 2026-2036
Spain Alfalfa Hay Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Alfalfa Hay Market Analytics
The EU Green Deal is decoupling Spanish alfalfa production from conventional water-intensive practices by embedding stricter sustainability benchmarks into CAP disbursements. Nafosa leverages its integrated dehydration complexes across Aragon to sustain year-round supply continuity for Middle Eastern export contracts. Al Dahra Agricultura España anchors procurement networks through backward integration into irrigated farming cooperatives in Castile-La Mancha. Alfalfa Monegros differentiates via specialized high-protein cultivars bred specifically for dairy nutrition protocols.
Spain alfalfa hay denotes dried perennial legume forage, typically harvested at early bloom stage with crude protein content ranging from 15% to 22% on a dry matter basis, then dehydrated at 800–900°C in rotary drum dryers to preserve nutritional density for livestock feed rations. Its primary commercial purpose centers on delivering consistent metabolizable energy and fiber to high-producing dairy herds, beef finishers, and performance horses where pasture quality fluctuates seasonally. Dehydrated alfalfa commands the dominant value share due to superior protein retention and longer storage stability versus field-cured alternatives, while pelleted alfalfa is displacing loose bales in automated dairy feeding systems where labor costs pressure operational margins. Exporters represent the fastest-growing end-user channel as North African and Gulf buyers seek EU-certified forage to replace domestic supply shortfalls.
Spain's Ministry of Agriculture, Fisheries and Food enforces compliance with EU Regulation 767/2009 on feed hygiene and labeling, while BSI Group Spain audits dehydration facilities against ISO 22000 food safety management protocols. The EU F-Gas Regulation indirectly shapes processing economics by restricting refrigerant options in cold storage infrastructure that preserves finished product quality. Stakeholders must monitor CAP tranche negotiations and Ebro Basin water allocation rulings to calibrate planting commitments against shifting input cost structures.
Market Dynamics
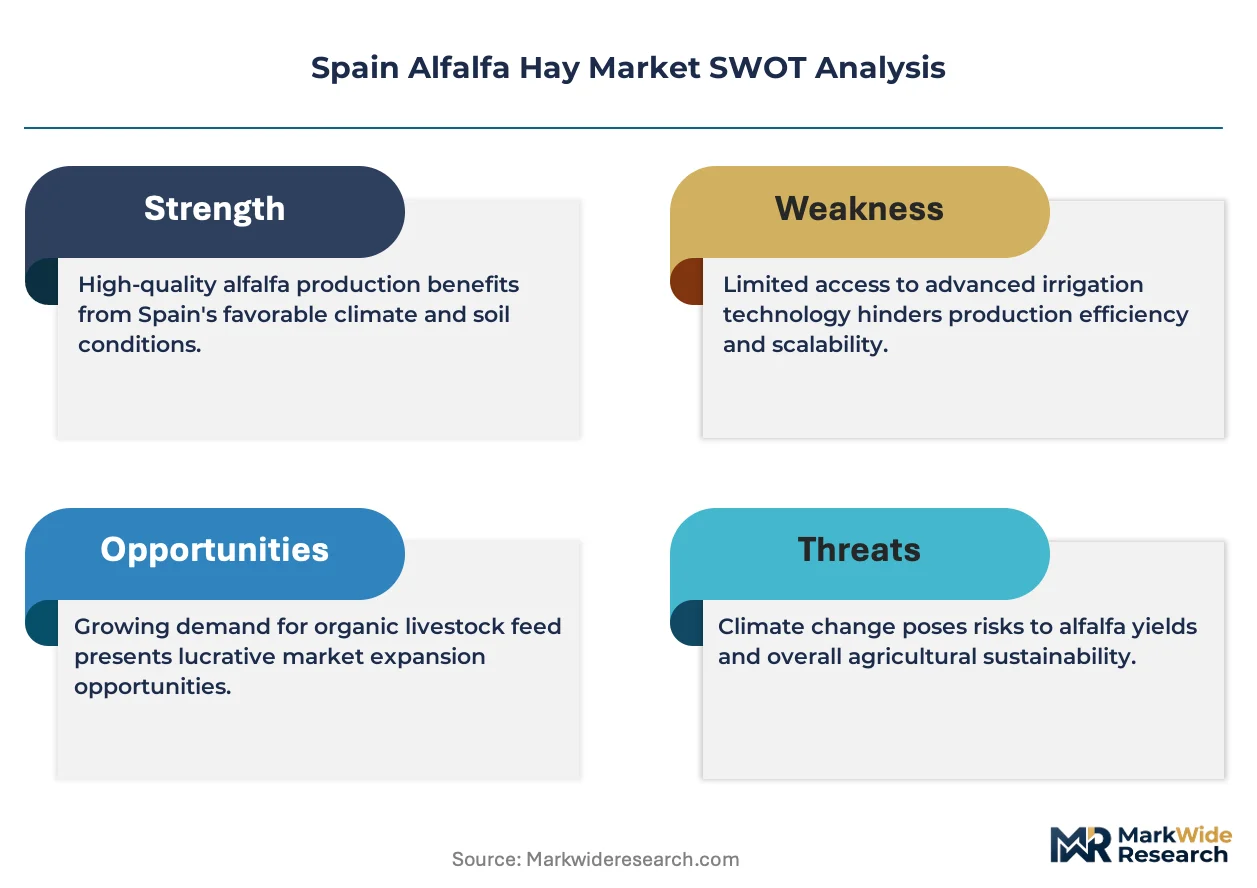
The EU Green Deal's Farm to Fork Strategy is compressing margins for conventional dehydration operators while rewarding Aragon-based facilities that have retrofitted water-recirculation systems. This regulatory wedge is splitting the competitive field between legacy field-cured producers and capital-intensive dehydration complexes.
Growth Catalysts
- Ebro Valley irrigation infrastructure:High-yield dehydration operations in this corridor supply protein-dense forage to dairy cooperatives across Castile-La Mancha, anchoring domestic feed security.
- CAP disbursement reforms:Sustainability benchmarks embedded in Common Agricultural Policy tranches incentivize contracted acreage expansion for premium cultivars meeting EU-certified export standards.
- Middle Eastern import substitution:North African and Gulf buyers facing domestic supply shortfalls are redirecting procurement toward Spanish dehydration facilities with ISO 22000 audit trails.
Market Restraints
- Ebro Basin water allocation rulings:Seasonal irrigation caps imposed by basin authorities constrain planting commitments during drought cycles, forcing yield volatility onto fixed-price contracts.
- F-Gas Regulation compliance costs:Restricted refrigerant options for cold storage infrastructure elevate preservation economics for finished product quality maintenance.
- Field-cured alfalfa substitution:Lower-cost sun-dried alternatives from non-EU origins displace volume in price-sensitive North African spot markets.
Strategic Opportunities
- Pelleted format automation:Dairy feeding systems across Catalonia are displacing loose bales with pelleted alfalfa, creating channel expansion for dehydration complexes with compression capabilities.
- Performance horse nutrition protocols:Specialized high-protein cultivars bred for equine metabolizable energy requirements command premium positioning in French and Italian import channels.
- EU F-Gas retrofit incentives:Cold storage infrastructure upgrades eligible for green transition financing enable year-round supply continuity for export contract fulfillment.
Industry Challenges
- Dehydration technician scarcity:Rotary drum dryer operation and temperature calibration expertise concentrates among aging workforce cohorts in Aragon, constraining facility expansion timelines.
- CAP tranche negotiation uncertainty:Shifting disbursement schedules complicate multi-year planting commitments for irrigated farming cooperatives in Castile-La Mancha.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Alfalfa Hay Market |
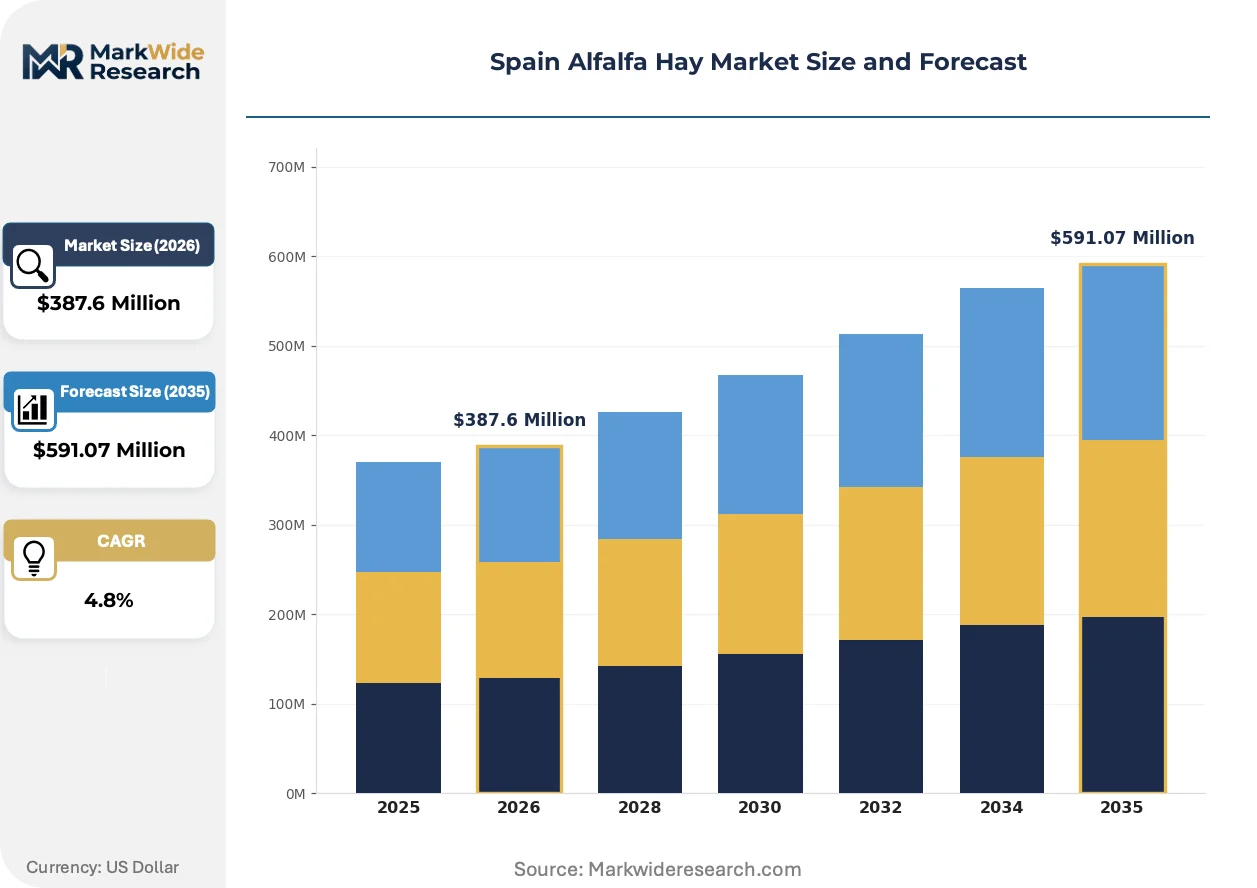
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Alfalfa, Pelleted Alfalfa, Chopped Alfalfa, Cubed Alfalfa End User: Dairy Farms, Beef Cattle Farms, Horse Owners, Exporters Packaging Type: Bales, Bags, Bulk, Containers Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Al Dahra Agricultura España, Nafosa, Alfalfa Monegros, Grupo Oses, DYCASA, Cubeit Hay Company, Coaba, Los Venteros, Tassili Agricultural Development Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Alfalfa Hay Market Evolving Landscape
Automation and regulatory compliance technology are compressing operational timelines across Spanish dehydration facilities. These shifts are reconfiguring capital deployment patterns and procurement relationships.
Near-infrared spectroscopy is integrating into rotary drum dryer control systems to monitor crude protein retention in real-time. Dairy cooperatives in Castile-La Mancha are adopting these sensor arrays at mid-scale dehydration facilities. The technology is integrating quality assurance directly into production workflow, reducing post-process laboratory testing delays.
EU Regulation 767/2009 feed hygiene enforcement is intensifying documentation requirements for cross-border shipments. Dehydration facilities must now maintain batch-level traceability from field to container. Exporters targeting Gulf markets are responding by consolidating supply relationships with audited cooperatives holding BSI Group Spain ISO 22000 certifications.
Long-term offtake agreements are displacing spot market purchases among Middle Eastern importers. These contracts specify protein content thresholds and delivery windows that favor dehydration complexes with captive farming operations. The shift is most visible in procurement patterns from Saudi and UAE buyers sourcing through Almería port logistics clusters.
Spain Alfalfa Hay Market Segmentation
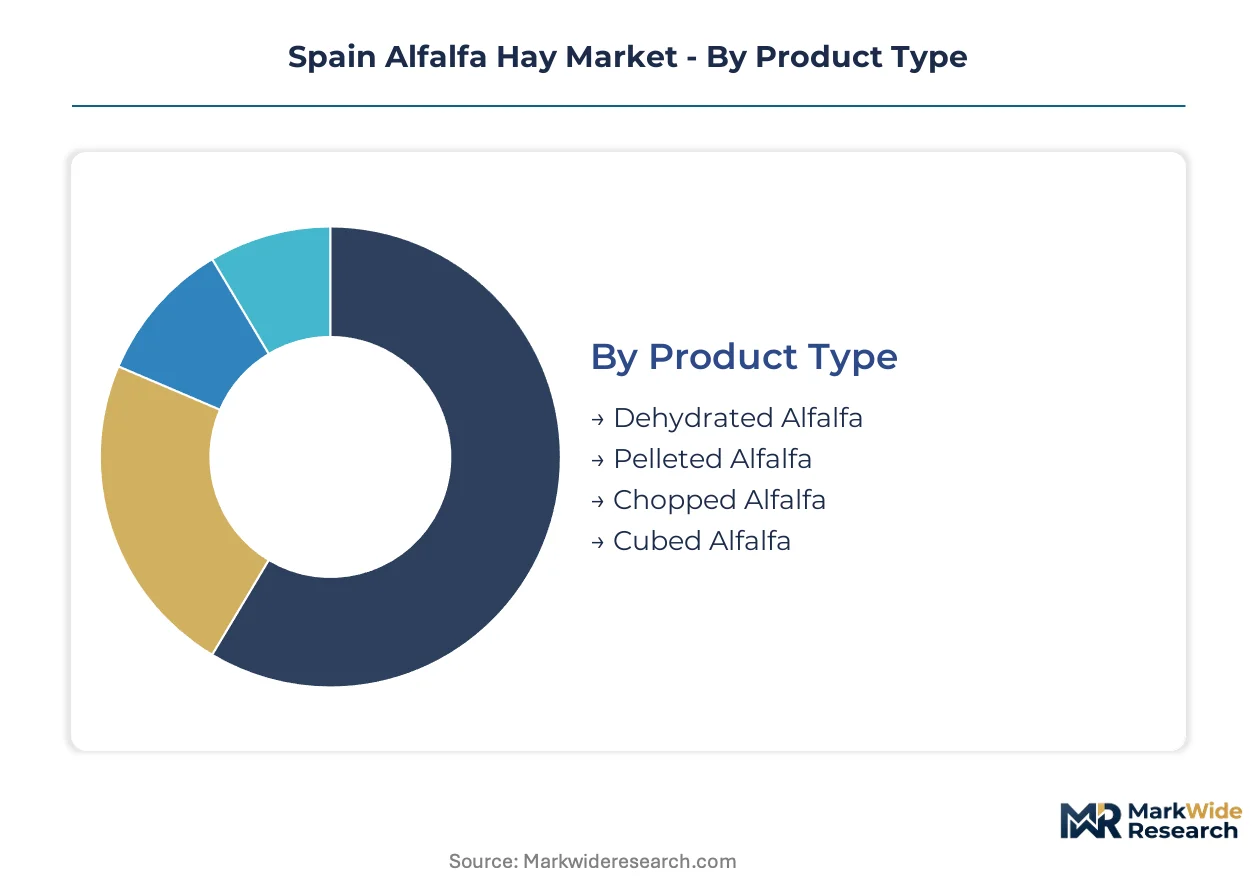
Segmentation in the Spain alfalfa hay market reflects divergent buyer priorities across dehydration technology, livestock nutrition protocols, and export logistics. Each dimension captures distinct margin structures and capital intensity requirements that shape supplier positioning.
Product Type:
Buyers select product formats based on protein retention requirements, storage constraints, and feeding system compatibility.
- Dehydrated Alfalfa:Rotary drum drying at 800–900°C preserves 15–22% crude protein content and extends shelf stability beyond field-cured alternatives. Dairy cooperatives across Castile-La Mancha specify this grade for metabolizable energy consistency in high-producing herds.
- Pelleted Alfalfa:Compression into standardized pellets enables automated dispensing in Catalonia dairy operations where labor costs pressure margins. The format reduces storage footprint and minimizes nutrient degradation during transport.
- Chopped Alfalfa:Coarse particle sizing suits beef finishing rations requiring fiber length for rumen health. Castile-La Mancha feedlots favor this format for blending flexibility.
- Cubed Alfalfa:Dense compression blocks target performance horse stables in Madrid and Barcelona where portion control and reduced dust exposure matter. Equine nutritionists specify cubes for metabolizable energy density.
Volume sits with dehydrated alfalfa; growth tilts toward pelleted formats.
End User:
End-user segmentation tracks protein specification intensity, contract duration preferences, and geographic concentration of demand.
- Dairy Farms:Herds across the Ebro Valley corridor require consistent crude protein delivery to sustain milk yield through seasonal pasture fluctuations. These buyers negotiate multi-year supply contracts with dehydration complexes.
- Beef Cattle Farms:Finishers in Extremadura prioritize fiber content and cost efficiency over protein density, creating price-sensitive spot market demand.
- Horse Owners:Performance stables in Catalonia and Madrid command premium positioning for low-dust, high-protein cultivars meeting equine metabolic requirements.
- Exporters:Gulf and North African buyers sourcing through Almería port clusters demand ISO 22000 audit trails and EU-certified batch documentation for import substitution.
Contract value concentrates with dairy farms; export channels are expanding most quickly.
Packaging Type:
Packaging selection balances handling efficiency, moisture protection, and containerization economics for cross-border shipments.
- Bales:Traditional rectangular or round bales dominate domestic spot markets and smallholder procurement across Andalusia. Field-cured product typically ships in this format.
- Bags:Polypropylene sacks protect dehydrated pellets and cubes from humidity during Mediterranean port storage. Exporters favor bags for container stuffing density.
- Bulk:Loose loading into specialized trailers serves large-scale dairy cooperatives with on-site silo infrastructure in Aragon.
- Containers:Twenty-foot equivalent units consolidate bagged or palletized cargo for Middle Eastern offtake agreements specifying Almería port origination.
Domestic volume flows through bales; containerized formats gain share in export fulfillment.
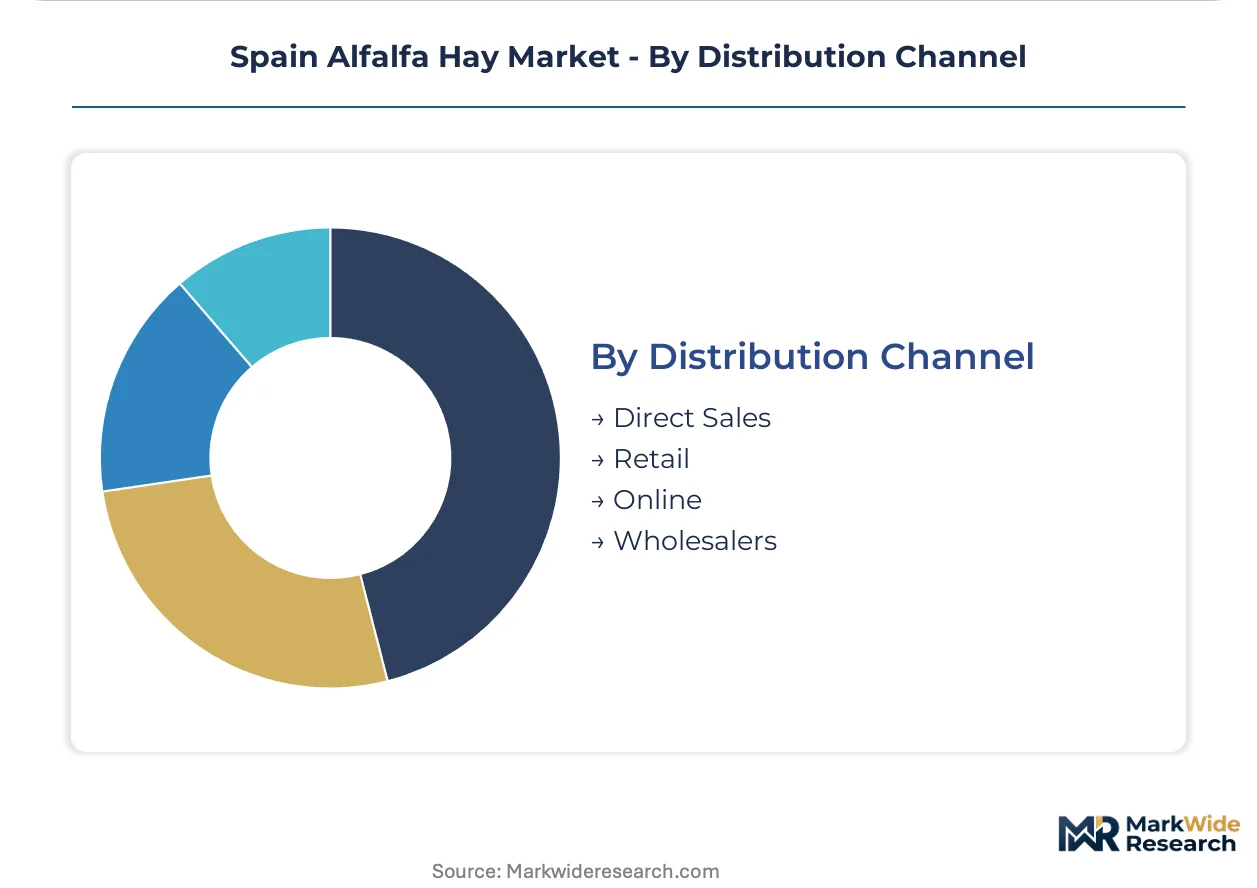
Distribution Channel:
Channel structure reflects buyer scale, technical service requirements, and documentation complexity for regulated feed shipments.
- Direct Sales:Dehydration complexes in Aragon maintain captive agronomy teams to secure multi-year planting contracts with irrigated farming cooperatives. This channel captures premium cultivar volume.
- Retail:Agricultural supply stores serve smallholder dairy and horse owners across Castile-La Mancha with bagged product and nutritional advisory.
- Online:Digital procurement platforms emerge for standardized pellet orders from performance horse stables seeking specification transparency.
- Wholesalers:Regional distributors aggregate field-cured bales from multiple origins for price-sensitive beef operations in Extremadura.
Direct sales anchor contract value; online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ebro Valley corridor anchors Spanish alfalfa production through its integrated irrigation networks and dehydration facility clusters. Aragon and Castile-La Mancha host the densest concentration of rotary drum drying operations serving both domestic dairy cooperatives and export channels through Almería port.
Aragon
Dehydration complexes across Zaragoza province leverage the Ebro River irrigation infrastructure to sustain year-round production cycles. The EU Green Deal's Farm to Fork Strategy tightens sustainability benchmarks for water recirculation systems at processing facilities. Nafosa operates integrated drying plants in this corridor to fulfill Middle Eastern export contracts with ISO 22000 audit trails.
Castile-La Mancha
Dairy farm cooperatives in Ciudad Real and Albacete provinces are expanding contracted acreage for premium cultivars meeting EU-certified standards. Spain's Ministry of Agriculture, Fisheries and Food enforces EU Regulation 767/2009 feed hygiene compliance across dehydration facilities. Al Dahra Agricultura España anchors procurement networks through backward integration into irrigated farming cooperatives in this region.
Catalonia
Performance horse stables in Barcelona province command premium positioning for high-protein, low-dust alfalfa cubes meeting equine metabolic requirements. The EU F-Gas Regulation shapes cold storage infrastructure economics for finished product quality preservation. Dairy feeding systems across Girona are displacing loose bales with pelleted formats to reduce labor cost pressure.
Andalusia
Almería port logistics clusters consolidate containerized shipments for Gulf and North African buyers seeking EU-certified forage import substitution. BSI Group Spain audits dehydration facilities against ISO 22000 food safety management protocols for cross-border documentation. Field-cured bales from smaller holdings supply domestic spot markets across Granada and Málaga provinces.
Extremadura
Beef finishing operations in Badajoz province prioritize fiber content and cost efficiency over protein density, creating price-sensitive demand for chopped alfalfa formats. Ebro Basin water allocation rulings impose seasonal irrigation caps that constrain planting commitments during drought cycles. Regional distributors aggregate field-cured product from multiple origins for feedlot procurement.
Spain Alfalfa Hay Market Competitive Landscape
Premium-margin players sit above commodity-margin players across dehydration technology and export certification tiers. The market structures around capital-intensive rotary drum drying complexes versus lower-cost field-cured producers. Three archetypes dominate: integrated dehydration operators with captive farming operations, specialized high-protein cultivar breeders, and regional distributors aggregating spot market volume. Competitive moves concentrate on backward integration into irrigated cooperatives and cold storage infrastructure upgrades for year-round export fulfillment.
Among integrated dehydration specialists, Nafosa and Al Dahra Agricultura España exemplify the capital-intensive archetype with Ebro Valley facility networks. Alfalfa Monegros occupies a position within the specialized cultivar tier, differentiating through breeding programs targeting dairy nutrition protocols. These three entities represent distinct competitive vectors: scale-driven export logistics, upstream control over irrigated acreage, and premium product differentiation through cultivar specialization.
| Leading Market Players |
|---|
| Al Dahra Agricultura España |
| Nafosa |
| Alfalfa Monegros |
| Grupo Oses |
| DYCASA |
| Cubeit Hay Company |
| Coaba |
| Los Venteros |
| Tassili Agricultural Development Company |
| Others |
Value Network & Pricing Analysis
Backward integration into irrigated farming cooperatives anchors supply position and pricing power for dehydration complexes serving EU-certified export channels. This upstream control over Castile-La Mancha acreage insulates contract holders from Ebro Basin water allocation volatility while commanding protein-content premiums.
Pricing Analysis
Yield-linked pricing anchors dehydrated alfalfa contracts, with protein retention thresholds directly indexing payment schedules for dairy cooperatives across Castile-La Mancha. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified export grades from domestic field-cured alternatives. Cost compression in sun-dried tiers is intensifying because Moroccan and Egyptian suppliers displace volume in North African spot markets. Beef finishers in Extremadura exhibit highest price sensitivity; Gulf importers sourcing through Almería port clusters show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Ebro River irrigation infrastructure, where basin authority rulings constrain planting commitments during drought cycles. Geographic supply concentration centers on Spain, with secondary sourcing from France and Italy for premium cultivar genetics. Raw material dependencies include phosphate fertilizers, diesel for rotary drum dryers, and polypropylene packaging. Tariff exposure runs through evolving EU-Mercosur trade negotiations affecting South American competitor access. Distribution runs through Almería port logistics clusters for Middle Eastern offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy integration is displacing legacy laboratory testing workflows across Spanish dehydration facilities. This sensor-based quality assurance transition compresses operational timelines and reconfigures capital deployment patterns.
For Market Incumbents: Deploy captive farming contracts as the primary defensive lever. Nafosa and Al Dahra Agricultura España should expand backward integration into Castile-La Mancha irrigated cooperatives to secure multi-year acreage commitments against CAP tranche uncertainty. ISO 22000 certification investment defends margin position against emerging field-cured substitutes from non-EU origins. For New Entrants and Emerging Players: EU Green Deal's Farm to Fork Strategy in Spain opens a window for water-recirculation technology specialists to retrofit legacy dehydration facilities. White-space targets include pelleted format automation for Catalonia dairy feeding systems and specialized equine nutrition protocols for French import channels. Go-to-market angle: partner with aging dehydration technician cohorts in Aragon to bridge operational expertise gaps. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated dehydration operators with captive farming operations and ISO 22000 audit trails. Long-term viability frames around water security and export certification moats. Acquisition target archetype: mid-scale Aragon facilities with Ebro Valley irrigation access and compression capabilities for pelleted formats. Signal to watch: CAP disbursement schedules shifting multi-year planting commitment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Irrigated Cooperatives | Captive acreage in Castile-La Mancha insures against Ebro Basin water allocation volatility. |
| Near-Infrared Spectroscopy Deployment | Real-time protein monitoring at Nafosa facilities reduces post-process laboratory testing delays. |
| ISO 22000 Certification Investment | BSI Group Spain audits enable Gulf buyer procurement substitution away from domestic shortfalls. |
| Pelleted Format Capacity Expansion | Compression capabilities capture Catalonia dairy automation trends displacing loose bales. |
| Cold Storage Infrastructure Retrofit | EU F-Gas Regulation compliance preserves finished product quality for year-round export fulfillment. |
Research Methodology
Trade databases, EU agricultural subsidy registries, and dehydration facility permitting records formed the secondary backbone for acreage and production volume estimation. Primary interviews with dehydration plant managers, dairy cooperative procurement leads, equine nutrition specialists, and BSI Group Spain certification auditors combined with secondary validation. Bottom-up and top-down triangulation cross-checked planted hectares against export shipment manifests through Almería port.
Bottom-up modeling built volume estimates from individual facility capacities across Aragon and Castile-La Mancha, while top-down analysis anchored against EU forage production aggregates. Segmentation dimensions modeled include dehydration technology tier, livestock nutrition protocol, export certification status, and regional irrigation infrastructure access. CAGRs derived from protein-content indexed contract value trajectories across the analysis window, incorporating Ebro Basin water allocation scenarios and CAP disbursement schedule assumptions.
Caveats apply where drought frequency intensification or EU-Mercosur trade agreement finalization could materially shift the outlook for Spanish export competitiveness. Forecasts reflect documented assumptions around irrigation infrastructure maintenance and Middle Eastern import substitution persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Alfalfa Protein Concentrate Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Apiculture Market