
 Bee Pollen Market | 2026-2036
Bee Pollen Market Size, Share, and Industry Trends Forecast 2026-2036
Bee Pollen Market Analysis
Buyer concentration among dietary supplement brands is realigning procurement dynamics across the bee pollen supply chain. NOW Foods leverages vertical integration into raw pollen sourcing to secure batch consistency for its supplement lines. Stakich anchors its position through geographic dominance in North American apiary partnerships. Comvita competes on brand strength in the premium functional foods segment, while Zhifengtang Bee Products controls domestic distribution depth across China's tier-one cities.
Bee pollen consists of granules collected by honeybees from flowering plants, typically containing proteins, amino acids, vitamins, minerals, and flavonoids with particle sizes ranging from 2 to 3 millimeters; its primary commercial purpose centers on nutritional fortification across supplements, functional foods, and cosmeceutical formulations. Powdered pollen leads product type revenue due to blending versatility in capsule and tablet manufacturing, while extracts command premium positioning in pharmaceutical-grade applications. Online retail channels are expanding fastest among distribution pathways, though health stores sustain margin pools through personalized consultation and practitioner endorsement.
The FDA exercises oversight through Current Good Manufacturing Practice regulations for dietary supplements, while the EU's EFSA evaluates novel food safety dossiers for bee pollen imports into member states. China's SAMR enforces GB standards for bee product labeling and adulteration testing, creating compliance thresholds that filter smaller exporters. Stakeholders must monitor evolving pesticide residue limits across these jurisdictions, as regulatory divergence between FDA and EFSA maximum levels directly shapes sourcing geography decisions and testing cost structures.
Market Dynamics
Certified organic procurement mandates from dietary supplement brands are compressing supply chains into vertically integrated apiary networks, forcing exporters to absorb batch-testing costs that previously sat with distributors.
Growth Catalysts
- SAMR GB Standards Enforcement:China's tightening adulteration testing protocols are filtering low-grade exporters and elevating pricing power for compliant domestic producers serving traditional medicine channels.
- Novel Food Dossier Streamlining:EFSA's evolving safety evaluation frameworks for bee pollen imports are reducing entry timelines for premium European functional food applications.
- Flavonoid Standardization:Advancements in chromatographic profiling are enabling pharmaceutical-grade extract specifications that command three-tier pricing differentiation across supplement tiers.
Market Restraints
- Apiary Concentration Risk:China's dominance in raw pollen output creates single-source vulnerability for importers facing climate-induced yield volatility in Henan and Shandong provinces.
- Pesticide Residue Divergence:Misaligned maximum levels between FDA and EFSA testing protocols force dual-certification investments that disproportionately burden small-scale exporters.
- Synthetic Substitute Threat:Algae-derived protein isolates and lab-cultured pollen analogs are capturing share in cost-sensitive cosmetic formulations.
Strategic Opportunities
- Practitioner Channel Expansion:Naturopathic and functional medicine clinics represent underpenetrated prescription-adjacent distribution for therapeutic-grade extracts in Australia and Canada.
- Cosmeceutical Convergence:Formulation partnerships combining pollen peptides with microbiome-targeted delivery systems are opening dermatological applications beyond traditional nutrition.
- EU Organic Certification Arbitrage:Producers achieving EU 2018/848 compliance gain preferential access to German and Dutch retail chains prioritizing regenerative sourcing credentials.
Industry Challenges
- Apiary Technician Scarcity:Skilled queen breeding and migratory pollination management expertise is contracting across traditional production regions, elevating labor costs.
- Blockchain Traceability Integration:Retrofitting legacy supply chains with immutable provenance systems requires capital deployment that mid-tier collectors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bee Pollen Market |
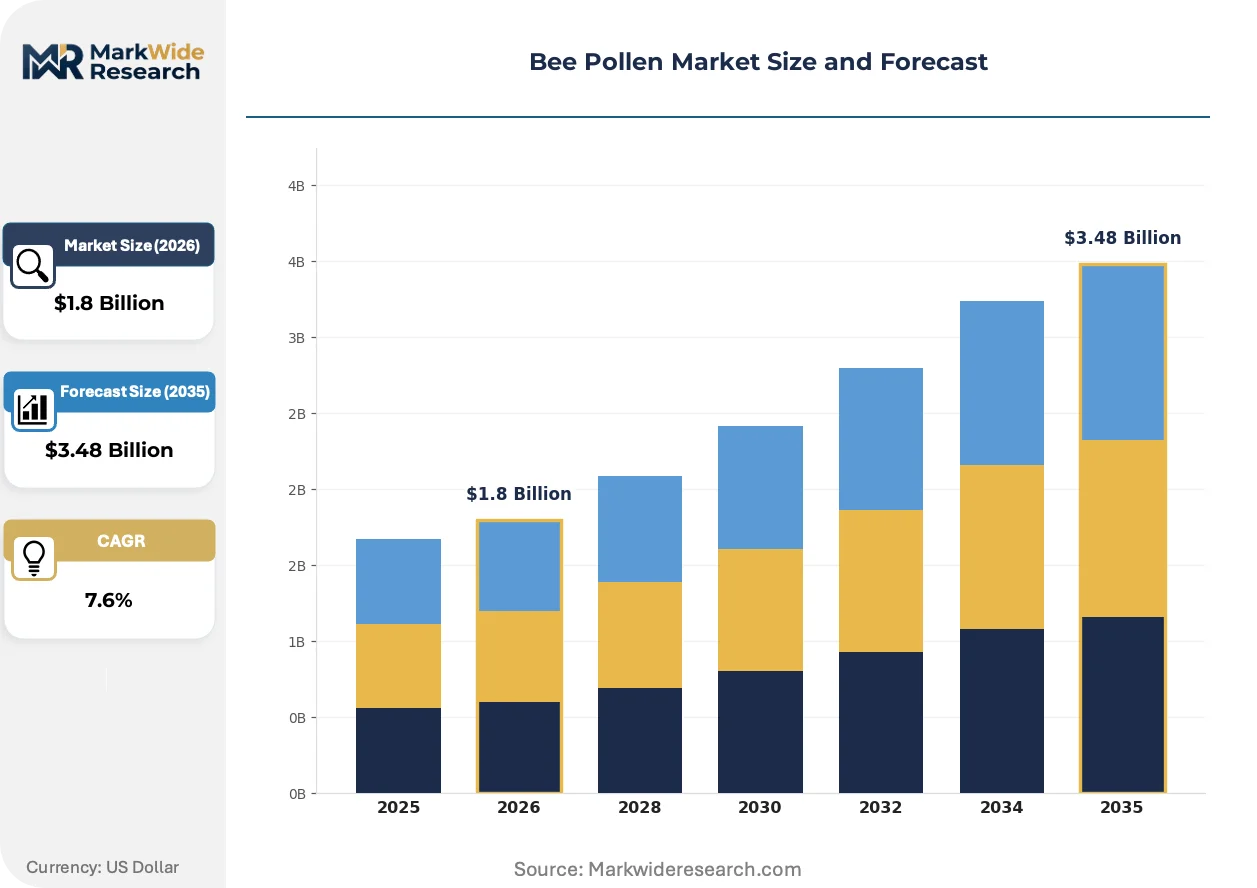
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Pollen, Fresh Pollen, Powdered Pollen, Extracts End User: Dietary Supplements, Cosmetics, Food & Beverage, Pharmaceuticals Distribution Channel: Online Retail, Health Stores, Supermarkets, Specialty Shops Application: Nutritional Products, Skin Care, Functional Foods, Energy Supplements |
| Companies Covered | NOW Foods, Stakich, Comvita, Zhifengtang Bee Products, Apis Natura, Y.S. Eco Bee Farms, Swanson Health Products, BeeVital, Beekeeper's Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bee Pollen Market Emerging Trajectories
Freeze-drying and low-temperature milling technologies are preserving bioactive compound integrity through processing stages, reshaping quality benchmarks across pharmaceutical and cosmetic grade segments.
Cryogenic grinding systems operating at minus 80 degrees Celsius are replacing conventional hammer mills for pollen cell-wall rupture. Nutraceutical contract manufacturers in Germany and Switzerland are adopting these units to meet enzyme activity retention specifications. This capital-intensive shift is absorbing smaller toll processors unable to finance nitrogen infrastructure, consolidating toll-manufacturing share among scaled operators.
EFSA's 2023 clarification on novel food status for specific pollen species is triggering reformulation cascades across EU functional food portfolios. Brands previously relying on unapproved botanical claims are retreating to established honeybee-collected variants. The regulatory tightening hits Nordic markets hardest, where clean-label positioning previously tolerated broader sourcing latitude.
Direct-to-practitioner sampling programs are displacing health-store shelf placement as the primary trial mechanism for premium extracts. Functional medicine networks in California and Texas are building recurring subscription volumes that bypass traditional retail margin stacks. This channel rotation is most pronounced where telehealth platforms integrate supplement protocols into remote consultation workflows.
Bee Pollen Market Segmentation
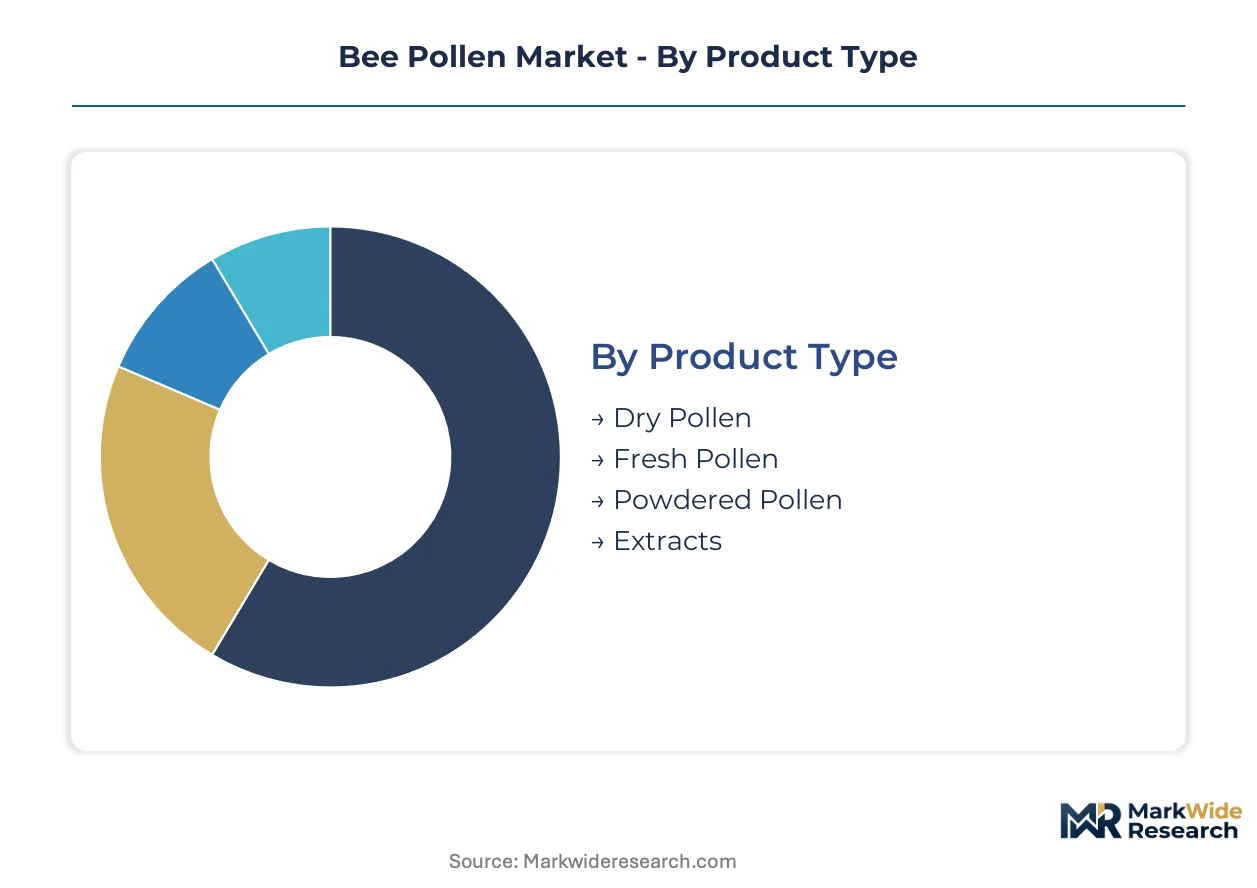
Bee pollen's commercial value hinges on processing intensity and bioactive preservation. Segment boundaries reflect divergent capital requirements, regulatory pathways, and end-user price sensitivity across the value chain.
Product Type:
Customization intensity spans from minimally handled raw granules to highly processed isolates, with capital deployment and certification burden escalating across this spectrum.
- Dry Pollen:Dehydrated granules retain enzymatic activity through controlled thermal processing below 40 degrees Celsius. Demand clusters in China's traditional medicine compounding pharmacies where practitioners specify geographic origin for therapeutic protocols. Shelf stability without refrigeration enables rural distribution depth.
- Powdered Pollen:Milled particles below 100 microns achieve homogeneous dispersion in capsule and tablet matrices. German and Swiss contract manufacturers drive specifications for enzyme activity retention, compressing toll-processing margins for facilities lacking cryogenic grinding infrastructure.
- Fresh Pollen:Refrigerated granules within 48 hours of collection preserve maximum flavonoid and amino acid profiles. Direct-to-consumer subscription models in California and Texas bypass retail margin stacks through cold-chain logistics partnerships.
- Extracts:Solvent or supercritical CO2 isolation yields standardized flavonoid concentrations for pharmaceutical dossiers. EFSA novel food compliance requirements filter supplier pools to vertically integrated apiary operations with in-house chromatographic testing.
Leading the category by volume: Powdered Pollen. Growing fastest: Extracts.
End User:
Application maturity and margin capture diverge sharply, with established nutritional channels funding R&D investment in nascent therapeutic segments.
- Dietary Supplements:Capsule, tablet, and powder formulations dominate procurement volumes from NOW Foods and Stakich. FDA Current Good Manufacturing Practice compliance creates certification moats that elevate pricing power for compliant domestic producers.
- Cosmetics:Peptide and antioxidant incorporation into microbiome-targeted delivery systems opens dermatological applications beyond traditional nutrition. Formulation partnerships with German and Swiss cosmeceutical laboratories command premium positioning.
- Food & Beverage:Functional ingredient integration into energy bars and fortified beverages requires flavor masking and heat stability. Clean-label positioning in Nordic markets faces EFSA regulatory tightening on unapproved botanical claims.
- Pharmaceuticals:Therapeutic-grade specifications for anti-inflammatory and immunomodulatory indications demand batch-level chromatographic profiling. Clinical trial enrollment in Australia and Canada advances prescription-adjacent positioning.
Category leadership sits with Dietary Supplements. Steepest expansion trajectory: Pharmaceuticals.
Distribution Channel:
Channel economics reflect customer acquisition cost structures and consultation intensity requirements across the purchase journey.
- Online Retail:Direct-to-consumer platforms capture subscription recurring revenue with telehealth integration in California and Texas. Search engine optimization for "organic bee pollen" terms concentrates marketing spend among vertically integrated brands with captive apiary content.
- Health Stores:Practitioner endorsement and personalized consultation sustain margin pools through dosage guidance and protocol customization. Shelf placement fees in North American chains favor established supplement brands with trade marketing budgets.
- Supermarkets:Mass-market penetration requires price positioning compatible with private-label competition. China's tier-one city retail chains prioritize domestic brands with SAMR GB standard compliance for consumer trust.
- Specialty Shops:Apitherapy clinics and traditional medicine dispensaries in Henan and Shandong provinces source specific floral origins for therapeutic specificity. Geographic concentration creates procurement relationships with regional collector cooperatives.
Online Retail commands volume leadership. Health Stores deliver margin concentration.
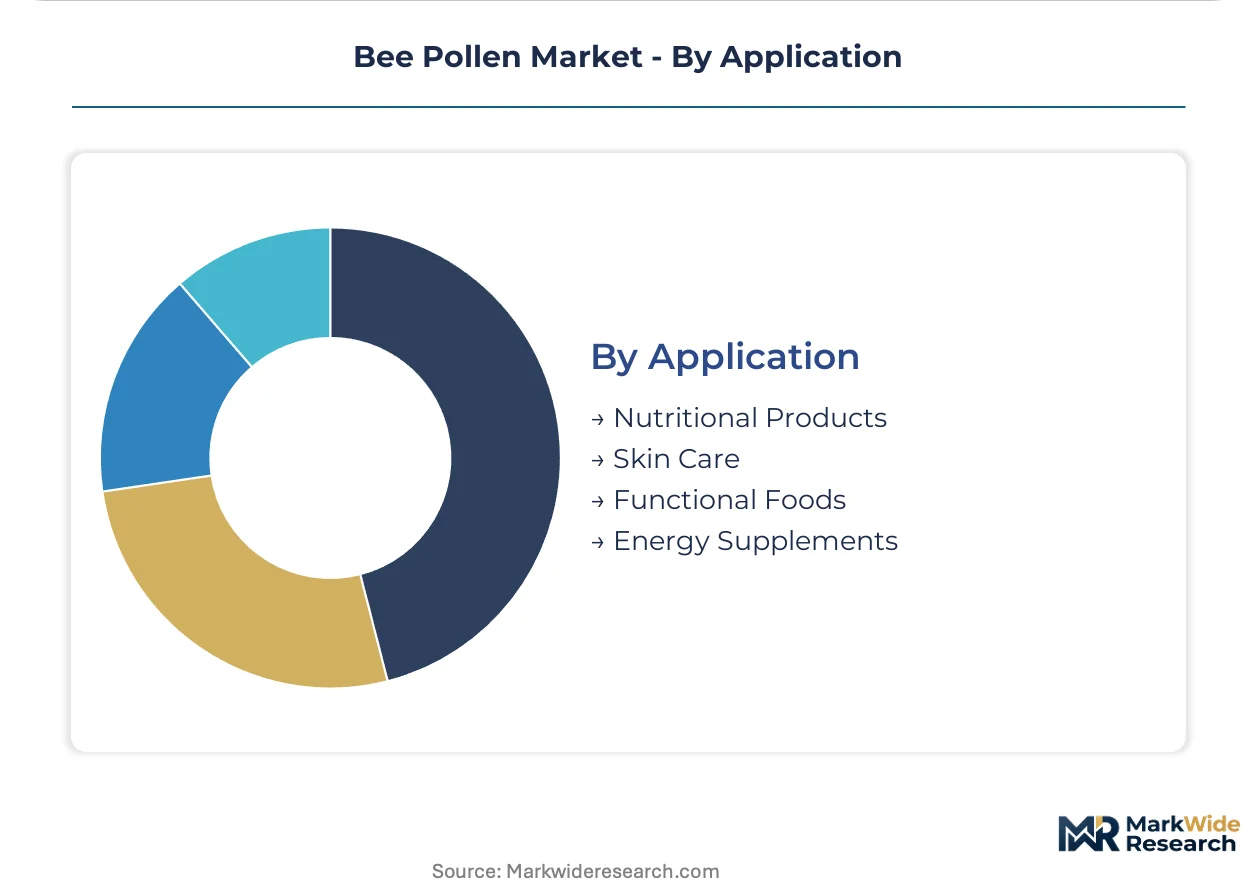
Application:
Functional positioning and clinical substantiation depth determine pricing tier and regulatory pathway across use cases.
- Nutritional Products:General wellness positioning in multivitamin complexes and protein fortification addresses broad consumer bases. China's domestic apiculture output serves traditional consumption patterns with established supply relationships.
- Skin Care:Topical peptide formulations target barrier repair and antioxidant protection in premium dermatological lines. German and Swiss cosmeceutical manufacturers specify cryogenically processed raw material for bioactive integrity.
- Functional Foods:Beverage and bar integration requires solubility and flavor compatibility at processing temperatures. EFSA novel food status clarifications trigger reformulation cascades across EU portfolios previously relying on broader sourcing latitude.
- Energy Supplements:Pre-workout and endurance positioning emphasizes rapid nutrient bioavailability through sublingual or liquid delivery. Direct-to-practitioner sampling in functional medicine networks builds recurring subscription volumes.
Nutritional Products anchor volume. Energy Supplements gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates raw pollen procurement volumes through its Henan and Shandong apiculture belts, while dietary supplement brands in Germany and the United States drive premium extract demand through stringent certification requirements.
China
Domestic consumption in tier-one cities absorbs substantial volumes for traditional medicine compounding, with SAMR GB standards enforcement filtering low-grade exporters from provincial supply chains. The agency's adulteration testing protocols elevate pricing power for compliant producers serving apitherapy clinics. Collector cooperatives in Henan province maintain direct procurement relationships with regional dispensaries specifying floral origin for therapeutic protocols.
Germany
Swiss and German contract manufacturers specify cryogenic grinding infrastructure for enzyme activity retention in pharmaceutical-grade applications, with EFSA novel food dossier requirements shaping import sourcing decisions. The country's national pharmaceutical regulator maintains strict evaluation frameworks for bee pollen derivatives entering functional food portfolios. Toll-processing facilities in Bavaria consolidate share as nitrogen infrastructure investments absorb smaller operators.
United States
Functional medicine networks in California and Texas build recurring subscription volumes through telehealth-integrated supplement protocols, bypassing traditional retail margin stacks. FDA Current Good Manufacturing Practice regulations create certification moats that elevate pricing power for compliant domestic producers. Direct-to-practitioner sampling programs displace health-store shelf placement as the primary trial mechanism for premium extracts.
Australia
Naturopathic clinics represent underpenetrated prescription-adjacent distribution for therapeutic-grade extracts, with the Therapeutic Goods Administration evaluating clinical trial enrollment for anti-inflammatory indications. The country's national pharmaceutical regulator advances immunomodulatory positioning through batch-level chromatographic profiling requirements. Practitioner channel expansion concentrates in Sydney and Melbourne functional medicine networks.
Switzerland
German and Swiss cosmeceutical manufacturers command premium positioning through formulation partnerships combining pollen peptides with microbiome-targeted delivery systems. Swissmedic maintains oversight of dermatological applications beyond traditional nutrition. Processing facilities in the Basel region adopt cryogenic grinding systems operating at minus 80 degrees Celsius to meet enzyme activity retention specifications.
Bee Pollen Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue practitioner-channel subscription models and cosmeceutical formulation partnerships. The supplier base stratifies across vertically integrated apiary operations, contract manufacturing specialists, and direct-to-consumer brands with captive content marketing. Three archetypes dominate: geographic aggregators controlling North American apiary partnerships, premium functional food specialists competing on brand strength, and domestic Chinese distributors with tier-one city penetration. Consolidation pressures concentrate among toll processors lacking cryogenic infrastructure, while backward integration into raw pollen sourcing secures batch consistency for supplement lines.
Among North American-based operators, NOW Foods and Stakich occupy positions within the geographic aggregator archetype, with the former exemplifying backward integration into captive apiary supply and the latter representing regional partnership network dominance. Comvita anchors the premium-tier vector for functional food positioning. Zhifengtang Bee Products exemplifies domestic Chinese distribution depth, reflecting the market's demand-side concentration in traditional medicine channels. These three named entities represent distinct strategic postures without implying specific market share figures or financial performance.
| Leading Market Players |
|---|
| NOW Foods |
| Stakich |
| Comvita |
| Zhifengtang Bee Products |
| Apis Natura |
| Y.S. Eco Bee Farms |
| Swanson Health Products |
| BeeVital |
| Beekeeper's Naturals |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade extract premiums against commodity dry pollen create a bifurcation that manifests in both contract structures and sourcing geography. EFSA novel food dossier requirements and FDA Current Good Manufacturing Practice tiers enforce certification ladders that compress margins at the standard tier while concentrating pricing power among vertically integrated apiary operations with in-house chromatographic testing.
Pricing Analysis
Volume leadership in dry pollen granules runs through thin margins dictated by China's SAMR GB standard compliance costs, while extract segments capture three-tier pricing differentiation through flavonoid standardization. Certification grade and cryogenic processing infrastructure serve as the primary price differentiation drivers. Pricing pressure stems from synthetic substitute encroachment in cosmetic applications. Dietary supplement brands exhibit lowest price sensitivity due to procurement mandates for certified organic pollen, whereas mass-market food and beverage integrators face acute cost compression.
Supply Chain Analysis
EU organic certification and EFSA novel food dossier requirements gate supplier participation, filtering export capacity toward vertically integrated apiary networks. Raw pollen supply concentrates in China, with secondary contributions from Romania and Spain. Bee colony health, seasonal floral availability, and migratory pollination management constitute critical input dependencies. Single-source vulnerability in Henan and Shandong provinces creates structural exposure to climate-induced yield volatility. Distribution runs through health stores and direct-to-practitioner channels for premium extracts, while online retail captures volume in standard-tier powdered pollen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic procurement mandates and cryogenic infrastructure requirements are forcing consolidation among toll processors, eliminating smaller collectors unable to finance nitrogen systems or absorb batch-testing costs.
For Market Incumbents: Anchor defensive positioning through captive apiary supply in North American partnership networks and backward integration into queen breeding operations. Synthetic protein substitutes and algae-derived isolates threaten cosmetic formulation share; counter through R&D investment in peptide-microbiome delivery systems. Certification moats around FDA and EFSA compliance tiers protect pricing power. For New Entrants and Emerging Players: Blockchain traceability platforms offer a technology-first wedge into practitioner-channel subscription models bypassing retail margin stacks. Australia's naturopathic clinic networks and California's telehealth-integrated functional medicine platforms represent the most penetrable white-space targets. Pursue direct-to-practitioner sampling programs with chromatographic batch profiling as the go-to-market anchor. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists possessing EU 2018/848 organic certification and in-house cryogenic processing given EFSA novel food streamlining catalysts. Long-term viability hinges on climate-resilient apiary geography diversification and therapeutic-grade extract pipeline advancement. Watch EFSA maximum residue level harmonization with FDA protocols as the inflection signal for dual-certification cost structure relief.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Investment | Minus 80-degree Celsius grinding systems meet German and Swiss enzyme retention specifications. |
| EU Organic Certification Achievement | EU 2018/848 compliance unlocks preferential access to Dutch and German regenerative retail chains. |
| Practitioner Channel Expansion | Direct-to-clinic sampling in California and Texas builds recurring subscription volumes bypassing retail. |
| Blockchain Traceability Integration | Immutable provenance systems address SAMR adulteration testing and EFSA novel food dossier requirements. |
| Cosmeceutical Formulation Partnership | Pollen peptide-microbiome delivery collaborations open dermatological applications beyond nutrition. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this bee pollen market assessment. Primary interviews with apiary cooperative managers, dietary supplement procurement directors, cosmeceutical formulation scientists, and EFSA regulatory consultants combined with SAMR GB standard documentation, FDA Current Good Manufacturing Practice guidance, and EU novel food safety dossiers. Bottom-up collector volume estimates and top-down extract demand projections underwent triangulation validation.
Granularity-level modeling operated at product type, end user, and distribution channel dimensions across the projection horizon. Powdered pollen volumes, extract growth trajectories, and regional regulatory cluster variations shaped analytical framework outputs. CAGRs derived from historical apiculture output trends, traditional medicine consumption patterns, and functional food penetration curves. Forecast inputs incorporated climate yield volatility assumptions and pesticide residue limit divergence scenarios.
Several conditions sit outside the modeled scope, including abrupt colony collapse disorder outbreaks, sudden EFSA-FDA residue limit harmonization, and synthetic pollen analog technological breakthroughs. Forecasts reflect documented assumptions regarding certification timeline stability and practitioner channel adoption rates. A model refresh is warranted upon material change in EFSA novel food evaluation frameworks or SAMR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market