
 Asia Pacific Tomato Seed Oil Market | 2026-2036
Asia Pacific Tomato Seed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Tomato Seed Oil Market Outlook
China's GB standards for edible vegetable oils is recalibrating extraction and refining protocols across the value chain. Ningxia Zhengyuan Wuzhong Tomato Products Co. anchors its position through captive tomato paste-to-oil processing in Ningxia. AGS Organics leverages certified organic cultivation partnerships to access premium export channels. Kazima Perfumers differentiates through fragrance-grade distillation expertise serving cosmetic compounders.
Asia Pacific tomato seed oil is a fixed oil extracted from Solanum lycopersicum seeds, typically containing 15-25% linoleic acid and 3-7% oleic acid by weight, obtained through cold-pressing or solvent extraction for use in emollient, culinary, and active-ingredient applications. Refined oil commands the largest volume share due to extended shelf stability and neutral flavor profiles preferred by food processors. Organic oil captures accelerating premiums as Japanese and Australian health stores enforce stricter provenance documentation. Unrefined oil retains niche positioning among artisanal cosmetic formulators seeking tocopherol-rich feedstock.
India's FSSAI, China's SAMR, and Japan's Ministry of Health, Labour and Welfare collectively govern food-grade and cosmetic-grade oil safety thresholds across the region. BIS certification requirements for packaged edible oils in India are pushing smaller crushers toward centralized refining infrastructure. Stakeholders must monitor regulatory divergence between cosmetic-grade and food-grade specifications when allocating capacity across product lines.
Market Dynamics
China's SAMR purity benchmarks for edible oils are forcing extraction facilities across the Asia Pacific tomato seed oil market to consolidate refining capacity or exit food-grade production entirely.
Growth Catalysts
- Cosmetic compounder demand:Southeast Asian skincare manufacturers are expanding cold-pressed oil procurement for tocopherol-rich emollient formulations targeting premium export channels.
- India's nutraceutical corridor:The Mumbai-Hyderabad logistics axis is concentrating encapsulation and softgel manufacturing, pulling seed oil volumes from Ningxia and Xinjiang processing clusters.
- Japan's provenance documentation:METI-aligned health store chains are enforcing stricter organic certification requirements, accelerating premiums for traceable supply chains.
Market Restraints
- Input cost volatility:Tomato paste processing margins determine seed availability; Ningxia paste-to-oil facilities face tomato concentrate price swings from seasonal harvest fluctuations.
- Regulatory friction:Divergent FSSAI cosmetic-grade versus food-grade specifications in India force dual-track certification investments that smaller crushers cannot absorb.
- Substitution threat:Grape seed oil and rice bran oil offer comparable linoleic acid profiles at lower unit economics for mass-market food processors.
Strategic Opportunities
- Underpenetrated Australian retail:Health food chains in Sydney and Melbourne lack dedicated tomato seed oil SKUs, creating first-mover shelf space for certified organic entrants.
- Fragrance-grade distillation:Cosmetic compounders in South Korea seek high-purity oleic acid fractions for perfume fixative applications beyond standard emollient use.
- China's dual carbon goals:SAMR incentives for solvent recovery systems are lowering operational costs for hexane extraction facilities that retrofit closed-loop distillation.
Industry Challenges
- Certification timeline compression:BIS packaged edible oil requirements in India demand 18-month compliance windows that outpace smaller crushers' capital-raising cycles.
- Skill scarcity in cold-pressing:Artisanal cosmetic formulators require operators trained in sub-40°C extraction protocols to preserve tocopherol integrity, a capability concentrated in Ningxia and Kerala.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Tomato Seed Oil Market |
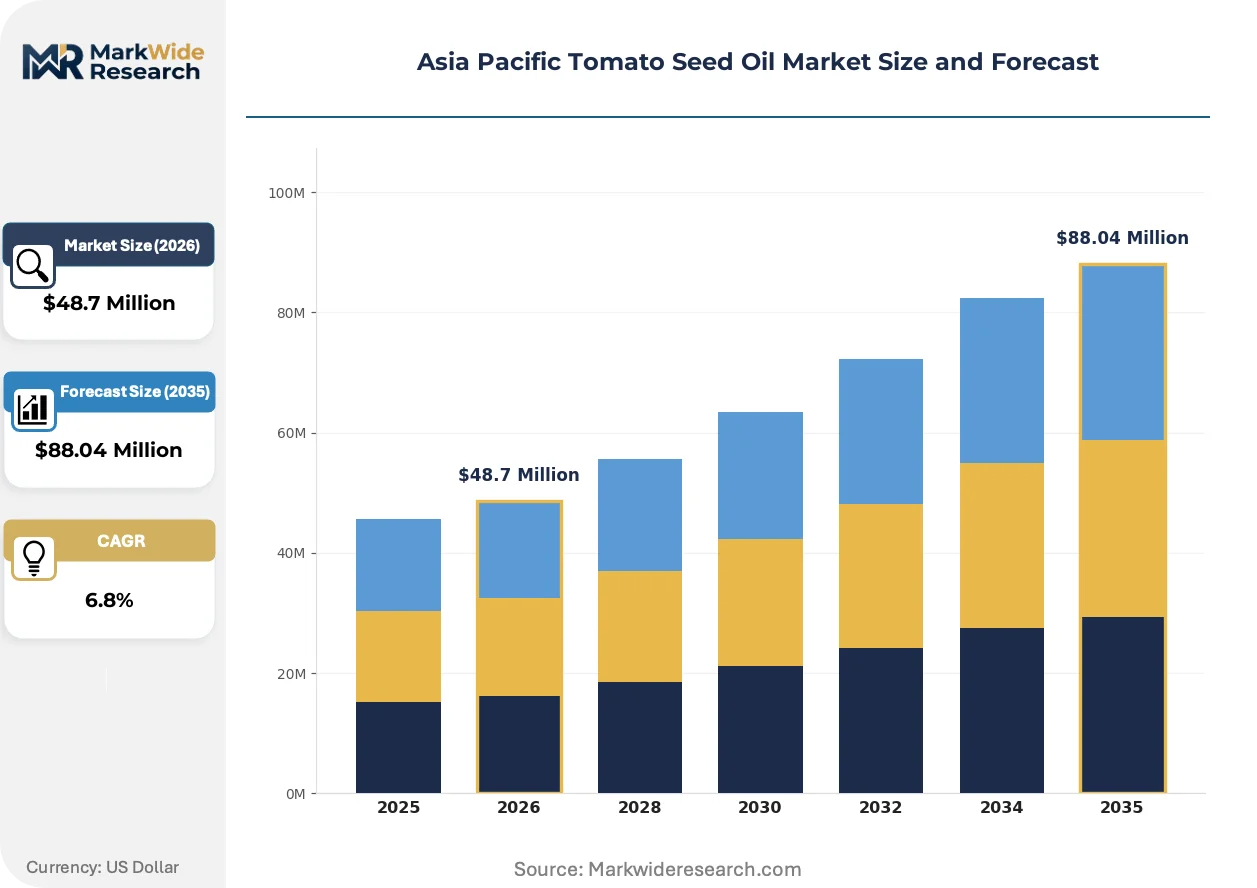
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Unrefined Oil, Organic Oil, Conventional Oil End Use Industry: Food Processing, Cosmetics, Pharmaceuticals, Nutraceuticals Packaging Type: Glass Bottles, Plastic Bottles, Bulk Containers, Tetra Paks Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | SVA Organics, Ningxia Zhengyuan Wuzhong Tomato Products Co., O&3, Kazima Perfumers, Aromex Industry, PRZ Herbals Care, Kanta Enterprises Private Limited, Greenwood Essential, AGS Organics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Tomato Seed Oil Market Strategic Shifts
Supercritical CO2 extraction is reshaping competitive positioning in the Asia Pacific tomato seed oil market by enabling solvent-free recovery of high-linoleic fractions for pharmaceutical-grade applications.
Cold-pressing technology is overtaking hexane extraction for premium cosmetic feedstock production. South Korean and Japanese skincare manufacturers are adopting sub-ambient mechanical pressing at scale to meet fragrance-grade purity specifications. This shift is compressing solvent extraction margins in the premium tier while expanding capacity constraints for certified organic lines.
China's updated GB standards for edible vegetable oils under SAMR are recalibrating refining protocols across the value chain. Facilities must now document trans-fatty acid thresholds below 2% by weight, forcing paste-to-oil processors to install molecular distillation units. The food-grade segment bears the heaviest compliance burden, with Ningxia-based integrated operators absorbing capex faster than standalone crushers.
Direct procurement contracts between cosmetic compounders and Ningxia cultivation cooperatives are displacing spot-market purchasing through Mumbai trading houses. Japanese and Australian health store buyers now require batch-level blockchain traceability from seed source to finished oil. This channel disintermediation is most visible in the organic segment, where provenance documentation commands 15-30% price premiums over conventional grades.
Asia Pacific Tomato Seed Oil Market Segmentation
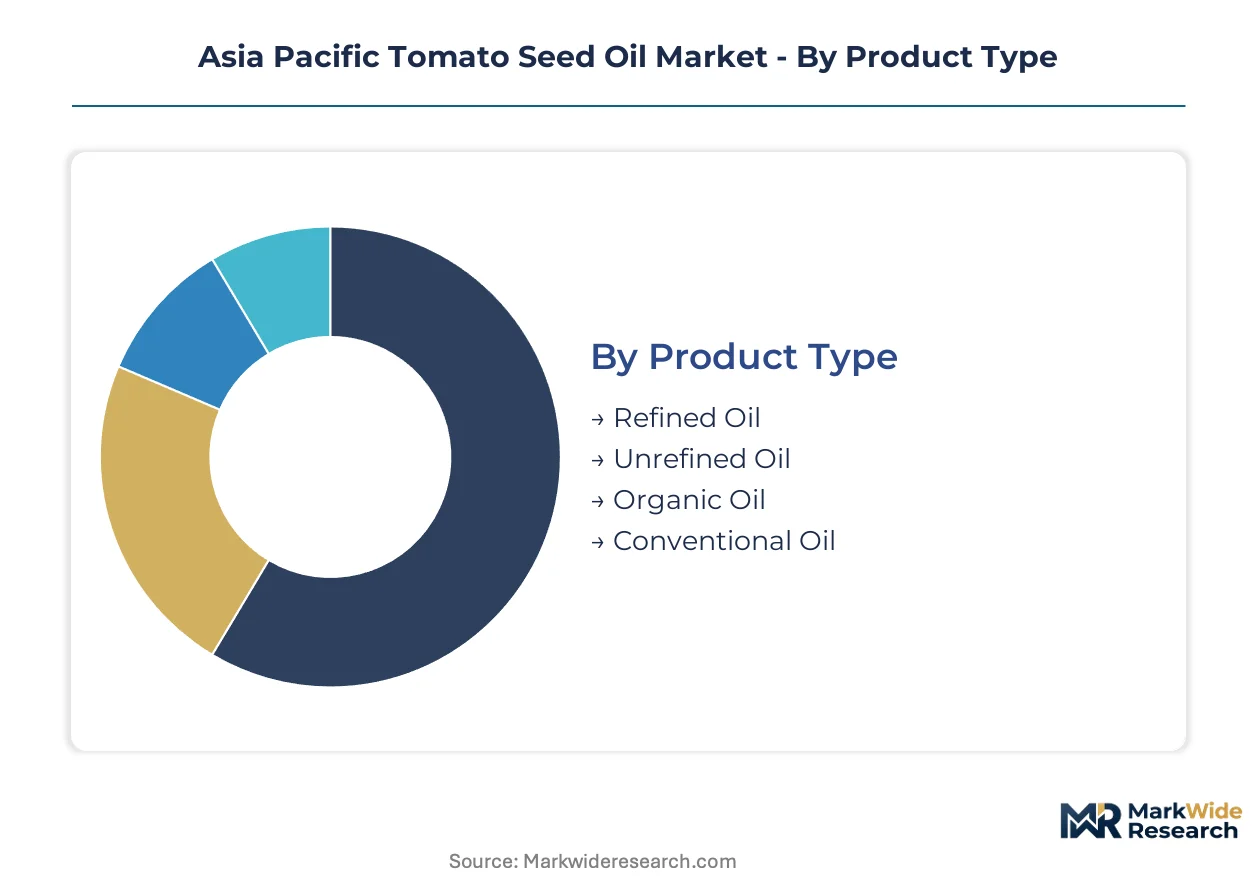
Asia Pacific tomato seed oil buyers prioritize shelf stability, certification grade, and end-use compliance when selecting product tiers. Segmentation reveals how processors allocate capacity between food-grade refining and cosmetic-grade cold-pressing to capture divergent margin pools across India, China, and Southeast Asia.
Product Type:
Purchase decisions pivot on shelf-life requirements versus tocopherol retention priorities across food and cosmetic applications.
- Refined Oil:Neutral flavor profiles and extended stability make this the default choice for food processors under China's SAMR trans-fat thresholds. Ningxia integrated facilities dominate supply to India's nutraceutical corridor due to paste-to-oil captive production economics.
- Organic Oil:Japanese METI-aligned health stores and Australian retail chains enforce batch-level traceability requirements, commanding 15-30% premiums over conventional grades. Certified organic lines face capacity constraints as cold-pressing protocols limit throughput.
- Unrefined Oil:Artisanal cosmetic formulators in Kerala and South Korea seek tocopherol-rich feedstock for emollient formulations.
- Conventional Oil:Mass-market food processors in Southeast Asia select this grade when substitution threats from grape seed oil pressure unit economics.
Refined oil leads on scale; organic oil leads on momentum.
End Use Industry:
Regulatory divergence between food-grade and cosmetic-grade specifications shapes processor investment decisions across the region.
- Cosmetics:Southeast Asian skincare manufacturers expand cold-pressed procurement for tocopherol-rich emollient formulations targeting premium export channels. South Korean fragrance compounders now specify high-purity oleic acid fractions for perfume fixative applications beyond standard cosmetic use.
- Food Processing:China's updated GB standards under SAMR mandate trans-fatty acid documentation below 2% by weight, forcing molecular distillation investments at Ningxia paste-to-oil facilities. India's FSSAI packaged edible oil rules compress compliance timelines for smaller crushers.
- Pharmaceuticals:Supercritical CO2 extraction enables solvent-free recovery of high-linoleic fractions for active-ingredient applications.
- Nutraceuticals:Mumbai-Hyderabad logistics axis concentrates encapsulation demand, pulling seed oil volumes from Xinjiang processing clusters.
Cosmetics commands margin premiums; nutraceuticals climbs fastest on softgel manufacturing expansion.
Packaging Type:
Channel requirements and shelf-preservation needs determine format selection across retail and institutional buyers.
- Bulk Containers:Food processors and cosmetic compounders in India and China procure tanker-load volumes for in-house refining and formulation, minimizing per-unit packaging costs.
- Glass Bottles:Japanese and Australian health stores specify UV-protective glass for organic SKUs to preserve tocopherol integrity during retail display.
- Plastic Bottles:Mass-market penetration in Southeast Asian supermarkets favors HDPE formats for cost-sensitive culinary oil positioning.
- Tetra Paks:Emerging format for ambient-stable culinary oil distribution in China's tier-two cities.
Bulk containers dominate volume throughput; glass bottles capture premium positioning.
Distribution Channel:
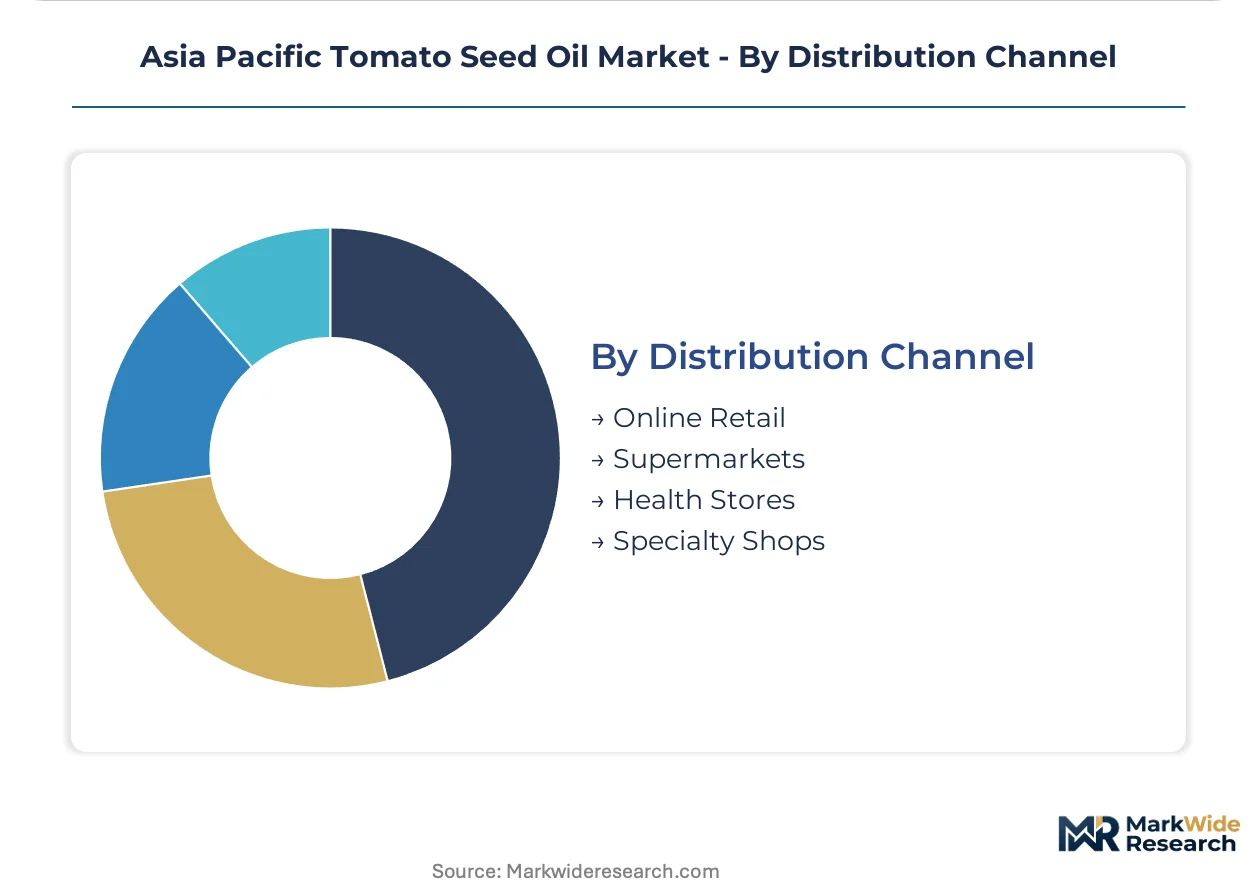
Provenance documentation requirements and buyer sophistication stratify channel economics across the region.
- Health Stores:METI-aligned chains in Japan and independent retailers in Sydney and Melbourne enforce blockchain traceability from Ningxia seed source to finished oil, displacing Mumbai trading house intermediation.
- Online Retail:Direct procurement platforms enable cosmetic compounders to contract Ningxia cultivation cooperatives, compressing spot-market margins.
- Supermarkets:Australia's underpenetrated retail landscape lacks dedicated tomato seed oil SKUs, creating first-mover shelf space opportunities for certified organic entrants.
- Specialty Shops:Artisanal cosmetic ingredient suppliers in Seoul and Mumbai serve formulators seeking sub-40°C cold-pressed grades.
Health stores lead on provenance premiums; online retail gains fastest on channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tomato seed oil extraction first scaled commercially in China's Ningxia region, where paste-to-oil integrated processing established the template now replicated across Asia Pacific. India's nutraceutical corridor and Southeast Asia's cosmetic compounder networks now drive second-wave demand growth.
China
SAMR's updated GB standards for edible vegetable oils mandate trans-fatty acid documentation below 2% by weight, forcing molecular distillation investments at paste-to-oil facilities. Ningxia Zhengyuan Wuzhong Tomato Products Co. anchors captive production from tomato paste through finished oil in Ningxia Hui Autonomous Region. Xinjiang processing clusters supply India's Mumbai-Hyderabad nutraceutical corridor via rail freight contracts.
India
FSSAI packaged edible oil rules compress 18-month compliance timelines that outpace smaller crushers' capital-raising cycles. BIS certification requirements push decentralized operators toward centralized refining infrastructure in Maharashtra and Gujarat. The Mumbai-Hyderabad logistics axis concentrates softgel encapsulation demand, pulling seed oil volumes from Chinese and domestic processing clusters.
Japan
METI-aligned health store chains enforce batch-level blockchain traceability from seed source to finished oil, accelerating premiums for certified organic supply chains. Japanese cosmetic compounders specify sub-40°C cold-pressed grades for tocopherol-rich emollient formulations. Import procurement runs through direct contracts with Ningxia cultivation cooperatives rather than Mumbai trading intermediaries.
South Korea
MFDS cosmetic-grade specifications diverge from food-grade thresholds, forcing dual-track certification investments for processors serving both segments. Seoul-based fragrance compounders now specify high-purity oleic acid fractions for perfume fixative applications beyond standard emollient use. Domestic skincare manufacturers adopt sub-ambient mechanical pressing at scale to meet fragrance-grade purity specifications.
Australia
TGA-aligned health food chains in Sydney and Melbourne lack dedicated tomato seed oil SKUs, creating first-mover shelf space opportunities for certified organic entrants. Australian retailers enforce UV-protective glass packaging for organic lines to preserve tocopherol integrity during retail display. Direct procurement platforms enable Ningxia cultivation cooperatives to bypass traditional distribution layers.
Asia Pacific Tomato Seed Oil Market Competitive Environment
The competitive structure tilts toward integrated paste-to-oil processors and certified organic specialists. Three archetypes dominate: Ningxia-based captive producers controlling upstream tomato paste supply, Indian trading houses with Mumbai-Hyderabad corridor logistics leverage, and certified organic operators accessing Japanese and Australian premium channels. Capacity consolidation and provenance documentation investments represent the dominant competitive moves as regulatory compliance costs escalate.
Among Ningxia-based integrated processors, Ningxia Zhengyuan Wuzhong Tomato Products Co. exemplifies the captive production archetype spanning tomato paste through refined oil. AGS Organics occupies a position within the certified organic tier, leveraging cultivation partnerships to access premium export channels. Kazima Perfumers represents fragrance-grade specialization, serving cosmetic compounders seeking high-purity fractions beyond standard emollient applications.
| Leading Market Players |
|---|
| SVA Organics |
| Ningxia Zhengyuan Wuzhong Tomato Products Co. |
| O&3 |
| Kazima Perfumers |
| Aromex Industry |
| PRZ Herbals Care |
| Kanta Enterprises Private Limited |
| Greenwood Essential |
| AGS Organics |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap processors in Ningxia and Xinjiang anchor supply discipline through captive tomato paste-to-oil conversion, converting seasonal harvest volatility into pricing power over Indian nutraceutical buyers and Southeast Asian cosmetic compounders. SAMR compliance costs and BIS certification timelines compress margin buffers for decentralized operators, forcing consolidation toward integrated facilities with balance-sheet capacity to absorb molecular distillation capex.
Pricing Analysis
Three-tier pricing structure across organic, refined, and conventional grades segments buyer willingness-to-pay by certification burden and tocopherol retention. Organic cold-pressed lines command 15-30% premiums over refined food-grade volumes, driven by METI-aligned Japanese health stores and Australian TGA requirements for batch-level traceability. Cost compression in conventional grades intensifies as grape seed oil and rice bran oil substitution threats pressure mass-market food processors. Mass-market Southeast Asian food manufacturers exhibit highest price sensitivity; Japanese cosmetic compounders show lowest.
Supply Chain Analysis
Tomato seed availability rests on Ningxia and Xinjiang paste processing margins, which fluctuate with seasonal concentrate pricing and harvest yields. Hexane solvent and molecular distillation equipment feed from Chinese domestic specialty chemical and engineering sectors. Single-source vulnerability concentrates in Ningxia integrated processors controlling 60-70% of food-grade refined output. Distribution runs through direct procurement contracts displacing Mumbai trading house intermediation, with blockchain-traceable lines bypassing traditional layers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific tomato seed oil market functions as a geographic-arbitrage play between China's SAMR-compliant integrated processing infrastructure and India's FSSAI-compressed compliance timelines that strand smaller crushers. Ningxia-based operators capture cost advantages from dual carbon incentives and solvent recovery retrofits unavailable to decentralized Indian competitors.
For Market Incumbents: Deepen backward integration into Ningxia cultivation cooperatives to lock seed supply ahead of seasonal paste processing margin swings. Expand molecular distillation capacity to capture food-grade volume consolidation as BIS timelines force Indian crusher exits. Defend against Korean fragrance-grade compounders seeking high-purity oleic acid fractions by certifying sub-40°C cold-pressing protocols for cosmetic channel retention. For New Entrants and Emerging Players: Health store chains in Sydney and Melbourne present first-mover shelf space opportunities with zero incumbent organic SKU presence. Australian TGA-aligned retailers lack dedicated tomato seed oil positioning, creating white-space entry for certified organic lines with UV-protective glass packaging. Bypass established distribution by contracting Ningxia cooperatives through direct procurement platforms, compressing spot-market margin capture. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian decentralized crushers facing 18-month FSSAI compliance windows that outpace capital-raising cycles. Long-term viability centers on provenance-documentation capabilities as Japanese METI and Australian TGA requirements harden. Watch blockchain traceability adoption rates among Ningxia cooperatives as inflection signal for premium channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Partnerships | Ningxia cooperatives with blockchain traceability secure 15-30% organic premiums from Japanese METI-aligned buyers. |
| Molecular Distillation Capacity Expansion | SAMR trans-fat thresholds below 2% force food-grade processors to install compliance hardware or exit entirely. |
| Fragrance-Grade Distillation Certification | Korean MFDS cosmetic specifications create high-purity oleic acid demand beyond standard emollient applications. |
| Direct Procurement Platform Launch | Channel disintermediation compresses Mumbai trading house margins while capturing provenance premiums. |
| Solvent Recovery System Retrofit | SAMR dual carbon incentives lower operational costs for hexane extraction facilities with closed-loop distillation. |
Study Parameters
Multiple input streams — primary interviews with extraction facility operators, cosmetic compounder procurement leads, and FSSAI compliance consultants; secondary validation through SAMR GB standard filings, Indian BIS certification databases, and Japanese METI organic traceability guidelines; plus customs trade data from Ningxia and Xinjiang processing clusters — were reconciled through bottom-up volume triangulation against top-down demand aggregation across the nutraceutical and cosmetic end-use segments.
Historical price realization data for organic, refined, and conventional grades was cross-referenced against panel input from Ningxia integrated processors and Mumbai-Hyderabad corridor logistics operators. Segmentation modeling spanned product type, end-use industry, packaging format, and distribution channel across the projection horizon. CAGRs were derived from installed capacity trajectories, regulatory compliance cost absorption curves, and substitution elasticity estimates for competing linoleic acid sources.
Revisions become necessary when SAMR purity benchmark enforcement intensifies, FSSAI compliance windows compress further, or blockchain traceability requirements harden across Japanese and Australian retail channels. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
United States Seed Market
Seeds
Global Grain Seed Market
Seeds
Americas Seeds Market
Seeds
Uganda Seeds Market
Seeds
South America Chia Seeds Market
Seeds
Global Forage Seeds Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
India Vegetable Seed Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Eucommia Seed Oil Market
Seeds
Avena Sativa Market
Seeds
United States Forage Seed Market
Seeds
Melon Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Sesame Seeds Market
Seeds
Hybrid Rice Seeds Market