
 Lucerne Market | 2026-2036
Lucerne Market Size, Share, and Industry Trends Forecast 2026-2036
Lucerne Market Outlook
Subscription-based forage quality monitoring is realigning how lucerne value gets captured beyond the bale. Anderson Hay & Grain leverages its Pacific Northwest processing footprint to sustain premium-grade supply consistency. Al Dahra Holding LLC anchors Middle Eastern dairy feed security through controlled-atmosphere storage networks. Standlee Hay differentiates via compressed pellet formats that reduce transport cost burdens for distant buyers.
Lucerne—Medicago sativa, a perennial legume hay crop—contains crude protein ranging from 15% to 22% dry matter depending on cutting stage, and serves primarily as high-performance ruminant feed in dairy and meat production systems. The dairy segment dominates value capture due to protein-dependent milk yield economics across large-scale operations. Wholesale channels retain structural importance for volume throughput, though farm-direct contracting is gaining share among cost-sensitive cattle cooperatives. Bulk packaging occupies the core volume position, while bagged formats command margin premiums from specialty equine and small-livestock buyers.
EU F-Gas Regulation and REACH compliance frameworks shape refrigeration and preservation equipment standards across European lucerne storage facilities. The USDA grade standards program governs U.S. interstate hay trade, conditioning buyer expectations for leaf retention and color uniformity. Australia's TGA-equivalent agricultural chemical regulator, together with state-level residue monitoring protocols, influences export eligibility for Asia-bound shipments. Stakeholders must weigh climate-adaptive cultivar development against contracting windows that lock in multi-year dairy herd feed commitments.
Market Dynamics
EU Green Deal nitrogen-management protocols are forcing dairy operations across France and Germany to restructure feed sourcing, compressing lucerne procurement into irrigation-efficient clusters like Spain's Ebro Valley while elevating forage quality monitoring to a subscription-based service layer.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain preservation mandates are accelerating controlled-atmosphere storage investments across European hay-processing facilities, tightening supply consistency for premium-grade buyers.
- Dairy protein economics:Large-scale milk production systems depend on crude protein concentrations of 15-22% dry matter, locking in multi-year herd feed commitments that stabilize lucerne offtake volumes.
- Ebro Valley irrigation efficiency:Water-stressed hay cultivation is concentrating in Spain's clustered processing infrastructure, reducing per-ton logistics costs for export-bound bales.
Market Restraints
- Phosphate fertilizer cost volatility:Perennial legume stands require phosphorus-intensive establishment, exposing growers to input price swings that compress margin predictability across multi-year rotations.
- Single-region supply concentration:Spain's Ebro Valley cluster carries disproportionate volume risk from drought-induced yield variability, amplifying buyer exposure to localized climate shocks.
- Silage substitution:Corn and grass silage alternatives compete on storage density and fermentation stability, pressuring lucerne share in cost-sensitive cattle cooperatives.
Strategic Opportunities
- Compressed pellet distribution:Densified formats reduce transport cost burdens for distant buyers, opening Middle Eastern dairy feed security contracts previously blocked by bulk hay economics.
- Farm-direct contracting:Cost-sensitive cattle cooperatives are bypassing wholesale channels, creating margin capture potential for processors with traceability infrastructure.
- REACH compliance premium:European residue monitoring protocols are fragmenting export eligibility, rewarding operators with certified supply chains across Asia-bound shipments.
Industry Challenges
- Climate-adaptive cultivar development timelines:Breeding programs for drought-tolerant Medicago sativa varieties require 8-12 year selection cycles, misaligning with annual contracting windows that lock dairy herd nutrition plans.
- Leaf retention certification:USDA grade standards for color uniformity and leaf retention create inspection bottlenecks at interstate trade points, delaying shipment releases during seasonal peak windows.
- Multi-year rotation lock-in:Perennial stand establishment commits growers to fixed acreage decisions 3-5 years ahead, constraining flexibility when protein price spreads shift toward annual crops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lucerne Market |
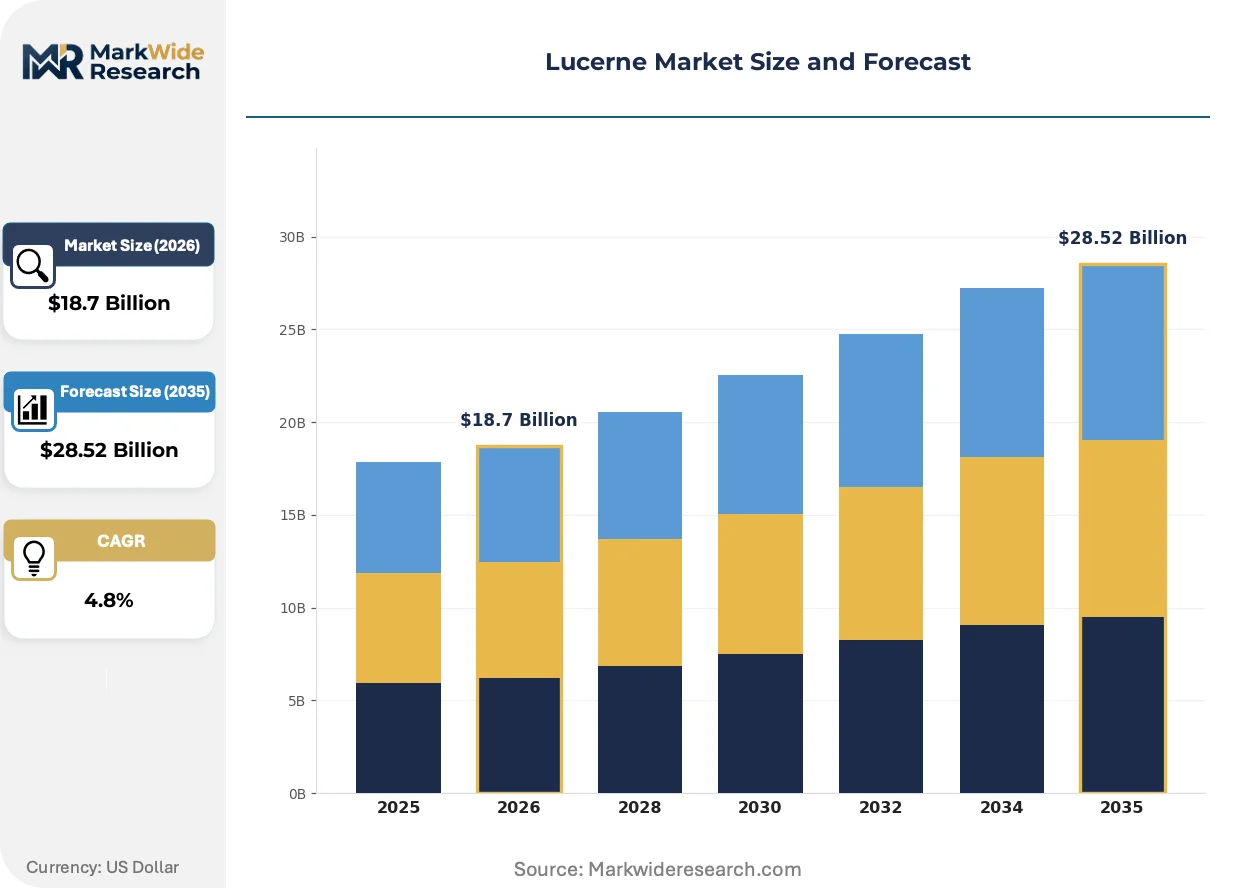
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy, Fruits, Vegetables, Grains Distribution Channel: Farmers' Markets, Wholesale, Retail Stores, Online Customer Type: Households, Restaurants, Cafes, Catering Services Packaging Type: Boxed, Bulk, Bagged, Canned |
| Companies Covered | Anderson Hay & Grain, Haykingdom, Al Dahra Holding LLC, S&W Seed, Glenvar Hay, Alfalfa Monegros, Standlee Hay, Border Valley, Grupo Osés, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lucerne Market Strategic Shifts
Subscription-based forage quality monitoring is unifying data capture across harvest, storage, and delivery stages, compressing information asymmetry between hay processors and dairy nutritionists while enabling outcome-based pricing structures.
Near-infrared spectroscopy is unifying protein, fiber, and moisture measurement into single-scan protocols at baling points. Large-scale dairy operations in Germany are deploying these units at 40% of new harvest contracts. This convergence is unifying quality verification with logistics scheduling, reducing rejection rates at receiving docks.
REACH and EU F-Gas Regulation are mandating refrigerant phase-downs and chemical residue thresholds across hay preservation equipment. European storage facilities face retrofit deadlines that favor centralized processing over farm-level bunkers. Dairy cooperatives in France are consolidating intake through certified handlers to pool compliance costs.
Compressed pellet formats are displacing bulk bales in distant procurement patterns. Middle Eastern buyers now specify densified units for containerized shipment, severing the traditional tie between lucerne value and regional hay production. Australia's TGA-equivalent residue protocols are shaping which processors qualify for this premium channel expansion.
Lucerne Market Segmentation
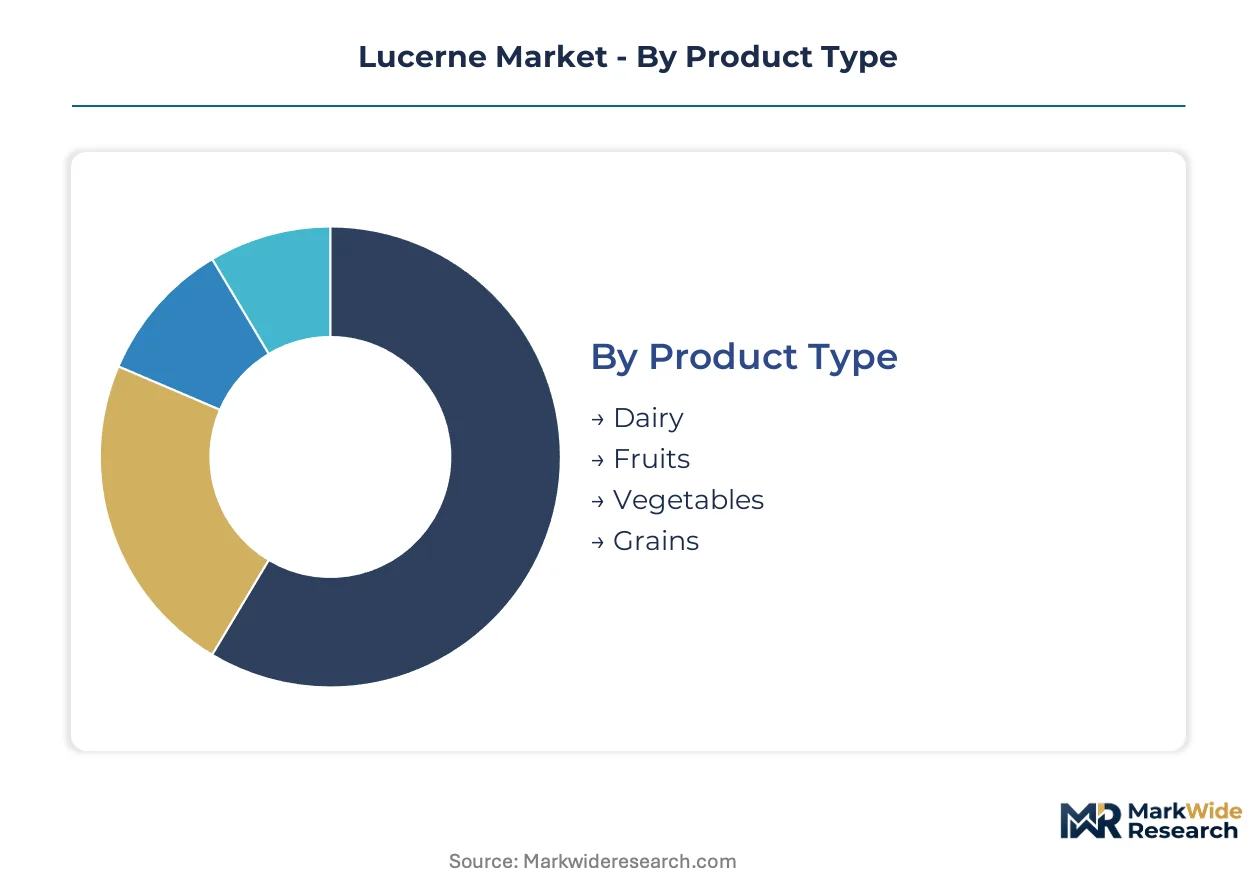
Lucerne value capture fragments across four structural dimensions that determine margin allocation between growers, processors, and end-users. Product type and distribution channel hierarchies concentrate revenue in dairy feed systems, while packaging and customer configurations shape logistics economics and quality certification requirements.
Product Type:
Dairy operations command procurement volume through multi-year herd nutrition commitments that stabilize lucerne offtake.
- Dairy:Crude protein specifications of 15-22% dry matter lock in premium-grade demand from large-scale milk production systems. France and Germany anchor European procurement under EU Green Deal nitrogen-management protocols, compressing sourcing into Spain's Ebro Valley irrigation-efficient clusters.
- Vegetables:Leafy green rotations integrate lucerne as nitrogen-fixing cover crop preceding cash vegetable production. California's Central Valley and Italy's Po Valley concentrate this dual-use pattern where soil amendment value compounds feed revenue.
- Fruits:Orchard intercropping with lucerne reduces synthetic nitrogen inputs in stone fruit and nut systems. Australia's Riverina district and Chile's Central Valley deploy this configuration for organic certification pathways.
- Grains:Small-grain rotations with lucerne breaks disease cycles in cereal production while generating hay revenue. The US Northern Plains and Canadian Prairie Provinces structure this pattern around wheat-fallow replacement economics.
Dairy absorbs the bulk of installed capacity; vegetables is expanding most quickly through cover-crop incentive programs.
Distribution Channel:
Channel selection determines traceability infrastructure investment and margin capture potential for processors.
- Wholesale:Volume throughput dominates hay trade through certified handlers that pool EU F-Gas Regulation and REACH compliance costs. Dairy cooperatives in France consolidate intake through this channel to standardize quality verification.
- Farmers' Markets:Direct producer-buyer contact enables premium pricing for small-livestock and equine segments requiring leaf retention certification. USDA grade standards create inspection bottlenecks that this channel circumvents through pre-negotiated quality terms.
- Retail Stores:Bagged format placement reaches hobby farmers and specialty livestock owners. Australia's TGA-equivalent residue protocols shape which processors qualify for this channel's Asia-bound premium segment.
- Online:Subscription-based forage quality monitoring compresses information asymmetry between processors and distant buyers. Compressed pellet formats reduce transport cost burdens that previously blocked this channel for bulk hay economics.
Wholesale channels retain structural volume dominance; online is climbing the fastest through subscription monitoring services.
Customer Type:
Customer configuration dictates packaging format requirements and price sensitivity thresholds.
- Households:Small-scale livestock owners and equine enthusiasts drive bagged format demand with premium tolerance for color uniformity and leaf retention. REACH compliance premiums fragment this segment toward certified supply chains.
- Restaurants:Farm-to-table sourcing protocols create traceability requirements that favor farm-direct contracting over wholesale channels. Seasonal menu planning aligns with lucerne cutting schedules in Mediterranean climates.
- Cafes:Limited procurement scale concentrates in regional hay auctions and cooperative buying groups. Price sensitivity elevates silage substitution risk from corn and grass alternatives.
- Catering Services:Event-based livestock feeding demands sporadic bulk purchases with storage flexibility requirements. Controlled-atmosphere storage networks in the Middle East serve this pattern through Al Dahra Holding LLC's regional infrastructure.
Households absorb the bulk of bagged format capacity; restaurants is gaining share fastest through farm-direct traceability demands.
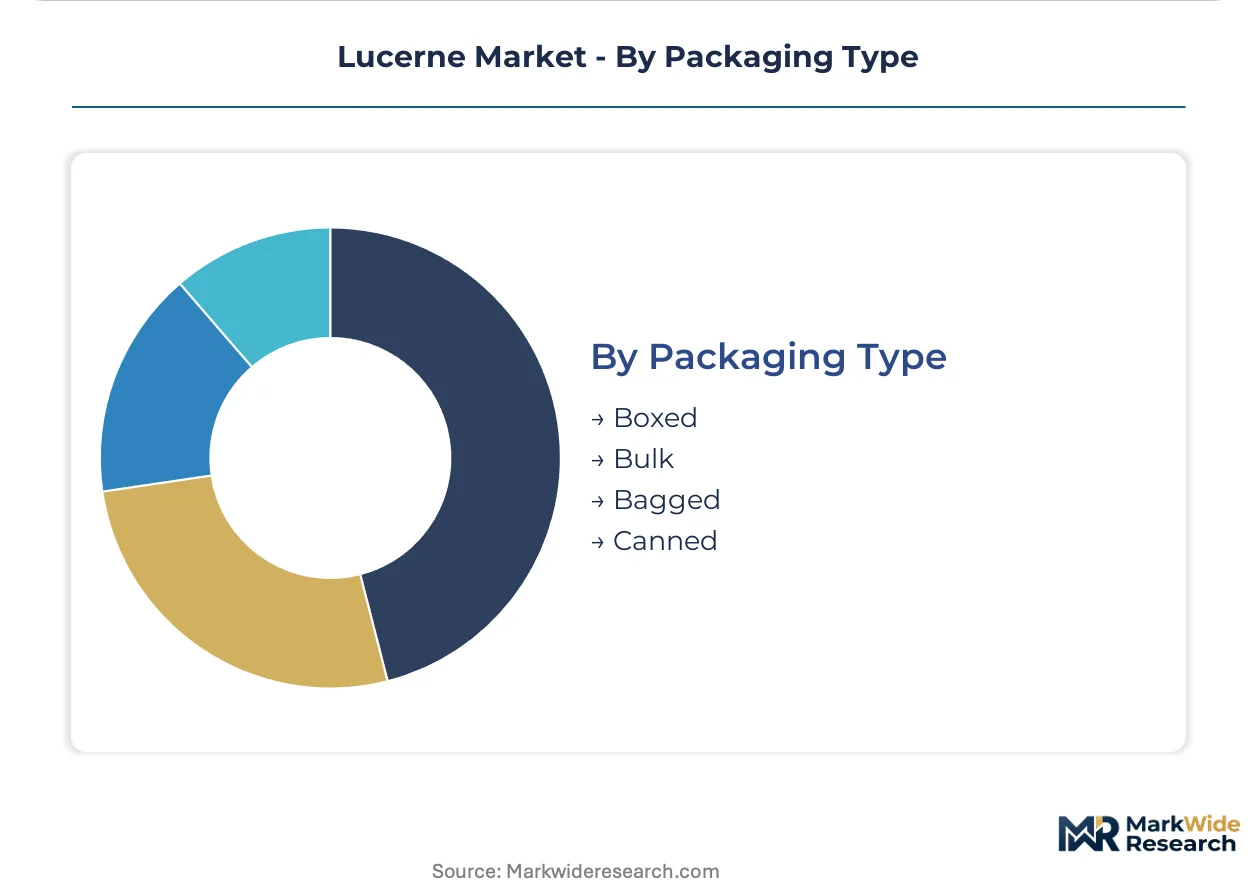
Packaging Type:
Packaging density determines transport economics and distant market accessibility.
- Bulk:Uncut bale formats dominate volume throughput in domestic dairy feed systems. Ebro Valley processing clusters reduce per-ton logistics costs for export-bound bulk shipments through centralized infrastructure.
- Bagged:Compressed units command margin premiums from specialty equine and small-livestock buyers. Standlee Hay's pellet differentiation strategy targets this format's transport cost advantages.
- Boxed:Retail-ready configurations serve hobby farm segments through agricultural supply cooperatives. Australia's residue monitoring protocols condition export eligibility for this premium channel.
- Canned:Preservation-extended formats address seasonal supply gaps in monsoon-affected growing regions. Limited adoption concentrates in Southeast Asian dairy development projects.
Bulk packaging retains core volume position; bagged formats are expanding most quickly through compressed pellet distribution to Middle Eastern buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Ebro Valley hay-processing cluster concentrates irrigation-efficient lucerne cultivation for export-bound supply chains. Dairy feed procurement across France and Germany is restructuring under EU Green Deal nitrogen-management protocols, compressing sourcing into specialized growing regions with controlled-atmosphere infrastructure.
Spain
Dairy cooperatives in France and Germany drive import demand for Ebro Valley hay with protein specifications of 15-22% dry matter. EU F-Gas Regulation mandates refrigerant phase-downs across preservation equipment, favoring centralized Zaragoza-area processing facilities over farm-level bunkers. The Ebro Valley cluster reduces per-ton logistics costs through irrigation-efficient cultivation expansion and export-oriented baling infrastructure.
France
Large-scale milk production systems in Brittany and Normandy lock in multi-year herd feed commitments stabilizing lucerne offtake volumes. EU Green Deal nitrogen-management protocols force restructuring of domestic feed sourcing toward certified low-residue supply chains. Dairy cooperatives consolidate intake through certified handlers in the Pays de la Loire region to pool REACH compliance costs and standardize quality verification.
Germany
Bavarian and Lower Saxony dairy operations deploy near-infrared spectroscopy units at 40% of new harvest contracts for unified protein measurement. ECHA-administered REACH frameworks shape residue thresholds conditioning buyer expectations for Asia-bound shipment eligibility. The Münsterland hay-processing corridor anchors premium-grade supply consistency through subscription-based forage quality monitoring services.
United States
Idaho and Washington hay processors leverage Pacific Northwest growing conditions to sustain leaf retention certification for interstate trade. USDA grade standards govern color uniformity expectations, creating inspection bottlenecks at seasonal peak windows. The Columbia Basin irrigation district concentrates compressed pellet production for distant buyers seeking transport cost reductions.
Australia
Riverina district growers integrate lucerne into orchard intercropping systems for organic certification pathways in stone fruit and nut production. TGA-equivalent agricultural chemical regulators, together with state-level residue monitoring protocols, condition export eligibility for Asia-bound shipments. Victorian hay processors invest in controlled-atmosphere storage networks to meet Middle Eastern dairy feed security contract specifications.
Lucerne Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across a structurally fragmented lucerne market. Tier-one processors with controlled-atmosphere storage networks capture premium margins from dairy cooperatives requiring supply consistency, while regional baling operations serve cost-sensitive cattle feeders through wholesale channels. Three archetypes dominate: vertically integrated hay-to-pellet processors, geographic-specialist exporters with irrigation-advantaged sourcing, and subscription-based quality monitoring platforms. Competitive intensity centers on compressed pellet format expansion and farm-direct contracting infrastructure that bypasses traditional wholesale intermediaries.
Among US-based hay processors, Anderson Hay & Grain and Standlee Hay occupy positions representing the integrated processor archetype with Pacific Northwest and Intermountain West sourcing footprints. Al Dahra Holding LLC, a UAE-based entity, exemplifies the geographic-specialist exporter model through Middle Eastern controlled-atmosphere storage networks serving dairy feed security contracts. These three entities anchor competitive positioning around format innovation and distant-market logistics economics rather than domestic volume scale alone.
| Leading Market Players |
|---|
| Anderson Hay & Grain |
| Haykingdom |
| Al Dahra Holding LLC |
| S&W Seed |
| Glenvar Hay |
| Alfalfa Monegros |
| Standlee Hay |
| Border Valley |
| Grupo Osés |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal nitrogen-management protocols gate qualified supply for premium-tier lucerne, compressing procurement into irrigation-efficient clusters where controlled-atmosphere infrastructure commands margin premiums from protein-dependent dairy cooperatives.
Pricing Analysis
Yield-linked protein premiums anchor lucerne pricing, with crude protein concentrations of 15-22% dry matter determining contract tiers for large-scale milk production systems. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified leaf retention grades from uncertified bulk shipments. Cost compression in economy-tier bales is intensifying because silage substitution from corn and grass alternatives pressures feed budgeting. Cattle cooperatives exhibit highest price sensitivity, while Middle Eastern dairy security contracts demonstrate lowest elasticity due to supply consistency requirements.
Supply Chain Analysis
Phosphate fertilizer supply rests on Moroccan and Chinese phosphate rock exporters, with sulfur and potash inputs drawing from Canadian and Belarusian sources. Spain's Ebro Valley, France's Pays de la Loire, and Germany's Münsterland corridor concentrate processing infrastructure for EU-bound dairy feed. Single-region supply concentration amplifies drought-induced yield variability risk across perennial stand commitments. Distribution runs through certified wholesale handlers pooling REACH compliance costs, with compressed pellet formats bypassing traditional bulk logistics for distant buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU F-Gas Regulation creates a barrier-to-entry moat for processors with controlled-atmosphere storage networks, fragmenting margin capture toward certified handlers.
For Market Incumbents: Deploy subscription-based forage quality monitoring to lock in multi-year dairy herd nutrition commitments before breeding program timelines deliver climate-adaptive cultivars. Consolidate intake through Zaragoza-area processing clusters to pool refrigerant phase-down compliance costs. Counter silage substitution threat by anchoring protein-dependent milk yield economics in contract structures. For New Entrants and Emerging Players: Near-infrared spectroscopy integration at baling points offers a technology-first wedge into farm-direct contracting channels bypassing wholesale intermediaries. Target cost-sensitive cattle cooperatives in Australia's Riverina district where residue monitoring protocols fragment export eligibility toward certified supply chains. Pursue compressed pellet format specialization for Middle Eastern containerized shipment specifications. For Investors and Strategic Acquirers: Breeding program announcements for drought-tolerant Medicago sativa varieties are the leading indicator that multi-year rotation lock-in value is shifting toward adaptive cultivar IP holders. Five-to-ten year viability centers on processors with backward integration into irrigation-advantaged sourcing and downstream pellet distribution infrastructure. Watch for USDA grade standard enforcement intensity at interstate trade points as inspection bottleneck signal.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Network Expansion | Ebro Valley facilities capture EU F-Gas Regulation compliance premiums from French dairy cooperatives. |
| Compressed Pellet Production Scale-Up | Densified formats unlock Middle Eastern dairy feed security contracts previously blocked by bulk economics. |
| Subscription Quality Monitoring Platform | Anderson Hay & Grain deploys data capture across harvest stages for outcome-based pricing structures. |
| Farm-Direct Contracting Infrastructure | Traceability investment bypasses wholesale channels for cost-sensitive cattle cooperative procurement. |
| Climate-Adaptive Cultivar Development | Standlee Hay anchors long-term supply consistency against drought-induced yield variability risk. |
Study Parameters
Independent corroboration across hay processor operations managers, dairy nutritionists at large-scale cooperatives, and agricultural chemical regulatory affairs specialists underwrites the qualitative findings in this analysis. Primary interviews with Ebro Valley baling contractors, Middle Eastern feed procurement officers, and Australian export certification auditors combined with secondary validation from EU F-Gas Regulation implementation reports, USDA grade standards documentation, and Australian TGA-equivalent residue protocol filings. Bottom-up volume modeling across product type, distribution channel, and packaging format segments triangulates against top-down protein demand estimates from dairy herd nutrition commitments.
Comparable-period anchoring to historical hay trade flows and dairy feed procurement patterns shaped the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer configuration, and packaging density tier across the analysis window. CAGRs were derived from protein-dependent milk yield economics and irrigation-efficient cultivation expansion trajectories. Industry-specific forecast inputs incorporated phosphate fertilizer cost volatility indices and controlled-atmosphere storage capacity buildout timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under drought-induced yield variability in Spain's Ebro Valley cluster and phosphate fertilizer price spike conditions. Forecasts reflect assumptions around EU Green Deal nitrogen-management protocol enforcement intensity and REACH residue threshold harmonization across Asia-bound shipment destinations. A small set of triggers—breeding program cultivar release schedules, USDA inspection bottleneck severity at peak windows, and Middle Eastern dairy herd expansion rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Guarana Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Singapore Floriculture Market