
 South America Agricultural Machinery Market | 2026-2036
South America Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
South America Agricultural Machinery Market Analytics
Market Context
Multi-source procurement for precision agriculture components is shifting toward vertically integrated supply chains among major OEMs. John Deere leverages its dealer network density to control aftermarket parts flow across Brazil and Argentina. AGCO Corporation anchors its regional position through localized assembly at its Santa Rosa facility in Rio Grande do Sul. Mahindra & Mahindra Ltd. competes on price-adjusted tractor configurations tailored for mid-size Brazilian cooperatives.
Technical Definition and Segment Structure
South America agricultural machinery encompasses self-propelled and towed equipment engineered for soil preparation, planting, crop management, and harvest operations, with power ratings spanning 50 to 600 horsepower and compliance with regional emissions protocols. Tractors and harvesters command the dominant share of product-type revenue due to replacement cycles in Brazil's Cerrado expansion zones. Precision agriculture technology represents the fastest-growing segment as variable-rate application systems displace conventional broadcast methods among agribusinesses. Diesel engines retain structural importance in technology segmentation, though IoT integration is creating new margin pools through subscription-based fleet management services.
Regulatory Framework and Outlook
Brazil's PROTRATOR rural credit program and ANFAVEA emissions standards, alongside Argentina's depreciation incentives and INTA certification requirements, directly shape equipment affordability and import competitiveness. ANVISA and INMETRO standards govern operator safety and environmental compliance for machinery sold across Mercosur trading zones. Stakeholders must monitor how Brazil's Central Bank interest rate adjustments affect PROTRATOR credit availability and replacement demand timing.
Market Dynamics
PROTRATOR credit availability from Brazil's Central Bank is compressing replacement cycles, forcing OEMs to synchronize production schedules with subsidy disbursement windows rather than seasonal planting calendars.
Growth Catalysts
- Variable-rate application systems:Brazilian agribusinesses in Mato Grosso are retrofitting existing fleets with precision agriculture modules to reduce fertilizer waste on Cerrado expansion zones.
- Argentina's accelerated depreciation:The country's tax treatment of agricultural equipment shortens payback periods for mid-size cooperatives purchasing 150-250 horsepower tractors.
- Mechanization gaps in Goiás:Harvester density per hectare trails Paraná benchmarks by 40%, creating replacement pull as soybean acreage consolidates.
Market Restraints
- Diesel engine import dependency:Powertrain sourcing concentrates in Mercosur-adjacent supply bases, exposing assemblers to currency volatility against the Brazilian real.
- ANFAVEA emissions compliance costs:Tier 4 equivalent standards add 12-18% to powertrain costs for equipment below 75 horsepower, squeezing margin on entry-level configurations.
- Used equipment arbitrage:Depreciated North American harvesters flood Paraguayan and Uruguayan secondary markets, delaying new-equipment absorption.
Strategic Opportunities
- Subscription-based fleet telemetry:IoT-enabled uptime guarantees are penetrating large-scale operations in Rio Grande do Sul, converting capital expenditure into recurring revenue for OEMs.
- INTA certification pathways:Argentina's agricultural technology institute offers streamlined approval for precision planting attachments, accelerating aftermarket penetration.
- Cooperative financing pools:Mid-size Brazilian buyers are aggregating procurement through state-level credit unions, creating volume aggregation channels bypassing traditional dealer networks.
Industry Challenges
- Telematics integration with legacy fleets:Pre-2015 tractors lack CAN bus architecture, requiring expensive retrofit kits that erode precision agriculture ROI calculations.
- Certification timeline compression:INMETRO safety testing queues extend 8-14 months for new harvester models, misaligning product launches with planting season windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Agricultural Machinery Market |
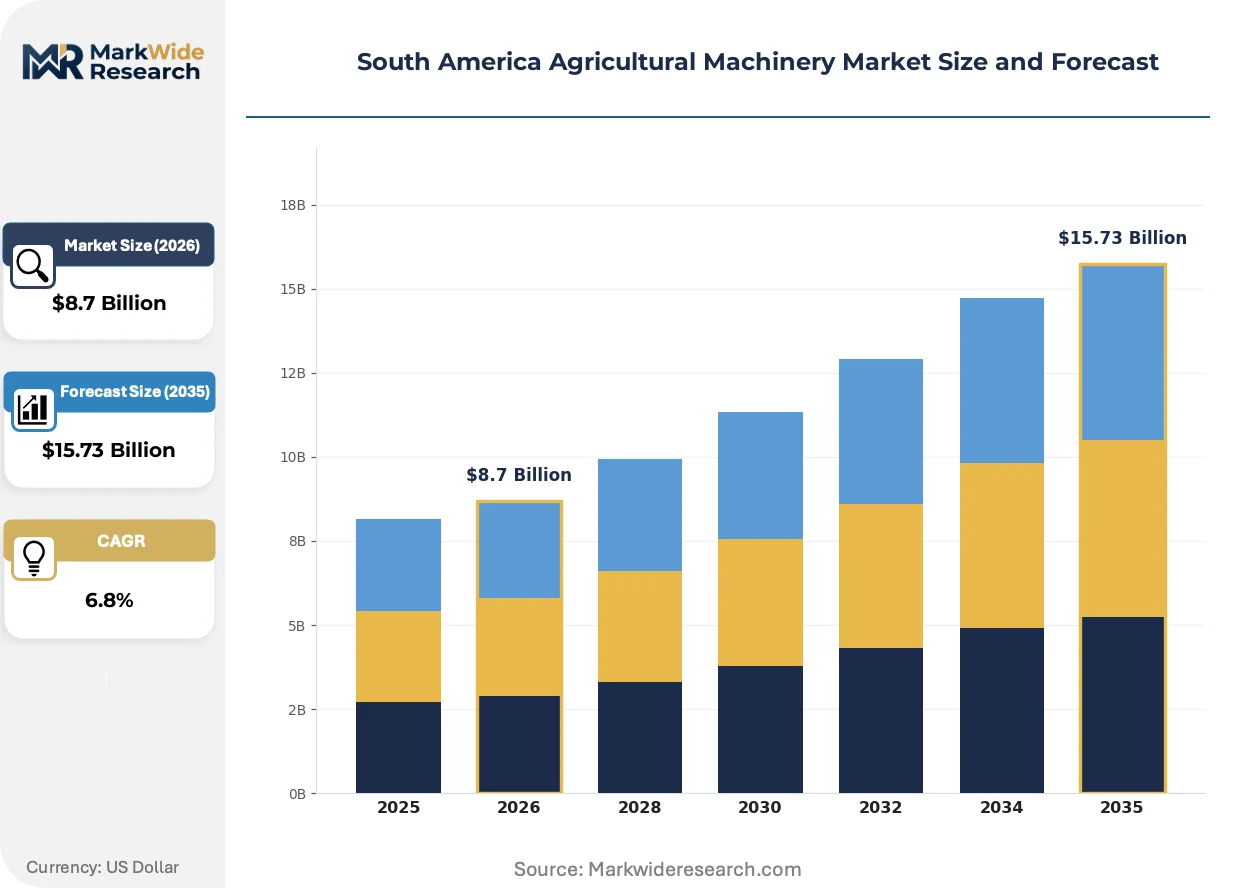
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Plows, Seeders, Harvesters Technology: Precision Agriculture, Automation, IoT Integration, Diesel Engines End User: Farmers, Cooperatives, Agribusinesses, Research Institutions Distribution Channel: Dealerships, Online Retail, Direct Sales, Distributors |
| Companies Covered | Kubota Corporation, CLAAS KGaA mbH, John Deere, SDF Group, Yanmar Holdings Co., Ltd., AGCO Corporation, Mahindra & Mahindra Ltd., Agrale S.A., CNH Industrial, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Agricultural Machinery Market Evolving Landscape
Electrification pressures and data monetization are splitting equipment value creation between hardware durability and software-enabled productivity guarantees, restructuring how OEMs capture margin across the ownership lifecycle.
Autonomous guidance systems are modularizing across tractor and harvester platforms, allowing Brazilian operators to upgrade path-planning capabilities without full machine replacement. Large-scale soy producers in Mato Grosso are adopting these retrofits at 18-24 month intervals. This modularity is compressing traditional 7-year replacement cycles into component-level refresh schedules.
ANVISA operator safety standards are tightening cabin visibility and emergency shutoff requirements for machinery operating in Mercosur trading zones. Brazilian assemblers must redesign operator environments to accommodate these mandates. Harvester manufacturers face the steepest redesign burden due to elevated cabin positioning and blind-spot complexity.
Cooperative buyers are consolidating procurement through centralized purchasing desks, displacing individual farm-level dealer relationships. State-level credit unions in Goiás and Mato Grosso now negotiate fleet-scale pricing directly with OEM regional offices. This concentration is visible most acutely in 100-200 horsepower tractor segments where cooperative membership density exceeds 60%.
South America Agricultural Machinery Market Segmentation
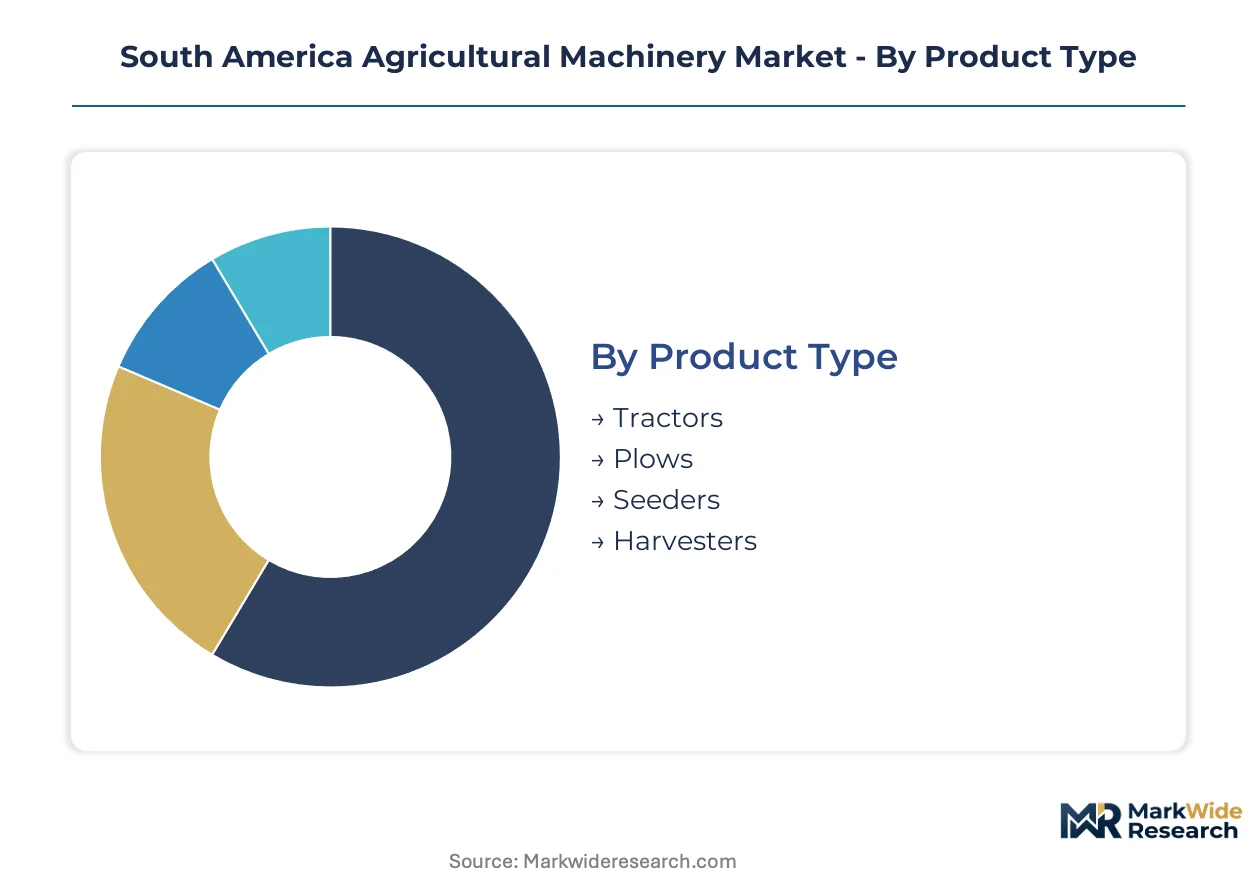
Equipment replacement cycles in South America diverge sharply across product configurations and operator scale. Understanding these segment boundaries clarifies where subsidy timing, credit availability, and technology refresh rates concentrate purchasing decisions.
Product Type:
Replacement cycles compress where fleet standardization meets financing program windows, stretching where secondary equipment arbitrage remains active.
- Tractors:Self-propelled units span 50-600 horsepower ratings with power take-off systems for implements. Demand clusters in Mato Grosso and Goiás states where mechanization rates trail Paraná benchmarks by 40% and PROTRATOR credit availability accelerates 150-250 horsepower acquisitions among mid-size operators.
- Harvesters:Self-propelled combines and forage harvesters engineered for soy, corn, and sugarcane operations with grain tank capacities exceeding 10,000 liters. Brazilian agribusinesses in Cerrado expansion zones dominate volume as consolidation drives fleet standardization and uptime guarantees become procurement criteria.
- Plows:Towed soil preparation implements including moldboard, disc, and chisel configurations. Argentine mid-size cooperatives favor accelerated depreciation-eligible units.
- Seeders:Precision planting equipment with variable-rate capability. INTA certification pathways in Argentina streamline aftermarket attachment approvals.
Volume placements concentrate in Tractors; the faster expansion belongs to Harvesters.
Technology:
Margin capture is shifting from hardware durability toward software-enabled productivity guarantees and subscription telemetry services.
- Precision Agriculture:Variable-rate application systems for seeding, fertilization, and crop protection using GPS guidance and soil mapping. Brazilian agribusinesses in Mato Grosso retrofit existing fleets to reduce fertilizer waste on Cerrado expansion zones where input costs pressure operating margins.
- Diesel Engines:Compression-ignition powertrains compliant with ANFAVEA Tier 4 equivalent emissions standards. Import dependency from Mercosur-adjacent supply bases exposes assemblers to currency volatility against the Brazilian real.
- IoT Integration:Connected fleet management platforms with subscription-based uptime guarantees. Large-scale operations in Rio Grande do Sul convert capital expenditure into recurring revenue relationships.
- Automation:Autonomous guidance systems modularizing across platforms. Mato Grosso soy producers adopt path-planning retrofits at 18-24 month intervals, compressing traditional 7-year replacement cycles.
Hardware procurement dominates current placements; telemetry and automation services are climbing the fastest.
End User:
Customer concentration patterns determine whether procurement flows through dealer networks or bypasses toward direct OEM negotiation.
- Agribusinesses:Large-scale integrated operations exceeding 10,000 hectares with centralized fleet management. These buyers negotiate fleet-scale pricing directly with OEM regional offices in Goiás and Mato Grosso, displacing traditional dealer relationships.
- Cooperatives:Member-owned agricultural enterprises aggregating procurement through state-level credit unions. Cooperative membership density exceeds 60% in 100-200 horsepower tractor segments, creating volume aggregation channels with concentrated bargaining power.
- Farmers:Individual owner-operators below 500 hectares dependent on PROTRATOR credit timing and dealer proximity.
- Research Institutions:Agricultural universities and INTA field stations acquiring specialized demonstration equipment.
Cooperative and agribusiness procurement concentrates volume; individual farmer replacement demand is expanding most quickly as credit access broadens.
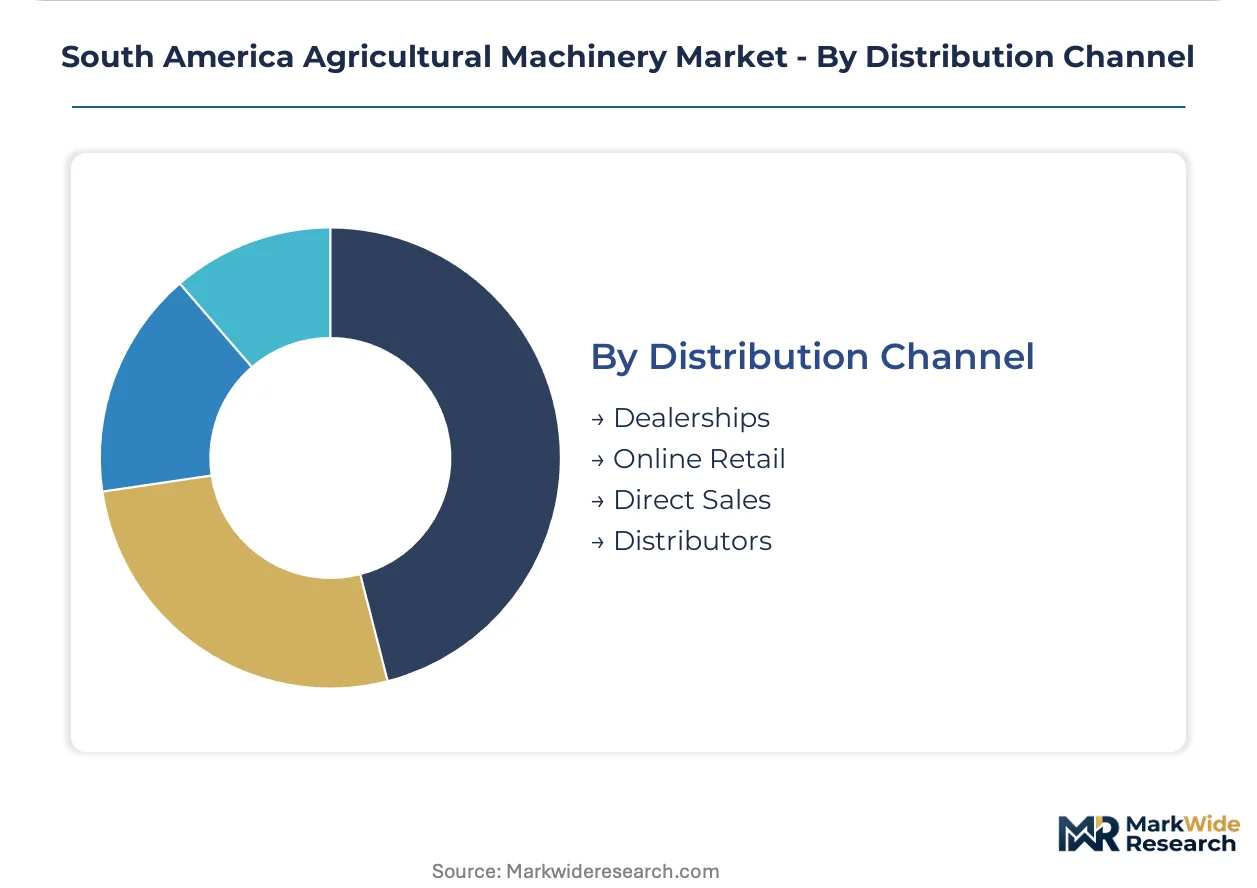
Distribution Channel:
Channel structure reflects the tension between OEM network control and buyer aggregation through alternative financing arrangements.
- Dealerships:Authorized retail networks providing sales, service, and parts distribution. John Deere leverages network density to control aftermarket parts flow across Brazil and Argentina.
- Direct Sales:OEM-to-buyer transactions bypassing intermediaries for fleet-scale orders. State-level credit unions in Goiás and Mato Grosso now negotiate directly with regional offices for cooperative procurement pools.
- Distributors:Independent wholesalers serving secondary markets and smaller operators in Paraguay and Uruguay where used North American equipment arbitrage delays new-equipment absorption.
- Online Retail:Digital platforms for parts, implements, and smaller equipment configurations.
Dealership networks retain the largest placement volumes; direct sales channels are gaining share fastest as cooperative procurement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean and corn cultivation zones anchor equipment demand across South America, with mechanization intensity varying sharply between established farming belts and frontier expansion areas. Credit availability and subsidy timing determine purchasing windows more than seasonal planting cycles.
Brazil
Mato Grosso and Goiás states drive tractor and harvester volume as large-scale soy operations consolidate acreage. The Central Bank's PROTRATOR rural credit program compresses replacement cycles, forcing OEMs to align production with disbursement windows rather than harvest calendars. Santa Rosa in Rio Grande do Sul hosts localized assembly operations serving southern cooperative networks.
Argentina
Pampas grain belts generate sustained demand for mid-size tractors eligible for accelerated depreciation treatment. INTA certification requirements streamline precision agriculture attachment approvals, reducing aftermarket entry barriers. Córdoba and Buenos Aires provinces concentrate cooperative procurement through centralized purchasing desks.
Paraguay
Secondary equipment arbitrage from North American used harvester imports delays new-machine absorption in border regions. Distributor networks dominate channel structure where dealer density remains thin. Eastern departments facing Brazilian soy expansion zones see gradual fleet modernization pressure.
Uruguay
Pasture-to-cropland conversion in northern departments creates intermittent machinery demand spikes. Currency volatility against the Brazilian real shapes import competitiveness for Argentine and Brazilian equipment. Montevideo serves as regional financing hub for cross-border cooperative credit arrangements.
Chile
Central Valley fruit and wine operations sustain niche demand for specialized harvesters and precision irrigation equipment. ANVISA-aligned safety standards govern cabin redesign requirements for Mercosur market access. Santiago-based distributors coordinate aftermarket parts flow for multinational fleet operators.
South America Agricultural Machinery Market Competitive Landscape
Global majors compete with regional champions across financing access and aftermarket service density. Market structure shows moderate consolidation, with tiered competition separating full-line providers from specialized harvester or tractor specialists. Three archetypes dominate: integrated full-line OEMs with captive finance arms, regional assemblers leveraging local content rules, and precision agriculture technology licensors. Capacity expansion and strategic partnerships with cooperative credit unions represent the dominant competitive moves reshaping channel control.
Within the full-line integrated tier, John Deere and AGCO Corporation exemplify archetypes built on dealer network density and localized assembly respectively. Mahindra & Mahindra Ltd. occupies a position as price-adjusted configuration specialist targeting mid-size Brazilian cooperatives. Among regional champions, Agrale S.A. anchors the Brazil-centric assembly archetype leveraging PROTRATOR program eligibility.
| Leading Market Players |
|---|
| Kubota Corporation |
| CLAAS KGaA mbH |
| John Deere |
| SDF Group |
| Yanmar Holdings Co., Ltd. |
| AGCO Corporation |
| Mahindra & Mahindra Ltd. |
| Agrale S.A. |
| CNH Industrial |
| Others |
Value Network & Pricing Analysis
Cooperative procurement pools in Brazil's Mato Grosso and Goiás states command fleet-scale pricing leverage, anchoring contract structures around subscription-based telemetry bundles rather than standalone equipment transactions. This buyer concentration reshapes how OEMs monetize hardware durability against software-enabled productivity guarantees.
Pricing Analysis
Warranty and service bundling separates premium configurations from standard tiers, with uptime guarantees and preventive maintenance contracts now standard in agribusiness fleet negotiations. Price differentiation rests on precision agriculture module integration and PROTRATOR credit eligibility tiers. Cost compression in entry-level tractors below 75 horsepower intensifies due to ANFAVEA Tier 4 compliance burdens. Smallholder farmers dependent on seasonal credit windows exhibit highest price sensitivity; large-scale integrated operators prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
INMETRO safety certification and ANFAVEA emissions qualification gating extends 8-14 months for new harvester models, misaligning product launches with planting calendars. Powertrain sourcing concentrates in Argentina, Brazil, and Mercosur-adjacent supply bases. Diesel engine castings, precision hydraulics, and GPS guidance modules constitute critical input dependencies. Single-source vulnerability in Tier 4 equivalent engine supply exposes assemblers to Brazilian real volatility. Distribution runs through authorized dealer networks in Brazil and Argentina, with direct OEM channels penetrating cooperative procurement pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America agricultural machinery sector sits at a technology-transition inflection, with IoT-enabled fleet telemetry displacing conventional ownership models and autonomous guidance retrofits fragmenting traditional replacement cycles.
For Market Incumbents: Lock in cooperative procurement relationships through captive financing arms aligned with PROTRATOR disbursement windows. Deepen backward integration into precision agriculture module production to defend margin pools against technology licensors. Prioritize INMETRO certification pipeline investments to compress approval timelines and synchronize launches with subsidy availability. For New Entrants and Emerging Players: Argentina's accelerated depreciation rules open a window for mid-size tractor configurations targeting 150-250 horsepower cooperative demand. Penetrate Goiás harvester density gaps where mechanization trails Paraná benchmarks. Pursue INTA certification pathways for precision planting attachments to accelerate aftermarket penetration without full-line manufacturing investment. For Investors and Strategic Acquirers: The window for entry favors precision agriculture technology licensors with modular retrofit architectures and established telemetry platforms. Long-term viability hinges on recurring revenue conversion rather than hardware shipment volumes. Monitor PROTRATOR credit availability from Brazil's Central Bank as the primary inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Fleet Telemetry | Converts John Deere and AGCO capital expenditure relationships into recurring revenue streams across Rio Grande do Sul agribusinesses. |
| Backward Integration into Precision Modules | Captures margin pools from variable-rate application systems displacing conventional broadcast methods in Mato Grosso. |
| Cooperative Credit Union Partnerships | Creates volume aggregation channels bypassing traditional dealer networks in Goiás and Mato Grosso procurement concentration. |
| INMETRO Certification Pipeline Investment | Compresses 8-14 month safety testing queues to align harvester launches with Brazilian planting season windows. |
| INTA Certification Pathway Navigation | Accelerates aftermarket precision planting attachment approvals for Argentine mid-size cooperative penetration. |
Research Methodology
Independent corroboration across OEM regional sales directors, cooperative procurement managers, and Central Bank agricultural credit officers underwrites the qualitative findings. Primary interviews with dealer network operators, aftermarket service heads, and precision agriculture technology providers combined with secondary validation from ANFAVEA production statistics, ANVISA safety filings, and PROTRATOR disbursement records. Bottom-up equipment placement estimates triangulate against top-down credit flow analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span product type, technology tier, end-user scale, and distribution channel structure. CAGRs derive from replacement cycle modeling synchronized with subsidy program windows and credit availability cycles. Forecast inputs incorporate Cerrado expansion acreage trajectories and cooperative membership density trends.
The model assumes a particular technology adoption path; alternative pathways for autonomous guidance retrofits would alter the outlook. Forecasts reflect assumptions regarding PROTRATOR credit continuity and ANFAVEA emissions phase-in schedules. A model refresh is warranted upon material change in Brazil's Central Bank interest rate policy affecting rural credit availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Autonomous Agricultural Machinery Market