
 Asia Pacific Animal Feed Market | 2026-2036
Asia Pacific Animal Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Animal Feed Market Analysis
Distributor networks across Southeast Asia is fragmenting as integrated livestock conglomerates build direct-to-farm supply arms. Charoen Pokphand Foods Public Company Limited leverages captive breeding-to-processing pipelines to lock in feed offtake across Thailand and Vietnam. New Hope Liuhe Co., Ltd. anchors its position through massive compound feed manufacturing scale in Sichuan and neighboring provinces. Cargill, Incorporated competes by positioning its aquaculture nutrition division to serve Indonesia's expanding marine cage operations.
Asia Pacific animal feed encompasses formulated nutritional products combining cereals, oilseed meals, protein supplements, and micronutrients processed through extrusion, pelleting, or mash blending to meet species-specific dietary requirements for livestock, aquaculture, and companion animals. Complete feed formulations dominate volume flows as poultry farmers and aquaculture producers prioritize convenience and ration consistency over mixing concentrates on-site. Premixes and additives capture disproportionate margin pools where Tongwei Co., Ltd. and Guangdong Haid Group Co., Ltd. specialize in vitamin-mineral blends and enzyme formulations for high-density shrimp ponds. Corn and soybean meal anchor raw material procurement, though wheat substitution rises when South American soybean logistics tighten.
China's SAMR enforces GB standards for mycotoxin limits and antibiotic residue thresholds, while India's FSSAI mandates feed ingredient registration and labeling transparency under evolving 2024 directives. Japan's METI coordinates with JIS standards bodies to certify imported aquafeed safety, creating compliance layers for exporters targeting premium marine product supply chains. Stakeholders must monitor how Indonesia's national feed self-sufficiency targets reshape import licensing for corn and soybean derivatives.
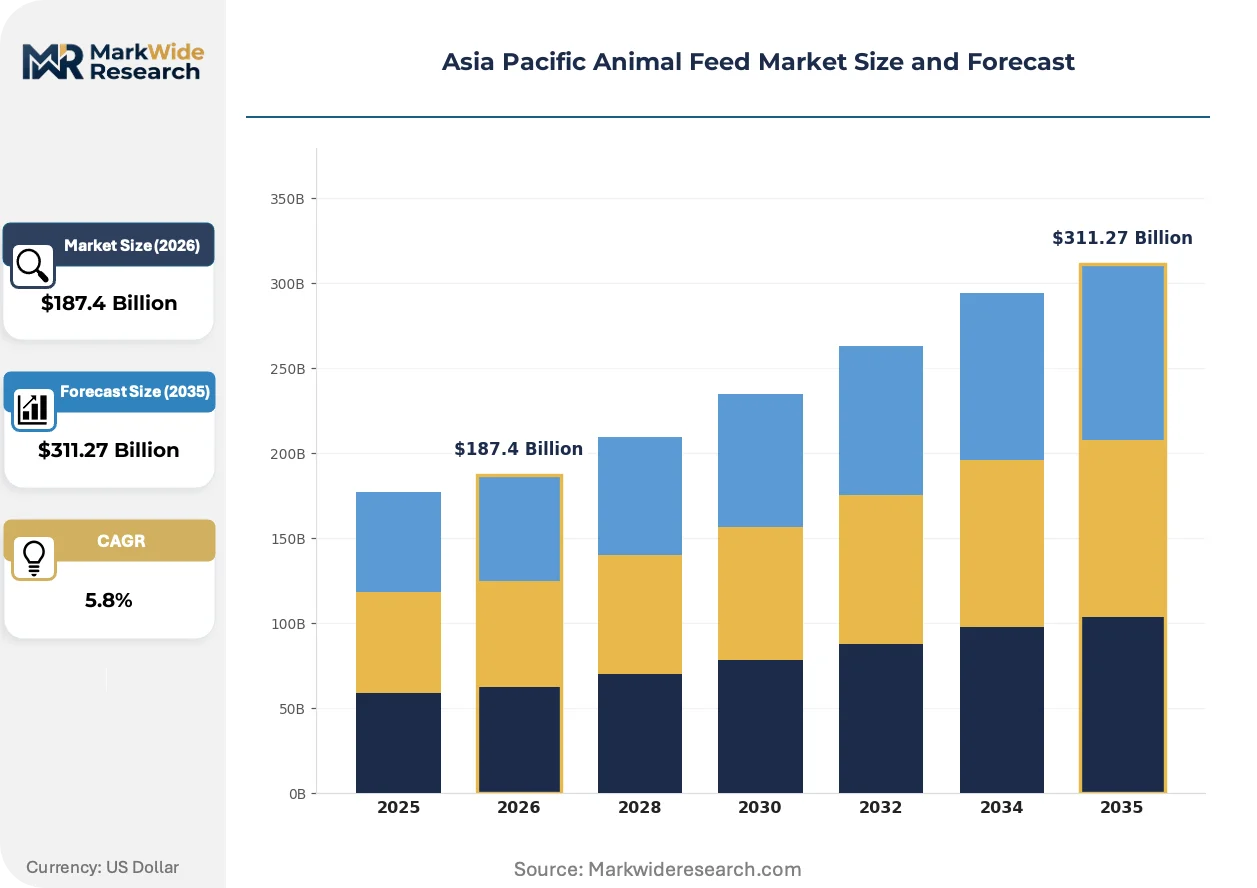
Market Dynamics
Intensive aquaculture expansion across Southeast Asia is restructuring feed procurement patterns as shrimp and finfish producers abandon farm-mixed rations for mill-delivered formulations. China's GB standards for antibiotic-free feed and India's FSSAI safety directives are compressing formulation flexibility while elevating compliance costs for regional suppliers.
Growth Catalysts
- Antibiotic-Free Mandates:China's SAMR enforcement of GB standards for residue thresholds forces formulation upgrades across domestic mills, accelerating enzyme and probiotic adoption in poultry and aquafeed rations.
- Mekong Delta Clustering:Vietnam's integrated aquafeed mills concentrate near shrimp processing zones, reducing logistics costs for intensive pond operators scaling from semi-intensive systems.
- FSSAI Registration Requirements:India's 2024 feed ingredient labeling directives tighten supply chain traceability, favoring organized compound feed manufacturers over informal mixers in dairy and poultry belts.
Market Restraints
- South American Soybean Logistics:Port congestion and export licensing volatility in Brazil and Argentina create raw material cost spikes, forcing wheat substitution that alters amino acid profiles in finished feeds.
- Mycotoxin Surveillance Gaps:Tropical storage conditions across Southeast Asia elevate aflatoxin contamination risks in corn silos, requiring costly testing infrastructure that small mills cannot absorb.
- Import Licensing Friction:Indonesia's national feed self-sufficiency targets restrict corn and soybean derivative import permits, constraining formulation flexibility for domestic aquafeed producers.
Strategic Opportunities
- Philippines Marine Cage Expansion:Untapped demand for high-performance tilapia and milkfish feeds in Mindanao and Visayas coastal zones offers first-mover positioning for extruded floating ration specialists.
- Premix Distribution Innovation:Direct-to-farm micronutrient delivery via mobile veterinary networks bypasses fragmented rural distributors, capturing margin pools in India's scattered dairy cooperative segments.
- Enzyme-Probiotic Convergence:Phytase and Bacillus strain combinations in shrimp feeds address both phosphorus discharge regulations and gut health optimization, aligning with Vietnam's environmental compliance timelines.
Industry Challenges
- Formulation Chemist Scarcity:Shortage of aquafeed nutritionists capable of balancing amino acid profiles for high-density shrimp ponds limits mill expansion in Vietnam and Indonesia.
- GB Standard Certification Timelines:China's SAMR approval processes for novel feed additives extend 18-24 months, delaying product launches against faster-moving competitors in other Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Animal Feed Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Concentrates, Premixes, Additives End User: Poultry Farmers, Aquaculture Producers, Ruminant Breeders, Pet Owners Raw Material: Corn, Soybean Meal, Wheat, Fish Meal Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Charoen Pokphand Foods Public Company Limited, New Hope Liuhe Co., Ltd., Cargill, Incorporated, Tongwei Co., Ltd., Guangdong Haid Group Co., Ltd., Archer-Daniels-Midland Company, Godrej Agrovet Limited, East Hope Group, Japfa, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Animal Feed Market Emerging Trajectories
Digital feed formulation platforms and precision aquaculture monitoring systems are compressing the gap between laboratory ration design and pond-side delivery. These technologies enable real-time adjustment of protein and energy densities based on biomass sensors and automated feeding triggers.
Extrusion technology with inline fat coating is virtualizing the traditional post-pelleting liquid application process. Thai and Vietnamese aquafeed producers adopt these integrated systems to achieve uniform lipid distribution in high-oil shrimp feeds. The technology is virtualizing quality control workflows by embedding near-infrared spectroscopy directly into production lines, reducing offline laboratory testing bottlenecks.
Japan's METI coordination with JIS standards bodies for imported aquafeed safety certification creates compliance layering that exporters must navigate for premium marine product supply chains. The industrial consequence is bifurcation between commodity feed exporters and certified suppliers serving sashimi-grade tuna and yellowtail operations. Indonesia's expanding marine cage sector faces the steepest adaptation curve as METI documentation requirements extend beyond product testing to facility audits.
Shrimp farmers in Vietnam's Mekong Delta now specify feed based on feed conversion ratio guarantees rather than unit price, compressing supplier switching cycles and elevating technical service demands. This specification behavior displaces traditional distributor relationships with direct mill partnerships. The shift is most visible in Bac Lieu and Ca Mau provinces where intensive super-intensive pond systems dominate production volumes.
Asia Pacific Animal Feed Market Segmentation
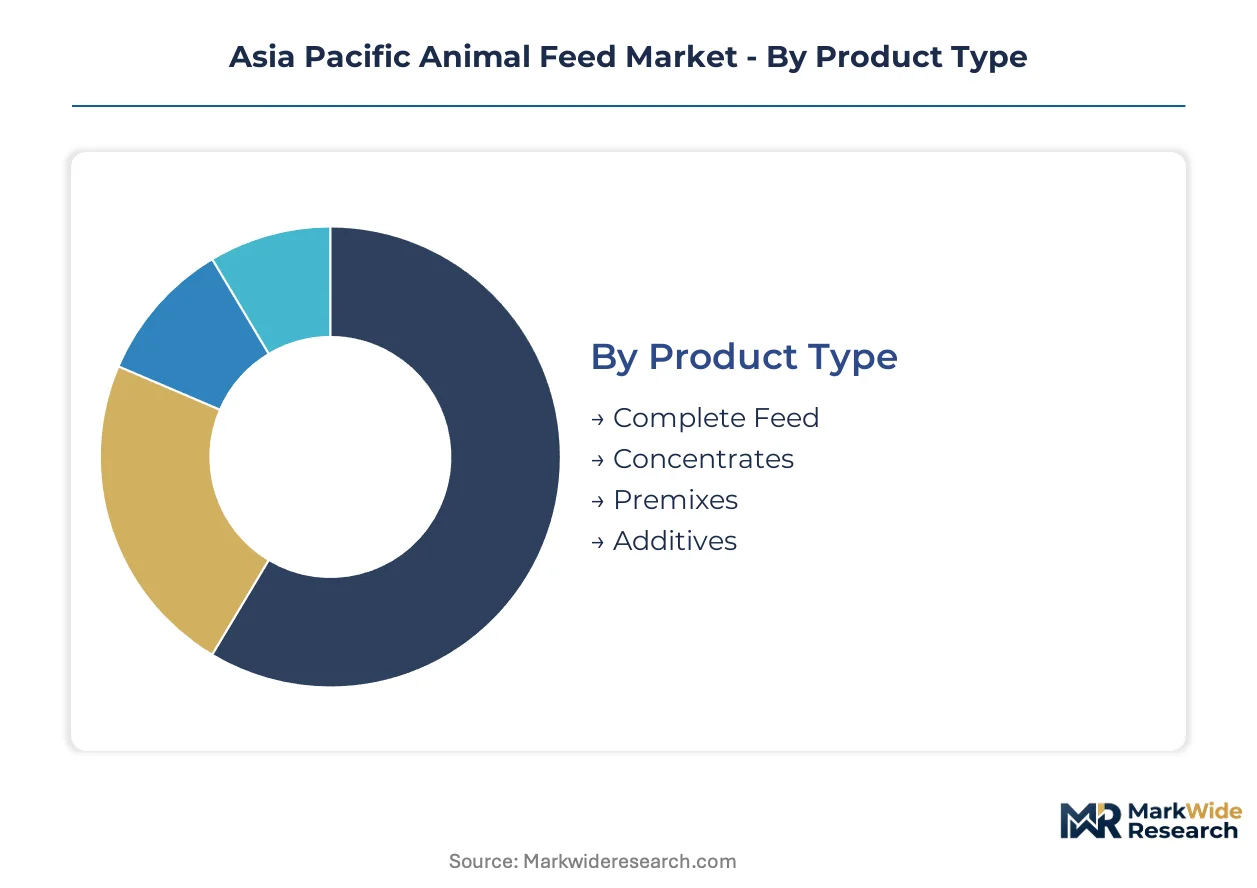
Asia Pacific feed buyers exhibit sharply divergent procurement behaviors across species and farm scale. Segmentation reveals how technical service intensity, formulation complexity, and channel economics reshape supplier economics in this fragmented landscape.
Product Type:
After-sales technical support intensity varies dramatically across product tiers, with premix and additive segments demanding sustained on-farm nutritionist engagement while complete feed transactions conclude at delivery.
- Complete Feed:Formulated rations delivering full nutritional requirements in ready-to-use pellets or mash, eliminating on-farm mixing labor. Demand concentrates in Vietnam's Mekong Delta intensive shrimp ponds and Thailand's broiler belt, where farm labor scarcity and FCR accountability pressures favor mill-delivered consistency over self-mixing.
- Premixes:Concentrated vitamin-mineral-enzyme blends requiring dilution into base feeds, capturing margin pools where technical differentiation matters. China's SAMR antibiotic-free mandates accelerate adoption as farms seek probiotic and phytase solutions to maintain performance without growth promoters.
- Concentrates:Protein-rich supplements blended with farm-sourced grains to reduce transport costs. India's FSSAI labeling directives favor organized manufacturers supplying dairy cooperatives in Gujarat and Punjab over informal village mixers.
- Additives:Functional ingredients including acidifiers, mycotoxin binders, and gut health modulators deployed at inclusion rates below 1%. Indonesia's marine cage expansion drives demand for heat-stable probiotic formulations suited to tropical storage conditions.
By volume, Complete Feed leads. By growth pace, Premixes are climbing the fastest as regulatory pressure and performance guarantees reshape procurement specifications.
End User:
Customer scale and sophistication fragment service economics, with aquaculture and poultry operations demanding formulation guarantees while ruminant and pet segments tolerate standardized products.
- Poultry Farmers:Broiler and layer operations across India, Thailand, and Vietnam purchasing complete feeds on FCR-linked contracts. Indonesia's feed self-sufficiency targets constrain import-dependent formulations, favoring domestic mill relationships.
- Aquaculture Producers:Shrimp and finfish farmers specifying extruded floating or sinking feeds with guaranteed conversion ratios. Vietnam's Mekong Delta clustering enables direct mill partnerships displacing traditional distributors.
- Ruminant Breeders:Dairy cooperatives and cattle fattening operations in India and Pakistan sourcing concentrates and mineral blocks. FSSAI registration requirements tighten supply chain traceability for organized players.
- Pet Owners:Premium dog and cat food buyers in Japan, South Korea, and urban China driving super-premium kibble and wet food demand. METI-JIS certification requirements create compliance layering for imported specialty formulations.
Poultry Farmers anchor volume flows. Aquaculture Producers gain share fastest as intensive pond systems displace extensive farming across Southeast Asia.
Raw Material:
Input cost volatility and substitution elasticity segment procurement strategies, with amino acid balancing expertise determining competitive position when South American logistics tighten.
- Corn:Primary energy source anchoring formulations across poultry and swine feeds. Tropical storage conditions elevate aflatoxin surveillance costs, favoring mills with inline near-infrared testing infrastructure.
- Soybean Meal:Dominant protein input whose South American supply volatility forces wheat and alternative protein substitution. China's GB mycotoxin standards compress sourcing flexibility for domestic mills.
- Wheat:Energy substitute gaining inclusion when soybean logistics spike, requiring amino acid supplementation to maintain performance. Australian and Black Sea supply flows serve Southeast Asian aquafeed producers.
- Fish Meal:High-value marine protein for shrimp and high-performance finfish feeds, constrained by Peruvian anchovy quota volatility. Substitution pressure from insect meal and single-cell proteins intensifies.
Corn and Soybean Meal dominate volume. Fish Meal commands premium positioning despite supply constraints.
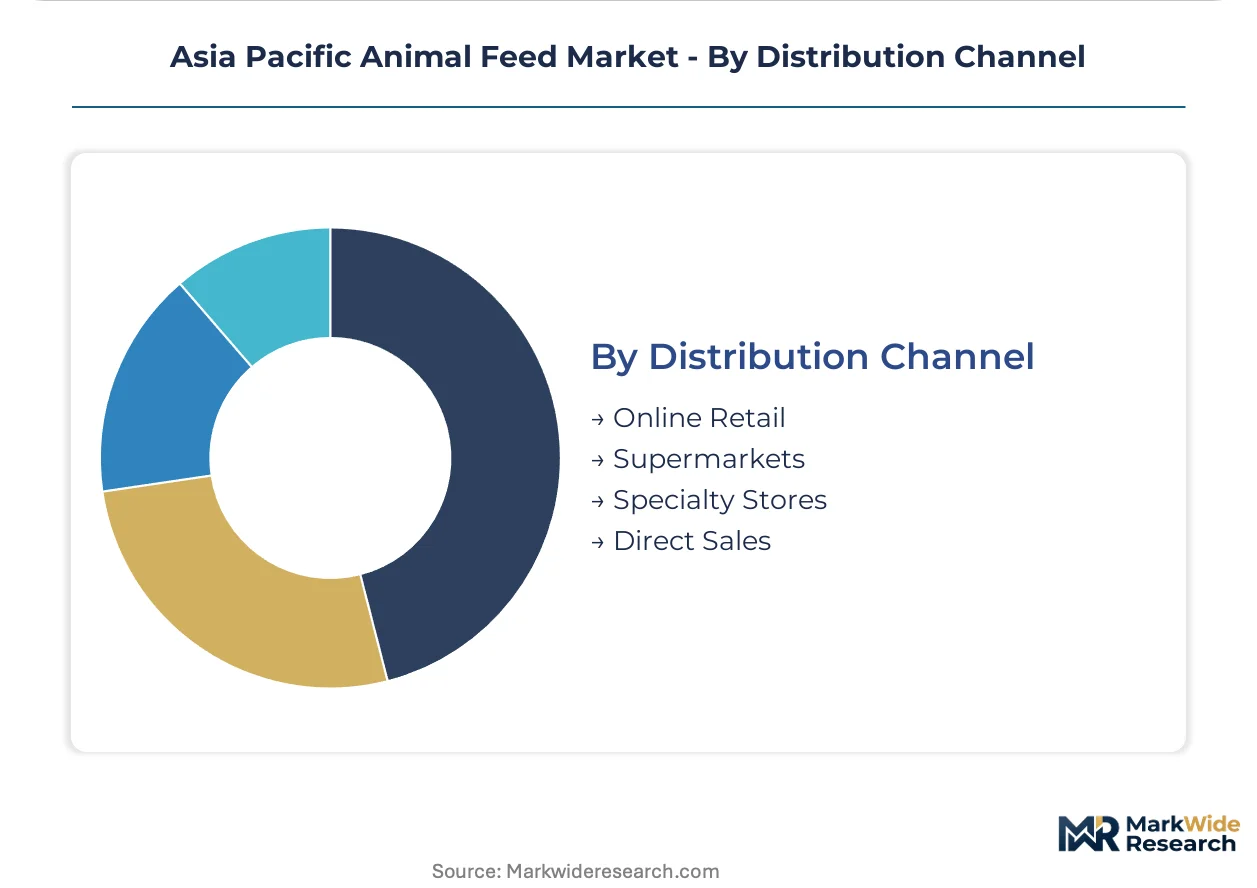
Distribution Channel:
Channel economics fragment by customer scale and geography, with direct sales capturing intensive operations while rural fragmentation sustains distributor relevance for scattered smallholders.
- Direct Sales:Mill-to-farm contracts serving large-scale poultry integrators and aquaculture clusters. Thailand's Charoen Pokphand and Vietnam's Haid Group deploy captive technical teams for pond-side service.
- Specialty Stores:Independent feed retailers serving dairy cooperatives and semi-intensive shrimp farmers with credit terms and local delivery. India's cooperative structure sustains this channel in Gujarat and Maharashtra.
- Supermarkets:Mass-market pet food and small-pack poultry feed for backyard producers. Urbanization in Indonesia and Philippines expands shelf space for branded companion animal products.
- Online Retail:Emerging channel for premix samples, specialty additives, and direct-to-farm micronutrient delivery. Mobile veterinary networks in India pilot digital ordering for dairy cooperative members.
Direct Sales leads by volume. Online Retail expands most quickly as digital platforms compress rural distribution gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing leverage through captive soybean crushing capacity, while Vietnam's Mekong Delta processors absorb freight premiums for imported protein meals. This asymmetry reshapes procurement patterns across Southeast Asian aquaculture belts.
China
Sichuan and neighboring provinces anchor compound feed manufacturing scale for poultry and swine operations. SAMR enforces GB standards for mycotoxin limits and antibiotic residue thresholds, compressing formulation flexibility for domestic mills. The Yangtze River Delta corridor clusters aquafeed production near Shanghai's port infrastructure for imported fish meal processing.
Vietnam
Intensive shrimp pond expansion across Bac Lieu and Ca Mau provinces drives formulated feed offtake as farmers abandon farm-mixed rations. The country's feed safety framework aligns with regional export certification requirements for EU and US seafood markets. Integrated aquafeed mills concentrate near Mekong Delta processing zones to reduce logistics costs for super-intensive pond operators.
India
Dairy cooperatives in Gujarat and Maharashtra sustain concentrate demand as FSSAI registration requirements tighten supply chain traceability. The 2024 feed ingredient labeling directives favor organized compound feed manufacturers over informal village mixers. Poultry belt operations across Haryana and Punjab purchase complete feeds on FCR-linked contracts with technical service guarantees.
Thailand
Broiler integrators deploy captive breeding-to-processing pipelines that lock in feed offtake across the Central Plains. Charoen Pokphand Foods leverages vertical control from genetics through processing to secure ration consistency. Eastern seaboard aquaculture zones specify extruded feeds with guaranteed conversion ratios for intensive marine cage operations.
Indonesia
Marine cage expansion across Sulawesi and Sumatra coastal waters drives demand for high-performance tilapia feeds. National feed self-sufficiency targets restrict corn and soybean derivative import permits, constraining formulation flexibility for domestic aquafeed producers. Java-based mills face raw material cost volatility as logistics from South American suppliers encounter port congestion delays.
Asia Pacific Animal Feed Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin pools in vitamin-mineral blends and enzyme formulations. The vendor base concentrates around three to four conglomerates with captive supply chains, while mid-scale compounders compete on technical service intensity for aquaculture clusters. Strategic archetypes include breeding-to-processing integrators, commodity-scale compounders, and premix-specialist nutrition houses. Competitive moves center on direct-to-farm technical team deployment and extrusion technology upgrades for high-oil shrimp feed formulations.
Within the integrated conglomerate tier, Charoen Pokphand Foods Public Company Limited and New Hope Liuhe Co., Ltd. exemplify breeding-to-processing control models that secure captive feed offtake. Cargill, Incorporated occupies a position among international traders leveraging global oilseed procurement networks to serve Indonesia's marine cage expansion. These three represent divergent strategic foundations: Thai-Vietnamese pipeline integration, Chinese domestic manufacturing scale, and multinational trading infrastructure.
| Leading Market Players |
|---|
| Charoen Pokphand Foods Public Company Limited |
| New Hope Liuhe Co., Ltd. |
| Cargill, Incorporated |
| Tongwei Co., Ltd. |
| Guangdong Haid Group Co., Ltd. |
| Archer-Daniels-Midland Company |
| Godrej Agrovet Limited |
| East Hope Group |
| Japfa |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Shandong and Jiangsu feed milling corridors is compressing utilization rates below break-even thresholds, forcing suppliers into extended payment terms and volume discounting to maintain offtake while smaller mills absorb margin erosion to preserve market position.
Pricing Analysis
Configured-to-order pricing for antibiotic-free aquafeed formulations commands a 15-25% premium over standard commodity rations, with China's SAMR GB certification tier and Vietnam's EU export-grade specifications serving as the primary differentiation drivers. Cost compression in economy-tier poultry feeds is intensifying because South American soybean logistics volatility forces wheat substitution that degrades amino acid profiles. Dairy cooperatives in India's Gujarat belt exhibit highest price sensitivity due to informal credit dependencies, while Japanese marine cage operators show lowest sensitivity given METI-JIS certification requirements that lock in premium supply relationships.
Supply Chain Analysis
Extended 90-120 day payment terms from Vietnamese aquafeed integrators to South American soybean traders are becoming standard supply-chain finance facilities that shift working capital burdens upstream. Raw material procurement draws from Brazil and Argentina for soybean meal, Australia and Black Sea origins for wheat substitution, and Peru for fish meal anchovy quotas. Single-source vulnerability concentrates in Brazilian port congestion chokepoints that cascade delays through Southeast Asian mill scheduling. Distribution runs through direct mill-to-farm contracts for intensive operations and fragmented rural cooperatives for scattered smallholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic-free mandate enforcement across China and India is disrupting formulation economics and compressing incumbent margins, creating acquisition opportunities for enzyme-probiotic specialists with SAMR and FSSAI pre-approval pathways.
For Market Incumbents: Pre-empt margin compression in commodity poultry feeds by accelerating backward integration into captive enzyme manufacturing in Sichuan corridor facilities, while securing FSSAI registration lock-in across India's dairy cooperative networks before 2024 labeling directives fully phase informal mixers from Gujarat and Punjab procurement channels. For New Entrants and Emerging Players: Marine cage zones in Indonesia's Sulawesi and Sumatra coastal waters represent the most penetrable entry point for extruded floating feed specialists, with direct technical team deployment bypassing Java-based distributor networks and capturing first-mover positioning ahead of domestic mill capacity expansion. For Investors and Strategic Acquirers: Capital is best deployed toward premix-specialist nutrition houses with existing SAMR additive approval pipelines and Vietnamese pond-side technical service infrastructure, as these capabilities compound over a multi-year horizon where formulation chemist scarcity intensifies acquisition premiums; monitor GB standard certification timeline acceleration as the signal for competitive positioning inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Manufacturing | Captures margin pools in phytase and probiotic formulations as SAMR antibiotic-free mandates accelerate adoption across Sichuan poultry belts. |
| FSSAI Registration Pre-Positioning | Locks in dairy cooperative supply relationships before 2024 labeling directives displace informal mixers from Gujarat and Punjab procurement channels. |
| Direct Technical Team Deployment | Bypasses fragmented rural distributors in Vietnam's Mekong Delta to capture FCR-guarantee contracts from super-intensive shrimp pond operators. |
| Extrusion Technology Upgrade | Enables inline fat coating and near-infrared quality control for high-oil shrimp feeds serving Indonesia's expanding marine cage sector. |
| Premix Distribution Innovation | Leverages mobile veterinary networks for micronutrient delivery to scattered dairy cooperative members across Maharashtra and Karnataka. |
Methodological Framework
The analysis maps complete feed, premix, concentrate and additive sub-sectors, each validated through compound feed mill operations directors, aquaculture nutritionists, dairy cooperative procurement managers, and FSSAI regulatory affairs leads. Primary interview insights triangulate against secondary sources including customs trade data for corn and soybean meal flows, SAMR GB standard filings, FSSAI registration databases, and SEC 10-K disclosures from listed feed conglomerates. Bottom-up volume builds from named mill capacities and offtake contracts reconcile with top-down macroeconomic consumption models.
Assumptions held fixed include China's dual carbon policy trajectory, India's FSSAI enforcement intensity, and Indonesian feed self-sufficiency target persistence, while South American soybean logistics volatility and Thai aquafeed export certification pathways were modeled as scenario variables across the projection horizon. Segmentation dimensions span product type tier, end-user species and scale cluster, raw material substitution elasticity, and distribution channel structure. CAGRs derive from trend extrapolation of intensive aquaculture pond conversion rates and poultry integration penetration, with enzyme-probiotic inclusion rate forecasts calibrated to SAMR antibiotic-free compliance timeline acceleration.
Practitioners should monitor South American port congestion persistence, SAMR novel additive approval velocity, and Mekong Delta shrimp disease outbreak frequency for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Algeria Agriculture Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Europe Compound Feed Market