
 South Africa Agriculture Market | 2026-2036
South Africa Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Agriculture Market Insights
Modular input bundles combining seeds, fertilizers, and agronomic advisory services is restructuring how commercial farmers procure production essentials. AFGRI Group leverages its vertically integrated supply chain to dominate grain handling and input distribution across the maize belt. Senwes Ltd anchors its position through extensive storage infrastructure and financing services that lock in grower loyalty. VKB Group competes in the northern Free State by specializing in precision agriculture technologies and localized agronomic support.
South Africa agriculture encompasses crop cultivation, animal husbandry, and allied activities operating across rainfall-dependent and irrigated systems, with maize yields averaging 5–6 tonnes per hectare under optimal conditions and livestock carrying capacity varying by veld type. The sector supplies raw materials to food manufacturers, export terminals, and energy processors while employing roughly 10% of the national workforce. Cereals and livestock occupy the largest revenue share due to deep integration with domestic food security programs and regional trade flows. Fruits command premium export margins through counter-seasonal supply to European and Asian markets. Biofuels represents the fastest-expanding end use industry as policy incentives and blending mandates redirect maize and sugarcane streams toward ethanol production.
The Department of Agriculture, Land Reform and Rural Development sets varietal registration and phytosanitary standards that gate market access for seed suppliers and produce exporters. BIS certification requirements for agricultural equipment and the country's national agricultural regulator enforce safety and quality benchmarks across machinery and chemical inputs. Stakeholders must monitor how land reform policy implementation and water licensing reforms under the National Water Act reshape farm operating economics and investment timelines.
Market Dynamics
Modular input bundles are restructuring procurement across South Africa's commercial farming sector, compressing traditional distributor margins while locking in grower loyalty through integrated financing and advisory services. This shift favors vertically integrated suppliers with captive storage infrastructure and credit capabilities.
Growth Catalysts
- Biofuel blending mandates:Policy incentives redirecting maize and sugarcane streams toward ethanol production are creating dedicated offtake agreements that stabilize farmer revenue predictability.
- Counter-seasonal export windows:Western Cape horticultural clusters supply European and Asian markets during Northern Hemisphere off-seasons, commanding premium pricing for pome and stone fruits.
- Precision agriculture adoption:Variable-rate application technologies and drone-enabled crop monitoring are lifting yields in the northern Free State maize belt beyond rain-fed baselines.
Market Restraints
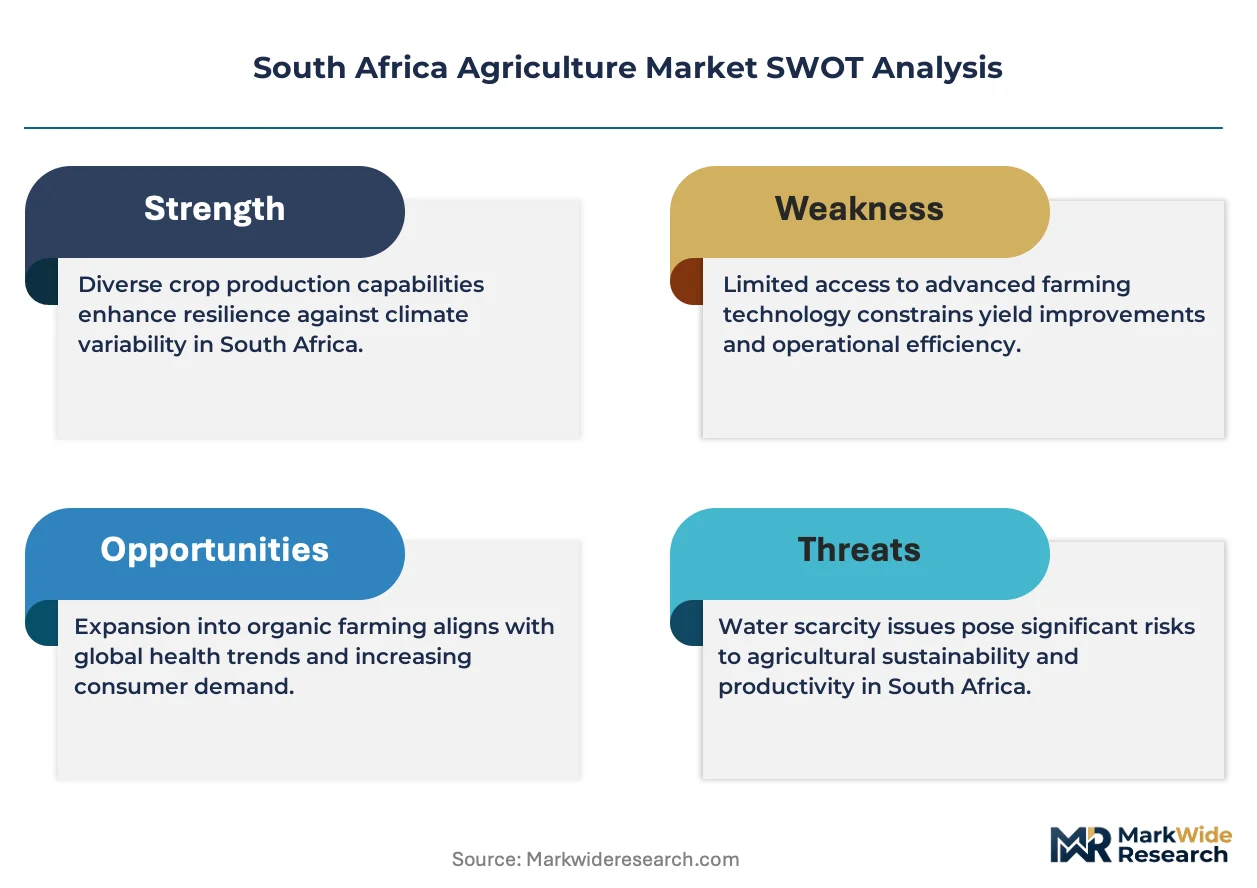
- Fertilizer import dependency:South Africa sources the majority of nitrogen and phosphate inputs through Durban and Richards Bay terminals, exposing farm budgets to currency volatility and shipping disruptions.
- Water licensing bottlenecks:The National Water Act's abstraction permitting process creates multi-year delays for expansion irrigation projects in Limpopo and Mpumalanga.
- Land tenure uncertainty:Ongoing land reform policy implementation extends investment timelines and complicates collateralization for medium-scale commercial operators.
Strategic Opportunities
- Eastern Cape underpenetration:The former Transkei region holds extensive underutilized arable land with emerging road and cold-chain infrastructure unlocking access to export corridors.
- Carbon credit monetization:Soil carbon sequestration protocols and verified emission reduction methodologies are creating supplemental revenue streams for conservation-minded livestock producers.
- Digital input marketplaces:Mobile-first platforms connecting farmers directly with seed and chemical manufacturers are disintermediating traditional cooperative distribution layers.
Industry Challenges
- Agronomic advisory scarcity:South Africa faces a shortage of certified crop advisors capable of interpreting satellite imagery and prescribing variable-rate input prescriptions at commercial scale.
- Equipment financing compression:Tractor and harvester procurement requires substantial capital outlays that strain balance sheets amid rising interest rate environments and compressed commodity cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Agriculture Market |
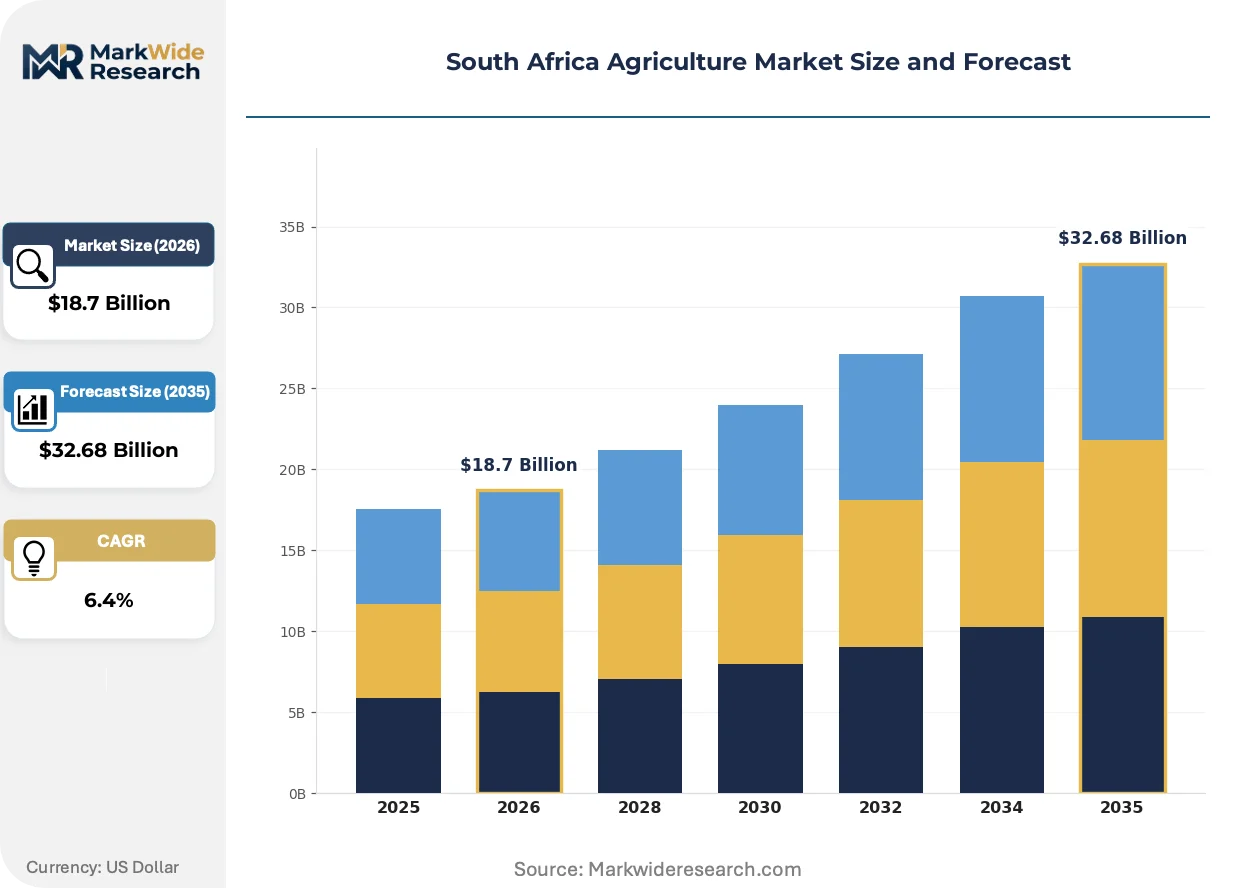
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Vegetables, Fruits, Livestock End Use Industry: Food Processing, Animal Feed, Export, Biofuels Packaging Type: Bags, Bottles, Cans, Bulk Containers Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | AFGRI Group, Senwes Ltd, VKB Group, NWK Limited, Tiger Brands, Pioneer Foods Group, Tongaat Hulett, Astral Foods, Illovo Sugar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Agriculture Market Trends and Innovations
Digital agriculture platforms and biotechnology protocols are converging to reshape how South African farmers manage risk, optimize input application, and access export certification. These shifts are compressing traditional advisory and distribution intermediaries while elevating data-centric service providers.
Drone-enabled multispectral imaging is absorbing tasks previously performed by ground-based scouts and extension officers. Large-scale grain operations in the Free State and North West provinces are deploying fixed-wing and quadcopter systems at accelerating rates. This technology is absorbing margin from traditional crop insurance products by enabling real-time damage assessment and parametric claim triggers.
The Department of Agriculture, Land Reform and Rural Development's evolving biotechnology protocols are tightening varietal registration timelines for genetically modified seed traits. Seed suppliers must now navigate stacked approval requirements for insect resistance and herbicide tolerance traits before commercial release. The maize seed segment is responding by consolidating trial data packages and accelerating local adaptation breeding programs.
Food processors and export traders are consolidating procurement through long-term offtake agreements that bundle quality certification with volume commitments. This pattern displaces spot-market transactions that previously dominated the wine and deciduous fruit sectors. The Western Cape's integrated packhouse-to-port infrastructure makes this consolidation most visible in table grape and citrus value chains.
South Africa Agriculture Market Segmentation
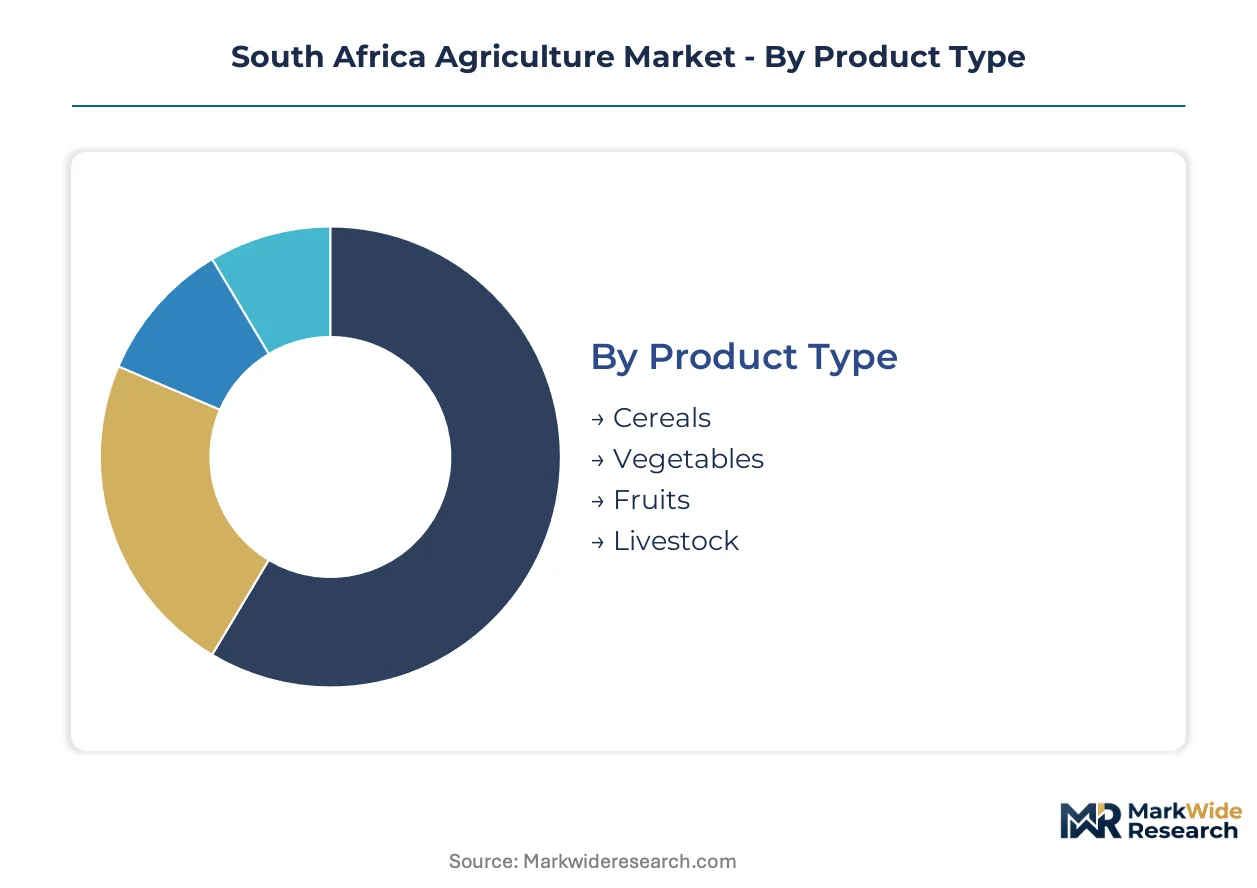
Segmentation reveals how South African agricultural output flows through distinct commercial pathways. Each dimension exposes pressure points in procurement, processing, and final delivery.
Product Type:
Replacement cycles for planting stock and breeding herds drive reinvestment timing across South Africa's commercial farming sector.
- Cereals:Maize, wheat, and sorghum dominate planted hectares across the Free State and North West provinces. Procurement concentrates around AFGRI Group and Senwes Ltd storage networks that handle the majority of the maize belt harvest.
- Livestock:Cattle, sheep, and poultry operations integrate with feedlot systems and abattoir chains. The sector's expansion is accelerating most quickly in Mpumalanga's emerging commercial feedlot clusters.
- Fruits:Pome, stone, and citrus varieties from Western Cape horticultural clusters supply counter-seasonal export windows to European markets.
- Vegetables:Potato, onion, and tomato production serves domestic fresh markets and limited processing contracts.
Volume placements concentrate in Cereals; the faster expansion belongs to Livestock.
End Use Industry:
Application-specific quality standards reshape how farmers manage harvest timing and post-harvest handling protocols.
- Food Processing:Milling, canning, and beverage manufacturing demand consistent grade specifications that contract farming arrangements increasingly guarantee. The segment's expansion is accelerating most quickly as manufacturers secure dedicated supply chains.
- Biofuels:Ethanol distilleries and biodiesel plants redirect maize and sugarcane streams under blending mandate compliance. Demand concentrates in KwaZulu-Natal's sugarcane belt and Mpumalanga's emerging ethanol facilities.
- Animal Feed:Compound feed manufacturers procure coarse grains and oilseed meals for poultry and pork production systems.
- Export:Phytosanitary certification requirements from the Department of Agriculture, Land Reform and Rural Development gate access to European and Asian markets.
Procurement volumes concentrate in Food Processing; the steepest expansion trajectory sits with Biofuels.
Packaging Type:
Cost tier differentiation separates commodity bulk handling from premium retail-ready presentation.
- Bulk Containers:Intermodal tanks and flexitanks move grain, oilseeds, and liquid products through Durban and Richards Bay export terminals. The segment commands the largest volume share across commercial grain operations.
- Bags:Woven polypropylene and paper sacks serve domestic milling and informal retail channels. Demand concentrates in Limpopo and Eastern Cape smallholder supply chains.
- Bottles:Glass and PET containers package wine, fruit juices, and specialty oils for retail distribution.
- Cans:Metal packaging preserves processed vegetables and meat products for shelf-stable distribution.
Volume concentrates in Bulk Containers; premium margin capture belongs to Bottles.
Distribution Channel:
Customer type stratification separates large-scale commercial procurement from fragmented smallholder access.
- Wholesale:Cooperative aggregators and grain traders consolidate harvests from multiple growers for onward sale to processors and exporters. VKB Group and AFGRI Group dominate this layer through captive storage infrastructure.
- Direct Sales:Long-term offtake agreements between farm operations and food processors eliminate intermediary margins. The Western Cape's integrated packhouse systems favor this channel for table grape and citrus exports.
- Retail:Supermarket chains and independent grocers source fresh produce through centralized procurement hubs.
- Online:Digital platforms connecting farmers with input suppliers and produce buyers are disintermediating traditional cooperative layers.
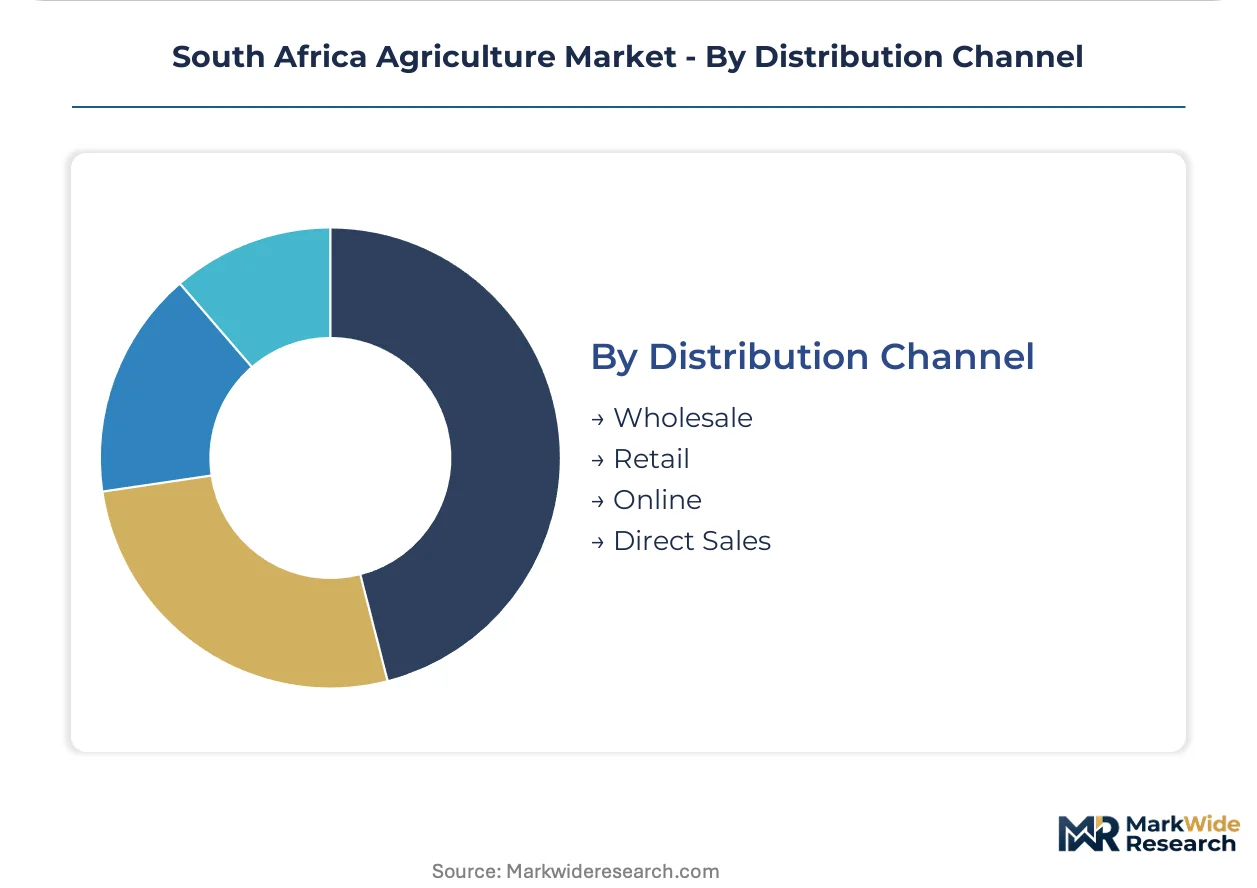
Transaction volume concentrates in Wholesale; channel innovation and growth momentum sit with Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's agricultural production concentrates in provinces that outpace domestic consumption, creating exportable surpluses in grains and horticulture while import dependency persists in wheat and rice. The Western Cape and Free State anchor commercial output, with sub-regional specialization deepening across the country's nine provinces.
Western Cape
Pome and stone fruit orchards supply counter-seasonal European markets through Cape Town's integrated cold-chain infrastructure. The Department of Agriculture, Land Reform and Rural Development enforces phytosanitary certification that gates access to EU trade corridors. Stellenbosch and Paarl wine clusters dominate premium export volumes while expanding table grape packhouses redirect harvests toward Asian destinations.
Free State
Maize and soybean cultivation covers the bulk of commercial hectares across this central province, feeding domestic milling and emerging biofuel processors. Water licensing reforms under the National Water Act constrain irrigation expansion in the eastern districts. Senwes Ltd and AFGRI Group storage networks consolidate harvests from Bloemfontein and surrounding districts for onward distribution to industrial buyers.
KwaZulu-Natal
Sugarcane estates supply Illovo Sugar mills and emerging ethanol distilleries under national blending mandate compliance. The province's subtropical climate supports banana and macadamia orchards targeting export markets. Durban's port infrastructure handles fertilizer imports that feed nitrogen-dependent crop systems across the coastal belt.
Limpopo
Avocado and mango production expands across the Levubu and Tzaneen valleys, capitalizing on northern hemisphere off-season demand windows. Groundwater abstraction permitting creates multi-year delays for orchard establishment under Department of Water and Sanitation oversight. Musina and Polokwane logistics corridors connect ripening facilities to Johannesburg export airfreight terminals.
Eastern Cape
The former Transkei region holds extensive underutilized arable land with emerging road infrastructure unlocking access to export corridors. Citrus and pineapple cultivation spreads across the Sundays River Valley with irrigation dependent on Algoa Bay desalination feasibility studies. East London's port expansion plans target dedicated reefer vessel handling for deciduous fruit shipments.
South Africa Agriculture Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Africa's agricultural value chain, creating tiered competition between integrated agribusiness groups and regional cooperatives. Storage infrastructure and captive financing capabilities separate dominant players from commodity traders. Three archetypes define competitive positioning: vertically integrated input-to-export conglomerates, regional cooperative aggregators with storage networks, and specialized precision agriculture technology providers. Capacity expansion in grain handling terminals and strategic partnerships with biofuel processors represent the dominant competitive moves reshaping procurement relationships.
Among storage-centric conglomerates, AFGRI Group and Senwes Ltd exemplify the vertically integrated archetype through grain handling dominance across the maize belt. VKB Group occupies a position within the precision agriculture specialist tier, anchoring competitive dynamics in the northern Free State through localized agronomic support capabilities. These three entities represent the structural concentration that defines input distribution and harvest consolidation across South Africa's commercial farming sector.
| Leading Market Players |
|---|
| AFGRI Group |
| Senwes Ltd |
| VKB Group |
| NWK Limited |
| Tiger Brands |
| Pioneer Foods Group |
| Tongaat Hulett |
| Astral Foods |
| Illovo Sugar |
| Others |
Pricing and Supply Chain Analysis
The South Africa Yellow Maize Spot Price serves as the dominant benchmark cascading through grain procurement tiers, compressing margins for distributors while amplifying price volatility exposure for rain-fed operators across the Free State and North West provinces.
Pricing Analysis
Margin tightening in input bundles reflects currency-driven fertilizer cost spikes and consolidated distributor leverage. Three-tier pricing structure across premium certified seed, standard commercial varieties, and economy open-pollinated cultivars stratifies farmer segments. Pricing pressure intensifies in the standard tier as VKB Group and AFGRI Group bundle advisory services to defend retention. Smallholder cooperatives in Limpopo and Eastern Cape exhibit highest price sensitivity due to constrained credit access.
Supply Chain Analysis
Single-source vulnerability sits with nitrogen fertilizer flows through Richards Bay terminals where Russian and Chinese suppliers dominate import volumes. Raw material dependencies span phosphate rock from Morocco, potash from Belarus, and ammonia from Trinidad. Supply chain risk centers on currency volatility amplifying landed cost unpredictability. Distribution runs through cooperative storage networks that consolidate harvests before onward sale to processors and export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's agriculture market operates as a supply-constrained system where water licensing bottlenecks and land tenure uncertainty prop input pricing power for integrated incumbents with captive storage infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into precision agriculture advisory capabilities that lock in grower loyalty. Expand storage capacity in the Eastern Cape's emerging corridors before infrastructure maturation erodes first-mover advantage. Digital input marketplaces threaten traditional cooperative distribution layers and demand preemptive platform investment.
For New Entrants and Emerging Players: Begin with carbon credit aggregation services targeting conservation-minded livestock producers in Mpumalanga's expanding feedlot clusters. The Eastern Cape's underpenetrated former Transkei region offers white-space access through mobile-first input marketplaces that bypass incumbent cooperative networks. Direct manufacturer-to-farmer platforms disintermediate legacy distribution margins.
For Investors and Strategic Acquirers: The window for entry favors precision agriculture technology providers with localized agronomic support capabilities and drone-enabled crop monitoring infrastructure. Acquisition targets should exhibit captive farmer relationships through embedded financing and storage access. Watch biofuel blending mandate acceleration as the signal indicating ethanol processor offtake agreement premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Deployment | Drone-enabled multispectral imaging absorbs traditional crop insurance and scouting functions across Free State grain operations. |
| Storage Infrastructure Expansion | Captive silo networks in Eastern Cape unlock access to underutilized arable land before road and cold-chain maturation. |
| Carbon Credit Protocol Development | Verified soil sequestration methodologies create supplemental revenue streams for livestock producers under emerging compliance frameworks. |
| Digital Input Marketplace Launch | Mobile-first platforms connecting farmers directly with seed manufacturers disintermediate traditional cooperative distribution layers. |
| Biofuel Processor Partnership | Long-term offtake agreements with ethanol facilities stabilize maize revenue predictability under national blending mandates. |
Research Methodology
Document review covered trade flow databases, agricultural census records, and regulatory filings from the Department of Agriculture, Land Reform and Rural Development, complemented by interviews with grain storage cooperative managers, input distributors, commercial farm operators, and biofuel processor procurement leads. Secondary validation drew from customs export data, National Water Act licensing records, and seed certification registries. Bottom-up farmer survey data triangulated against top-down production statistics.
Market size outputs reflect demand-side aggregation across cereals, livestock, fruits, and vegetables segments, with end-use splits modeled for food processing, biofuels, animal feed, and export channels. CAGRs derived from historical production trends, input cost trajectories, and policy incentive elasticity. Forecast inputs incorporated rainfall variability patterns, biotechnology adoption curves, and ethanol blending mandate compliance timelines.
Underlying measurement precision varies by segment; commercial grain and horticultural export data carry tighter precision than smallholder vegetable production estimates. Forecasts reflect assumptions around water licensing reform pace, land reform policy implementation, and currency stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Netherlands Cashew Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market