
 Italy Animal Protein Market | 2026-2036
Italy Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Animal Protein Market Foresight
Plant-based protein isolates are expanding their presence in Italian processed meat formulations, pressuring traditional animal protein economics across mid-tier retail tiers. Groupe Lactalis leverages its dairy-protein extraction infrastructure to compete in adjacent animal-derived ingredient markets. FrieslandCampina Ingredients anchors premium nutritional applications with specialized whey and casein fractions. Roquette Frères differentiates through plant-animal hybrid formulations that occupy reformulation pipelines at major Italian food manufacturers.
Animal protein encompasses the edible tissue, collagen, and derived fractions from slaughtered livestock and aquaculture species, typically requiring controlled temperature chains below four degrees Celsius to preserve functional and nutritional integrity. These proteins serve as essential amino acid sources for human nutrition and as functional binders in emulsified food systems. Poultry leads volume throughput in Italian processing plants due to shorter production cycles and favorable feed conversion ratios. Fish commands premium positioning in northern retail corridors where per-capita seafood consumption exceeds national averages. Beef sustains margin concentration in specialty channels and protected designation of origin supply chains despite declining household frequency.
Italy's Ministry of Health enforces slaughter hygiene standards under EU Regulation 853/2004, while the Istituto Superiore di Sanità monitors zoonotic risk pathways that shape farm-to-fork traceability investments. The EU Green Deal's Farm to Fork Strategy forces Italian processors to document carbon intensity per kilogram of carcass weight, redirecting capital toward methane-reduction technologies and manure-management infrastructure. Stakeholders must monitor how delegated acts under the EU Deforestation Regulation reshape feed-origin verification requirements for imported soy and palm derivatives.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is redirecting Italian capital toward methane-reduction infrastructure, compressing margins for conventional feedlot operators while advantaging pasture-based systems with documented carbon intensity.
Growth Catalysts
- PNRR Livestock Incentives:Italy's National Recovery and Resilience Plan channels public funds toward lower-emission production systems, accelerating barn retrofits and manure-management upgrades.
- Premium Poultry Procurement:Food service operators across Lombardy and Veneto are expanding contracts for specialized cuts, pulling volume toward northern processing clusters.
- Cold-Chain Density:Refrigerated logistics networks between Milan and Verona enable same-day fresh distribution, locking in quality premiums for regional processors.
Market Restraints
- Feed Input Volatility:Soy and palm derivative imports face escalating verification costs under the EU Deforestation Regulation, squeezing compound feed economics.
- Slaughter Capacity Concentration:Northern Italy hosts disproportionate processing infrastructure, forcing southern producers into costly live animal transport.
- Plant Protein Substitution:Pea and fava bean isolates are capturing formulation share in mid-tier retail sausages, eroding volume for conventional pork trim.
Strategic Opportunities
- Sicilian Aquaculture Expansion:Underdeveloped marine finfish production off the southern coast offers untapped capacity for sea bream and sea bass cultivation.
- Hybrid Protein Formulations:Blended plant-animal products occupy reformulation pipelines at major Italian manufacturers, opening new SKU territory.
- Protected Designation Channels:Chianina and Maremmana beef denominations command sustained margin concentration in specialty retail despite household frequency decline.
Industry Challenges
- Veterinary Specialization Shortage:Farm-to-fork traceability investments under EU Regulation 853/2004 require qualified personnel that rural provinces struggle to retain.
- Legacy System Integration:Methane-capture hardware must interface with decades-old barn ventilation infrastructure, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Animal Protein Market |
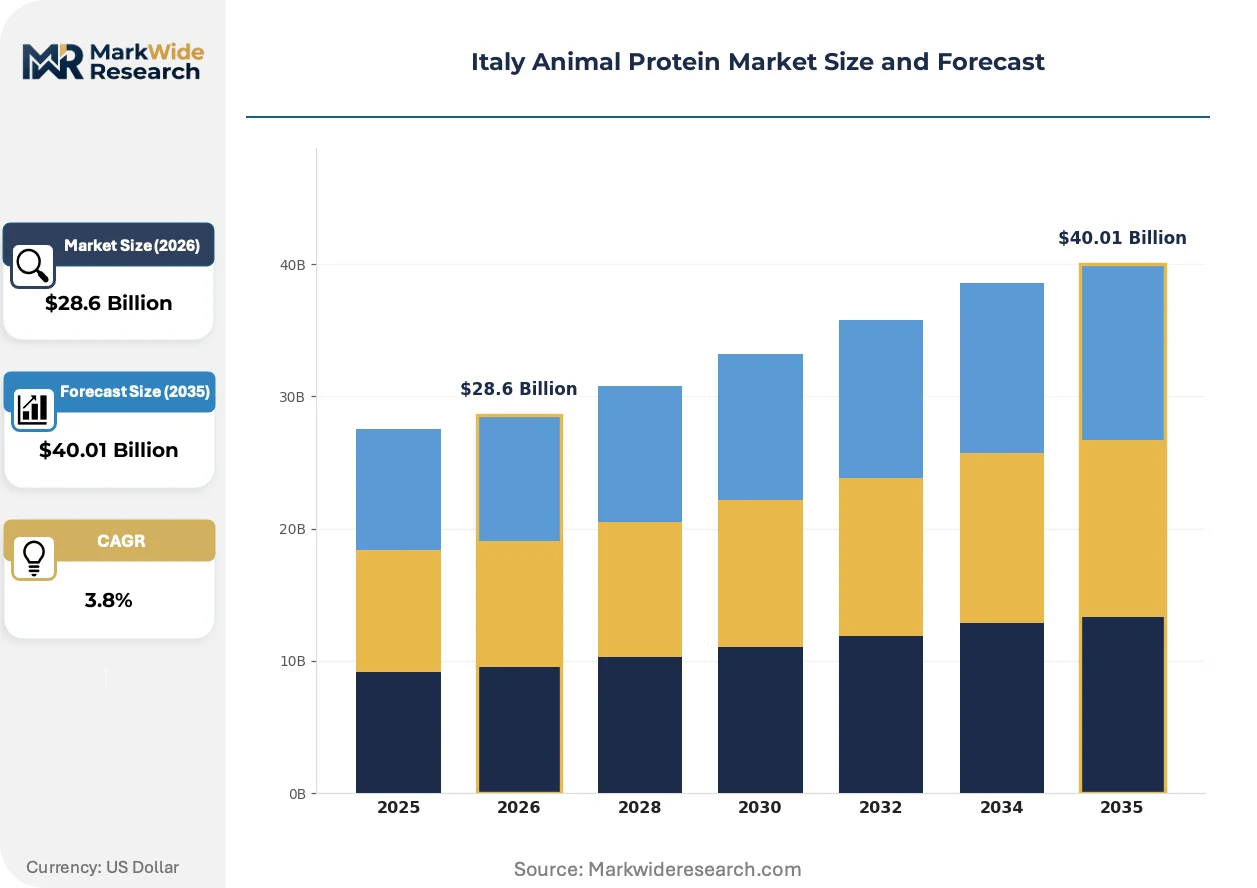
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Fish End User: Households, Restaurants, Food Services, Retailers Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale Packaging Type: Bulk, Vacuum Pack, Tray Pack, Cans |
| Companies Covered | Agrial Group, Arla Foods amba, Darling Ingredients Inc., Fonterra Co-operative Group Limited, Lactoprot Deutschland GmbH, Groupe Lactalis, FrieslandCampina Ingredients, Roquette Frères, Archer-Daniels-Midland Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Animal Protein Market Shifts & Advancements
Italian animal protein production is fragmenting along sustainability-verification lines, with technology and procurement models diverging between premium traceable supply and commodity channels.
Precision fermentation for dairy-derived functional proteins is modularizing ingredient supply chains. Nutraceutical formulators in Bologna and Parma are adopting these inputs to reduce batch-to-batch variability. The technology is compressing lead times for specialized whey fractions that previously required dedicated cheese-making partnerships.
Delegated acts under the EU Deforestation Regulation are reshaping feed-origin documentation requirements. Italian compounders must now verify geolocation data for soy suppliers back to the plot level. Poultry integrators with Brazilian supply exposure face the steepest compliance ramps and are accelerating alternative protein source trials.
Contract structures between processors and food service buyers are shortening from annual to quarterly terms. Lombardy-based distributors are unbundling volume commitments from price locks, transferring margin risk upstream. This pattern concentrates most visibly in the premium poultry segment where spot-market liquidity supports rapid repricing.
Italy Animal Protein Market Segmentation
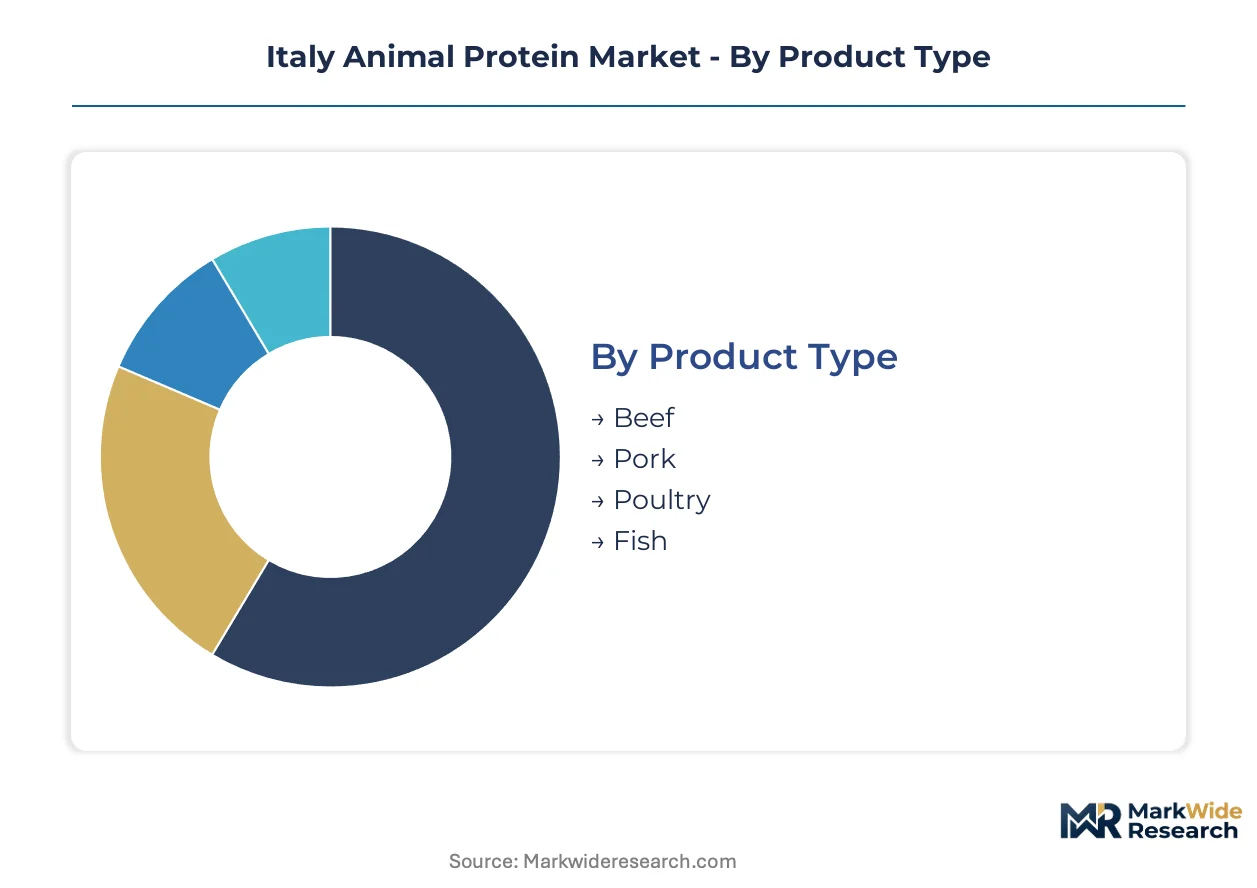
Italian animal protein procurement splits sharply between standardized commodity flows and customized premium channels. Cold-chain density in the north enables fresh distribution models that reshape how each segment captures value.
Product Type:
Customization spans from commodity carcass cuts to breed-specific denominations with documented provenance and carbon intensity.
- Poultry:Shorter production cycles and favorable feed conversion ratios concentrate volume throughput in Lombardy and Veneto processing plants. Food service operators across these regions are expanding procurement contracts for specialized cuts, pulling fresh distribution toward northern cold-chain corridors.
- Fish:Marine finfish commands premium positioning in northern retail corridors where per-capita seafood consumption exceeds national averages. Sicilian aquaculture expansion offers untapped capacity for sea bream and sea bass cultivation off the southern coast.
- Beef:Chianina and Maremmana denominations sustain margin concentration in specialty retail despite declining household frequency.
- Pork:Conventional trim faces volume pressure from plant protein substitution in mid-tier retail sausage formulations.
Most installed capacity flows through Poultry. Expansion is steepest in Fish.
End User:
Cost tiers separate mass-market household procurement from premium food service contracts with quarterly repricing terms.
- Restaurants:Lombardy-based distributors are unbundling volume commitments from price locks, transferring margin risk upstream to processors. Spot-market liquidity in premium poultry segments supports rapid repricing cycles.
- Food Services:Contract structures are shortening from annual to quarterly terms, concentrating most visibly in specialized cut procurement across the Milan-Verona industrial corridor.
- Households:Frequency decline in beef purchases compresses volume in conventional retail channels.
- Retailers:Mid-tier supermarkets face formulation pressure from plant-animal hybrid products occupying reformulation pipelines.
Volume concentrates in Food Services. Margin capture is climbing fastest in Restaurants.
Distribution Channel:
Supply concentration in northern infrastructure forces southern producers into costly live animal transport or refrigerated logistics investments.
- Supermarkets:Refrigerated logistics networks between Milan and Verona enable same-day fresh distribution, locking in quality premiums for regional processors serving these retail chains.
- Wholesale:Northern Italy hosts disproportionate processing infrastructure, creating dependency relationships with southern production zones.
- Specialty Stores:Protected designation of origin supply chains anchor margin concentration for Chianina and Maremmana beef denominations.
- Online:Cold-chain integrity requirements limit penetration for fresh products outside dense urban corridors.
Throughput dominance sits with Supermarkets. Channel development is accelerating in Online.
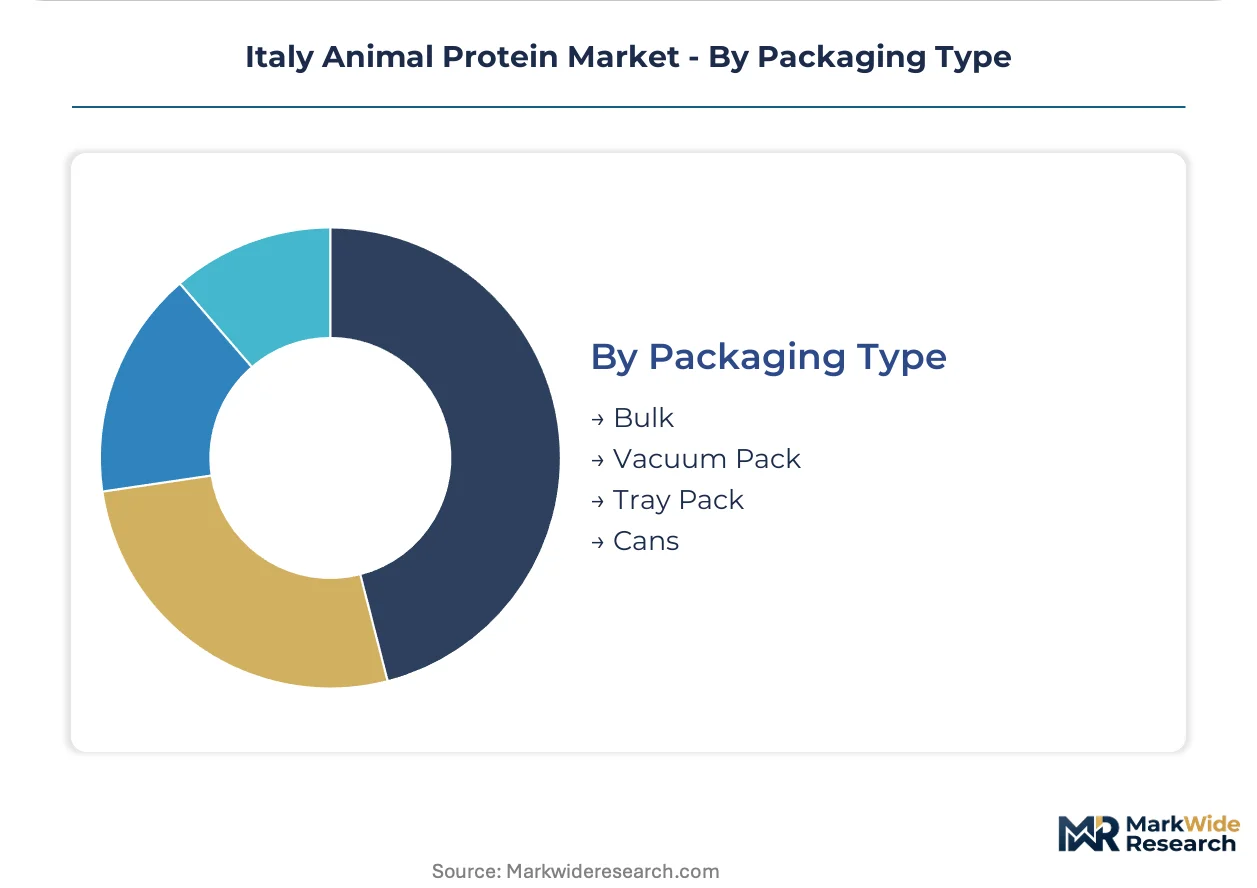
Packaging Type:
Maturity gradients separate legacy bulk formats from precision packaging that extends shelf life and enables premium positioning.
- Vacuum Pack:Controlled atmosphere technology preserves functional and nutritional integrity below four degrees Celsius, supporting extended distribution radii from northern processing clusters.
- Tray Pack:Modified atmosphere configurations dominate fresh retail presentation in Lombardy and Veneto supermarkets.
- Bulk:Food service and wholesale channels rely on commodity formats with minimal processing overhead.
- Cans:Shelf-stable formats capture residual demand in southern provinces with lower cold-chain penetration.
Processing volume flows primarily through Vacuum Pack. Format innovation is advancing most quickly in Tray Pack.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Milan-Verona industrial corridor anchors Italian animal protein processing capacity, concentrating cold-chain infrastructure and premium food service procurement in the northern industrial belt.
Lombardy
Food service operators across Lombardy are expanding contracts for specialized poultry cuts, pulling fresh distribution toward regional processing clusters. The National Recovery and Resilience Plan channels public funds toward barn retrofits and manure-management upgrades in the province. Milan-based distributors are unbundling volume commitments from price locks, transferring margin risk upstream to processors serving the metropolitan market.
Veneto
Per-capita seafood consumption in Veneto exceeds national averages, commanding premium positioning for marine finfish in retail corridors. The EU Green Deal's Farm to Fork Strategy forces processors to document carbon intensity per kilogram of carcass weight, redirecting capital toward methane-reduction technologies. Verona anchors refrigerated logistics networks that enable same-day fresh distribution to supermarkets across the industrial corridor.
Emilia-Romagna
Nutraceutical formulators in Bologna and Parma are adopting precision fermentation inputs to reduce batch-to-batch variability in specialized whey fractions. The Istituto Superiore di Sanità monitors zoonotic risk pathways that shape farm-to-fork traceability investments across the region. Processing facilities in Parma concentrate dairy-protein extraction infrastructure competing in adjacent animal-derived ingredient markets.
Sicily
Underdeveloped marine finfish production off the southern coast offers untapped capacity for sea bream and sea bass cultivation. Southern producers face costly live animal transport or refrigerated logistics investments due to disproportionate northern processing infrastructure. Delegated acts under the EU Deforestation Regulation reshape feed-origin verification requirements for imported soy derivatives affecting regional compounders.
Tuscany
Chianina beef denominations sustain margin concentration in specialty retail channels despite declining household frequency. Protected designation of origin supply chains anchor premium positioning for Maremmana beef in regional markets. Veterinary specialization shortages in rural provinces complicate farm-to-fork traceability investments required under EU Regulation 853/2004.
Italy Animal Protein Market Competitive Landscape
Portfolio diversification dominates the current landscape as processors reposition around sustainability-verification lines and hybrid protein formulations. The vendor base splits between consolidated dairy-derived ingredient specialists and fragmented meat processors adapting to plant-animal hybrid competition. Three archetypes occupy distinct positions: dairy-protein extractors leveraging existing infrastructure, precision fermentation technology adopters, and traditional processors defending specialty denomination channels. M&A activity and methane-reduction technology licensing represent the dominant competitive moves reshaping capital allocation.
Among dairy-derived ingredient specialists, Groupe Lactalis, FrieslandCampina Ingredients, and Fonterra Co-operative Group Limited exemplify the infrastructure-leverage archetype. Groupe Lactalis occupies a position within the dairy-protein extraction tier competing in adjacent animal-derived markets. FrieslandCampina Ingredients anchors premium nutritional applications through specialized whey and casein fraction capabilities. Fonterra represents the cooperative-structured model within dairy-protein supply. Roquette Frères sits within the plant-animal hybrid formulation space, occupying reformulation pipelines at major Italian manufacturers. These five entities collectively illustrate how protein sourcing capabilities are fragmenting along sustainability-verification and technology-adoption lines.
| Leading Market Players |
|---|
| Agrial Group |
| Arla Foods amba |
| Darling Ingredients Inc. |
| Fonterra Co-operative Group Limited |
| Lactoprot Deutschland GmbH |
| Groupe Lactalis |
| FrieslandCampina Ingredients |
| Roquette Frères |
| Archer-Daniels-Midland Co |
| Others |
Supply & Pricing Matrix
Captive cold-chain infrastructure between Milan and Verona anchors both supply positioning and pricing power for northern Italian processors serving premium food service channels. This vertical integration into refrigerated distribution networks enables same-day fresh delivery that locks in quality premiums and insulates specialized poultry and seafood cuts from commodity price cycles.
Pricing Analysis
Input-cost pass-through from Brazilian soy and palm derivative imports under the EU Deforestation Regulation is compressing compound feed economics and squeezing mid-tier pork trim margins. Three-tier pricing structure across premium PDO beef, standard fresh poultry, and economy frozen pork reflects quality grade and certification level differentiation. Pricing pressure stems from plant protein substitution in mid-tier retail sausages, with household beef purchasers showing highest price sensitivity and Lombardy food service operators demonstrating lowest sensitivity due to quarterly contract repricing flexibility.
Supply Chain Analysis
Regional distribution centers in Milan and Verona operate hub-and-spoke patterns that concentrate processing infrastructure in northern Italy while forcing southern producers into costly live animal transport. The supply chain draws from Brazilian soy imports, domestic corn production, and Mediterranean fishmeal sources. Single-source vulnerability sits with Brazilian feed ingredient exposure under tightening geolocation verification requirements. Distribution runs through cold-chain-dependent supermarket networks with residual wholesale bulk flows to food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's animal protein market functions as a stable compounder anchored by irreplaceable PDO denomination premiums and persistent northern food service demand density.
For Market Incumbents: Hedge against plant protein displacement by accelerating hybrid formulation R&D partnerships with major Italian manufacturers. Secure backward integration into Sicilian aquaculture capacity before marine finfish expansion attracts capital inflows. Defensive certification investment in EU Green Deal methane-reduction documentation preserves premium channel access against regulatory exclusion.
For New Entrants and Emerging Players: Capture underdeveloped southern processing capacity through refrigerated logistics investments that bypass northern infrastructure bottlenecks. Target Sicilian sea bream and sea bass cultivation where marine finfish production remains nascent against Veneto consumption premiums. Deploy precision fermentation technology partnerships with Bologna nutraceutical formulators as the fastest go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where veterinary specialization shortages complicate EU Regulation 853/2004 compliance investments across rural provinces. Long-term viability favors processors with documented carbon intensity systems and PDO supply chain control. Watch delegated act implementation timelines under the EU Deforestation Regulation as the inflection signal for feed cost restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Production | Reduces Brazilian soy exposure under tightening EU Deforestation Regulation verification requirements. |
| Hybrid Protein Formulation Development | Occupies reformulation pipelines at major Italian manufacturers facing plant substitution pressure. |
| Sicilian Aquaculture Capacity Buildout | Captures untapped marine finfish production capacity off Italy's southern coast. |
| Methane-Capture Technology Licensing | Enables EU Green Deal compliance for pasture-based systems with documented carbon intensity. |
| PDO Supply Chain Certification Investment | Preserves margin concentration in Chianina and Maremmana beef specialty retail channels. |
Research Methodology
Bottom-up food service procurement modeling reconciled against top-down processing capacity tracking forms the analytical core of this study. Primary interviews with poultry integrator procurement directors, compound feed formulators, cold-chain logistics operators, and restaurant group purchasing managers combined with secondary validation from EU customs trade data, Istituto Superiore di Sanità zoonotic risk reports, and PNRR livestock incentive disclosures. Triangulation between slaughter volume statistics and food service contract flow data ensures segmentation integrity.
Input-output matrix framing connects feed ingredient cost structures through processing yields to end-user price realizations across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, distribution format, and regional cold-chain density. CAGRs derive from compound growth trajectory analysis applied to verified baseline volumes. Industry-specific forecast inputs incorporate EU Deforestation Regulation compliance cost curves and PNRR methane-reduction technology adoption rates.
Regulatory implementation delays, feed commodity price volatility, and veterinary labor supply constraints are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumption sets regarding policy enforcement timelines and technology deployment rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
India Agriculture Market