
 Saudi Arabia Agriculture Market | 2026-2036
Saudi Arabia Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Agriculture Market Insights
Organic certification under SFDA and SASO standards is rotating market access toward producers with verified sustainable practices. Almarai Company leverages integrated dairy and fodder operations across the Kingdom's central belt. NADEC anchors large-scale wheat and dairy production through state-supported land allocations. ARASCO specializes in animal feed manufacturing, sustaining supply security for the poultry and livestock segments.
Saudi Arabia agriculture encompasses crop cultivation, livestock husbandry, aquaculture, and horticulture adapted to arid-zone constraints through desalination-dependent irrigation and climate-controlled greenhouse systems. Its primary purpose centers on reducing food import dependency while supplying raw materials to domestic food processing and retail channels. Crops and livestock occupy the dominant value share, though aquaculture gains traction as Red Sea fish farming expands. Hydroponics and precision agriculture represent the fastest-growing technology segments, driven by water scarcity and labor optimization imperatives.
SFDA enforces food safety and labeling standards that dictate pesticide residue limits and packaging requirements for domestic sale, while SASO technical regulations govern imported agricultural equipment and inputs. The Saudi Green Initiative and related environmental compliance frameworks shape water allocation and carbon accounting for large producers. Stakeholders must monitor evolving subsidy structures and water tariff reforms that could alter cost competitiveness across production regions.
Market Dynamics
SFDA food safety mandates and drip irrigation technology diffusion are tightening compliance requirements for new entrants while concentrating procurement power among integrated domestic processors.
Growth Catalysts
- Saudi Green Initiative procurement mandates:Domestic food processors must expand local sourcing quotas, redirecting supply contracts toward certified Saudi producers.
- Desalination infrastructure expansion:New reverse osmosis plants in the Eastern Province are unlocking previously barren land for commercial cultivation.
- Qassim dairy cluster economies:Concentrated feed milling and veterinary services in this central region reduce logistics costs for livestock operators.
Market Restraints
- Water tariff volatility:Subsidy reforms under the National Water Strategy threaten operating cost predictability for open-field irrigation operators.
- Imported equipment dependency:SASO technical regulations on foreign agricultural machinery create certification delays and supplier concentration risk.
- Phosphorus fertilizer price swings:Global phosphate rock supply disruptions transmit directly into Saudi input costs given limited domestic mining capacity.
Strategic Opportunities
- Red Sea aquaculture zones:Untapped coastal waters near Jazan offer brackish-water farming potential for high-value marine species.
- Hydroponics-vertical farming convergence:Climate-controlled greenhouse operators can stack production layers to overcome land scarcity constraints.
- Carbon credit monetization:Saudi Green Initiative frameworks may soon reward verified soil carbon sequestration from sustainable tillage practices.
Industry Challenges
- Agritech engineering talent scarcity:Precision agriculture deployment outpaces local university pipeline output for irrigation systems specialists.
- SFDA organic certification timelines:Multi-year transition periods and residue testing backlogs delay market access for conventional-to-organic converters.
- Legacy flood irrigation asset stranding:Existing infrastructure investments resist rapid drip system retrofitting despite water policy pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Agriculture Market |
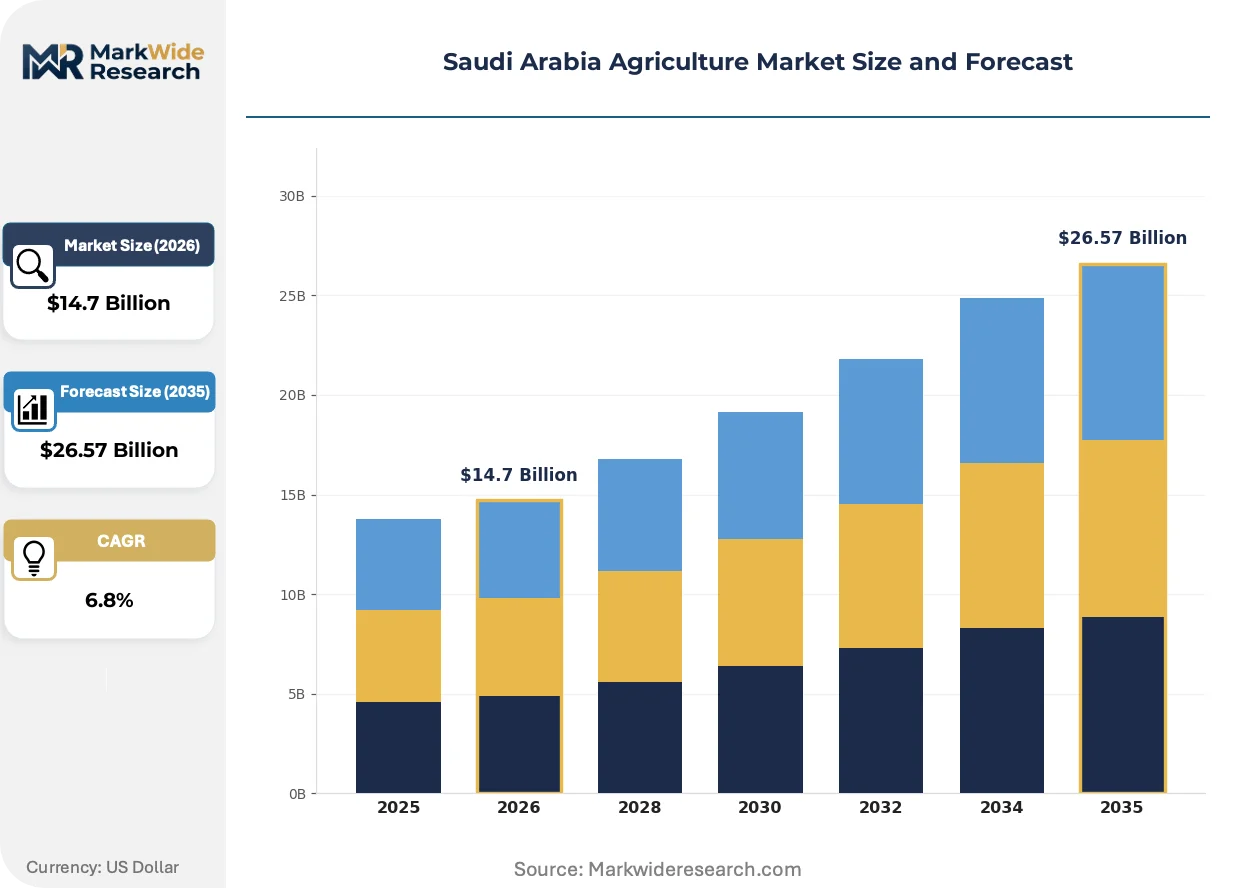
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crops, Livestock, Aquaculture, Horticulture End Use Industry: Food Processing, Export, Retail, Biofuels Distribution Channel: Direct Sales, Wholesale, Online, Cooperatives Technology: Hydroponics, Drip Irrigation, Precision Agriculture, Organic Farming |
| Companies Covered | Almarai Company, National Agricultural Development Company (NADEC), Savola Group, Tabuk Agricultural Development Company, Al-Jouf Agricultural Development Company, Arabian Agricultural Services Company (ARASCO), Saudi Agricultural and Livestock Investment Company (SALIC), Al-Othaim Holding Company, Al-Safi Danone, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Agriculture Market Trends and Innovations
Technology convergence between sensor networks and automated irrigation is compressing water consumption benchmarks while reshaping farm labor requirements across the Kingdom's production belts.
Precision drip fertigation systems are displacing flood irrigation as the dominant water delivery method in Saudi open-field vegetable production. Large-scale tomato and pepper growers in Al-Qassim and Al-Kharj are retrofitting center-pivot systems with soil-moisture probes and variable-rate injectors. This hardware shift is displacing uniform water application norms and enabling sub-field zoning that cuts per-ton water intensity by measurable margins.
SFDA pesticide maximum residue limits now enforce quarterly testing protocols for domestic leafy green producers seeking retail distribution licenses. The regulation compresses harvest-to-shelf timelines and forces integration with certified third-party laboratories. Central region greenhouse operators bear the heaviest compliance burden given their proximity to Riyadh's hypermarket distribution hubs.
Domestic food manufacturers now contract directly with grower cooperatives under fixed-volume agreements that bypass traditional wholesale souks. This channel consolidation concentrates price-setting power with Almarai and NADEC procurement divisions. The pattern is most pronounced in the dairy and fresh produce categories where cold-chain reliability requirements favor vertically integrated suppliers over fragmented trader networks.
Saudi Arabia Agriculture Market Segmentation
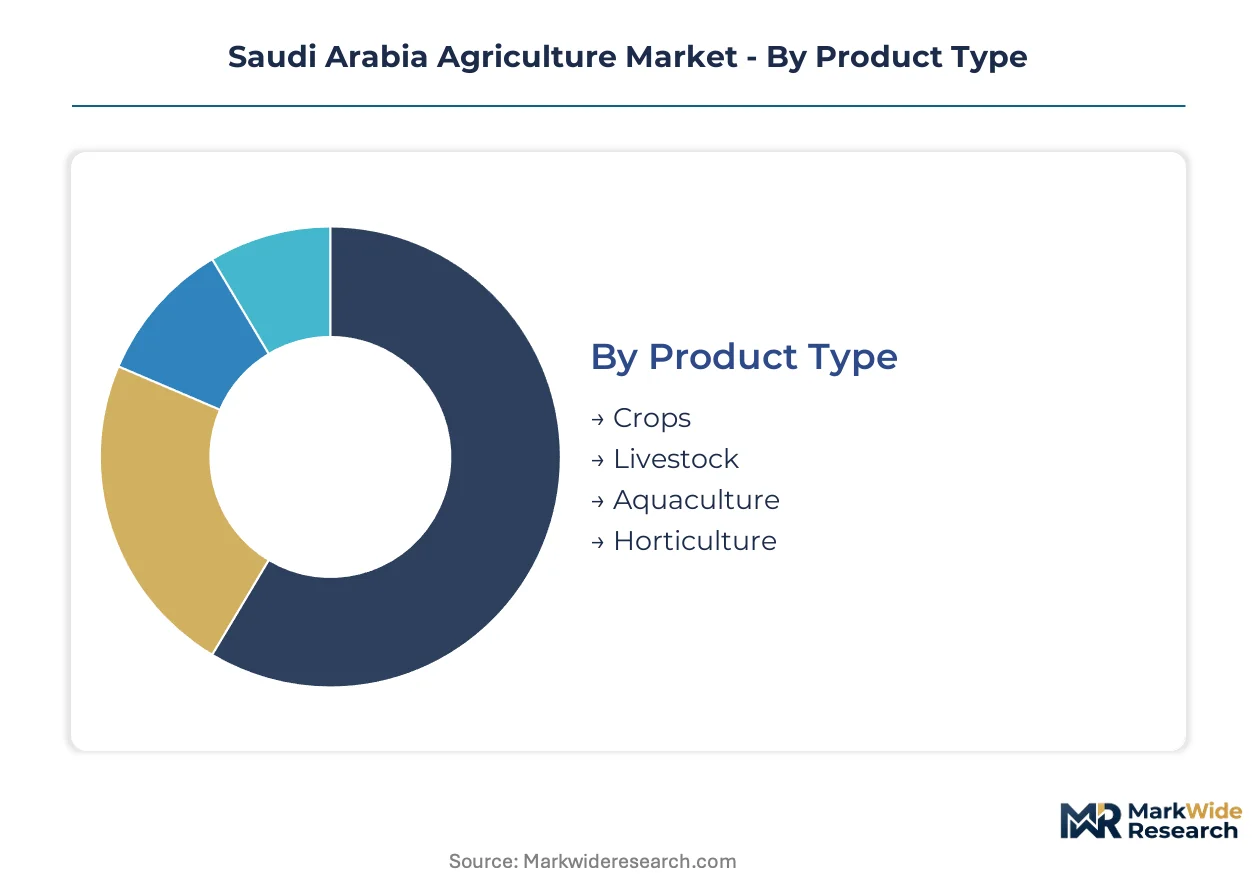
Segmentation reveals how SFDA compliance tiers and water access patterns concentrate value across distinct production systems. Each dimension exposes divergent cost structures and procurement pathways that shape competitive positioning for domestic and export-facing operators.
Product Type:
SFDA residue testing protocols apply differential stringency across animal versus plant-based outputs, segmenting compliance burdens and certification timelines.
- Crops:Field-grown cereals, vegetables, and forage occupy the largest cultivated area under center-pivot and drip systems. Wheat and barley production concentrates in Qassim and Al-Kharj where subsidized water allocations sustain domestic milling requirements. SFDA pesticide maximum residue limits enforce quarterly laboratory testing for retail-bound harvests.
- Livestock:Dairy cattle, poultry, and sheep operations integrate with domestic feed milling capacity anchored by ARASCO and Almarai procurement networks. Herd expansion depends on imported genetics and veterinary service density in the central belt.
- Aquaculture:Red Sea fish farming near Jazan and Duba supplies tilapia and shrimp to domestic processors. Brackish water systems bypass freshwater tariff exposure.
- Horticulture:Date palm cultivation dominates Al-Qassim and Eastern Province output, with organic certification penetration rising for European export contracts.
Established volume favors Crops; emerging adoption favors Aquaculture.
End Use Industry:
Customer specifications diverge sharply between bulk commodity processors and premium retail channels.
- Food Processing:Almarai and NADEC procurement divisions contract directly with grower cooperatives for standardized volume and cold-chain reliability. Fixed-price agreements displace spot market sourcing for dairy and fresh produce inputs.
- Export:Date and halal-certified meat shipments to Gulf neighbors and Southeast Asia require SASO conformity assessment and destination-country phytosanitary documentation.
- Retail:Hypermarket chains in Riyadh and Jeddah demand SFDA-certified organic labeling and traceable packaging for leafy greens and fresh herbs.
- Biofuels:Limited domestic ethanol distillation from agricultural waste operates at pilot scale pending regulatory clarity on fuel blending mandates.
Contract security favors Food Processing; margin expansion favors Export.
Distribution Channel:
Channel selection determines working capital intensity and price discovery mechanisms.
- Direct Sales:Large integrated producers bypass intermediaries to supply institutional foodservice and processing plants. This channel captures margin otherwise absorbed by trader networks.
- Wholesale:Traditional souk traders aggregate fragmented smallholder output in Riyadh's central produce market. Price volatility reflects spot supply fluctuations.
- Online:E-commerce platforms connect greenhouse operators with urban consumers for premium herb and microgreen subscriptions. Delivery logistics concentrate in Riyadh and Jeddah metropolitan zones.
- Cooperatives:Grower associations pool harvests for collective bargaining with retail chains and export packers. SFDA certification costs spread across member volumes.
Scale economies favor Direct Sales; customer reach favors Cooperatives.
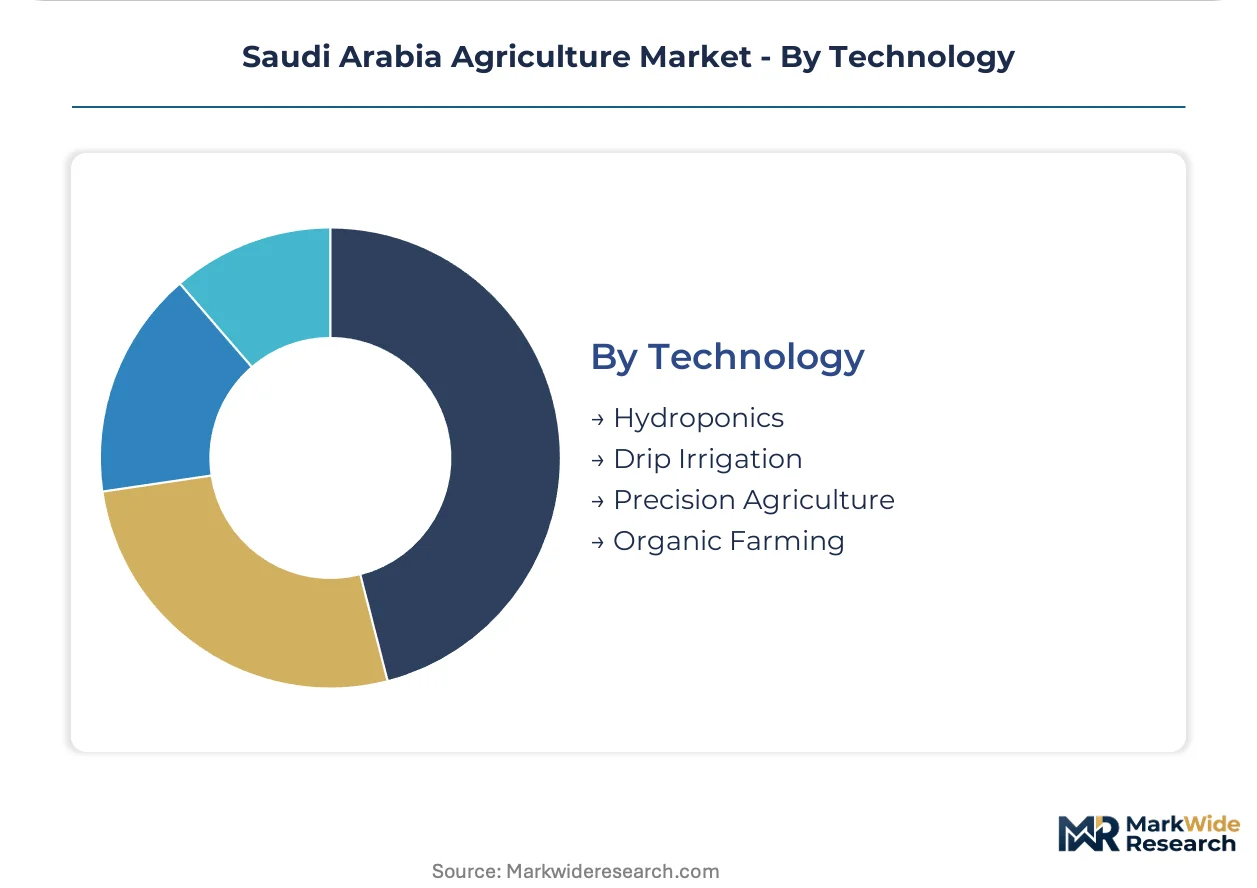
Technology:
Capital intensity and water efficiency differentiate adoption trajectories across farm sizes.
- Hydroponics:Soilless cultivation in climate-controlled greenhouses enables year-round tomato and cucumber production near urban demand centers. Stacked vertical systems multiply output per square meter in land-constrained Riyadh periphery.
- Drip Irrigation:Precision water delivery with soil-moisture sensors dominates open-field vegetable retrofitting in Al-Qassim. Variable-rate fertigation cuts per-ton water intensity compared to flood systems.
- Precision Agriculture:Drone-mounted multispectral imaging and GPS-guided equipment optimize input application for large wheat and alfalfa operations. Technical talent scarcity constrains deployment speed.
- Organic Farming:SFDA-certified conversion requires multi-year transition periods and residue testing backlogs. Premium pricing applies for retail and export channels.
Water policy favors Drip Irrigation; margin capture favors Hydroponics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's agricultural output clusters around state-backed land allocations and desalination corridors. Riyadh anchors dairy and poultry procurement networks. The Eastern Province leverages reverse osmosis infrastructure for commercial cultivation. Qassim concentrates date palm and forage production. Western Region coastal zones host emerging aquaculture operations. NEOM Northwest pilots climate-controlled greenhouse systems for export-oriented horticulture.
Riyadh
Central belt dairy demand concentrates procurement power with integrated processors. SFDA food safety mandates enforce quarterly residue testing for retail-bound milk and fresh produce. Al-Kharj and Al-Qassim satellite zones supply fodder and forage through ARASCO-contracted feed mills.
Eastern Province
Desalination-dependent irrigation unlocks commercial vegetable production near Jubail and Al-Ahsa. National Water Strategy tariff reforms threaten cost predictability for open-field operators. Dammam metropolitan demand pulls greenhouse tomato and cucumber output through direct retail contracts.
Qassim
Date palm cultivation dominates Buraydah and Unaizah districts with rising organic certification penetration. Saudi Green Initiative procurement quotas redirect supply contracts toward certified cooperatives. Al-Qassim Dairy Cluster concentrates veterinary services and cold-chain logistics for livestock operators.
Western Region
Jeddah and Makkah metropolitan demand drives premium herb and microgreen subscriptions through e-commerce platforms. Red Sea coastal waters near Jazan host brackish-water tilapia and shrimp farming. Brackish aquaculture bypasses freshwater tariff exposure facing inland operators.
NEOM Northwest
Climate-controlled greenhouse pilots test stacked vertical production for European export markets. NEOM regulatory sandbox frameworks may relax SFDA organic certification timelines for technology-validated operations. Tabuk agricultural zones supply trial volumes for hypermarket distribution partnerships.
Saudi Arabia Agriculture Market Competitive Landscape
Listed leaders compete with private specialists across land allocation access and procurement contract security. The market exhibits tiered concentration with state-linked entities controlling primary production and integrated processors dominating downstream channels. Three archetypes define competitive positioning: vertically integrated dairy-livestock conglomerates, state-supported grain and forage producers, and specialized animal feed manufacturers. Capacity expansion through desalination corridor land leases and backward integration into captive fodder supply represent the dominant competitive moves.
Within the integrated agribusiness tier, Almarai Company and NADEC anchor procurement networks across the Kingdom's central belt. Arabian Agricultural Services Company (ARASCO) occupies the specialized feed manufacturing position, sustaining supply security for poultry and livestock segments. These three entities exemplify the market's structural bias toward scale-driven operators with preferential land and water access.
| Leading Market Players |
|---|
| Almarai Company |
| National Agricultural Development Company (NADEC) |
| Savola Group |
| Tabuk Agricultural Development Company |
| Al-Jouf Agricultural Development Company |
| Arabian Agricultural Services Company (ARASCO) |
| Saudi Agricultural and Livestock Investment Company (SALIC) |
| Al-Othaim Holding Company |
| Al-Safi Danone |
| Others |
Pricing and Supply Chain Analysis
Drip irrigation retrofits replacing flood systems across Al-Qassim and Al-Kharj simultaneously compress water input costs and redraw procurement geography toward desalination corridor clusters with metered tariff predictability. This hardware substitution forces price realignment across three distinct supply tiers while concentrating contract power with integrated processors capable of underwriting capital-intensive precision agriculture deployments.
Pricing Analysis
Certification level under SFDA organic standards creates the primary spread between commodity spot and premium contract tiers. Pricing stratifies across premium certified-organic, standard SFDA-compliant, and economy conventional grades with residue testing frequency as the key discriminator. Pricing pressure stems from water tariff volatility under National Water Strategy reforms that threaten margin stability for open-field operators. Smallholder cooperatives exhibit highest price sensitivity due to working capital constraints, while Almarai and NADEC procurement divisions lock long-term offtake at fixed premiums.
Supply Chain Analysis
Inventory lead times for imported drip irrigation hardware and precision agriculture sensors stretch procurement cycles to 90-120 days given SASO technical regulation clearance requirements. Supply concentrates in Germany, Netherlands, and Israel for advanced fertigation equipment, while phosphate fertilizer draws from Moroccan and Jordanian mining operations. Single-source vulnerability pervades desalination membrane supply chains dominated by Japanese and Korean manufacturers. Distribution runs through ARASCO-contracted feed mills and Almarai cold-chain logistics for livestock inputs, with greenhouse produce bypassing wholesale souks via direct retail contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's agriculture sector sits at an inflection where SFDA compliance automation and precision water technology converge to displace fragmented conventional operators. The Saudi Green Initiative procurement mandates are accelerating this disruption by redirecting volume toward certified integrated producers.
For Market Incumbents: Consolidate land and water allocation access through preferential lease renewals in Qassim and Eastern Province desalination corridors. Deepen backward integration into captive fodder supply to insulate feed cost volatility from ARASCO pricing power. Prioritize SFDA organic certification investment to capture premium retail channel contracts before multi-year transition backlogs lengthen. For New Entrants and Emerging Players: Lead with hydroponics-vertical farming convergence in Riyadh periphery where land scarcity and urban demand density justify stacked production economics. Target Red Sea aquaculture zones near Jazan where brackish water systems bypass freshwater tariff exposure facing inland competitors. Secure NEOM regulatory sandbox partnerships to test accelerated organic certification pathways for technology-validated operations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision agriculture technology providers holding sensor network and automated irrigation IP. Five-to-ten year viability hinges on water policy predictability and SFDA enforcement consistency rather than commodity price cycles. Monitor National Water Strategy tariff implementation timelines as the critical inflection signal for open-field operator distress and consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Fodder Supply | ARASCO feed cost volatility insulation secures livestock margin stability for integrated dairy operators. |
| SFDA Organic Certification Acceleration | Premium retail channel access in Riyadh hypermarkets commands measurable price spreads over conventional grades. |
| Desalination Corridor Land Lease Expansion | Eastern Province reverse osmosis infrastructure unlocks previously barren cultivation zones with tariff-predictable water access. |
| Precision Agriculture Technology Deployment | Drone-mounted multispectral imaging optimizes input application for large wheat and alfalfa operations in Al-Kharj. |
| Red Sea Aquaculture Zone Development | Jazan brackish-water tilapia and shrimp farming bypasses freshwater tariff exposure threatening inland operators. |
Research Methodology
Desk research of SFDA regulatory filings, SASO technical regulations, National Water Strategy policy documents, and Saudi Green Initiative procurement frameworks preceded structured interviews with agricultural operations directors, irrigation systems engineers, feed mill procurement managers, and greenhouse technology specialists. Primary fieldwork across Riyadh, Qassim, and Eastern Province production zones was cross-validated against customs data for agricultural equipment imports and desalination infrastructure investment disclosures. Bottom-up grower surveys and top-down processor procurement data were triangulated to reconcile volume estimates.
Variance decomposition across product type, end-use industry, distribution channel, and technology adoption tiers shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling that weighted water policy scenarios against SFDA enforcement intensity. Segment-specific drivers included drip irrigation retrofit penetration rates, organic certification transition timelines, and aquaculture zone licensing velocity.
The analysis sits within stated boundaries; outcomes outside sustained Saudi Green Initiative procurement enforcement or accelerated water tariff reform would require recalibration. Forecasts reflect documented assumptions regarding desalination capacity expansion and regulatory compliance automation adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Primary Feed Materials Market