
 Europe Alfalfa Hay Market | 2026-2036
Europe Alfalfa Hay Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Alfalfa Hay Market Foresight
CE marking under EU feed hygiene regulations is reorganizing which suppliers can access cross-border trade within the European single market. Grupo Osés leverages its integrated dehydration and pelletization infrastructure across northern Spain to sustain supply consistency for dairy cooperatives. Nafosa anchors Iberian production capacity with specialized cropping cycles that dominate the premium dehydrated hay tier. Gruppo Carli differentiates through Italian sourcing networks that compete on shorter lead times to central European horse owners.
Alfalfa hay comprises dried legume forage with crude protein content typically ranging from 15% to 22% on a dry matter basis, produced through field curing or mechanical dehydration for preservation of nutritional value in ruminant and equine diets. Pellets and cubes are gaining structural share as dairy farms mechanize feeding systems and seek reduced storage footprints compared to traditional bales. Premium and good grades command disproportionate margin pools where protein content and leaf retention determine pricing power, while chopped hay occupies growing niches in precision dairy nutrition programs. The grade dimension fundamentally shapes buyer segmentation, with horse owners and competitive equestrian operations driving selective demand for leaf-rich, low-dust premium lots.
EMA feed material registration requirements and EU Green Deal sustainability disclosures are reshaping import documentation and carbon footprint verification for non-European suppliers. REACH-related scrutiny on pesticide residues in fodder crops tightens quality thresholds that Spanish and Italian growers must meet for retained market access. Stakeholders should monitor evolving EU deforestation-free supply chain regulations, as these will determine whether third-country hay volumes from North Africa or North America retain competitive positioning against domestic European production.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is tightening sustainable fodder sourcing requirements across the European single market. Dairy cooperatives in Spain and France are expanding alfalfa inclusion rates in high-yield cow rations as protein feed costs fluctuate, reshaping procurement patterns for dehydration-grade crops.
Growth Catalysts
- CE marking compliance:Cross-border trade within the European single market is reorganizing supplier access under EU feed hygiene regulations, favoring established dehydration infrastructure operators.
- Dairy farm mechanization:Pellets and cubes are gaining structural share as automated feeding systems spread across northern Spain and France, reducing storage footprints compared to traditional bales.
- Irrigation infrastructure:Spain's Ebro Valley concentrates demand through consistent dehydration-grade crop quality supported by advanced water management systems.
Market Restraints
- Input cost volatility:Natural gas prices for mechanical dehydration create margin pressure on Spanish and Italian processors during winter production cycles.
- Supply concentration risk:Iberian production capacity dominates the premium dehydrated hay tier, creating vulnerability to regional drought or water allocation disputes.
- REACH pesticide scrutiny:Residue thresholds for fodder crops tighten quality requirements that growers must meet for retained market access.
Strategic Opportunities
- Italian sourcing networks:Shorter lead times to central European horse owners create differentiation potential against Iberian supply chains.
- Carbon footprint verification:EU Green Deal sustainability disclosures enable premium positioning for domestic European production against third-country imports.
- Precision dairy nutrition:Chopped hay occupies growing niches in ration formulation programs targeting high-yield cow productivity metrics.
Industry Challenges
- Deforestation-free documentation:Evolving EU supply chain regulations will determine whether North African or North American hay volumes retain competitive positioning, requiring extensive traceability systems.
- EMA feed material registration:Import documentation complexity for non-European suppliers creates compliance timeline delays and administrative burden.
- Dehydration equipment capex:Mechanical drying infrastructure requires substantial capital investment, limiting entry for new processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Alfalfa Hay Market |
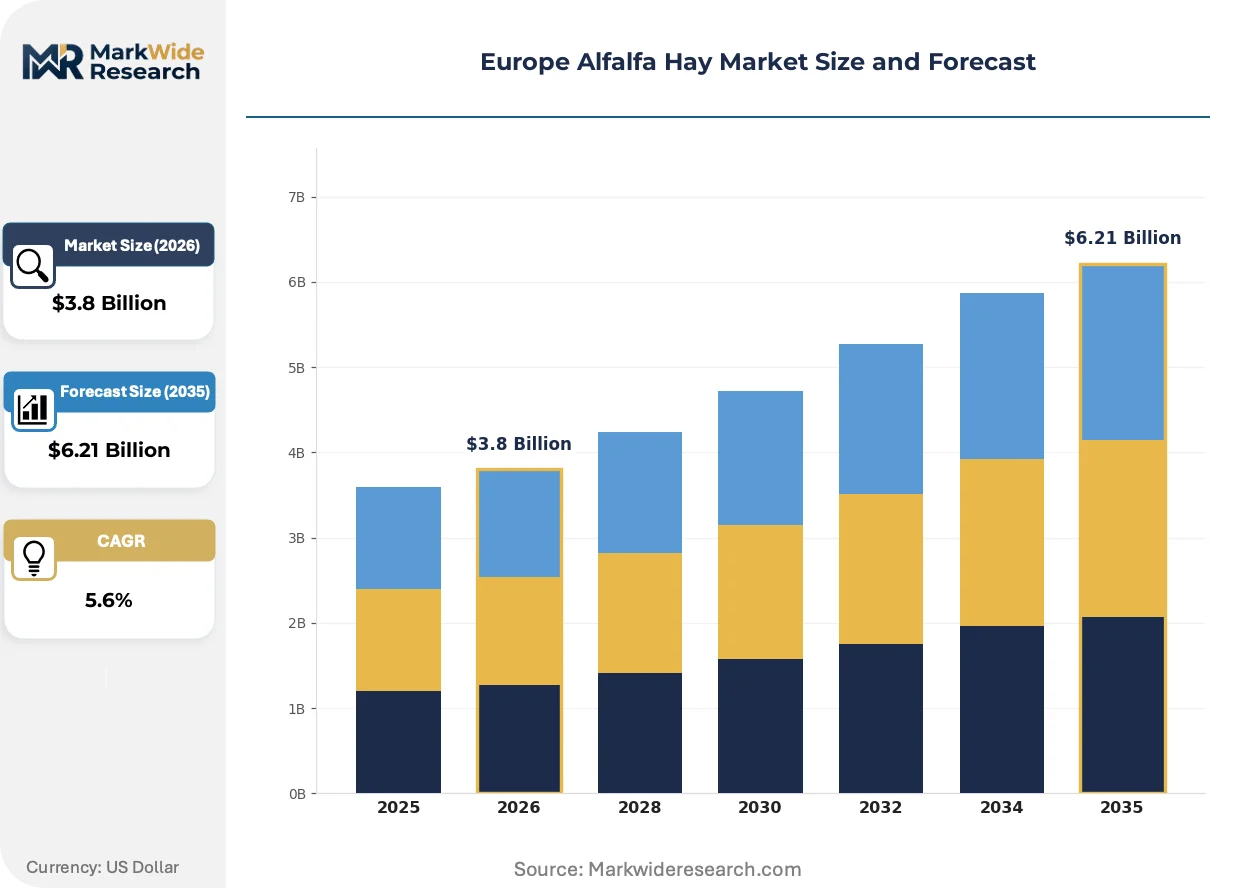
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Hay, Pellets, Cubes, Chopped Hay End User: Dairy Farms, Poultry Farms, Horse Owners, Aquaculture Grade: Premium, Good, Fair, Low Quality Packaging Type: Bales, Bags, Bulk, Totes |
| Companies Covered | Alfalfa Monegros S.L., Grupo Osés, Anderson Hay & Grain Inc., Cubeit Hay Company, Gruppo Carli, Al Dahra ACX Global Inc., Coaba, Nafosa, Border Valley, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Alfalfa Hay Market Shifts & Advancements
Mechanical dehydration technology and automated feeding systems are actively reshaping how alfalfa hay moves from field to ruminant. Three interconnected developments are restructuring product formats, compliance requirements, and buyer relationships across the European market.
Mechanical dehydration is decomposing the traditional field-curing supply chain by enabling consistent protein preservation and leaf retention regardless of weather conditions. Dairy cooperatives in Spain and France are adopting dehydration-grade hay at accelerating rates for high-yield cow rations. This technology is compressing seasonal supply volatility and enabling year-round contract structures that field-cured operations cannot match.
EU Green Deal sustainability disclosures are mandating carbon footprint verification for imported feed materials, creating documentation burdens for non-European suppliers. The EMA feed material registration framework now requires enhanced traceability protocols that domestic Spanish and Italian growers can satisfy more readily. Premium and good grade hay segments are most affected, with buyers shifting preference toward verifiable low-carbon domestic sourcing.
Horse owners and competitive equestrian operations are consolidating purchasing through specialized distributors who guarantee leaf-rich, low-dust premium lots with batch-specific nutritional certification. Traditional commodity brokers serving mixed livestock operations are losing share to vertically integrated suppliers controlling dehydration, pelletization, and direct delivery. This channel transformation is most visible in Germany and the Netherlands, where stable management standards have professionalized procurement functions.
Europe Alfalfa Hay Market Segmentation
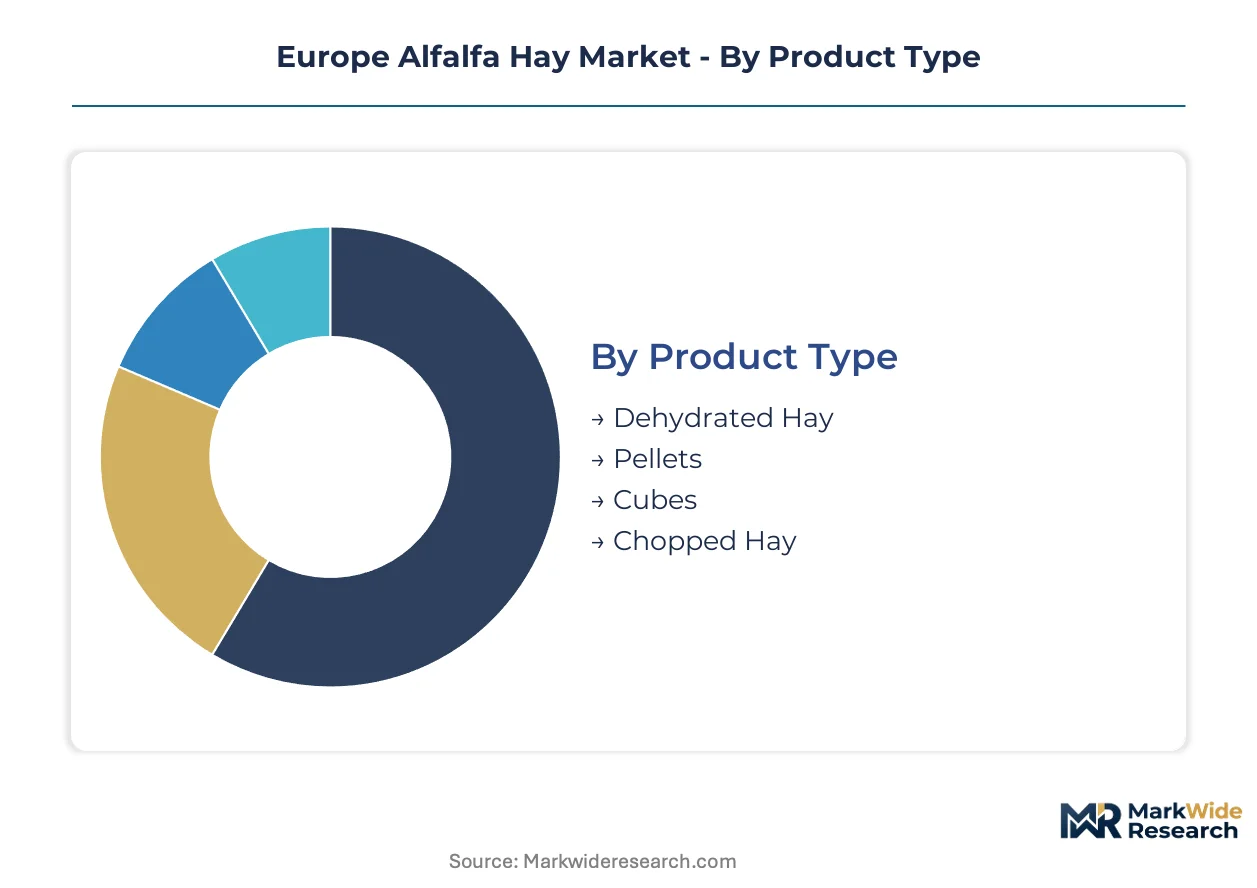
Segmentation in the Europe alfalfa hay market reveals how regulatory compliance, mechanization trends, and end-use specialization fragment procurement patterns across distinct product formats and customer categories. Buyers in Spain's Ebro Valley and northern France prioritize different specifications than central European horse owners, creating tiered demand structures that suppliers must navigate.
Product Type:
CE marking under EU feed hygiene regulations creates divergent compliance burdens across mechanical processing methods, favoring operators with integrated dehydration infrastructure over field-cured alternatives.
- Dehydrated Hay:Mechanical dehydration preserves crude protein content between 15% and 22% on a dry matter basis through controlled thermal processing, eliminating weather-dependent quality variation. Dairy cooperatives in Spain's Ebro Valley concentrate procurement here for high-yield cow rations where consistent nutritional specification justifies premium positioning. REACH-related scrutiny on pesticide residues tightens input sourcing requirements that Iberian processors must satisfy for retained market access.
- Pellets:Compression into cylindrical forms reduces storage footprint by 60-70% compared to traditional bales while enabling automated feeding system integration. Northern Spanish and French dairy farms are expanding pellet inclusion rates as protein feed costs fluctuate and mechanization spreads across large-scale operations. The EU Green Deal's Farm to Fork strategy favors this format for traceability documentation in sustainability disclosures.
- Cubes:Denser compression than pellets creates slower consumption rates suited to equine feeding protocols where controlled intake matters.
- Chopped Hay:Precision dairy nutrition programs in France are adopting shorter particle lengths for ration formulation targeting specific productivity metrics.
Dehydrated hay handles the majority of throughput; pellets are expanding most quickly on share as dairy mechanization accelerates.
End User:
Customer-type differentiation tracks directly to nutritional specification tolerance and procurement professionalization levels across livestock and equine sectors.
- Dairy Farms:High-yield cow rations in Spain and France drive volume demand for protein-standardized lots with batch-specific certification. Automated feeding system adoption favors pellets and cubes that reduce labor input and storage requirements. EMA feed material registration requirements for imported materials create preference for domestic European sourcing with simpler documentation trails.
- Horse Owners:Competitive equestrian operations and professional stable managers in Germany and the Netherlands demand leaf-rich, low-dust premium grades with guaranteed crude protein floors. Specialized distributors are consolidating purchasing power here, displacing traditional commodity brokers through vertical control of dehydration and direct delivery.
- Poultry Farms:Smaller volume uptake concentrates in regions where alfalfa inclusion supports yolk coloration and omega fatty acid profiles.
- Aquaculture:Emerging experimental applications in Mediterranean finfish operations test alfalfa protein concentrate as fishmeal partial replacement.
Dairy farms absorb the largest volume flows; horse owners generate the steepest margin premiums per ton.
Grade:
Protein content thresholds and leaf retention rates stratify pricing power across four quality tiers that shape supplier positioning.
- Premium:Maximum leaf retention with crude protein exceeding 20% dry matter and minimal stem content commands selective demand from competitive equestrian operations. Batch-specific nutritional certification with carbon footprint verification enables positioning against third-country imports under EU Green Deal sustainability disclosures.
- Good:Moderate leaf retention with protein 17-20% serves standard dairy rations where consistency outweighs maximum specification. Spanish and Italian growers dominate this tier through specialized cropping cycles and irrigation infrastructure.
- Fair:Higher stem inclusion accepts lower protein floors for cost-sensitive mixed livestock operations.
- Low Quality:Weather-damaged or over-mature field-cured material occupies shrinking niches as mechanical dehydration expands.
Premium grade captures disproportionate margin pools; good grade moves the highest absolute tonnage.
Packaging Type:
Physical handling requirements and storage economics determine format selection across customer scale and infrastructure investment levels.
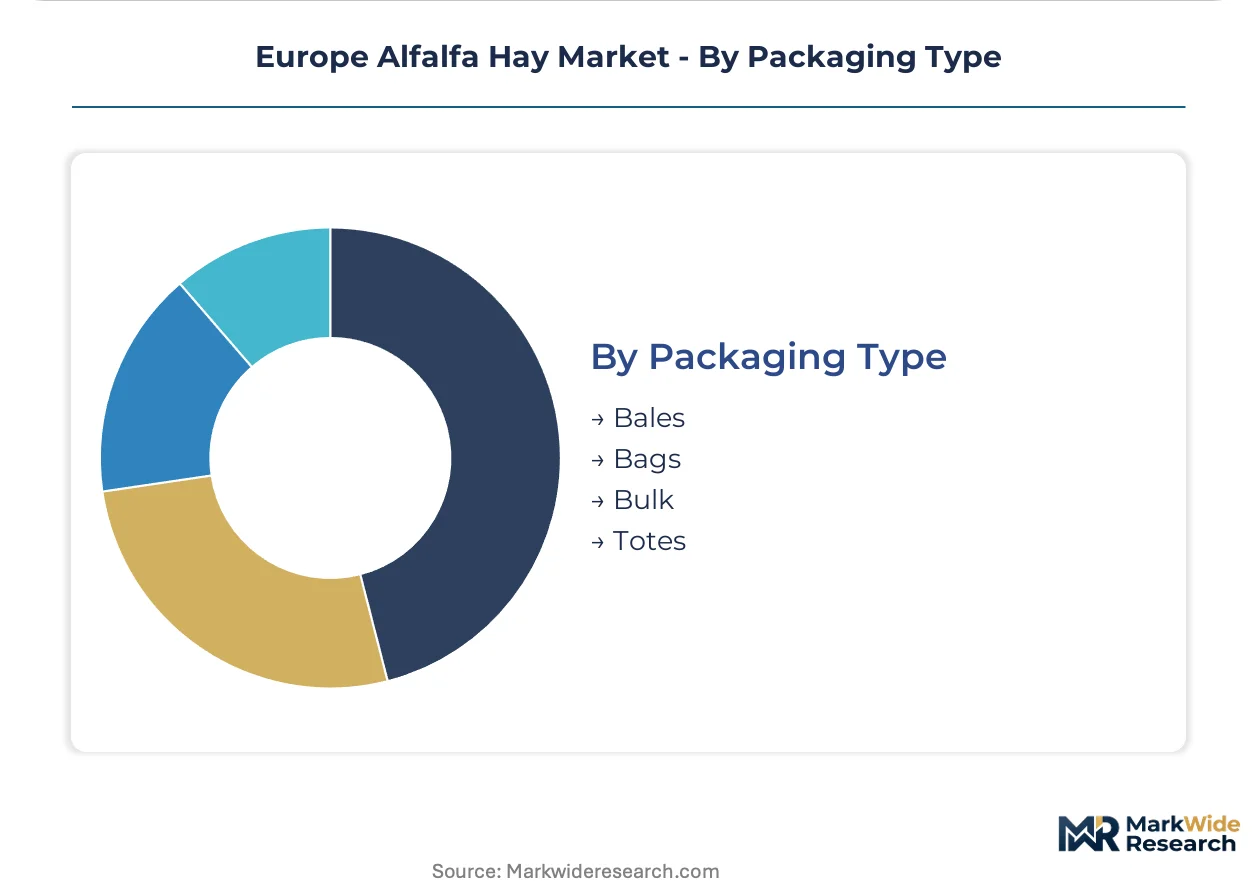
- Bales:Traditional rectangular or round formats persist among smaller operations with existing handling equipment and covered storage capacity. Field-cured supply chains favor this lowest-processing format, though share erodes as dehydration infrastructure expands.
- Bulk:Loose material in dedicated silos minimizes per-unit packaging cost for large dairy cooperatives with pneumatic handling systems. Northern Spain's integrated dehydration and pelletization facilities optimize for bulk outbound logistics to major cooperative buyers.
- Bags:20-50kg units serve horse owners and smaller livestock operations requiring portioned inventory management.
- Totes:Intermediate bulk containers bridge scale gaps for mid-size operations lacking full bulk infrastructure.
Bulk dominates volume throughput among dairy processors; bags retain essential positioning in equine channels where handling flexibility matters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mediterranean Rail Freight Corridor links Iberian dehydration facilities to dairy processors across northern Europe, underwriting Spain's centrality in premium hay logistics. This infrastructure asset positions the Ebro Valley as the continent's dominant sourcing node for protein-standardized fodder.
Spain
Dairy cooperatives in Aragon and Catalonia expand pellet procurement for automated feeding systems. EMA feed material registration requirements favor domestic processors over North African imports. Grupo Osés anchors dehydration capacity across northern Spain with integrated pelletization infrastructure serving French cooperative buyers.
France
High-yield cow rations in Brittany and Normandy drive demand for protein-verified hay lots. EU Green Deal Farm to Fork sustainability disclosures mandate carbon footprint documentation that disadvantages third-country suppliers. The Port of Rouen concentrates import logistics for dehydrated hay moving into Paris Basin dairy operations.
Italy
Emilia-Romagna's equine breeding clusters source leaf-rich premium grades with batch-specific certification. REACH pesticide residue thresholds tighten input sourcing for Po Valley growers. Gruppo Carli leverages shorter lead times to German and Dutch horse owners against Iberian supply chains.
Germany
Professional stable managers in Lower Saxony and North Rhine-Westphalia consolidate purchasing through specialized distributors. CE marking under EU feed hygiene regulations reorganizes cross-border supplier access. The Rhine-Main corridor channels dehydrated hay logistics from Dutch transshipment hubs to central European buyers.
Netherlands
Rotterdam's port infrastructure handles bulk dehydrated hay transshipment for redistribution into German dairy markets. EMA documentation requirements for imported materials create administrative delays favoring EU-origin sourcing. Precision dairy nutrition programs in Gelderland adopt chopped hay formats for ration formulation targeting productivity metrics.
Europe Alfalfa Hay Market Competitive Landscape
Listed leaders compete with private specialists across dehydration infrastructure ownership, fragmenting competitive terrain between scale-driven cooperatives and family-held processing operations. The vendor base stratifies around three archetypes: integrated dehydration-pelletization operators, field-cured commodity brokers, and premium-grade specialists serving equine channels. Capacity expansion and backward integration into captive cropping represent the dominant competitive moves as processors secure protein-standardized supply.
Within the integrated infrastructure tier, Grupo Osés and Nafosa exemplify Iberian dehydration specialists with controlled supply chains from field to pellet. Gruppo Carli occupies a position among Italian sourcing networks competing on proximity to central European equine buyers. Anderson Hay & Grain Inc. represents North American export-oriented operations navigating EMA registration complexity for retained European market access.
| Leading Market Players |
|---|
| Alfalfa Monegros S.L. |
| Grupo Osés |
| Anderson Hay & Grain Inc. |
| Cubeit Hay Company |
| Gruppo Carli |
| Al Dahra ACX Global Inc. |
| Coaba |
| Nafosa |
| Border Valley |
| Others |
Supply & Pricing Matrix
Forty-five-day lead times from Iberian dehydration facilities to German dairy cooperatives concentrate pricing power with integrated processors who control pelletization infrastructure and year-round contract fulfillment. This temporal compression of supply reliability enables premium capture for dehydration-grade hay while field-cured alternatives trade at persistent discounts due to weather-dependent quality variance.
Pricing Analysis
Volume-discount tiering structures separate premium dehydrated lots with batch-specific certification from standard-grade field-cured material and economy-grade weather-damaged supply. Pricing stratifies across premium, standard, and economy tiers where protein content verification and leaf retention rates determine contract premiums. Cost compression in standard-grade segments is intensifying because natural gas price volatility for mechanical dehydration feeds into processor margin pressure during winter production cycles. Dairy cooperatives in northern Spain and France exhibit lowest price sensitivity due to ration formulation requirements, while mixed livestock operations in peripheral markets drive hardest bargaining for economy-tier material.
Supply Chain Analysis
Spain and Italy anchor European dehydration-grade hay production through specialized cropping cycles and irrigation infrastructure that supports consistent protein preservation. The supply chain draws from natural gas inputs for thermal processing, alfalfa seedstock from proprietary breeding programs, and specialized baling equipment for leaf retention. Single-source vulnerability concentrates in the Ebro Valley where water allocation disputes or regional drought could disrupt premium supply. Distribution runs through Mediterranean Rail Freight Corridor links to Dutch transshipment hubs and direct bulk delivery to French dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nutritional certification services and carbon footprint verification layers are expanding faster than commodity hay volumes as EU Green Deal disclosures mandate documentation depth that processors can monetize through subscription-grade traceability contracts.
For Market Incumbents: Secure backward integration into captive alfalfa cropping in Aragon and Catalonia to defend against North African import competition under evolving deforestation-free regulations. Invest in dehydration equipment redundancy to mitigate natural gas price volatility that threatens margin stability during winter production cycles. For New Entrants and Emerging Players: Anchor in Italian sourcing networks serving German and Dutch equine channels where shorter lead times create differentiation against Iberian supply chains. Target precision dairy nutrition programs in France with chopped hay formats that command formulation-service premiums beyond commodity pellet pricing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mechanical dehydration infrastructure as REACH compliance and carbon verification systems require processor-level investment that field-cured operators cannot match. Acquisition candidates with integrated pelletization capacity and established EMA feed material registration offer strongest positioning through the analysis window. Monitor water allocation policy shifts in Spain's Ebro Basin as inflection indicator for supply concentration risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cropping | Grupo Osés and Nafosa secure protein-standardized supply against irrigation allocation volatility. |
| Carbon Footprint Verification Program | Domestic Spanish and Italian growers differentiate against North African imports under EU Green Deal disclosures. |
| Precision Dairy Nutrition Service Launch | Chopped hay formats capture formulation premiums in French high-yield cow ration programs. |
| Dehydration Equipment Redundancy Investment | Dual-fuel thermal processing mitigates natural gas price volatility during winter production cycles. |
| Specialized Distributor Channel Control | Vertical control of dehydration-to-stable delivery displaces commodity brokers in German equine markets. |
Research Methodology
The analysis maps dehydration infrastructure ownership, product format adoption curves, and grade-tier procurement patterns, each validated through plant managers at Spanish and Italian processing facilities, procurement leads at French dairy cooperatives, distribution channel partners in German equine supply chains, and regulatory affairs specialists navigating EMA feed material registration. Primary interview findings triangulate against secondary sources including EU customs trade data, EFSA feed safety bulletins, dehydration equipment manufacturer disclosures, and irrigation authority water allocation records. Bottom-up volume estimates from processor capacity utilization cross-check against top-down demand calculations from dairy herd expansion metrics and equine population surveys.
Consistency checks validate volume and value outputs against external benchmarks including feed industry association consumption surveys and agricultural commodity trade flow databases across the projection horizon. The analytical framework models product type, end user segment, grade tier, and packaging format dimensions alongside regional production hub clustering. CAGRs derive from segmented growth rate analysis applied to baseline volume and value estimates, with forecast inputs including dairy farm mechanization adoption curves, EU Green Deal implementation timelines, and irrigation infrastructure investment pipelines.
Underlying assumptions cover sustained EU Green Deal enforcement trajectory, stable natural gas price bands for thermal processing economics, and intact Mediterranean Rail Freight Corridor capacity, with deviation risk concentrated in regulatory acceleration on deforestation-free documentation and climate-induced water allocation restrictions. Forecasts reflect these documented assumptions with acknowledgment that EMA registration complexity for non-European suppliers or drought frequency in Iberian production zones could materially revise trajectory. Recalibration cycles align with material shifts in EU feed hygiene regulation implementation and irrigation policy reform announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market