
 Philippines Feed Industry Market | 2026-2036
Philippines Feed Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Feed Industry Market Insights
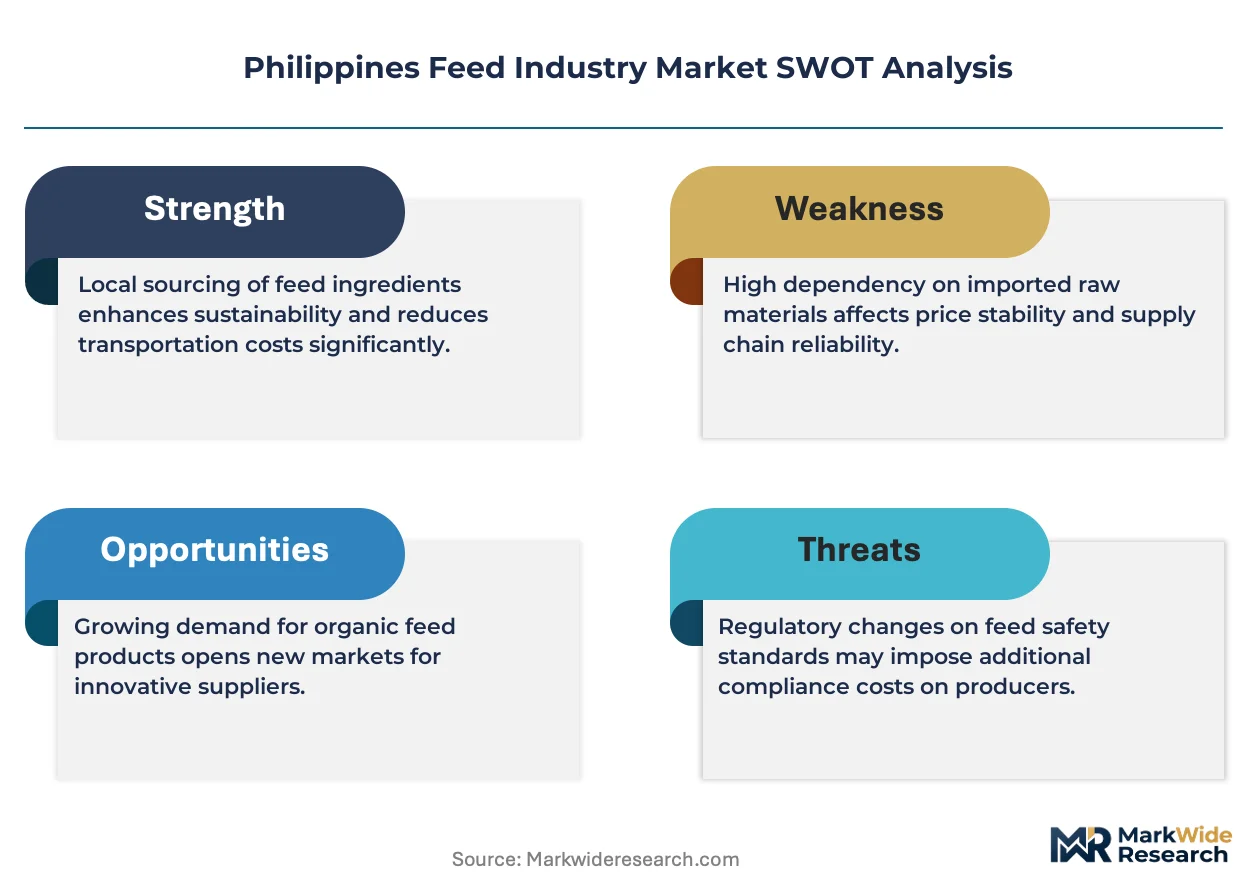
Asset-light contract growing arrangements is tilting competitive dynamics toward integrators with balance-sheet flexibility. Charoen Pokphand Foods Philippines Corporation leverages captive breeding and slaughtering capacity to lock in feed offtake. San Miguel Foods anchors its position through backward integration into grain trading and port logistics. Vitarich specializes in aquaculture feeds, occupying a niche where marine ingredient sourcing creates margin differentiation.
The Philippines feed industry encompasses nutritionally formulated mixtures of grains, oilseeds, protein meals, vitamins, and minerals processed through extrusion or pelleting to deliver specified metabolizable energy and crude protein levels for targeted livestock performance. These formulations serve as the primary input cost in commercial animal protein production, directly influencing feed conversion ratios and carcass yields. Poultry feed dominates volume given the country's per capita chicken consumption leadership in Southeast Asia, while aquaculture feed commands premium pricing due to fish meal inclusion requirements. Complete feed captures the largest value pool as integrators outsource formulation complexity, though high-protein variants are gaining traction among independent growers seeking faster weight gain.
The Department of Agriculture's AO 42 restricts antibiotic growth promoters, forcing reformulation toward phytogenics and organic acid blends that DSM Nutritional Products AG and Alltech supply. BIS-equivalent feed safety certifications and FSSAI-aligned import protocols for Indian soybean meal shape raw material sourcing decisions. Stakeholders must monitor how the Bureau of Animal Industry's pending traceability rules will reshape distribution channel accountability and testing costs.
Market Dynamics
Antibiotic withdrawal mandates under AO 42 are forcing rapid reformulation across Philippine feed mills, compressing margins while creating first-mover advantages for integrators with captive R&D capacity.
Growth Catalysts
- AO 42 Implementation:The Department of Agriculture's antibiotic growth promoter ban is accelerating demand for phytogenic and organic acid feed additives as livestock integrators seek compliant formulations.
- Central Luzon Poultry Belt Expansion:Contract growing arrangements in this region are concentrating feed procurement volumes among integrators with balance-sheet flexibility to fund grower facility upgrades.
- Aquaculture Premium Segmentation:Marine ingredient inclusion requirements for shrimp and fish feeds are creating margin pools distinct from commoditized poultry formulations.
Market Restraints
- Fish Meal Price Volatility:Peruvian anchovy catch variability and El Niño disruptions transmit directly to aquaculture feed cost structures, compressing processor margins during scarcity cycles.
- Soybean Meal Import Dependency:BIS-equivalent certification requirements and FSSAI-aligned Indian import protocols create sourcing bottlenecks that concentrate supplier power with accredited traders.
- Traceability Infrastructure Gaps:Pending Bureau of Animal Industry rules will impose testing and documentation burdens that smaller independent mills lack capital to absorb.
Strategic Opportunities
- Mindanao Aquaculture Development:Underpenetrated coastal provinces offer white space for specialized marine feed distribution networks serving emerging shrimp farming clusters.
- Phytogenic Additive Convergence:Essential oil extraction technology paired with precision dosing systems enables differentiation against generic antibiotic-free formulations.
- Digital Procurement Platforms:Direct-to-grower feed ordering applications are disintermediating traditional distributor networks in Visayas independent farming communities.
Industry Challenges
- Nutritionist Talent Scarcity:Reformulation complexity under AO 42 demands specialists in metabolizable energy modeling that Philippine universities currently underproduce.
- Cold Chain Capex Burden:Aquaculture feed's fish meal sensitivity requires temperature-controlled logistics investments that strain regional distributor balance sheets.
- Multi-Certification Overlap:Simultaneous BIS-equivalent, FSSAI-aligned, and pending traceability compliance creates documentation friction for importers serving multiple integrator specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Feed Industry Market |
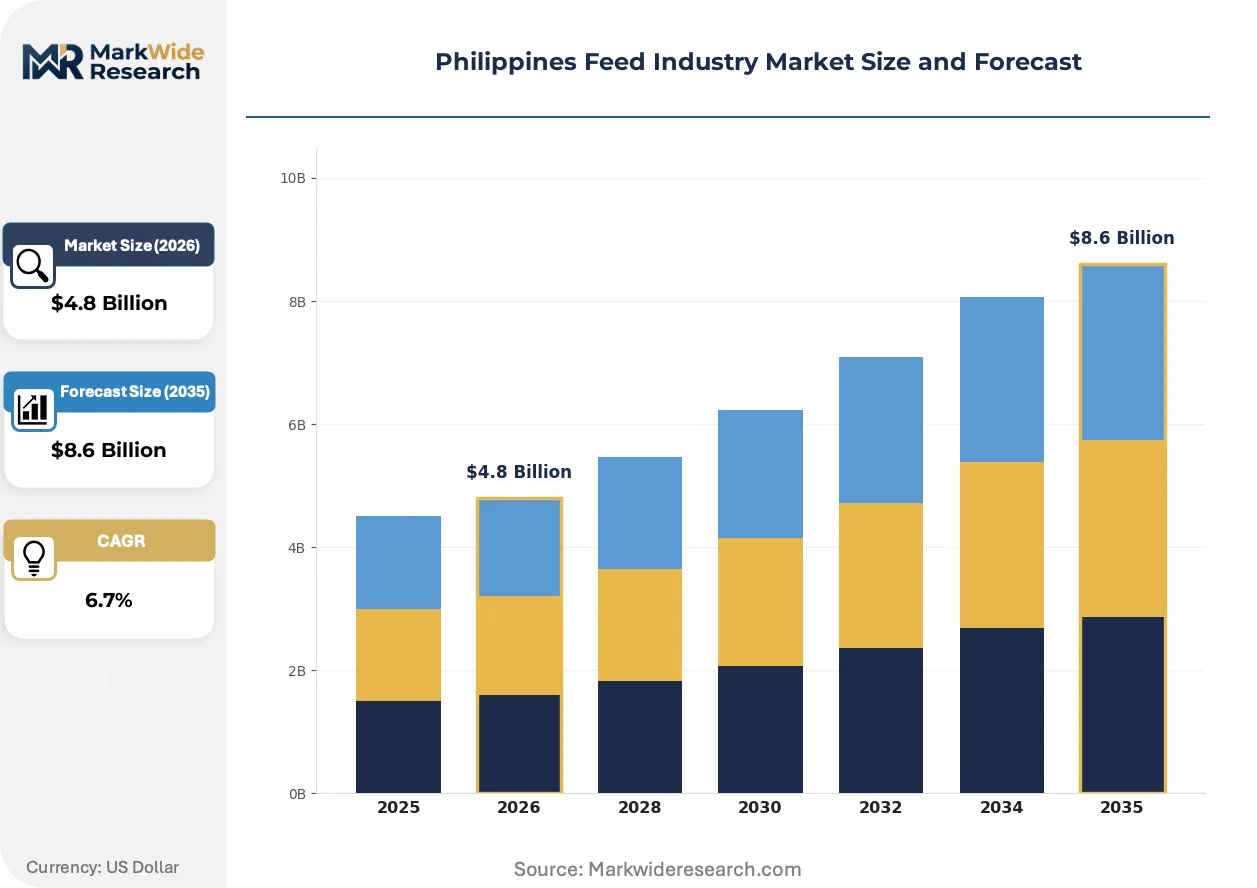
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Supplementary Feed, Medicated Feed, Base Mix Ingredient Type: Corn, Soybean Meal, Fish Meal, Wheat Bran Animal Type: Poultry, Swine, Aquaculture, Ruminants Formulation Type: Conventional, Organic, Non-GMO, High-Protein |
| Companies Covered | Charoen Pokphand Foods Philippines Corporation, Cargill Incorporated, San Miguel Foods (B-meg), Universal Robina Corporation, Vitarich, Alltech, Inc., Archer Daniel Midland Co., DSM Nutritional Products AG, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Feed Industry Market Trends and Innovations
Extrusion technology advances and regulatory chemistry substitution are compressing traditional formulation cycles while digital procurement tools reshape distributor economics.
Precision pelleting with variable density control is rendering obsolete fixed-formula extrusion systems that cannot adjust binders for tropical humidity fluctuations. Large integrators in Central Luzon are retrofitting lines within 18-month cycles. This compression favors equipment suppliers with local technical service presence over distant OEMs.
The Department of Agriculture's pending traceability rules will mandate batch-level documentation from raw material receipt through grower delivery. Feed mills are pre-positioning ERP systems to capture chain-of-custody data. Smaller regional players in Visayas face compliance timelines that outpace their IT upgrade capacity.
Contract growing consolidation is compressing independent distributor relevance as integrators centralize procurement through captive supply agreements. Traditional feed dealers in Bulacan and Pampanga are losing volume to direct mill-to-farm logistics. This channel shift is most visible in broiler operations where integrators control 80% of live bird offtake.
Philippines Feed Industry Market Segmentation
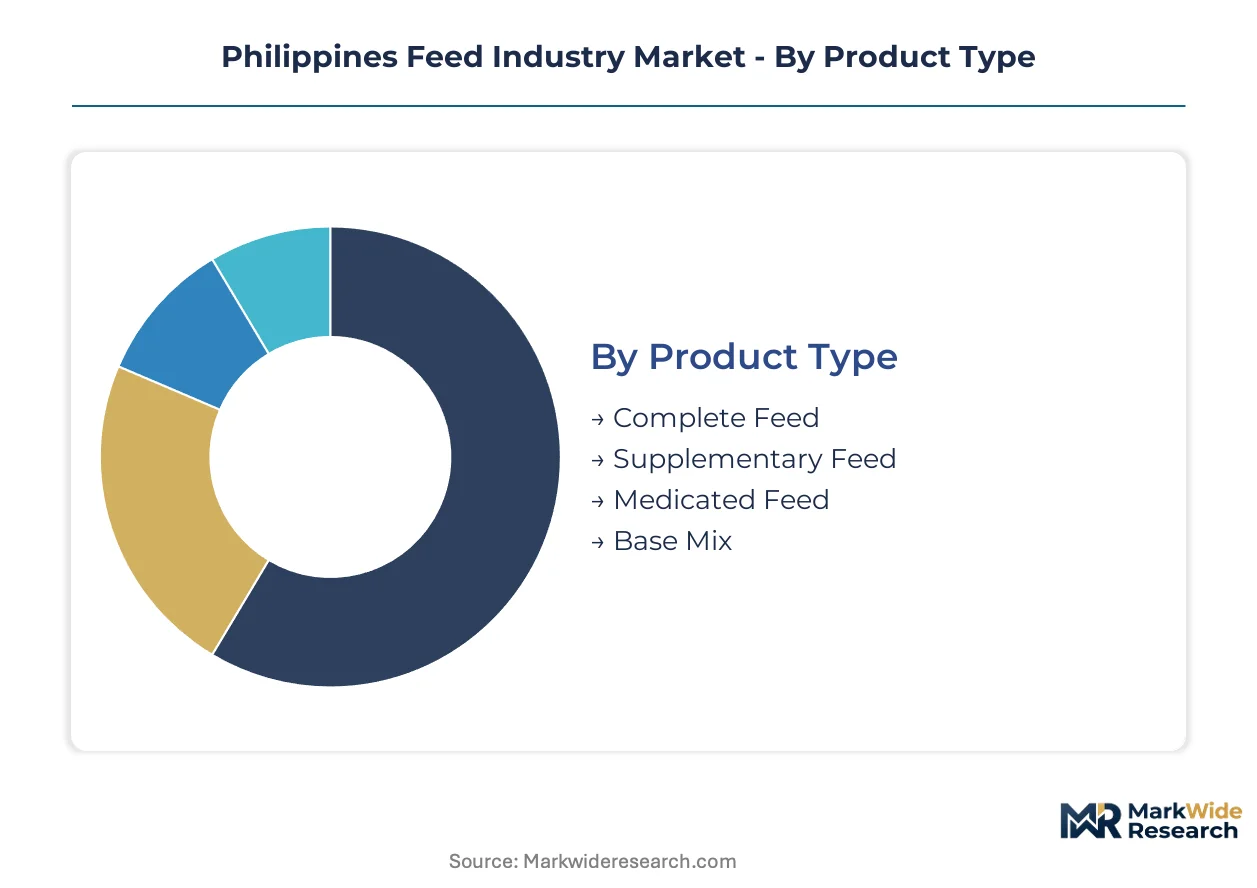
Feed segmentation in the Philippines reveals how procurement patterns diverge between integrators seeking turnkey solutions and independent growers optimizing input costs through partial formulations. Each dimension exposes distinct margin pressures and regulatory exposure under AO 42.
Product Type:
After-sales service intensity varies sharply across product tiers, with complete feed demanding technical field support for conversion ratio optimization while base mix requires only formulation guidance.
- Complete Feed:Fully formulated rations delivering specified metabolizable energy and crude protein levels through extrusion or pelleting. Central Luzon integrators driving contract growing consolidation source complete feed exclusively to standardize grower performance and simplify procurement audits.
- Supplementary Feed:Concentrated nutrient packs designed to fortify on-farm grain mixes, typically 15-40% inclusion rates. Independent swine operations in Batangas and Bulacan favor this tier for cost control, though AO 42 reformulation complexity is pushing some toward complete alternatives.
- Medicated Feed:Therapeutic and prophylactic formulations containing regulated additives. The Bureau of Animal Industry's veterinary prescription requirements constrain distribution to accredited mills with licensed nutritionists.
- Base Mix:Premix concentrates of vitamins, minerals, and amino acids for on-farm blending. Large ruminant operations in Mindanao source base mix to leverage locally available roughage while controlling micronutrient precision.
By volume, Complete Feed leads. By growth pace, Medicated Feed is climbing fastest as antibiotic withdrawal timelines compress.
Ingredient Type:
Raw material cost tiers stratify procurement strategies, with marine-derived inputs commanding premium positioning against commoditized grain streams.
- Corn:Primary energy source constituting 50-60% of typical poultry formulations. Domestic production shortfalls force Visayas mills to source from Mindanao and import channels, concentrating supplier power with traders holding BIS-equivalent import accreditations.
- Soybean Meal:Standardized protein meal at 44-48% crude protein content. Indian FSSAI-aligned protocols and Bureau of Customs inspection bottlenecks create procurement friction that favors integrators with long-term supply contracts.
- Fish Meal:Premium protein ingredient at 60-65% crude protein with essential amino acid profiles for aquaculture. Peruvian anchovy catch variability and El Niño cycles transmit directly to shrimp feed cost structures.
- Wheat Bran:Fiber-rich milling byproduct serving ruminant and swine rations. Regional flour mill proximity determines cost competitiveness, favoring Luzon-based feed operations.
Corn dominates procurement tonnage. Fish Meal commands the steepest price volatility and margin compression exposure.
Animal Type:
Customer type concentration shapes service models, with poultry integrators demanding integrated supply contracts and aquaculture specialists requiring marine ingredient technical support.
- Poultry:Broiler and layer formulations optimized for feed conversion ratios in tropical conditions. Central Luzon's contract growing belt concentrates 60% of national feed offtake through integrator-processor captive agreements.
- Swine:Grower-finisher and sow diets with phytase and organic acid inclusions for gut health. African Swine Fever recovery patterns in Batangas and Quezon are rebuilding herd inventories and feed demand.
- Aquaculture:Shrimp and finfish feeds with fish meal dependency and water stability requirements. Mindanao coastal development is expanding addressable market for specialized marine formulations.
- Ruminants:Cattle and dairy concentrates complementing pasture-based systems. Negros Occidental sugarcane belt provides molasses integration opportunities for regional mills.
Poultry leads absolute consumption. Aquaculture is expanding most quickly as export-oriented shrimp farming scales.
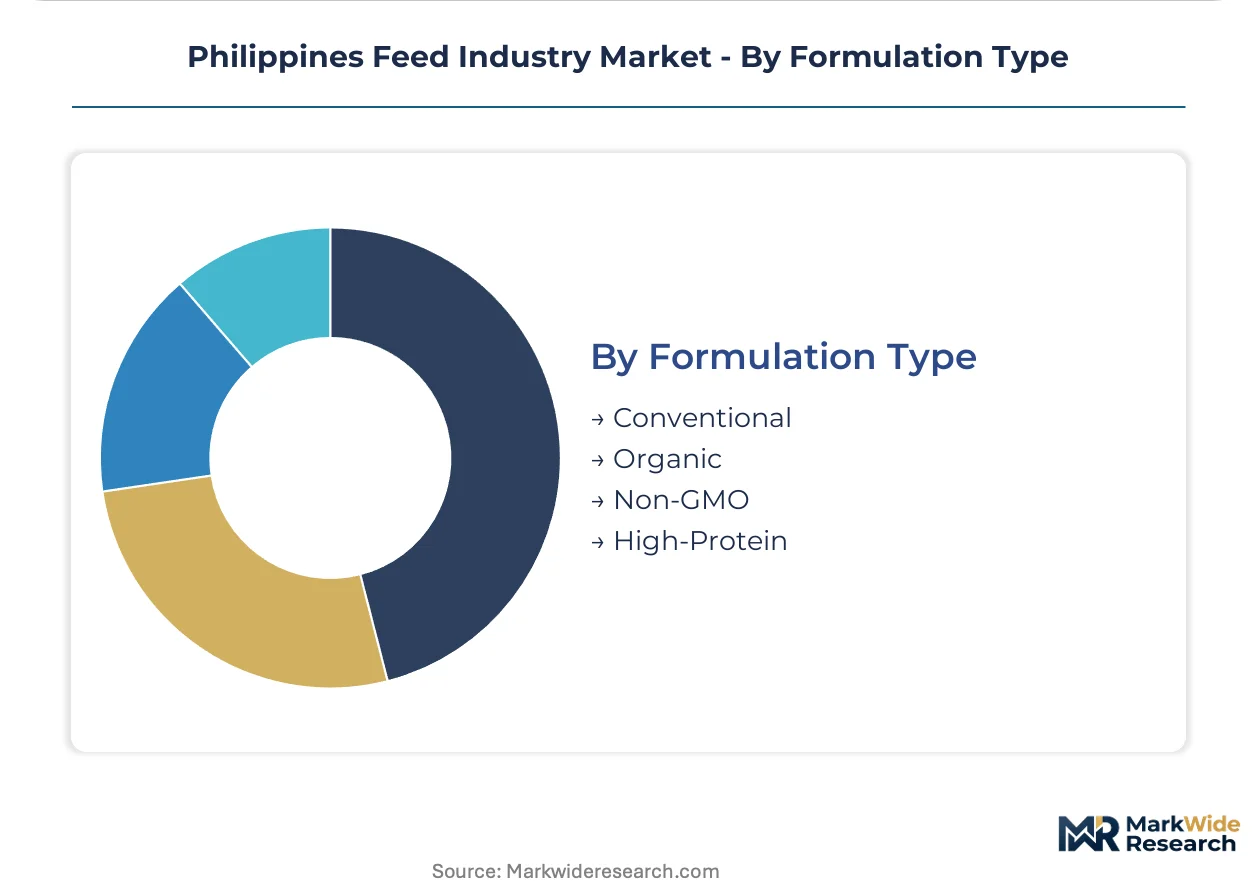
Formulation Type:
Margin differentiation tracks certification complexity, with organic and non-GMO tiers extracting price premiums against conventional commoditized streams.
- Conventional:Standard antibiotic growth promoter formulations transitioning under AO 42 mandates. Reformulation costs and phytogenic additive sourcing are compressing margins for mills without captive R&D.
- Organic:Certified synthetic additive-free rations with traceable ingredient chains. Niche demand from premium retail channel integrators in Cavite and Laguna supports limited production scale.
- Non-GMO:Identity-preserved grain sourcing with PCR testing verification. Feed mills with dedicated handling infrastructure capture segregation premiums from export-oriented poultry processors.
- High-Protein:Elevated amino acid density formulations targeting accelerated weight gain. Independent broiler growers seeking shorter grow-out cycles drive regional demand in Pampanga and Tarlac.
Conventional formulations retain volume dominance. High-Protein is gaining share fastest among independent growers optimizing turnover velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed procurement in the Philippines clusters around integrator-controlled contract growing belts, with buyer archetypes dictating regional supply chain configurations rather than geographic proximity alone.
Central Luzon
Poultry integrators in Bulacan and Pampanga dominate compound feed offtake through captive supply agreements covering 60% of national volume. The Department of Agriculture's AO 42 antibiotic withdrawal mandates are accelerating mill consolidation as smaller players lack reformulation capacity. Tarlac's extrusion facilities are retrofitting precision pelleting lines to serve integrator specifications.
Calabarzon
Swine feed demand in Batangas and Quezon is rebuilding following African Swine Fever herd recovery, with independent growers favoring supplementary feed for cost control. The Bureau of Animal Industry's veterinary prescription requirements for medicated feed constrain distribution to accredited mills. Laguna's premium retail channel integrators are sourcing limited organic certified volumes.
Visayas
Corn supply deficits force Cebu and Iloilo mills to source from Mindanao traders holding BIS-equivalent import accreditations. Digital procurement platforms are disintermediating traditional distributor networks among independent farming communities. Negros Occidental's sugarcane belt offers molasses integration opportunities for regional ruminant feed operations.
Mindanao
Aquaculture feed specialists are establishing coastal distribution networks to serve emerging shrimp farming clusters in underpenetrated provinces. Fish meal price volatility from Peruvian anchovy catch variability transmits directly to processor margins. Davao Gulf finfish operations require water-stable formulations with technical field support.
Philippines Feed Industry Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement relationships. The Philippine feed market exhibits moderate consolidation where three to four integrators command 70% of poultry contract growing volumes while independent mills serve fragmented swine and ruminant segments. Strategic archetypes include captive breeding-to-slaughter integrators, grain-trading backward integrated processors, and marine ingredient aquaculture specialists. Dominant competitive moves involve ERP pre-positioning for pending traceability mandates and cold chain capacity expansion for temperature-sensitive aquaculture formulations.
Within the integrator tier, Charoen Pokphand Foods Philippines Corporation and San Miguel Foods exemplify channel-controlling archetypes through captive supply chain structures. Vitarich occupies a specialist position representing the aquaculture feed segment where marine ingredient sourcing creates distinct margin dynamics. DSM Nutritional Products AG and Alltech, Inc. sit within the inputs tier supplying phytogenic and organic acid additives demanded by AO 42 reformulation requirements.
| Leading Market Players |
|---|
| Charoen Pokphand Foods Philippines Corporation |
| Cargill Incorporated |
| San Miguel Foods (B-meg) |
| Universal Robina Corporation |
| Vitarich |
| Alltech, Inc. |
| Archer Daniel Midland Co. |
| DSM Nutritional Products AG |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Central Luzon's poultry belt concentrates 60% of national feed milling capacity, giving integrators in Bulacan and Pampanga outsized leverage in contract negotiations with regional distributors. This geographic concentration amplifies pricing power for Charoen Pokphand Foods Philippines Corporation and San Miguel Foods, which dictate formulation specifications and volume terms to captive suppliers.
Pricing Analysis
Certification level creates the primary spread between feed tiers, with BIS-equivalent and FSSAI-aligned import protocols commanding premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks ingredient sourcing rigor and after-sales technical support intensity. Pricing pressure stems from AO 42 reformulation costs and fish meal volatility, compressing margins for mills without captive R&D. Independent growers in Visayas exhibit highest price sensitivity, while Central Luzon integrators prioritize conversion ratio performance over unit cost.
Supply Chain Analysis
Charoen Pokphand Foods Philippines Corporation and San Miguel Foods anchor domestic production through captive milling networks, with regional independents filling gaps in Mindanao and Visayas. Raw material procurement draws from Indian soybean meal traders, Peruvian fish meal suppliers, and Mindanao corn aggregators. Supply chain risk centers on El Niño-driven fish meal scarcity and Bureau of Customs inspection bottlenecks for FSSAI-aligned imports. Distribution runs through mill-direct logistics to integrator facilities, bypassing traditional dealer networks in contract growing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines feed industry sits in a livestock cycle recovery phase, with African Swine Fever herd rebuilding and poultry integrator expansion driving input demand normalization.
For Market Incumbents: Harden formulation lock-in through exclusive supply agreements with Central Luzon contract growers facing AO 42 compliance deadlines. Expand backward integration into grain trading and port logistics to neutralize BIS-equivalent import bottlenecks. Prioritize ERP pre-positioning for pending Bureau of Animal Industry traceability mandates that will disqualify smaller competitors. For New Entrants and Emerging Players: Pursue aquaculture feed specialization in Mindanao's underpenetrated coastal provinces, where marine ingredient technical support creates differentiation against commoditized poultry players. Target shrimp farming clusters with water-stable formulations and field-level water quality advisory services. Deploy digital procurement platforms to disintermediate Visayas distributor networks serving independent growers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrators with captive breeding-to-slaughter operations and long-term grower contracts. Long-term viability favors asset-light contract growing models with balance-sheet flexibility to fund facility upgrades. Monitor Bureau of Animal Industry traceability rule implementation timelines as inflection indicator for mill consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Pre-Positioning for Traceability | Captures chain-of-custody data ahead of Bureau of Animal Industry compliance deadlines. |
| Cold Chain Capacity Expansion | Addresses fish meal temperature sensitivity for Mindanao aquaculture distribution networks. |
| Phytogenic Additive Partnerships | Secures DSM Nutritional Products AG and Alltech supply for AO 42 reformulation requirements. |
| Digital Procurement Platform Launch | Disintermediates traditional Visayas dealer networks through direct mill-to-farm ordering. |
| Grain Trading Backward Integration | Neutralizes BIS-equivalent import bottlenecks via San Miguel Foods-style port logistics control. |
Research Methodology
A standing panel of feed mill operations directors, integrator procurement managers, Bureau of Animal Industry regulatory officers, and Indian soybean meal traders provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through customs import records, Department of Agriculture AO 42 implementation circulars, and FSSAI-aligned protocol documentation. Bottom-up volume modeling from individual mill capacities and top-down demand estimation from livestock inventory data were triangulated for convergence.
Scenario-bracketing around fish meal price volatility and AO 42 reformulation cost pass-through generated high-low projections across the analysis window. Segmentation dimensions modeled include product type, ingredient tier, animal category, and regional procurement cluster. CAGRs were derived from trend extrapolation with cross-validation against livestock production forecasts and feed conversion ratio assumptions. Peruvian anchovy catch variability and El Niño cycle intensity served as key external inputs.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates, global grain futures, and marine ingredient spot markets would shift the trajectory. Quarterly review of Bureau of Animal Industry regulatory announcements, Indian monsoon patterns affecting soybean harvests, and Central Luzon contract growing consolidation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Algeria Agriculture Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
Greenhouse Market