
 China Automotive Sunroof Market | 2026-2036
China Automotive Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Sunroof Market Outlook
Multi-source procurement among domestic glass suppliers is expanding as vehicle manufacturers reduce dependency on single foreign vendors. Fuyao Group leverages its integrated float-glass-to-sunroof production chain to anchor pricing power in the premium segment. Webasto Group competes through its established module assembly footprint in southern China. Inalfa Roof Systems Group B.V. specializes in large-format panoramic systems for electric vehicle platforms.
An automotive sunroof is a transparent or opaque panel installed in a vehicle roof, typically constructed from tempered or laminated glass with UV-interlayer films, designed to admit light and ventilation while maintaining structural rigidity per roof crush standards. The assembly integrates sealing systems, drainage channels, and motorized drive mechanisms to enable powered or manual operation. Panoramic sunroof configurations now dominate margin pools as OEMs bundle them with premium interior packages. Power slide technology leads volume penetration among electric vehicle architectures where manual mechanisms face ergonomic constraints. Fixed sunroof variants sustain demand in cost-optimized compact segments where opening functionality adds unacceptable weight and complexity.
MIIT certification requirements for roof opening systems and GB standards for automotive glass safety shape product development timelines and testing expenditures for all market participants. SAMR enforcement of quality consistency protocols limits market access for unqualified component suppliers. Stakeholders must monitor NEV platform architecture shifts, as battery pack placement and cabin thermal management requirements are altering sunroof size and material specifications faster than regulatory cycles can adapt.
Market Dynamics
Panoramic glass configurations are displacing traditional opening sunroofs across China's premium electric vehicle platforms, as battery placement constraints and cabin thermal management requirements reshape supplier engineering priorities.
Growth Catalysts
- MIIT NEV Directives:New energy vehicle mandates prioritize lightweight glazing solutions, accelerating laminated glass adoption for panoramic roof systems.
- Yangtze River Delta Manufacturing:Premium passenger vehicle OEMs in Shanghai and surrounding provinces bundle sunroofs as standard equipment in mid-tier trims.
- Large-Format Panoramic Systems:Electric vehicle architectures favor fixed and tilt-slide configurations that maximize cabin daylight penetration without compromising structural integrity.
Market Restraints
- Float Glass Input Volatility:Energy-intensive silica processing exposes suppliers to electricity cost swings in eastern China manufacturing zones.
- Foreign Vendor Dependency:Precision drive mechanisms and sealing systems remain concentrated among German and Japanese component specialists.
- GB Roof Crush Standards:Stringent safety testing protocols extend product development cycles and raise qualification barriers for new entrants.
Strategic Opportunities
- Chongqing Manufacturing Corridor:Western China vehicle production expansion creates localized demand for integrated sunroof module assembly.
- SAMR Quality Consistency Enforcement:Stricter market access rules favor qualified domestic suppliers with certified testing facilities.
- Photovoltaic Glass Convergence:Transparent solar cell integration with sunroof glazing opens energy-harvesting applications for extended-range electric vehicles.
Industry Challenges
- Polymer Interlayer Certification:UV-blocking film qualification under GB automotive glass standards demands 18-24 month validation timelines.
- Thermal Management Integration:Battery pack proximity to roof structures complicates heat load calculations and climate control system coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Sunroof Market |
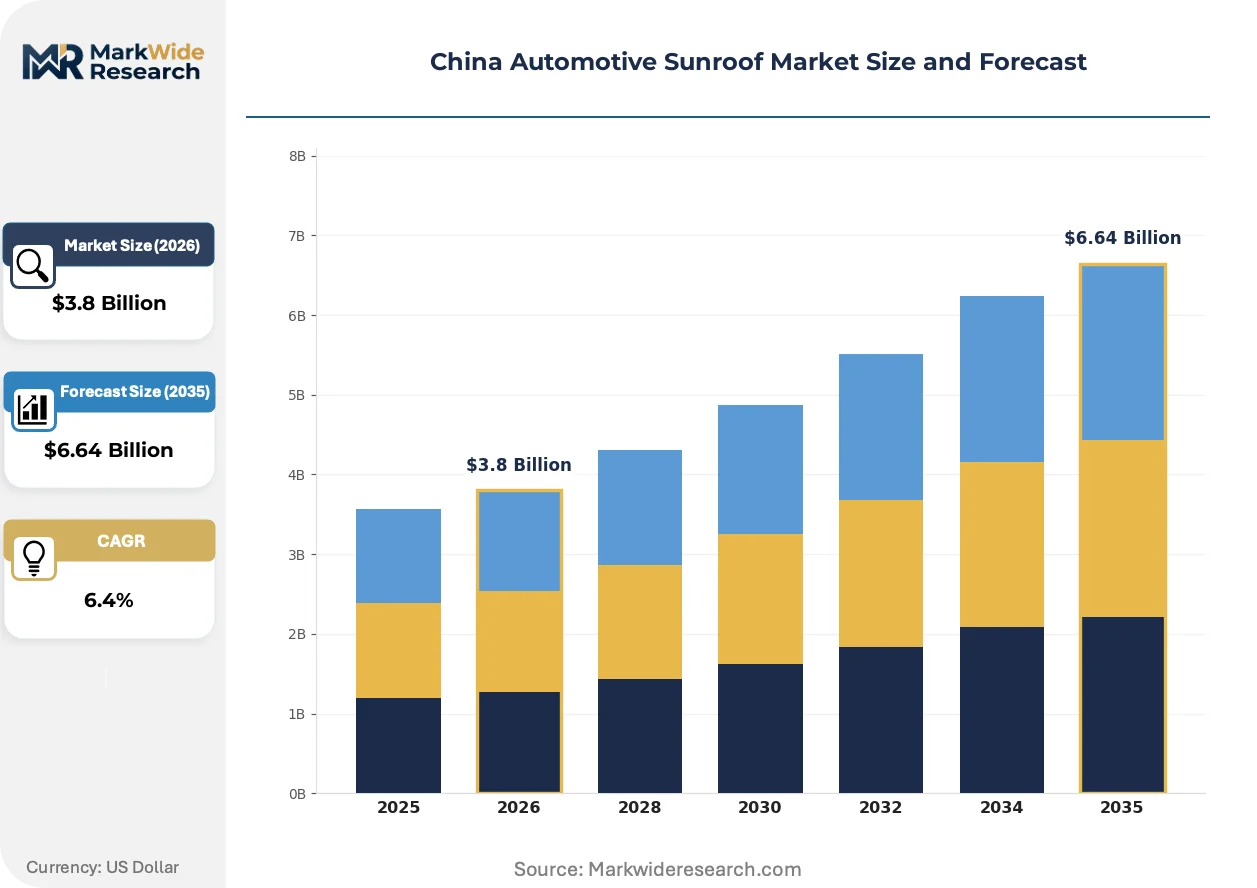
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic Sunroof, Conventional Sunroof, T-Top Sunroof, Fixed Sunroof Technology: Manual Slide, Power Slide, Solar Powered, Tilt End User: OEMs, Aftermarket, Vehicle Manufacturers, Automotive Suppliers Size: Standard Size, Large Size, Compact Size, Custom Size |
| Companies Covered | Fuyao Group, Aisin Seiki Co., Ltd, Webasto Group, CIE Automotive, Yachiyo Industry Co Ltd, Shanghai Mobitech Technology Co., Ltd., Saint-Gobain, Magna International Inc, Inalfa Roof Systems Group B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Sunroof Market Strategic Shifts
Material science advances and regulatory tightening are compressing traditional product lifecycles while opening new specification tiers for integrated roof systems.
Electrochromic dimmable glass is absorbing premium segment share from conventional shade-equipped sunroofs. NEV platforms in the Pearl River Delta specify variable-tint panels that eliminate mechanical roller assemblies. This consolidation is absorbing margin from downstream shade suppliers and simplifying assembly line complexity.
GB standards for automotive glass safety are tightening impact resistance and fragmentation requirements for laminated roof panels. MIIT certification protocols now mandate extended environmental cycling tests for motorized opening mechanisms. Premium electric SUV manufacturers in Guangzhou province are responding by pre-qualifying dual-source glass suppliers to de-risk approval timelines.
Direct OEM-supplier engineering partnerships are replacing tiered distributor networks for panoramic system procurement. Major vehicle manufacturers in Shanghai and Beijing now embed sunroof specialists within platform development teams from concept phase. This disintermediation is most pronounced in dedicated NEV architectures where roof module integration affects battery thermal modeling.
China Automotive Sunroof Market Segmentation
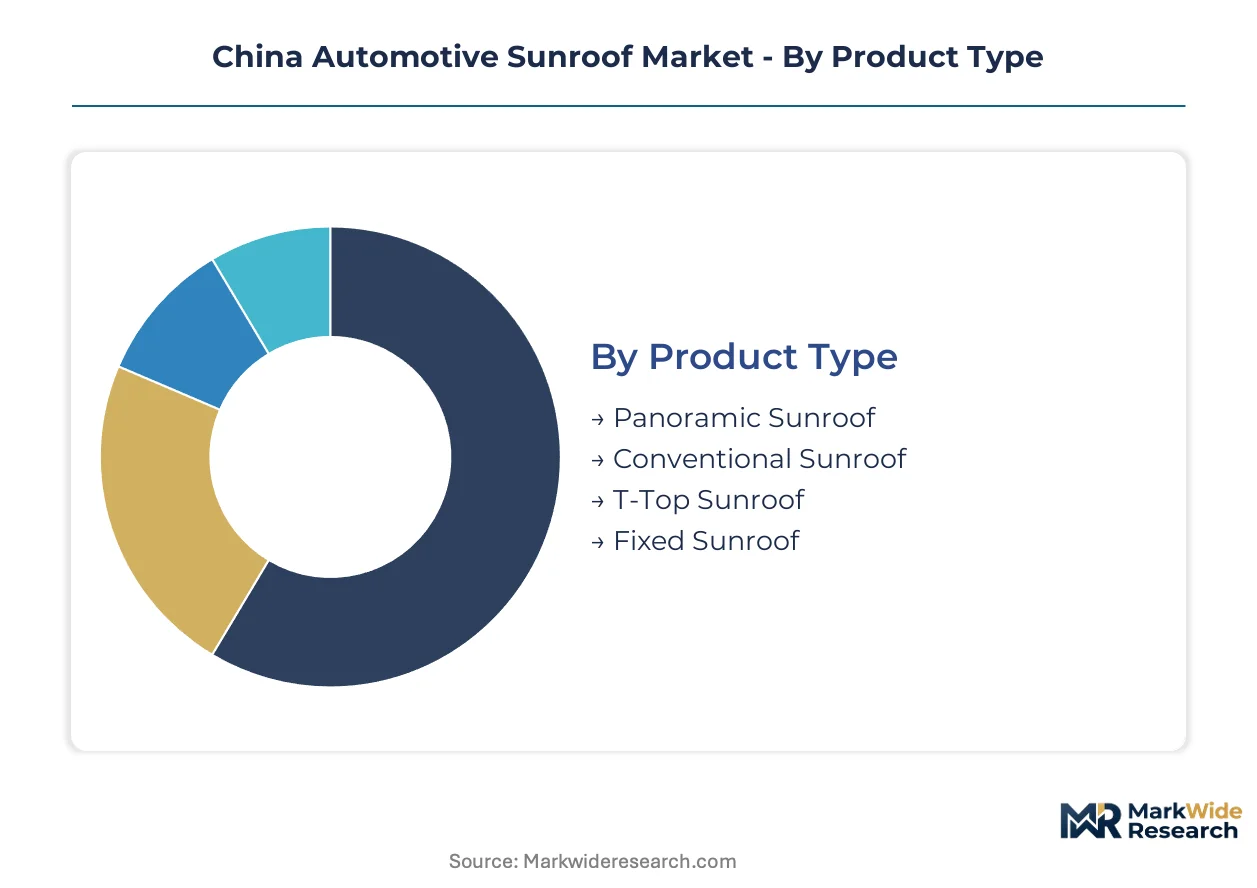
Segmentation in the China automotive sunroof market reveals how battery platform architectures and regional manufacturing clusters reshape specification requirements across product tiers. Understanding these divisions exposes where laminated glass investments concentrate versus where cost-optimized sealing systems suffice.
Product Type:
Standalone panoramic systems dominate premium electric vehicle platforms, while embedded conventional formats sustain volume in internal combustion engine lineups across the Yangtze River Delta.
- Panoramic Sunroof:Large-format laminated glass panels spanning front and rear passenger zones, specified with UV-interlayer films and electrochromic dimming capability. Demand concentrates in Guangzhou province premium electric SUVs where cabin daylight penetration differentiates interior packages against NEV competitors.
- Conventional Sunroof:Compact opening panels with motorized slide or tilt functionality, constructed from tempered glass with integrated drainage channels. Volume placements cluster in Shanghai corridor mid-tier sedans where OEMs bundle sunroofs as standard equipment without panoramic cost premiums.
- T-Top Sunroof:Dual removable glass panels separated by central roof structure, retaining torsional rigidity per GB roof crush standards. Limited adoption in Chongqing sports coupe manufacturing where structural reinforcement adds unacceptable mass to electric architectures.
- Fixed Sunroof:Non-opening transparent panels eliminating motorized mechanisms, specified for cost-optimized compact segments. Favored in western China vehicle production where battery pack proximity complicates opening system thermal management.
Volume placements concentrate in Conventional Sunroof configurations; the faster expansion belongs to Panoramic Sunroof systems.
Technology:
Cost tier stratification separates precision drive mechanisms from manual alternatives, with power-assisted systems capturing margin pools in premium manufacturing corridors.
- Power Slide:Electric motor-driven horizontal opening with anti-pinch sensors and programmable position memory. Dominates Beijing and Shanghai NEV platforms where ergonomic constraints eliminate manual crank mechanisms and MIIT certification mandates extended cycling durability.
- Manual Slide:Mechanical crank or lever operation without electrical integration, specified for entry-level compact vehicles. Sustained demand in cost-optimized western China production where battery range priorities suppress auxiliary electrical load.
- Solar Powered:Photovoltaic cell integration with transparent glazing, generating supplemental charge for extended-range electric vehicle battery systems. Emerging specification in Pearl River Delta manufacturing where transparent solar convergence opens energy-harvesting applications.
- Tilt:Vertical rear-edge ventilation opening with minimal mechanism complexity, bridging fixed and full-slide functionality. Preferred in mid-tier Guangzhou crossovers where partial opening satisfies ventilation requirements without panoramic system cost.
Power Slide mechanisms claim the dominant volume position; Solar Powered technology is climbing the fastest as photovoltaic glass qualification accelerates under MIIT new energy directives.
End User:
Customer type segmentation tracks procurement authority concentration, with direct OEM engineering partnerships displacing tiered distributor networks for panoramic system integration.
- OEMs:Original equipment manufacturers specifying sunroof modules at platform concept phase, embedding suppliers within battery thermal modeling teams. Shanghai and Beijing electric vehicle architects demand direct engineering partnerships for roof-integrated climate control coordination.
- Vehicle Manufacturers:Assembly entities procuring complete sunroof modules for final vehicle integration, concentrated in Yangtze River Delta and Chongqing corridors. These stakeholders drive standardization pressures that compress supplier margins through multi-source procurement mandates.
- Automotive Suppliers:Tier-1 module integrators managing glass, sealing, and mechanism sub-supplier networks. Fuyao Group and Webasto Group compete through captive float-glass supply or established southern China assembly footprints respectively.
- Aftermarket:Post-production installation channels for sunroof retrofits and replacement glass, limited by GB automotive glass safety certification requirements and SAMR quality consistency enforcement that favors qualified domestic testing facilities.
Volume placements concentrate with Vehicle Manufacturers; the steepest expansion trajectory belongs to direct OEM procurement channels.
Size:
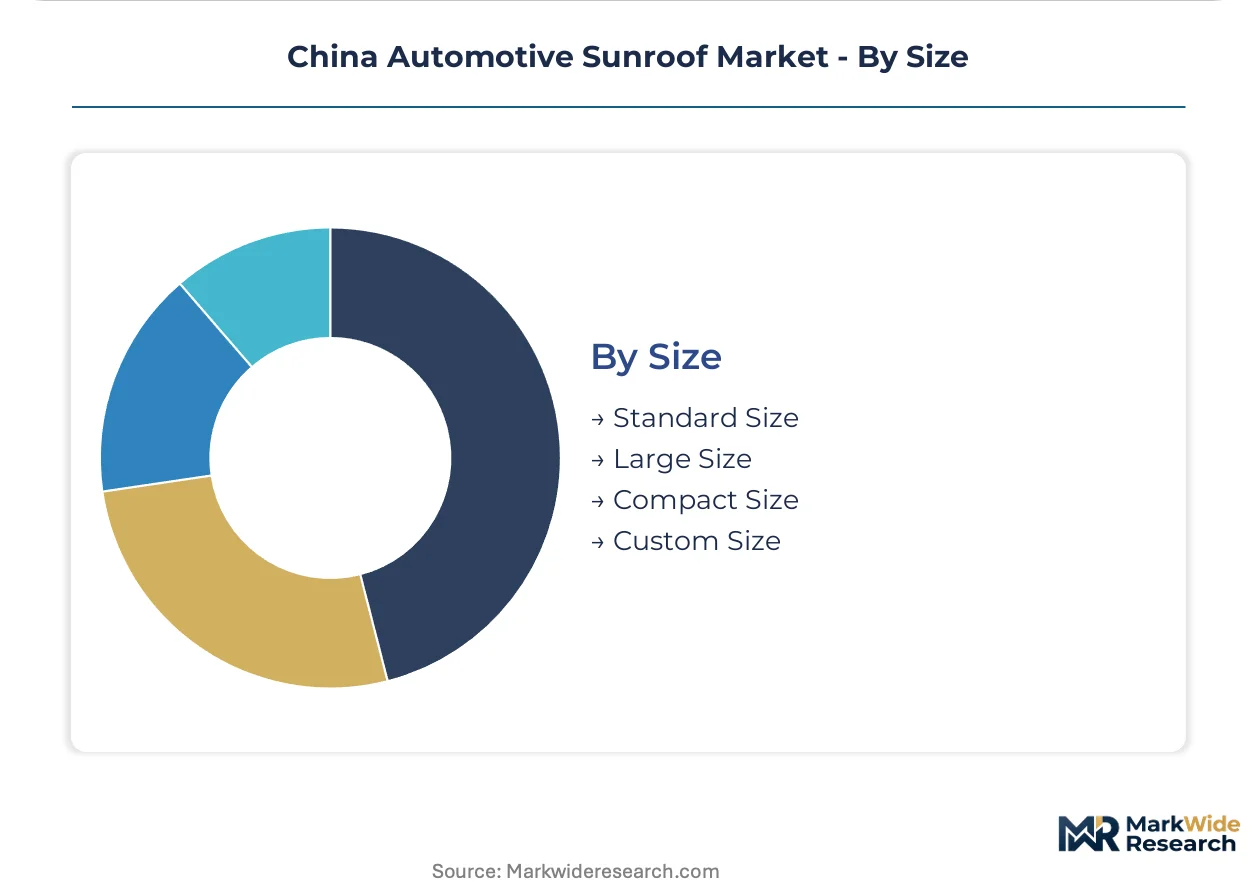
Application-driven dimension requirements split between thermal management constraints in battery-electric platforms and interior packaging flexibility in conventional architectures.
- Large Size:Extended glass panels exceeding 1.2 meters in longitudinal dimension, spanning multiple passenger rows. Specified in premium Pearl River Delta electric SUVs where panoramic daylight penetration anchors interior luxury positioning.
- Standard Size:Conventional front-seat opening dimensions compatible with majority sedan and crossover roof structures. Dominates Shanghai corridor mid-tier production where platform sharing across multiple nameplates demands dimensional consistency.
- Compact Size:Reduced-diameter panels for A-segment and B-segment vehicles, minimizing weight and structural reinforcement requirements. Sustained demand in western China small vehicle manufacturing where cost optimization suppresses feature content.
- Custom Size:Bespoke dimensions for specialty vehicle architectures, low-volume premium nameplates, or concept-to-production transitions. Concentrated in Beijing design studios where NEV platform differentiation drives non-standard roof module development.
Standard Size configurations retain the dominant volume position; Custom Size specifications are gaining share fastest as dedicated NEV architectures proliferate beyond shared platform constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in eastern Shandong Province anchor China's automotive glass supply chain, with float-glass production clustering along the Bohai Rim and Yangtze River Delta corridors. These mineral localities determine where sunroof module assembly concentrates and which manufacturing zones absorb premium specification demand.
Yangtze River Delta
Shanghai-based premium passenger vehicle OEMs bundle panoramic sunroofs as standard equipment across mid-tier sedan and SUV nameplates. MIIT new energy vehicle directives prioritize lightweight glazing solutions, accelerating laminated glass adoption for large-format roof systems. Manufacturing activity concentrates in Shanghai and surrounding Jiangsu and Zhejiang provinces where Fuyao Group maintains integrated float-glass-to-sunroof production facilities.
Pearl River Delta
Guangzhou province electric SUV manufacturers specify electrochromic dimmable glass panels to differentiate interior luxury positioning against NEV competitors. GB standards for automotive glass safety tighten impact resistance requirements for laminated roof panels, extending qualification timelines for new suppliers. Design studios in Shenzhen and Guangzhou embed sunroof specialists within battery thermal modeling teams from platform concept phase.
Sichuan-Chongqing Corridor
Western China vehicle production expansion creates localized demand for integrated sunroof module assembly serving cost-optimized compact segments. SAMR quality consistency enforcement limits market access for unqualified component suppliers, favoring domestic testing facilities with certified GB compliance. Chongqing manufacturing clusters favor fixed sunroof variants where battery pack proximity complicates opening system thermal management.
Beijing-Tianjin-Hebei
Beijing electric vehicle architects demand direct engineering partnerships with glass suppliers for roof-integrated climate control coordination. NMPA and MIIT certification protocols mandate extended environmental cycling tests for motorized opening mechanisms. Premium NEV platforms in the capital region pre-qualify dual-source glass suppliers to de-risk approval timelines under tightening regulatory scrutiny.
Shandong Peninsula
Bohai Rim float-glass production anchors raw material supply for tempered and laminated sunroof panels serving northern China assembly plants. Energy-intensive silica processing exposes suppliers to electricity cost swings, compressing margins for independent fabricators without captive energy supply. Qingdao and Yantai manufacturing zones supply standard-size conventional sunroof configurations to mid-tier vehicle producers across the Beijing-Tianjin corridor.
China Automotive Sunroof Market Competitive Environment
Capacity expansion dominates the current landscape as domestic suppliers build certified testing facilities to capture share from foreign component specialists. The vendor base stratifies across three tiers: integrated glass-to-module producers with captive float-glass supply, module assemblers sourcing laminated panels from third-party fabricators, and precision mechanism specialists concentrated among German and Japanese component houses. Two strategic archetypes define competitive positioning: backward-integrated glass producers leveraging upstream control over raw material quality, and technology licensors partnering with domestic fabricators to circumvent GB qualification barriers. Geographic expansion into western China manufacturing corridors and strategic partnerships for photovoltaic glass convergence represent the dominant competitive moves.
Among integrated producers, Fuyao Group exemplifies the backward-integrated archetype with in-house float-glass production chains. Webasto Group occupies a position as the established module assembly specialist with southern China manufacturing footprints. Inalfa Roof Systems Group B.V. represents the large-format panoramic technology tier, anchoring premium electric vehicle platform specifications. These three companies illustrate how competitive positioning stratifies across raw material control, regional assembly presence, and specialized NEV architecture alignment.
| Leading Market Players |
|---|
| Fuyao Group |
| Aisin Seiki Co., Ltd |
| Webasto Group |
| CIE Automotive |
| Yachiyo Industry Co Ltd |
| Shanghai Mobitech Technology Co., Ltd. |
| Saint-Gobain |
| Magna International Inc |
| Inalfa Roof Systems Group B.V. |
| Others |
Value Chain & Pricing Dynamics
Family-controlled glass conglomerates with captive float-glass production anchor supply discipline in China's automotive sunroof market, translating upstream silica processing control into pricing power against module assemblers lacking backward integration. Their ownership structure insulates capacity decisions from short-term margin pressure, stabilizing contract terms for Yangtze River Delta OEMs even as electricity cost volatility squeezes independent fabricators.
Pricing Analysis
Warranty bundling separates premium panoramic suppliers from commodity players, with electrochromic dimming functionality and extended cycling guarantees commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on MIIT certification status and UV-interlayer film qualification grade, with SAMR-registered testing facilities extracting brand premiums. Cost compression in conventional tempered-glass segments is intensifying because multi-source procurement mandates from Shanghai corridor OEMs force mechanism suppliers to absorb logistics premiums. Aftermarket channels exhibit highest price sensitivity due to GB glass safety compliance burdens, while Beijing-Tianjin NEV architects show lowest sensitivity for roof-integrated climate control coordination.
Supply Chain Analysis
Refurbishment flows for motorized drive mechanisms remain underdeveloped, with precision component specialists in Germany and Japan controlling reverse logistics for warranty claims rather than domestic remanufacturing. Geographic supply concentration centers on China for float-glass production, South Korea for polymer interlayer films, and Japan for anti-pinch sensor modules. Raw material dependencies draw from Shandong Province silica deposits, Malaysian tin oxide for electrochromic coatings, and Saudi petrochemical feedstock for sealing polymers. Single-source vulnerability in precision drive mechanisms exposes assemblers to qualification timeline risks. Distribution runs through direct OEM engineering partnerships for panoramic systems, bypassing tiered distributor networks that still handle conventional sunroof replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China automotive sunroof market functions as a vertical-integration race where captive float-glass supply determines margin survival, with Fuyao Group's upstream control forcing competitors to secure equivalent raw material leverage or accept supplier pricing terms.
For Market Incumbents: Deepen backward integration into polymer interlayer production to offset Japanese chemical specialist dependency, while expanding certified testing facility capacity in Chongqing to capture western China NEV platform demand. Defensive moves must address photovoltaic glass convergence threats from Pearl River Delta design studios embedding transparent solar cells into roof thermal modeling. For New Entrants and Emerging Players: SAMR quality consistency enforcement in Sichuan-Chongqing opens a window for domestic fabricators with GB-compliant testing infrastructure to displace unqualified component suppliers. White-space targets include fixed sunroof variants for cost-optimized compact segments and solar-powered mechanisms for extended-range electric vehicles. Go-to-market positioning should emphasize direct OEM engineering partnerships from platform concept phase, mirroring Beijing-Tianjin procurement patterns. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap module assemblers with southern China manufacturing footprints and pending MIIT certification timelines, particularly those caught between float-glass input volatility and OEM price pressure. Long-term viability over a multi-year horizon rests on photovoltaic glass convergence readiness and electrochromic dimming technology access. Watch NEV platform architecture shifts altering roof thermal management specifications as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float-Glass Production | Fuyao Group's captive Shandong silica processing eliminates raw material price exposure for Yangtze River Delta OEM contracts. |
| Photovoltaic Glass Convergence Partnership | Transparent solar cell integration with MIIT-certified glazing opens energy-harvesting specifications for Pearl River Delta electric SUVs. |
| Dual-Source Supplier Pre-Qualification | Beijing-Tianjin NEV architects de-risk GB approval timelines by embedding second-qualified glass fabricators within platform teams. |
| Chongqing Manufacturing Footprint Expansion | Western China vehicle production growth creates localized module assembly demand beyond Yangtze River Delta concentration. |
| Electrochromic Dimming Technology Licensing | Shenzhen design studios specify variable-tint panels eliminating mechanical shade assemblies and absorbing downstream supplier margin. |
Study Parameters
Multi-period observation of NEV platform architecture shifts, GB standard revision timelines, and MIIT certification queue lengths anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement directors, SAMR compliance officers, float-glass plant managers, and aftermarket distribution channel heads. Secondary validation drew from MIIT new energy vehicle directive filings, GB automotive glass safety standard drafts, vehicle production databases, and customs records tracking silica sand and polymer interlayer imports. Bottom-up assembly cost modeling triangulated against top-down market sizing across panoramic and conventional product configurations.
Segment-weighting approaches distributed value projections across product type, technology mechanism, end-user procurement channel, and dimensional specification tiers, with particular attention to battery-electric versus internal combustion engine platform content differences. CAGRs were derived from installed base growth trajectories and replacement cycle assumptions throughout the forecast period. Industry-specific inputs included OEM sunroof penetration rates by vehicle class and regional manufacturing cluster capacity utilization patterns.
The model assumes a particular technology adoption path; alternative pathways for photovoltaic glass integration or electrochromic dimming cost reduction would alter the outlook for conventional shade-equipped sunroof demand. Forecasts reflect assumptions regarding MIIT enforcement consistency and GB standard implementation timelines. Practitioners should monitor NEV thermal management specification changes and polymer interlayer qualification queue lengths for early signals of supply constraint or demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market