
 Automotive Baggage Handling System Market | 2026-2036
Automotive Baggage Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Baggage Handling System Market Outlook
Mechatronics engineering talent is bifurcating the competitive landscape, with Asian suppliers capturing graduates faster than European peers. Daifuku Co., Ltd. leverages its Osaka R&D campus to sustain robotics integration leadership. BEUMER Group anchors its position through captive manufacturing of modular conveyor components. Siemens competes by extending its digital twin software into baggage handling simulation environments.
An automotive baggage handling system comprises motorized conveyor networks, sortation mechanisms, and tracking interfaces designed to transport components, tool kits, and finished assemblies through manufacturing and distribution facilities. These systems typically operate at belt speeds of 0.5 to 2.5 meters per second with payload capacities exceeding 50 kilograms per linear meter, ensuring synchronized flow between paint shops, assembly lines, and outbound logistics docks. Conveyor Systems dominate installed base value due to their ubiquity across body-in-white and final assembly operations, while Sortation Systems capture expanding share as mixed-model production intensifies. RFID technology leads authentication throughput, though IoT Sensors represent the fastest-expanding technology segment as predictive maintenance contracts proliferate among German and Japanese OEM suppliers.
NHTSA guidelines on automated vehicle operation in plant environments and OSHA ergonomic mandates for manual lifting thresholds directly shape system specifications and retrofit timelines. The EU Green Deal's embodied carbon requirements for industrial equipment are tightening material sourcing rules for conveyor belt polymers and steel framing. Stakeholders must monitor how EPA power-factor regulations and emerging ISO energy-efficiency certifications for material handling equipment reshape total cost-of-ownership calculations and supplier qualification criteria.
Market Dynamics
Electrification of conveyor networks under EPA power-factor regulations is compressing retrofit timelines across automotive assembly plants, forcing OEMs to phase out pneumatic systems before end-of-life cycles conclude.
Growth Catalysts
- OSHA ergonomic mandates:Manual lifting thresholds in US manufacturing facilities are accelerating automated baggage handling deployment in final assembly zones.
- RFID authentication throughput:Component tracking accuracy requirements are pulling investment into integrated sensor-conveyor architectures.
- Stuttgart-Wolfsburg corridor concentration:German OEM supplier density is creating localized demand clusters for high-speed sortation systems.
Market Restraints
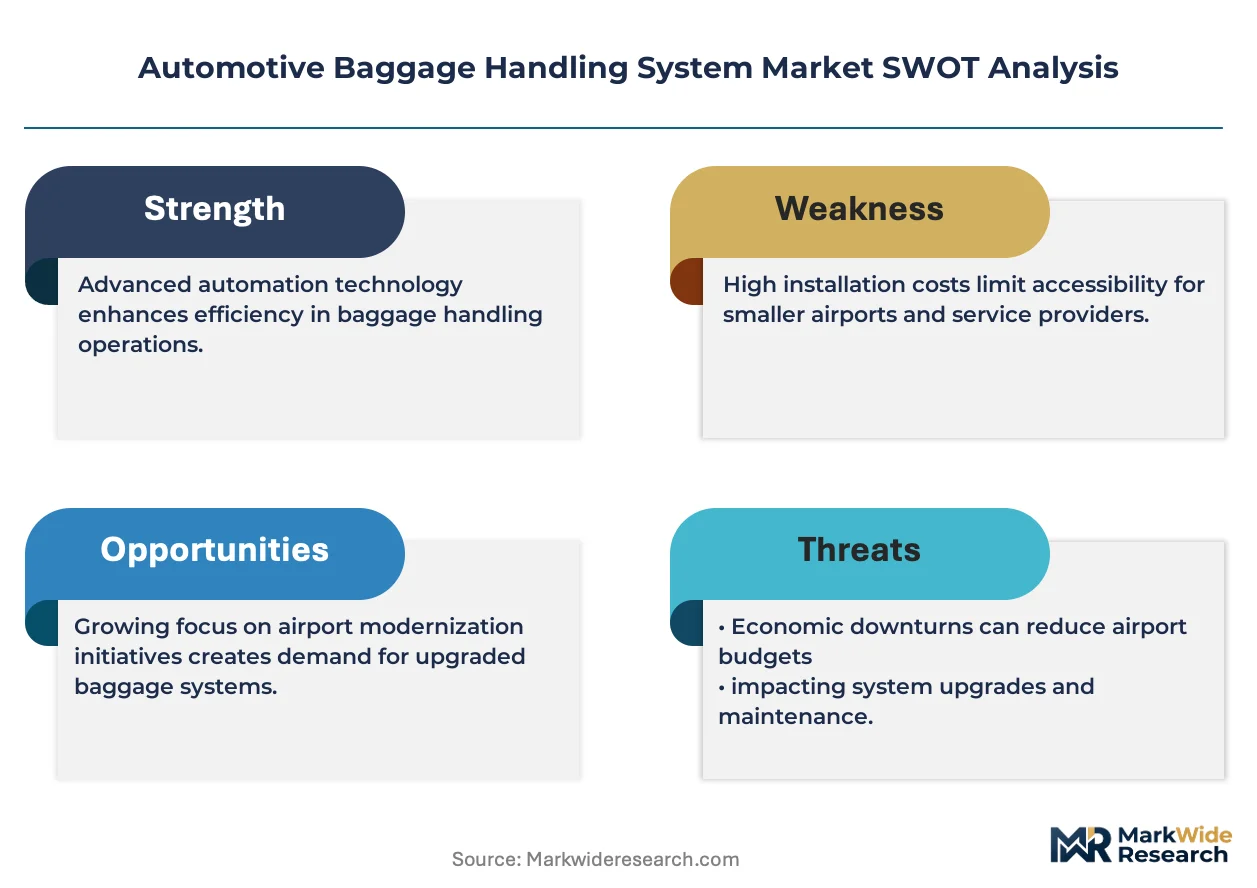
- Steel framing cost volatility:EU Green Deal embodied carbon rules are tightening polymer and metal sourcing, inflating raw material input expenses.
- Mechatronics talent scarcity:Asian suppliers are capturing engineering graduates faster than European peers, constraining R&D velocity in Western markets.
- Pneumatic system residual base:Existing compressed-air infrastructure represents sunk capital that delays full electrification transitions.
Strategic Opportunities
- IoT sensor predictive maintenance:Japanese and German OEM suppliers are expanding service-contract revenue streams through real-time conveyor monitoring.
- Digital twin simulation:Software-based baggage handling validation is opening new revenue channels for automation integrators.
- Modular conveyor component standardization:Captive manufacturing of interchangeable subsystems is reducing field installation labor requirements.
Industry Challenges
- ISO energy-efficiency certification timelines:Equipment qualification criteria are extending supplier approval cycles by multiple quarters.
- Legacy system integration friction:Mixed-model production lines require retrofitting tracking interfaces onto decades-old conveyor foundations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Baggage Handling System Market |
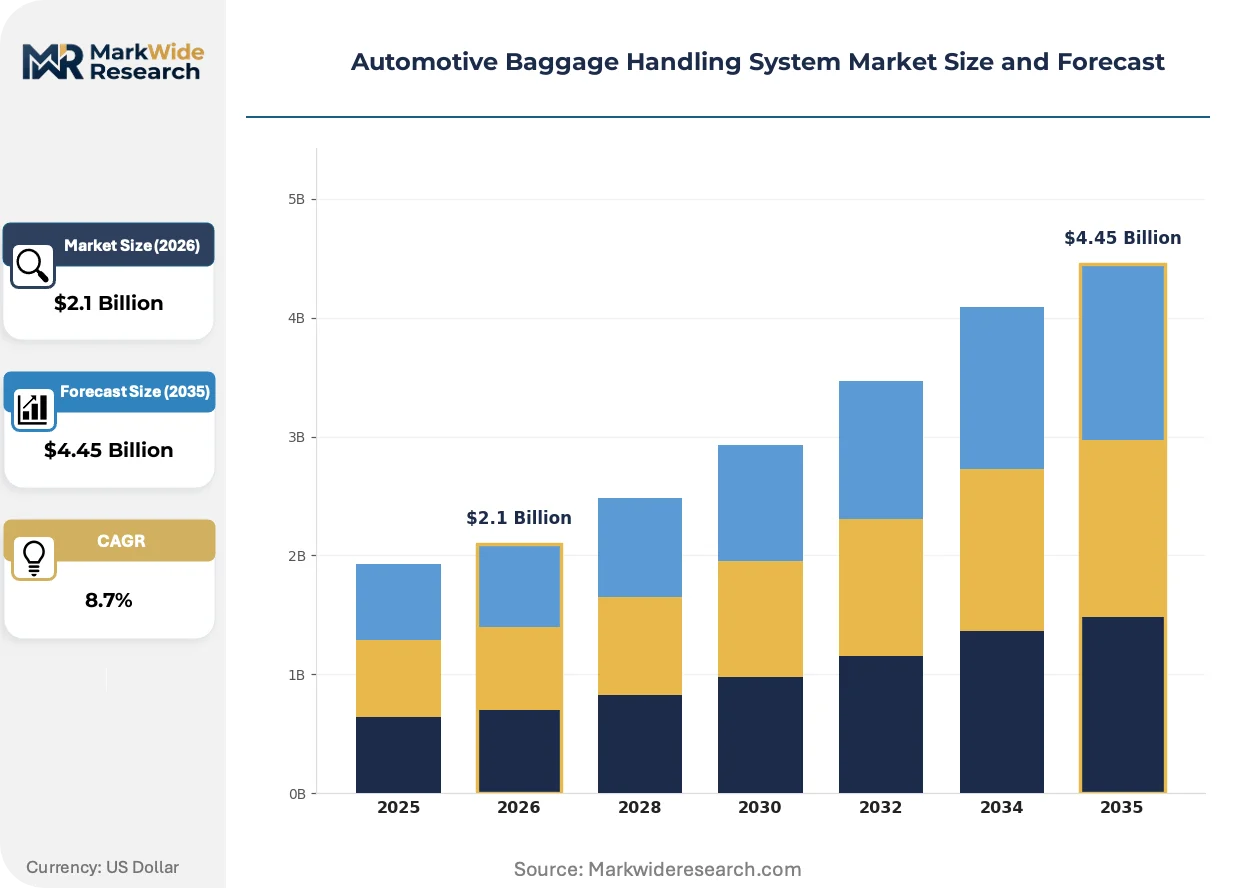
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, Sortation Systems, Auto-Tagging Systems, Tracking Solutions Technology: RFID, Barcode Scanning, IoT Sensors, Automated Guided Vehicles End User: Airports, Airlines, Handling Service Providers, Logistics Companies Installation: New Installations, Upgrades, Maintenance Services, Retrofits |
| Companies Covered | Vanderlande Industries B.V., Daifuku Co., Ltd., BEUMER Group, Siemens, Pteris Global Limited, Fives Group, G&S Airport Conveyor, Logplan, Grenzebach Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Baggage Handling System Market Strategic Shifts
Automation architectures are converging with embedded intelligence layers, compressing the gap between mechanical conveyance and autonomous decision-making in automotive logistics environments.
IoT sensor arrays are miniaturizing. These devices embed vibration, temperature, and current-draw monitoring directly into conveyor roller housings. Tier-1 automotive suppliers in Germany and Japan are deploying them at scale across paint shop and body-in-white lines. The technology is miniaturizing maintenance windows from scheduled intervals to condition-triggered interventions.
REACH polymer restrictions are tightening conveyor belt composition rules. The regulation is forcing reformulation of PVC and polyurethane compounds used in high-friction zones. German system integrators are accelerating qualification of bio-based elastomer alternatives ahead of 2027 compliance deadlines.
Buyer contracting patterns are compressing from capital purchase to performance-based service agreements. Automotive OEMs in Japan are shifting from equipment ownership to throughput-guaranteed subscriptions. This restructures supplier cash flows from upfront recognition to recurring revenue streams concentrated in mixed-model assembly facilities.
Automotive Baggage Handling System Market Segmentation
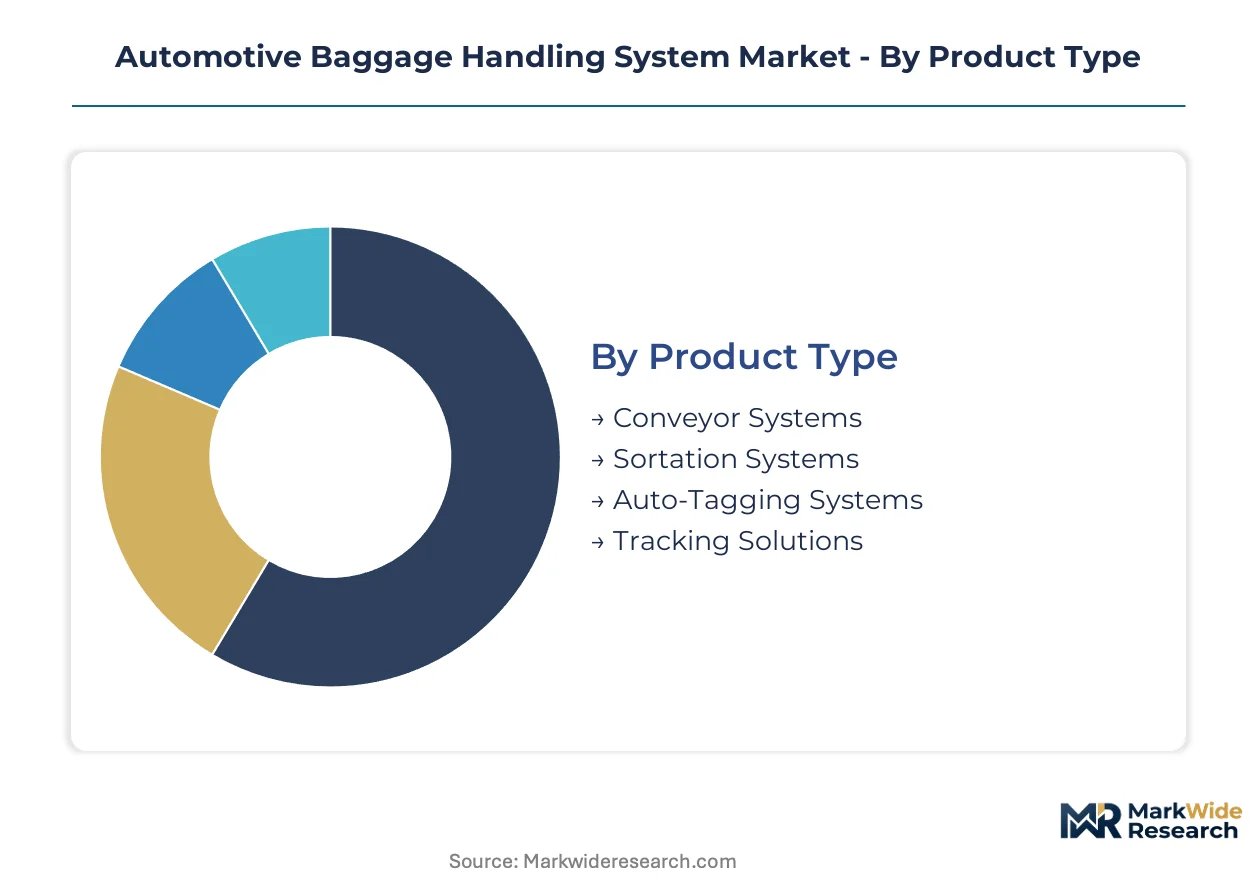
Segmentation in automotive baggage handling reveals how capital deployment splits between foundational infrastructure and intelligence layers. OEM procurement patterns favor integrated solutions that compress installation timelines while expanding real-time visibility into component flow.
Product Type:
Margin pools concentrate in sortation and tracking technologies where software integration commands premium pricing over mechanical-only conveyance.
- Conveyor Systems:Motorized belt networks transport components at 0.5 to 2.5 meters per second with payload capacities exceeding 50 kilograms per linear meter. German OEMs around Stuttgart and Wolfsburg specify these for body-in-white and final assembly synchronization under EPA electrification mandates.
- Sortation Systems:Diverter mechanisms and high-speed pushers route mixed-model components to designated assembly stations. Japanese OEM suppliers are deploying these at scale as production lines flex between electric and combustion vehicle variants.
- Auto-Tagging Systems:Automated label application equipment integrates with upstream ERP systems to maintain component genealogy records.
- Tracking Solutions:Software platforms aggregate sensor data into location-aware dashboards for plant logistics managers.
Conveyor Systems hold installed capacity. Sortation Systems is rotating up the share rankings.
Technology:
Technology selection tracks the shift from periodic authentication to continuous condition monitoring across automotive assembly environments.
- RFID:Passive and active radio-frequency tags authenticate component batches at conveyor transition points. German and Japanese OEM suppliers prioritize this technology for its reliability in paint shop environments where optical methods degrade.
- IoT Sensors:Embedded vibration, temperature, and current-draw monitors in roller housings enable predictive maintenance contracts. Tier-1 suppliers in Japan are expanding service-based revenue through real-time conveyor health monitoring.
- Barcode Scanning:Laser and camera-based linear code readers provide cost-effective tracking for low-velocity assembly zones.
- Automated Guided Vehicles:Battery-powered mobile robots supplement fixed conveyor infrastructure in reconfigurable assembly layouts.
RFID dominates authentication throughput. IoT Sensors is climbing the fastest as predictive maintenance contracts proliferate.
End User:
End user segmentation reflects divergent procurement authority between asset-owning OEMs and contracted service operators.
- Handling Service Providers:Third-party logistics contractors manage component receiving and sequencing for multiple OEMs from shared facilities. These operators standardize on modular conveyor architectures to reconfigure lines between contracts.
- Logistics Companies:Dedicated automotive freight specialists invest in tracking solutions that bridge plant inbound docks with supplier outbound operations.
- Airports:Commercial aviation ground handling operations deploy baggage systems with specifications overlapping automotive material handling.
- Airlines:Carrier-owned ground operations maintain captive maintenance capabilities for conveyor infrastructure.
Handling Service Providers concentrate procurement volume. Logistics Companies is gaining share fastest through integrated supply chain contracts.
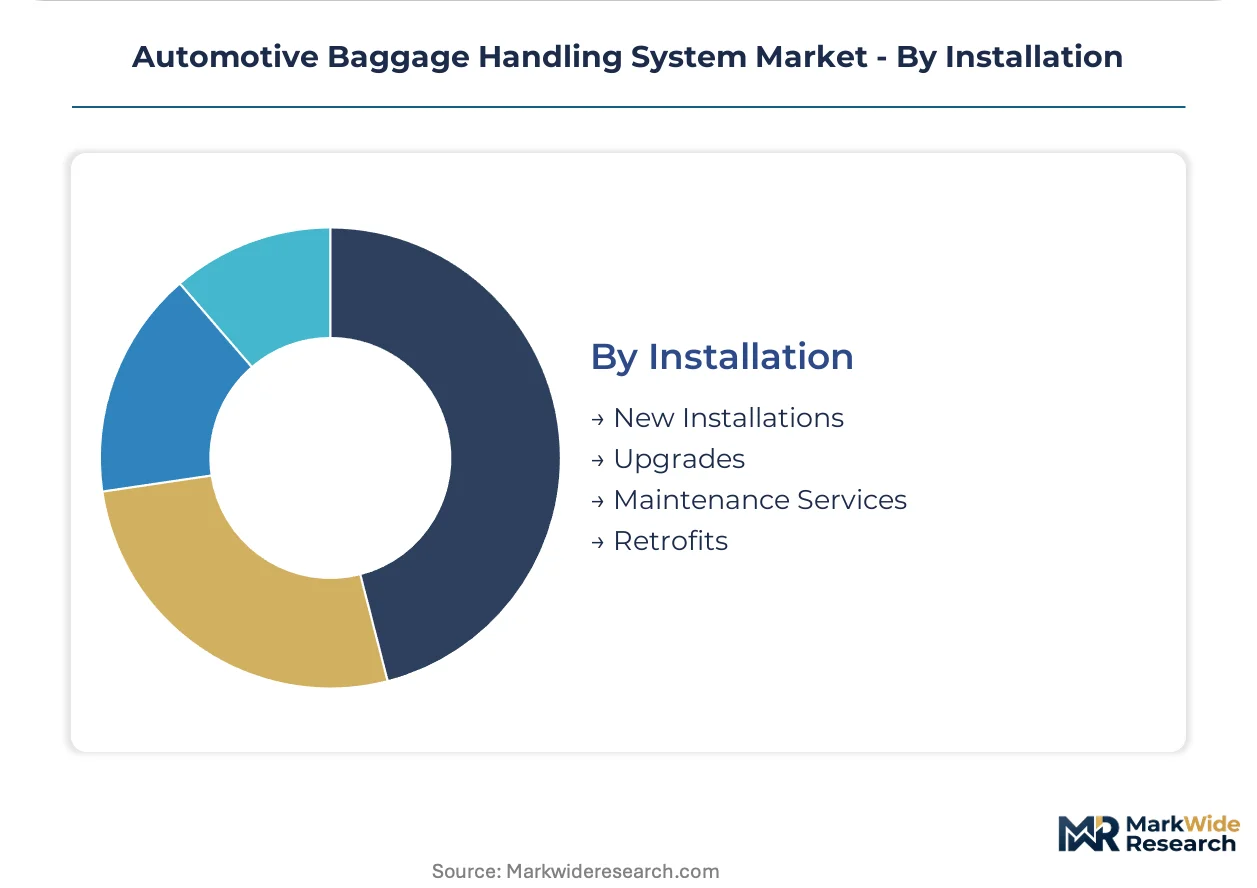
Installation:
Installation type segmentation captures the retrofit imperative driven by EPA power-factor regulations and OSHA ergonomic mandates.
- Upgrades:Control system replacements and belt material swaps to meet EU Green Deal embodied carbon requirements for conveyor polymers. German system integrators are accelerating bio-based elastomer qualifications ahead of compliance deadlines.
- Retrofits:Pneumatic-to-electric conversions forced by EPA regulations before end-of-life cycles conclude. US assembly plants face compressed timelines to phase out compressed-air infrastructure.
- New Installations:Greenfield conveyor networks in expanded or relocated assembly facilities.
- Maintenance Services:Scheduled and condition-based upkeep contracts preserving system availability guarantees.
Upgrades holds current deployment volume. Retrofits is expanding most quickly under regulatory compression timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA power-factor regulations and OSHA ergonomic mandates anchor United States demand, while EU Green Deal embodied carbon rules and Japan's METI efficiency standards shape investment patterns across major automotive manufacturing corridors.
United States
OSHA lifting thresholds and EPA electrification mandates are accelerating pneumatic-to-electric retrofits across Michigan and Ohio assembly plants. Tier-1 suppliers face compressed timelines to phase out compressed-air infrastructure before regulatory deadlines. Detroit-Windsor corridor facilities concentrate procurement of high-capacity conveyor networks for body-in-white synchronization.
Germany
EU Green Deal polymer sourcing restrictions and REACH compliance deadlines are reformulating conveyor belt compositions for Stuttgart and Wolfsburg OEM clusters. KBA vehicle safety standards intersect with ECHA chemical regulations to tighten equipment qualification protocols. Baden-Württemberg system integrators are accelerating bio-based elastomer testing ahead of 2027 compliance windows.
Japan
METI industrial efficiency benchmarks and JIS certification requirements are pulling investment into predictive maintenance architectures across Toyota City and Nagoya production zones. Tier-1 suppliers are expanding IoT sensor deployments under performance-based service contracts. Kansai region manufacturers concentrate mechatronics R&D for mixed-model sortation systems.
China
MIIT smart manufacturing directives and dual carbon targets are electrifying conveyor networks across Yangtze River Delta automotive hubs. GB standards for industrial equipment energy efficiency are reshaping supplier qualification criteria. Shanghai-Suzhou corridor facilities are deploying high-speed sortation for electric vehicle assembly flexibility.
South Korea
MFDS-equipment safety alignment and national carbon neutrality targets are driving conveyor electrification across Ulsan and Gwangju automotive complexes. Government R&D subsidies for smart factory technologies are accelerating IoT sensor integration. Seoul Capital Area suppliers concentrate digital twin software development for baggage handling simulation.
Automotive Baggage Handling System Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the automotive baggage handling system market. Japanese and European specialists dominate robotics integration and digital twin software, while Chinese and Korean fabricators compete on modular component manufacturing. The structure fragments across three strategic archetypes: integrated automation conglomerates, captive conveyor manufacturers, and software-centric system integrators. M&A activity concentrates on predictive maintenance capabilities, while geographic expansion targets German and Japanese OEM supplier networks.
Among integrated automation conglomerates, Daifuku Co., Ltd. and Siemens exemplify divergent strategic positions. Daifuku occupies the robotics-meets-conveyance intersection through its Osaka-based engineering heritage. Siemens anchors the digital twin software layer, extending industrial automation platforms into baggage handling simulation environments. BEUMER Group represents the captive manufacturing archetype, controlling modular component production to compress field installation timelines.
| Leading Market Players |
|---|
| Vanderlande Industries B.V. |
| Daifuku Co., Ltd. |
| BEUMER Group |
| Siemens |
| Pteris Global Limited |
| Fives Group |
| G&S Airport Conveyor |
| Logplan |
| Grenzebach Group |
| Others |
Value Chain & Pricing Dynamics
ISO energy-efficiency certification timelines gate both supplier qualification and price differentiation simultaneously, compressing approval cycles while stratifying vendors into certified-premium and uncertified-standard tiers. Buyers in the Stuttgart-Wolfsburg corridor increasingly demand documented compliance as a non-negotiable entry threshold, forcing tier-2 fabricators to absorb qualification costs or exit procurement pools.
Pricing Analysis
Japanese OEM suppliers command 15-25% premiums over Chinese fabricators for equivalent conveyor capacity. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in the standard tier intensifies because steel framing volatility and REACH polymer reformulation squeeze margins. Handling Service Providers exhibit highest price sensitivity due to contract renegotiation cycles, while captive OEM procurement teams prioritize availability guarantees over unit cost.
Supply Chain Analysis
Germany and Japan anchor precision conveyor component fabrication, while China concentrates modular belt and roller housing production. Raw material dependencies span specialty steel alloys from South Korea, bio-based elastomers under EU Green Deal qualification, and rare-earth magnets for motorized drive units. Single-source vulnerability concentrates in certified polymer formulations meeting REACH 2027 deadlines. Distribution runs through Tier-1 system integrators who bundle mechanical, sensor, and software layers for turnkey deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA power-factor mandates and OSHA ergonomic thresholds constitute a dual regulatory inflection, accelerating electrification retrofits while compressing supplier consolidation windows. This disruption creates asymmetric opportunity for positioned players.
For Market Incumbents: Shield installed base relationships through captive predictive maintenance contracts that embed IoT sensor arrays. Deepen backward integration into bio-based elastomer production ahead of REACH compliance deadlines. Daifuku and BEUMER Group archetypes leverage Osaka and Beckum engineering footprints to outpace Asian competitors on mechatronics talent retention.
For New Entrants and Emerging Players: Predictive maintenance service-layer gaps in US Midwest assembly plants offer white-space entry where incumbent coverage remains thin. Target retrofits segment in Michigan-Ohio corridor where compressed EPA timelines outstrip incumbent installation capacity. Pursue OEM direct contracting rather than Tier-1 subcontractor channels to capture margin pool compression.
For Investors and Strategic Acquirers: EU Green Deal 2027 compliance milestones reshape the acquisition landscape toward certified-component specialists with validated bio-based polymer supply chains. Five-to-ten year viability favors captive manufacturers with modular standardization capabilities over pure-play software integrators. Monitor EPA enforcement intensity signals as inflection indicator for retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Expansion | Japanese OEM suppliers convert capital sales to recurring revenue under METI efficiency benchmarks. |
| Bio-Based Elastomer Qualification | Baden-Württemberg integrators secure REACH 2027 compliance ahead of ECHA enforcement windows. |
| Digital Twin Software Integration | Siemens extends industrial automation platforms into baggage handling simulation environments. |
| Modular Component Standardization | BEUMER Group compresses field installation timelines through captive manufacturing control. |
| Pneumatic-to-Electric Retrofit Acceleration | US assembly plants phase out compressed-air infrastructure under EPA power-factor mandates. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket service heads, and plant maintenance directors anchored the qualitative base. Primary interview findings triangulated against customs trade data, SEC equipment supplier filings, vehicle production databases, and IHS Markit registration data. Bottom-up unit economics and top-down sectoral sizing converged through iterative validation.
Sensitivity analysis tested volume and value outputs across product type, technology layer, end-user archetype, and installation mode dimensions. CAGRs derived from regression against automotive production forecasts and regulatory compliance timelines. Industry-specific inputs included conveyor electrification retrofit pipelines and predictive maintenance contract attach rates.
Material uncertainties — steel cost volatility, REACH enforcement intensity, mechatronics talent migration patterns — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory adherence and OEM capital allocation priorities. Recalibration cycles align with material shifts in EPA rulemaking and EU Green Deal implementation trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market