
 Automotive Cabin Insulation Material Market | 2026-2036
Automotive Cabin Insulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cabin Insulation Material Market Outlook
Mexico is narrowing its position as a North American production hub for acoustic component supply. DuPont leverages its fluoropolymer expertise to dominate high-temperature underhood insulation segments. Autoneum Holdings Inc. anchors European OEM relationships through integrated carpet and inner dash systems. Saint-Gobain sustains leadership in glass wool solutions for thermal and acoustic combined applications.
Automotive cabin insulation material encompasses engineered substrates designed to attenuate airborne noise, structure-borne vibration, and thermal transfer within passenger compartments, typically specified by density ratings between 20-200 kg/m³ and acoustic absorption coefficients exceeding 0.80 across 500-4000 Hz frequency bands. Foam products, particularly polyurethane formulations, lead volume demand due to moldability into complex door and headliner geometries, while fiberglass retains share in underbody shields where thermal resistance above 150°C remains mandatory. Mass loaded vinyl competes in aftermarket retrofit channels where cost sensitivity limits specification to partial cabin treatments rather than full-vehicle integration.
The US NHTSA and EPA jointly shape material selection through crashworthiness flammability standards and fuel economy mandates that penalize weight-intensive insulation packages. Europe's REACH restrictions and F-Gas Regulation constrain certain blowing agents and halogenated flame retardants, redirecting formulation investment toward water-blown polyurethane and bio-polyester alternatives. Stakeholders must monitor how evolving OEM platform electrification strategies rebalance acoustic priorities between powertrain isolation and road-noise dominance.
Market Dynamics
Platform electrification is compressing acoustic engineering cycles as EV architectures eliminate engine-borne noise signatures and amplify road and wind intrusion. This shift forces material suppliers to recalibrate density-performance tradeoffs for frequencies below 500 Hz.
Growth Catalysts
- REACH chemical restrictions:Europe's phasedown of halogenated flame retardants redirects R&D budgets toward bio-polyester fiber development. Compounders in Germany and France now qualify water-blown polyurethane systems for premium EV door modules.
- Lightweighting mandates:NHTSA fuel economy penalties push Detroit OEMs to specify aerogel-composite headliners below 40 kg/m³ density. Thermal-acoustic dual-function substrates reduce part count in cabin assemblies.
- China's dual carbon targets:Provincial EV purchase subsidies in Jiangsu and Zhejiang accelerate local procurement of recycled-content insulation. Domestic suppliers capture volume previously held by imported glass wool.
Market Restraints
- Petrochemical input volatility:Polyol and isocyanate price swings compress foam processor margins. Long-term supply agreements with Middle Eastern feedstock producers remain rare.
- Supplier concentration in glass wool:High-temperature mineral fiber capacity clusters in Belgium and eastern Germany. Automotive qualification timelines exceed 18 months, locking buyers into incumbent relationships.
- Mass loaded vinyl substitution ceiling:Dense MLV layers face displacement by micro-perforated films in aftermarket retrofit channels. Weight penalties limit OEM adoption to wheel-arch applications only.
Strategic Opportunities
- India's PLI scheme for auto components:Tier-2 cities in Pune and Chennai emerge as contract manufacturing hubs for acoustic felts. Local content requirements favor joint ventures with domestic textile processors.
- Thermal-acoustic convergence:Battery pack fire barriers demand intumescent coatings bonded to nonwoven substrates. Material suppliers with flame-spread certification capabilities capture adjacent revenue pools.
- Direct-to-fleet channel expansion:Ride-hail operators in California and Texas specify standardized cabin retrofit kits. Volume procurement bypasses traditional dealer distribution markups.
Industry Challenges
- Acoustic simulation talent scarcity:OEM NVH departments compete for finite pools of engineers trained in SEA and FEM modeling. Universities in Stuttgart and Detroit expand specialized master's programs.
- Multi-material bonding complexity:Foam-to-film lamination defects in hot-humid climates trigger warranty claims. Process control investments exceed $2 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cabin Insulation Material Market |
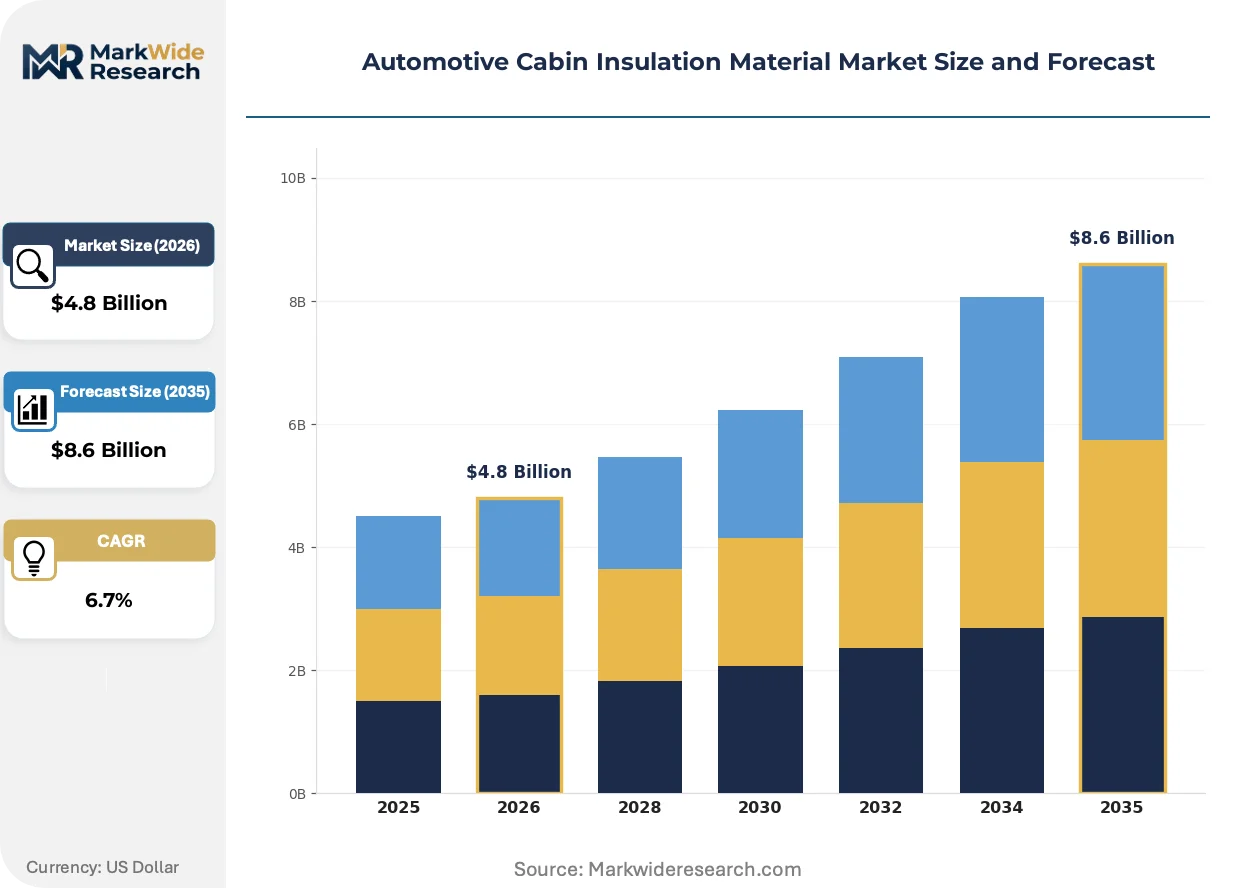
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Fiberglass, Cotton, Mass Loaded Vinyl Application: Soundproofing, Thermal Insulation, Vibration Damping, Environmental Control End User: OEMs, Aftermarket, Tier 1 Suppliers, Vehicle Assemblers Material: Polyester, Polyurethane, Neoprene, Others |
| Companies Covered | DuPont, Armacell International GmbH, Saint-Gobain, 3M Company, Covestro AG, BASF SE, Autoneum Holdings Inc., Owens Corning, Johns Manville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cabin Insulation Material Market Strategic Shifts
Digital twin workflows and closed-loop recycling protocols are compressing development timelines from 36 months to 18 months for new cabin insulation platforms. Suppliers now compete on simulation accuracy and scrap recovery rates rather than commodity chemistry alone.
Active noise cancellation hardware is virtualizing passive material specifications in luxury EV architectures. Mercedes-Benz and BMW integrate microphone-emitter arrays into headliner modules, reducing foam thickness requirements by 30% in front cabin zones. This convergence of electronics and substrates forces acoustic material suppliers to codevelop mounting interfaces with tier-1 audio integrators.
Europe's F-Gas Regulation is banning hydrofluorocarbon blowing agents in polyurethane foam production by 2030. Spanish and Italian compounders accelerate investment in pentane and water-blown alternatives, though thermal conductivity tradeoffs persist in sub-zero climates. Nordic OEMs now qualify dual-blowing-agent formulations to maintain R-values across temperature extremes.
Fleet operators now specify acoustic performance in service-level agreements rather than material certificates. Uber and Lyft procurement teams in Texas and Florida demand cabin noise caps measured at 70 dB during highway operation, shifting supplier accountability to installed outcomes. This performance contracting compresses material selection cycles and elevates system integrators over component vendors.
Automotive Cabin Insulation Material Market Segmentation
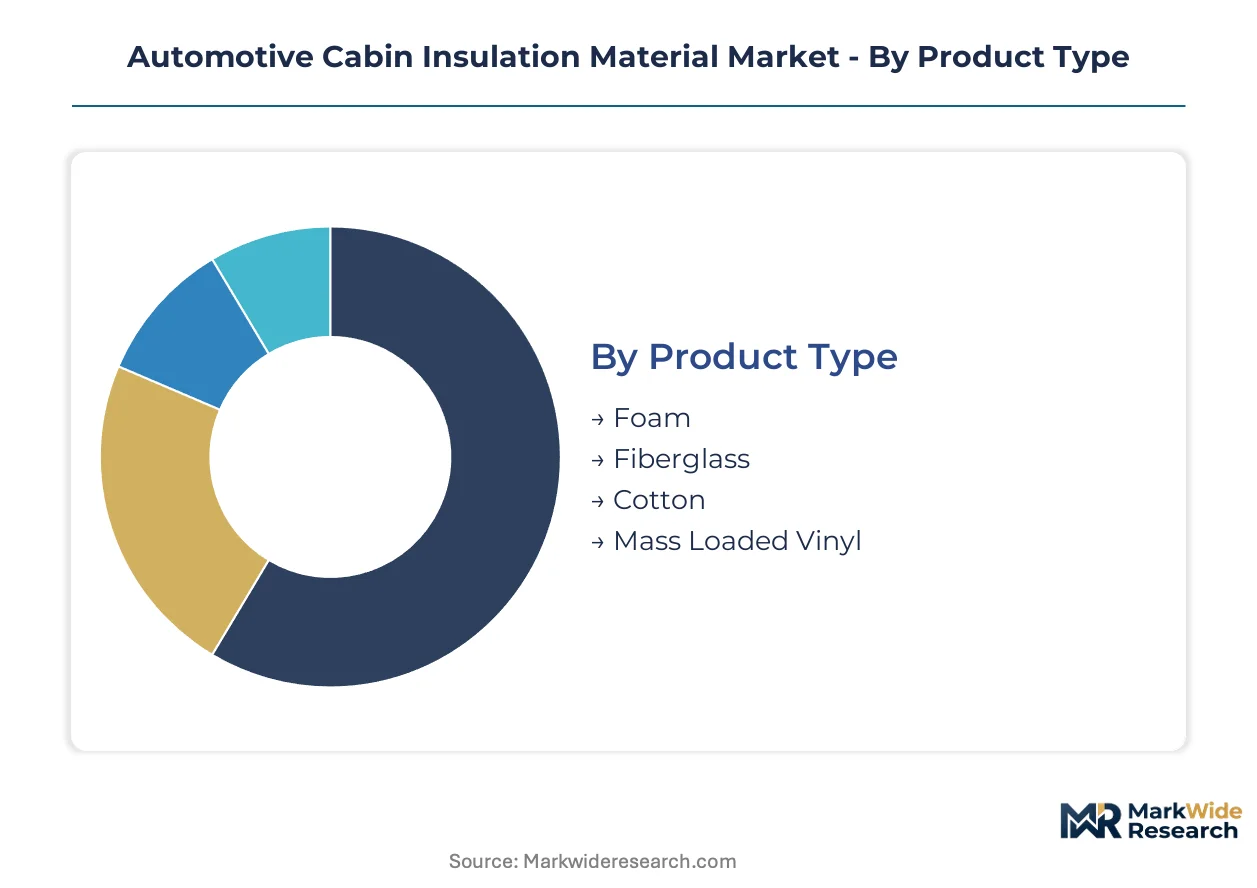
Material selection in automotive cabin insulation hinges on acoustic absorption coefficients, thermal resistance thresholds, and moldability into complex geometries. OEM platform electrification is compressing specification cycles as EV architectures eliminate engine-borne noise and amplify road intrusion. Suppliers now compete on simulation-validated performance rather than commodity chemistry alone.
Product Type:
Cost tier stratification across product categories reflects density-performance tradeoffs and qualification timeline investments.
- Foam:Polyurethane formulations dominate volume demand due to moldability into complex door and headliner geometries. Water-blown systems now qualify for premium EV door modules in Germany and France under REACH phasedown mandates.
- Fiberglass:Mineral fiber retains mandatory share in underbody shields where thermal resistance above 150°C remains non-negotiable. High-temperature capacity clusters in Belgium and eastern Germany, locking buyers into 18-month automotive qualification timelines.
- Cotton:Bio-polyester fiber development redirects R&D budgets as Europe's halogenated flame retardant restrictions tighten.
- Mass Loaded Vinyl:Dense MLV layers face displacement by micro-perforated films in aftermarket retrofit channels where weight penalties limit OEM adoption to wheel-arch applications.
Foam holds installed capacity. Fiberglass is rotating up the share rankings.
Application:
Application segmentation tracks how EV platform electrification rebalances acoustic priorities between eliminated powertrain isolation and amplified road-noise dominance.
- Soundproofing:Active noise cancellation hardware virtualizes passive specifications in luxury EV architectures. Mercedes-Benz and BMW integrate microphone-emitter arrays into headliner modules, reducing foam thickness requirements by 30% in front cabin zones.
- Thermal Insulation:Battery pack fire barriers demand intumescent coatings bonded to nonwoven substrates. Material suppliers with flame-spread certification capabilities capture adjacent revenue pools in thermal-acoustic convergence.
- Vibration Damping:Structure-borne attenuation specifications recalibrate for frequencies below 500 Hz as engine-borne signatures disappear from EV platforms.
- Environmental Control:Cabin climate management integration drives dual-function substrate specifications that reduce part count in cabin assemblies.
Soundproofing commands current specification volume. Thermal insulation is climbing the fastest as battery thermal management requirements intensify.
End User:
Customer type segmentation reveals diverging procurement patterns between integrated OEM platforms and fragmented aftermarket channels.
- OEMs:Detroit automakers specify aerogel-composite headliners below 40 kg/m³ density under NHTSA fuel economy penalty pressure. Long-term supply agreements with Middle Eastern feedstock producers remain rare, compressing foam processor margins during polyol volatility.
- Aftermarket:Ride-hail operators in California and Texas specify standardized cabin retrofit kits with volume procurement bypassing traditional dealer distribution markups. Fleet procurement teams demand cabin noise caps measured at 70 dB during highway operation.
- Tier 1 Suppliers:Autoneum anchors European OEM relationships through integrated carpet and inner dash systems requiring multi-material bonding expertise.
- Vehicle Assemblers:Mexico narrows its position as a North American production hub for acoustic component supply to integrated assembly operations.
OEMs concentrate specification authority. Aftermarket is gaining share fastest through fleet channel expansion.
Material:
Material chemistry segmentation tracks regulatory displacement of halogenated formulations toward bio-based and water-blown alternatives.
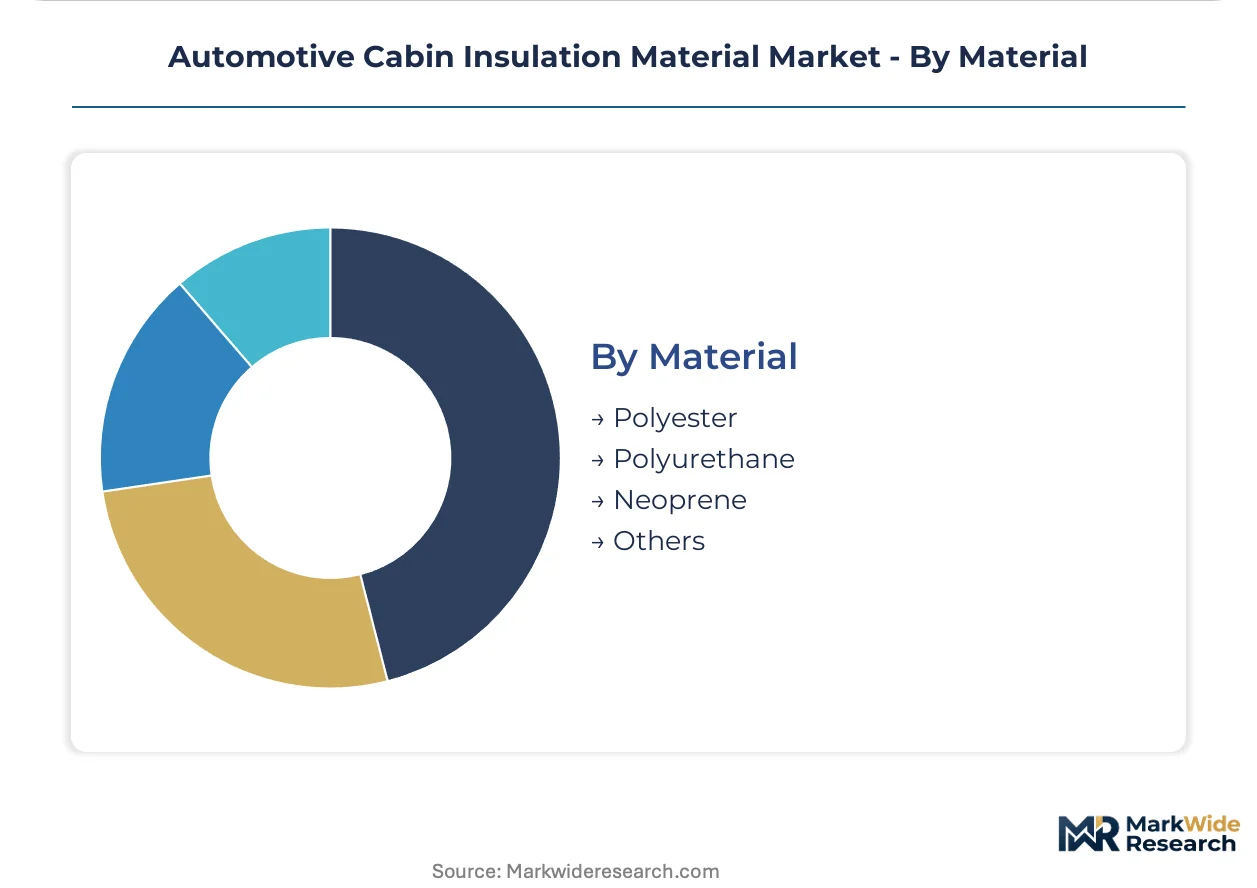
- Polyester:Bio-polyester fiber development accelerates as Europe's REACH restrictions constrain certain blowing agents and halogenated flame retardants. Spanish and Italian compounders invest in pentane alternatives despite thermal conductivity tradeoffs in sub-zero climates.
- Polyurethane:F-Gas Regulation bans hydrofluorocarbon blowing agents by 2030, redirecting formulation investment toward water-blown systems. Nordic OEMs now qualify dual-blowing-agent formulations to maintain R-values across temperature extremes.
- Neoprene:Synthetic rubber formulations retain niche applications requiring chemical resistance and durability in harsh underhood environments.
- Others:Emerging substrate categories include aerogel composites and recycled-content insulation capturing volume previously held by imported glass wool in Jiangsu and Zhejiang provinces.
Polyurethane maintains formulation dominance. Polyester is expanding most quickly on bio-based qualification momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework anchors European material qualification, while NHTSA fuel economy penalties and China's dual carbon targets reshape procurement patterns across three distinct regulatory zones. OEM platform electrification compresses specification cycles differently in each market.
Germany
Premium EV architectures from BMW and Mercedes-Benz drive multi-layer insulation system demand. The F-Gas Regulation accelerates water-blown polyurethane adoption for door modules. Stuttgart and Munich host qualification centers where compounders validate bio-based formulations for 18-month automotive timelines.
United States
Detroit automakers specify aerogel-composite headliners below 40 kg/m³ density under NHTSA fuel economy mandates. EPA emissions standards constrain blowing agent selection for domestic foam production. Michigan and Ohio concentrate tier-1 supplier engineering centers for integrated carpet and dash systems.
China
Provincial EV purchase subsidies in Jiangsu and Zhejiang redirect volume toward recycled-content insulation. MIIT platform standardization accelerates local procurement of nonwoven substrates. Yangtze River Delta manufacturers capture share previously held by imported glass wool through dual carbon compliance.
India
PLI scheme incentives for auto components attract acoustic felt contract manufacturing to Pune and Chennai. BIS thermal resistance standards govern battery pack fire barrier specifications. Tier-2 cities emerge as joint venture hubs with domestic textile processors meeting local content requirements.
Mexico
Nuevo León and Bajío Region assembly plants narrow North American acoustic component supply chains. USMCA rules of origin influence material sourcing decisions for integrated headliner production. Border state logistics clusters reduce lead times for Detroit OEM just-in-sequence programs.
Automotive Cabin Insulation Material Market Competitive Environment
Capability concentration sits with specialty chemical compounders; scale advantage sits with diversified materials conglomerates. The market structures around three tiers: integrated automotive suppliers with OEM line-fit relationships, petrochemical majors with captive polymer supply, and regional foam fabricators serving aftermarket channels. Dominant competitive moves include backward integration into blowing agent production and strategic partnerships with tier-1 audio integrators for active-passive system convergence.
Within the diversified materials tier, DuPont and Saint-Gobain exemplify distinct capability anchoring—fluoropolymer expertise versus glass wool leadership. BASF SE occupies a position representing petrochemical scale advantage in polyurethane formulation. These three entities illustrate how European regulatory pressure and North American lightweighting mandates create divergent strategic postures without requiring identical competitive responses.
| Leading Market Players |
|---|
| DuPont |
| Armacell International GmbH |
| Saint-Gobain |
| 3M Company |
| Covestro AG |
| BASF SE |
| Autoneum Holdings Inc. |
| Owens Corning |
| Johns Manville |
| Others |
Value Chain & Pricing Dynamics
Nuevo León assembly clusters concentrate polyurethane foam capacity for North American OEM programs, compressing supplier margins when polyol feedstock volatility spikes. Detroit automakers leverage this geographic density to enforce annual cost-down targets while USMCA rules of origin constrain alternative sourcing.
Pricing Analysis
Belgium-to-Mexico price spreads for high-temperature mineral fiber exceed standard foam quotations by triple-digit percentages, reflecting 18-month automotive qualification timelines that lock buyers into incumbent relationships. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified bio-based formulations from commodity water-blown systems and unqualified aftermarket retrofit materials. Cost compression in standard polyurethane tiers is intensifying because Middle Eastern feedstock supply agreements remain rare. Aftermarket retrofit channels exhibit highest price sensitivity; premium EV platform engineers demonstrate lowest sensitivity due to performance contracting requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessments for recycled-content insulation procurement. High-temperature glass wool capacity clusters in Belgium, Germany, and the Czech Republic; foam compounding feeds from polyol and isocyanate streams anchored in Middle Eastern petrochemical complexes and Asian chemical processing hubs. Single-source vulnerability persists in automotive-qualified blowing agent supply. Distribution runs through tier-1 integrators with OEM line-fit relationships rather than direct material supplier-to-OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive cabin insulation sector tracks cyclical recovery patterns tied to EV platform launch cadence. OEM electrification investment waves create material specification windows that compress and expand procurement urgency.
For Market Incumbents: Harden qualification timeline advantages by embedding fire-spread certification capabilities into adjacent battery barrier product lines. Deepen backward integration into pentane and water-blown blowing agent production to offset petrochemical input volatility. Lock in multi-year supply agreements with Yangtze River Delta manufacturers before local content requirements tighten further.
For New Entrants and Emerging Players: India's tier-2 cities in Pune and Chennai represent underpenetrated contract manufacturing white space for acoustic felt production under PLI scheme incentives. Target fleet retrofit kit standardization for ride-hail operators in California and Texas, where volume procurement bypasses entrenched dealer networks. Pursue joint venture structures with domestic textile processors to satisfy local content thresholds.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with dual-blowing-agent formulation capabilities spanning sub-zero to temperate climate performance. Five-to-ten year viability rests on simulation-validated material platforms rather than commodity chemistry scale. Acquisition target archetype: regional foam fabricators with active-passive system integration partnerships. Monitor Nordic OEM dual-blowing-agent qualification rates as inflection indicator for formulation technology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Production | Captive pentane supply insulates margins from Middle Eastern polyol volatility. |
| Fire-Spread Certification Investment | Intumescent coating capabilities unlock battery pack fire barrier revenue pools. |
| Active-Passive System Partnership | Codevelopment with tier-1 audio integrators preserves foam specification share against ANC virtualization. |
| Joint Venture with Domestic Textile Processor | Local content compliance in India PLI scheme accelerates acoustic felt contract manufacturing access. |
| Digital Twin Workflow Deployment | Simulation accuracy competition compresses 36-month development cycles to 18-month platforms. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with OEM platform engineers, tier-1 supplier procurement leads, acoustic material compounders, and fleet operator procurement teams. Secondary validation drew from NHTSA fuel economy filings, EPA emissions disclosures, ECHA REACH registration databases, MIIT platform standardization notices, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across material chemistry and application segments.
Calibration against historical qualification timeline data and announced EV platform production ramps shaped projection parameters across the analysis window. Segmentation dimensions included material type, application function, propulsion architecture, OEM tier positioning, and regional production cluster. CAGRs derived from slope-logic regression against electrification penetration curves, with battery thermal management intensity and active noise cancellation adoption rates as automotive-specific demand modifiers.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting automotive capex cycles or petrochemical feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory phase-in schedules and OEM platform electrification commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Pneumatic Seat System Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Global Smart Tailgate Market