
 Global Luxury Car Coachbuilding Market | 2026-2036
Global Luxury Car Coachbuilding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Luxury Car Coachbuilding Market Outlook
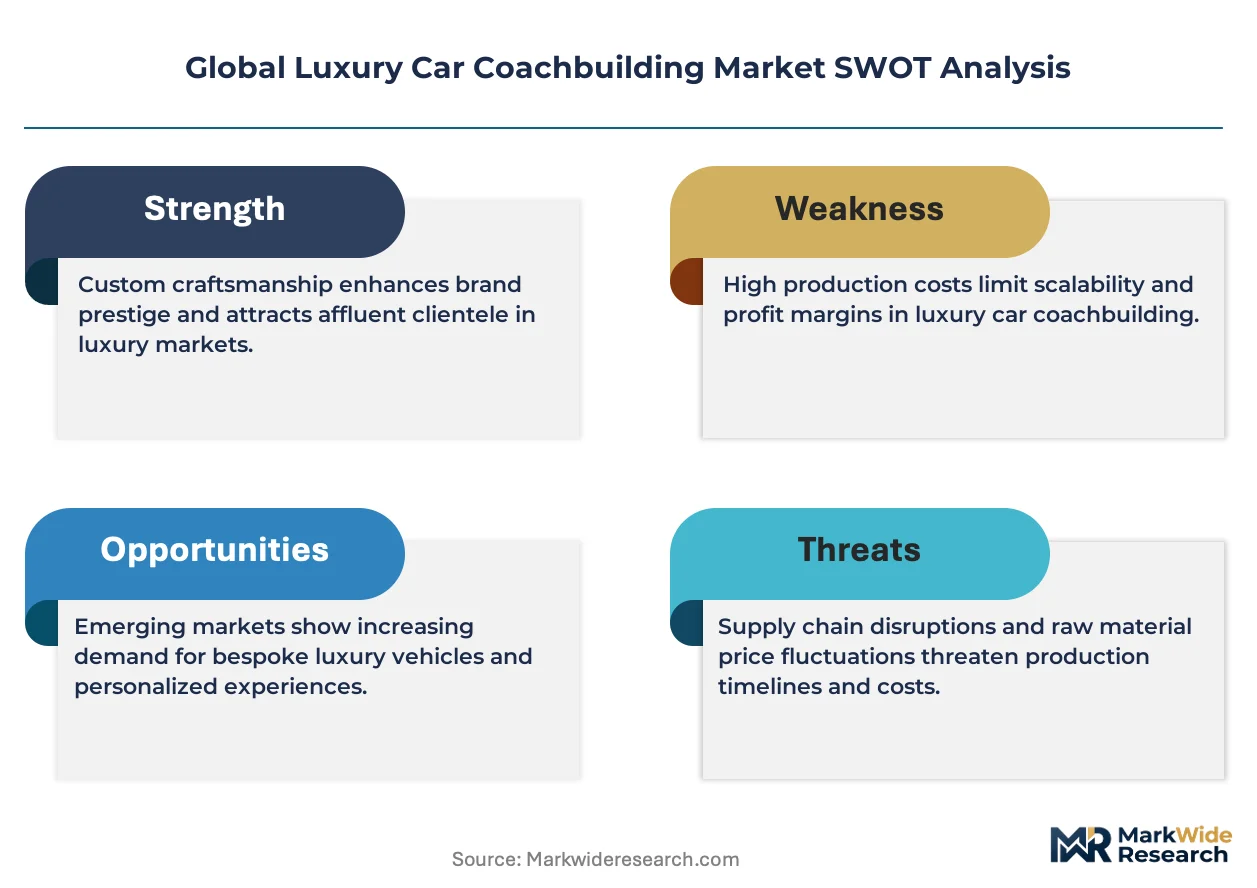
The gap between hand-built coachwork and factory personalization is recalibrating competitive boundaries in the luxury automotive ecosystem. Pininfarina leverages its Turin design heritage to anchor premium electric grand touring commissions. Carrozzeria Touring Superleggera sustains its Milanese aluminum superleggera craft against industrialized carbon fiber methods. Zagato Milano differentiates through limited-series Zagato-bodied coupes that occupy the intersection of art and automotive engineering.
Luxury car coachbuilding denotes the artisanal design and fabrication of bespoke automobile bodies upon donor chassis, employing hand-formed aluminum panels, carbon fiber pre-preg layups, and multi-stage lacquer finishing processes that extend build cycles to twelve months or longer. The discipline serves collectors and exclusive brands seeking singular vehicles unattainable through mass customization programs. Custom Bodies command the deepest margin pools where individual client specifications drive six-figure design premiums. High-Net-Worth Individuals represent the fastest-expanding end-user category as new wealth in technology and energy sectors enters automotive collecting. Direct Sales channels dominate transaction architecture, though luxury dealerships in Geneva and London extend geographic reach for established ateliers.
EU REACH restrictions on volatile organic compounds in paint systems and ECHA classification of certain resin hardeners constrain material selection for continental coachbuilders. EPA tailpipe and crashworthiness standards in the United States govern homologation pathways for bespoke vehicles entering American collections. NHTSA low-volume manufacturer provisions create regulatory latitude for limited-production commissions. Stakeholders must monitor evolving carbon accounting frameworks that threaten to impose lifecycle disclosure obligations on artisanal production models with inherently unstandardized supply chains.
Market Dynamics
Carbon fiber pre-preg consolidation among three Japanese suppliers is rewriting raw material economics for European ateliers, compressing design-to-delivery cycles while elevating unit costs for small-batch coachbuilders dependent on aerospace-grade weave specifications.
Growth Catalysts
- EU Green Deal carbon accounting frameworks:Early compliance positioning by Turin and Milan ateliers is securing preferential supplier status with OEM chassis donors seeking Scope 3 disclosure partners.
- Technology sector wealth concentration:Founders from artificial intelligence and cryptocurrency ventures in California and Singapore are commissioning electric grand touring bodies at unprecedented rates.
- Saudi Arabia:Royal household patronage and sovereign wealth vehicle investments are establishing Riyadh as a commissioning hub rivaling traditional European centers.
Market Restraints
- Aluminum sheet supply concentration:Premium 5000-series alloy availability depends on single-source Austrian rolling mills, exposing ateliers to six-month lead time volatility.
- REACH resin hardener restrictions:ECHA classification of aromatic amine curing agents forces reformulation of structural adhesives used in carbon fiber monocoque bonding.
- Factory personalization programs:Rolls-Royce Bespoke and Ferrari Tailor Made capture margin pools previously accessible only to independent coachbuilders.
Strategic Opportunities
- Restoration and rebodying of classic chassis:California's NHTSA low-volume manufacturer provisions enable legal pathway for electric powertrain swaps in vintage donor vehicles.
- South Korea:MFDS-aligned material certification standards are creating first-mover advantage for ateliers pre-qualifying carbon fiber suppliers for chaebol family commissions.
- Hybrid aluminum-carbon construction:Convergence of superleggera heritage methods with automated fiber placement is opening weight reduction thresholds previously unattainable in hand-built bodies.
Industry Challenges
- Master panel beater succession:The craft knowledge for hand-forming compound curvature aluminum without digital reverse-engineering resides with aging practitioners in Turin and Modena.
- Homologation timeline compression:EPA crashworthiness validation for bespoke vehicles entering US collections requires 18-month certification cycles that misalign with collector auction calendars.
- IP fragmentation in digital surfacing:Disputes over algorithmic-generated body sculpting software licenses are delaying commission starts for ateliers without captive design engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Luxury Car Coachbuilding Market |
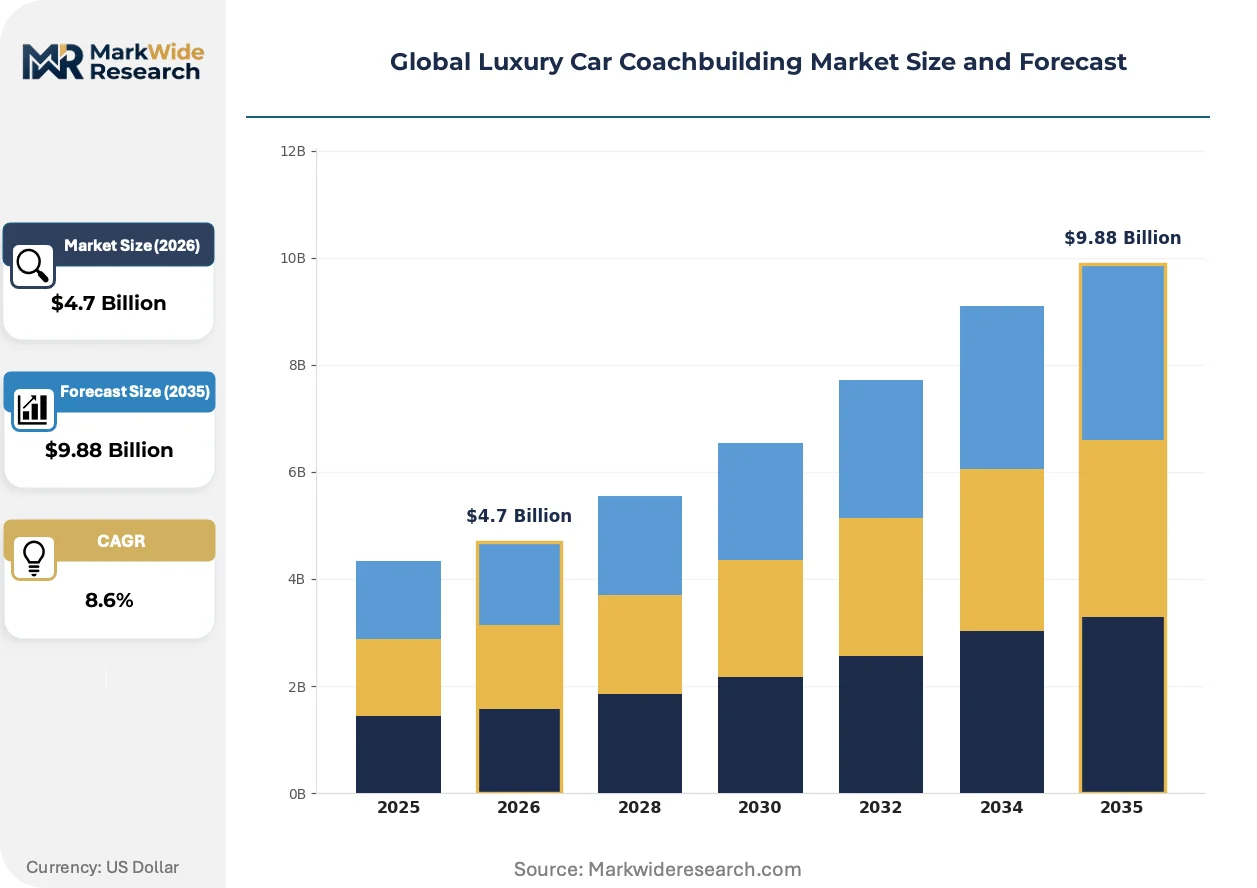
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Bodies, Glass-Fiber Composite, Aluminum Framework, Steel Chassis End User: Exclusive Brands, High-Net-Worth Individuals, Automotive Enthusiasts, Collectors Service Type: Design Consultation, Manufacturing, Finishing, Repairs Distribution Channel: Direct Sales, Online Platforms, Luxury Dealerships, Auctions |
| Companies Covered | Pininfarina, Carrozzeria Touring Superleggera, Italdesign Giugiaro, Zagato Milano, Carrosserie Akkermans, ARES Modena, Fioravanti, Moal Coachbuilders, Motorima, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Luxury Car Coachbuilding Market Strategic Shifts
Computational design tools and sustainable material certifications are bifurcating the coachbuilding craft between algorithmically optimized production and heritage hand-work preservation.
Automated fiber placement for carbon fiber body shells is rewriting structural possibilities for electric vehicle architectures. Saudi sovereign commissions and Silicon Valley technology founders are specifying full monocoque construction at volumes previously reserved for motorsport applications. This capability compression is enabling 40% weight reduction versus aluminum-intensive methods while demanding capital commitments beyond traditional atelier balance sheets.
REACH restrictions on volatile organic compounds in multi-stage lacquer systems are forcing reformulation of heritage paint processes. Italian and German coachbuilders are investing in waterborne ceramic clearcoat technologies that satisfy ECHA emission thresholds without sacrificing depth-of-image finish quality. The compliance burden falls heaviest on restoration divisions dependent on period-correct solvent-based materials.
Direct commissioning through encrypted digital platforms is displacing Geneva and London dealership intermediaries for established collector relationships. Younger principals from technology and energy fortunes in Singapore and Dubai prefer secure video consultation to physical atelier visits. This channel shift concentrates margin capture with coachbuilders while demanding cybersecurity infrastructure foreign to heritage family businesses.
Global Luxury Car Coachbuilding Market Segmentation
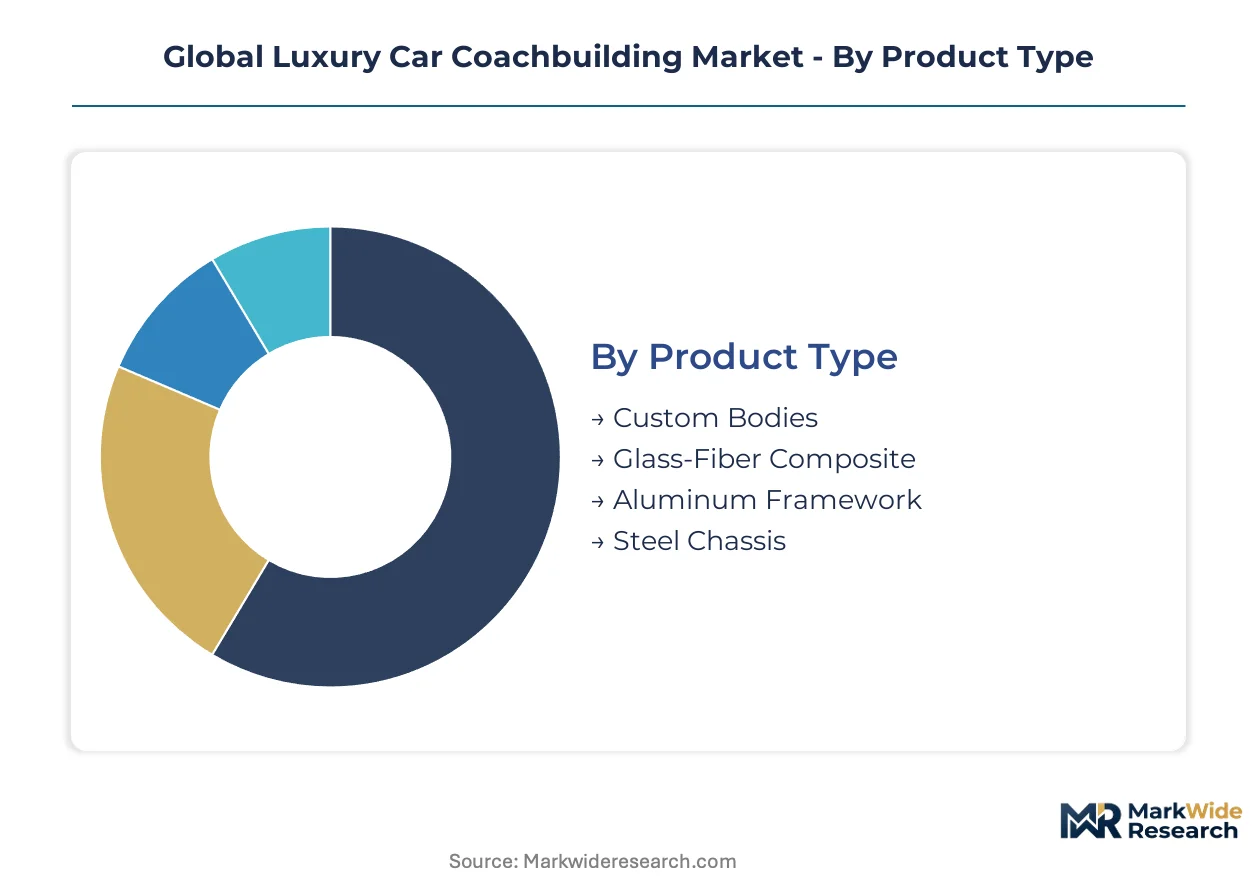
Segmentation in luxury car coachbuilding reveals how value pools distribute across fabrication methods, client archetypes, and transaction architectures. Understanding these divides exposes where artisanal ateliers retain pricing power against factory personalization programs.
Product Type:
Material selection dictates structural possibilities, finish durability, and regulatory compliance pathways across commissioning cycles.
- Custom Bodies:Hand-formed aluminum panels and carbon fiber pre-preg layups create unibody structures with twelve-month build cycles. Royal households in Saudi Arabia and billionaire industrialists in Switzerland commission these at record rates, absorbing six-figure design premiums for singular vehicles unattainable through mass programs.
- Aluminum Framework:Superleggera heritage methods employ 5000-series alloy sheets hand-beaten over wooden bucks. Supply concentration at Austrian rolling mills exposes Turin and Milan ateliers to lead time volatility, yet the technique sustains collector preference for period-correct restoration work.
- Glass-Fiber Composite:Lower-density tooling enables rapid prototyping for concept commissions and show vehicles. California low-volume manufacturers leverage this for electric powertrain swap feasibility studies.
- Steel Chassis:Structural donor platforms from OEM partners provide crashworthiness certification foundations. EPA homologation pathways depend on these underlying architectures for US market entry.
Custom Bodies leads on scale; Aluminum Framework leads on momentum.
End User:
Wealth concentration patterns determine commissioning frequency, specification complexity, and atelier relationship longevity.
- High-Net-Worth Individuals:Technology founders from artificial intelligence and cryptocurrency ventures in California and Singapore are specifying electric grand touring bodies at unprecedented rates. These principals prefer encrypted digital platforms to physical atelier visits, demanding cybersecurity infrastructure foreign to heritage family businesses.
- Collectors:Established principals maintain multi-decade relationships with specific ateliers for sequential commissions. Auction calendar alignment pressures these clients to accelerate homologation timelines that otherwise extend eighteen months for EPA crashworthiness validation.
- Exclusive Brands:OEM partners seeking Scope 3 disclosure partners pre-qualify ateliers with early EU Green Deal compliance positioning. Turin and Milan workshops secure preferential chassis donor status through this channel.
- Automotive Enthusiasts:Entry-level commissioning through restoration and rebodying of classic chassis occupies this tier. NHTSA low-volume provisions enable legal electric powertrain swaps for vintage donor vehicles.
Collectors anchor revenue stability; High-Net-Worth Individuals drive steepest expansion trajectory.
Service Type:
Value capture migrates upstream as digital tools compress design-to-delivery cycles and compliance burdens reshape finishing operations.
- Manufacturing:Automated fiber placement for carbon fiber monocoques enables forty-percent weight reduction versus aluminum-intensive methods. Capital requirements exceed traditional atelier balance sheets, consolidating this tier among Saudi sovereign-backed commissions.
- Design Consultation:Algorithmic-generated body sculpting software licenses fragment IP ownership, delaying commission starts for ateliers without captive engineering. Disputes over digital surfacing tools concentrate in Milan and Turin.
- Finishing:REACH restrictions on volatile organic compounds force reformulation of heritage multi-stage lacquer processes. Waterborne ceramic clearcoat investments satisfy ECHA emission thresholds without sacrificing depth-of-image quality.
- Repairs:Master panel beater succession crises threaten this segment as compound curvature aluminum craft knowledge resides with aging practitioners in Modena. Digital reverse-engineering cannot replicate hand-formed heritage techniques.
Manufacturing commands margin concentration; Design Consultation is gaining share fastest.
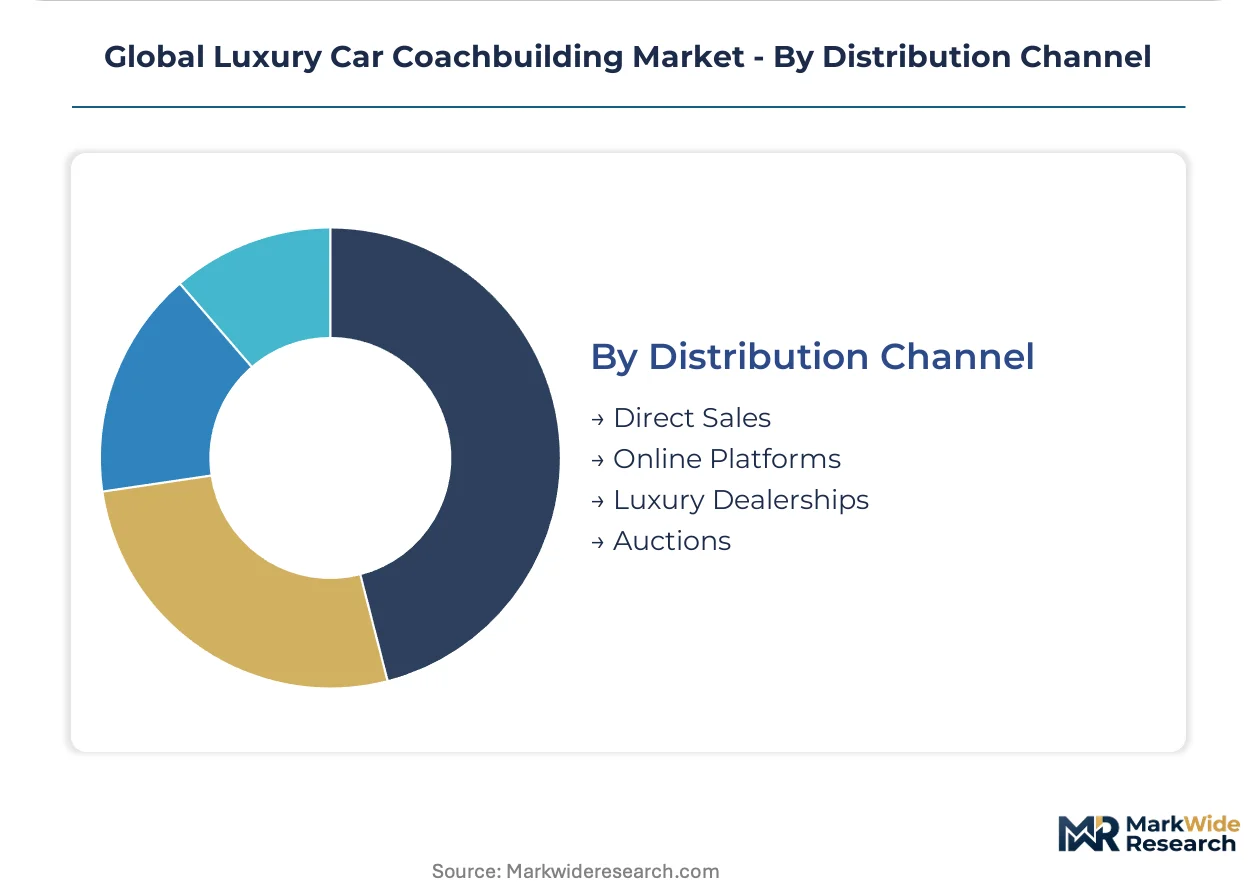
Distribution Channel:
Channel architecture determines geographic reach, client acquisition cost, and margin retention for heritage ateliers.
- Direct Sales:Encrypted video consultation platforms displace traditional intermediaries for established collector relationships. Younger principals in Dubai and Singapore prefer this channel, concentrating margin capture with coachbuilders.
- Luxury Dealerships:Geneva and London showrooms extend geographic reach for European ateliers seeking Middle Eastern and Asia-Pacific clients. These intermediaries absorb commission percentages that direct channels eliminate.
- Online Platforms:Emerging digital marketplaces facilitate discovery for first-time commissioners. Cybersecurity infrastructure investments separate viable platforms from heritage family businesses lacking technical capabilities.
- Auctions:Secondary market validation establishes provenance and resale value for completed commissions. Homologation timeline compression misaligns with auction calendar cycles, creating delivery pressure.
Direct Sales leads on margin retention; Online Platforms lead on client acquisition velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master panel beaters and carbon fiber laminators concentrate in Northern Italy, anchoring the craft heritage that sustains bespoke automotive fabrication worldwide.
Saudi Arabia
Royal household patronage and sovereign wealth vehicle investments drive commissioning volumes rivaling European centers. SFDA-aligned material import protocols govern carbon fiber pre-preg entry for Riyadh-based ateliers. The capital's emerging collector district hosts direct commissioning platforms that bypass traditional Geneva intermediaries.
United Kingdom
Billionaire industrialists sustain multi-decade atelier relationships through sequential bespoke commissions. DVSA individual vehicle approval pathways regulate bespoke vehicle homologation for road use. London's Mayfair cluster maintains dealership intermediaries serving Middle Eastern principals seeking European craftsmanship credentials.
Switzerland
Private banking networks facilitate discrete commission financing for ultra-high-net-worth collectors. Swissmedic-aligned chemical handling standards constrain paint system formulations in Zurich-region workshops. Geneva's luxury automotive corridor retains geographic reach functions despite direct digital platform encroachment.
United States
Technology founders from artificial intelligence and cryptocurrency ventures commission electric grand touring bodies at unprecedented rates. NHTSA low-volume manufacturer provisions create regulatory latitude for limited-production bespoke vehicles. California's restoration specialists leverage EPA tailpipe pathways for electric powertrain swaps in vintage donor chassis.
Italy
Turin and Milan ateliers leverage EU Green Deal early compliance to secure preferential chassis donor status with OEM partners. ECHA REACH restrictions on aromatic amine curing agents force structural adhesive reformulation for carbon fiber monocoque bonding. The Piedmont-Lombardy corridor concentrates aging master craftsmen whose hand-forming knowledge resists digital replication.
Global Luxury Car Coachbuilding Market Competitive Environment
Top-tier vendors anchor heritage design houses, while mid-tier specialists occupy restoration and rebodying niches. The vendor base distributes across three structural tiers: design-origin ateliers with OEM chassis partnerships, independent coachbuilders serving collector restoration markets, and technology-integrated newcomers pursuing electric vehicle architectures. Consolidation pressures concentrate among carbon fiber pre-preg dependent fabricators facing Japanese supplier consolidation. Geographic expansion into Saudi Arabia and Singapore represents the dominant competitive move alongside strategic partnerships for EU REACH compliance positioning.
Within the heritage-design archetype, Pininfarina and Carrozzeria Touring Superleggera exemplify ateliers leveraging regional craft identities—Turin design heritage and Milanese aluminum superleggera methods respectively—to anchor premium commissioning relationships. Zagato Milano occupies a position at the intersection of art and automotive engineering through limited-series coupe production. ARES Modena represents technology-integrated fabrication approaches that compress traditional build cycles through automated fiber placement adoption.
| Leading Market Players |
|---|
| Pininfarina |
| Carrozzeria Touring Superleggera |
| Italdesign Giugiaro |
| Zagato Milano |
| Carrosserie Akkermans |
| ARES Modena |
| Fioravanti |
| Moal Coachbuilders |
| Motorima |
| Others |
Value Chain & Pricing Dynamics
Master panel beaters concentrated in Turin's Piedmont-Lombardy corridor command wage premiums that widen spreads between heritage aluminum superleggera commissions and automated carbon fiber production tiers. Labor-cost differentials between aging Italian craftsmen and Saudi-trained laminators reshape pricing architectures across commissioning cycles.
Pricing Analysis
Bundled design-consultation-manufacturing packages versus unbundled component sourcing splits the market into integrated atelier relationships and à la carte restoration services. Price differentiation hinges on EU REACH compliance certification and royal household provenance premiums. Pricing pressure stems from factory personalization programs at Rolls-Royce Bespoke and Ferrari Tailor Made capturing margin pools previously reserved for independents. Automotive enthusiasts exhibit highest price sensitivity; royal households in Saudi Arabia and billionaire industrialists in Switzerland demonstrate lowest.
Supply Chain Analysis
Warehouse-distribution layers for carbon fiber pre-preg materials concentrate in regional hub patterns anchored by Japanese supplier consolidation. Raw material flows draw from Austrian rolling mills for 5000-series aluminum alloys, Japanese aerospace-grade carbon fiber weavers, and German resin hardener formulators. Single-source vulnerability at Austrian premium alloy suppliers exposes ateliers to lead time volatility. Distribution runs through direct encrypted platforms displacing Geneva and London dealership intermediaries for established collector relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Luxury Car Coachbuilding Market functions as a stable compounder anchored by irreplaceable craft heritage concentrated in Northern Italy. Ultra-high-net-worth wealth formation in technology and energy sectors sustains commissioning velocity through economic cycles.
For Market Incumbents: Acquire master panel beater craft knowledge through structured succession programs before aging practitioners in Modena and Turin exit the workforce. Secure preferential chassis donor status with OEM partners through early EU Green Deal compliance positioning. Factory personalization programs at major marques threaten margin capture; defensive certification investments in waterborne ceramic clearcoat technologies preserve heritage finish quality against REACH restrictions. For New Entrants and Emerging Players: Capture electric powertrain swap feasibility studies under California's NHTSA low-volume manufacturer provisions. Target restoration and rebodying of classic chassis as the most penetrable entry tier, where homologation timeline compression creates service gaps. Establish encrypted digital commissioning platforms to displace Geneva intermediaries for Dubai and Singapore principals seeking direct atelier relationships. For Investors and Strategic Acquirers: OEM chassis donors seeking Scope 3 disclosure partners are the most active acquirer in this space, consolidating compliant ateliers into captive supplier networks. Long-term viability favors targets with hybrid aluminum-carbon construction capabilities bridging superleggera heritage and automated fiber placement. Watch for ECHA reclassification of aromatic amine curing agents as the signal indicating regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU REACH Compliance Positioning | Early adopters secure preferential chassis donor status with OEM partners seeking Scope 3 partners. |
| Automated Fiber Placement Adoption | Technology-integrated newcomers compress build cycles while demanding capital beyond traditional atelier balance sheets. |
| Encrypted Digital Platform Development | Direct commissioning channels concentrate margin capture with coachbuilders while demanding cybersecurity infrastructure. |
| Master Craftsman Succession Programs | Structured knowledge transfer preserves hand-forming capabilities that digital reverse-engineering cannot replicate. |
| Saudi Arabia Geographic Expansion | Riyadh's emerging collector district hosts sovereign-backed commissions rivaling traditional European centers. |
Study Parameters
Coverage spans Saudi Arabia, the United Kingdom, Switzerland, the United States, and Italy, with primary inputs from each market cluster. The approach combines structured interviews with atelier owners, OEM platform engineers, carbon fiber procurement specialists, and royal household vehicle fleet managers with secondary validation. Sources include ECHA REACH regulatory filings, NHTSA low-volume manufacturer registration databases, vehicle production statistics, and customs records for premium aluminum alloy imports. Bottom-up commission volume estimates and top-down wealth-concentration analysis provide triangulation.
Granularity-level modeling disaggregates the analysis window by material type, end-user archetype, service category, and distribution channel, with additional segmentation by regional regulatory cluster. CAGRs derive from regression analysis against ultra-high-net-worth population growth and commissioning frequency patterns. Key forecast inputs include EU Green Deal implementation timelines and SFDA-aligned material import protocol evolution in Saudi Arabia.
Regulatory reclassification of resin hardeners, master craftsman retirement waves, and OEM factory personalization program expansion are the dominant revision risks. Forecasts reflect documented assumptions regarding wealth concentration trajectories and compliance cost pass-through rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Windscreen Washer System Market