
 Automotive Panoramic Sunroof Market | 2026-2036
Automotive Panoramic Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Panoramic Sunroof Market Analysis
Premium SUV and electric vehicle buyers are unwinding the traditional sedan-centric demand pattern that long dominated sunroof procurement. Webasto SE leverages its integrated glass and mechanism platforms to sustain design partnerships with European OEMs. Magna International Inc. anchors North American supply through vertically controlled module assembly. Inalfa Roof Systems Group BV competes on sliding-system specialization across Asian vehicle platforms.
An automotive panoramic sunroof constitutes an oversized transparent or translucent roof aperture, typically spanning two or more passenger rows, constructed from laminated safety glass or polycarbonate composites with embedded UV-interlayer films and electrochromic tint layers; its primary function delivers cabin daylighting, spatial perception expansion, and venting utility while maintaining rollover structural integrity. Electric deployment variants now lead volume contribution as hands-free operation becomes a baseline expectation in premium nameplates. Glass technology segments command the dominant margin pool due to weight-reduction coatings and acoustic damping interlayers, while polycarbonate formulations represent the fastest-growing structural category driven by mass-reduction targets in battery-electric architectures.
NHTSA's Federal Motor Vehicle Safety Standard 216a governs roof crush resistance for panoramic installations in the United States, while ECE R43 and the EU's General Safety Regulation mandate glazing fragmentation behavior and ejection mitigation across European type approvals. China's GB 9656 standard sets parallel impact-resistance and optical-transmittance thresholds that MIIT enforces through vehicle-type certification. OEMs and suppliers must monitor how divergent regional test protocols for head-impact and weather-sealing durability reshape platform engineering decisions and homologation timelines.
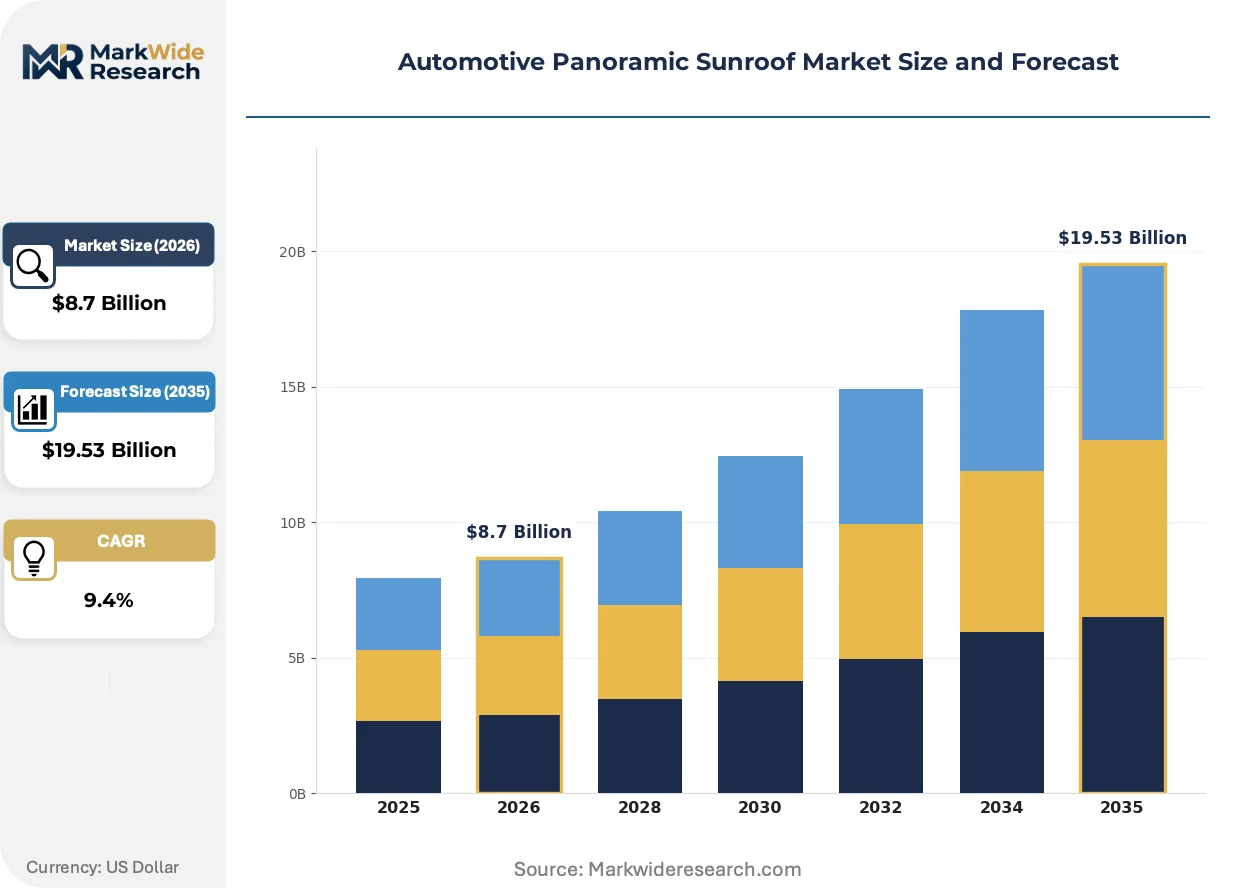
Market Dynamics
Electric vehicle architectures are rewiring panoramic sunroof procurement logic, as battery-pack weight budgets force OEMs to prioritize polycarbonate composites over traditional laminated glass across premium nameplates.
Growth Catalysts
- EU General Safety Regulation:Mandated ejection-mitigation glazing standards accelerate replacement cycles across European vehicle fleets, pulling demand for certified panoramic modules.
- Polycarbonate composite adoption:Battery-electric platforms specify mass-reduction targets that polycarbonate sunroof structures satisfy, opening fitment in mid-tier electric SUVs.
- China MIIT certification pipeline:Streamlined GB 9656 type-approval processes reduce homologation timelines for foreign suppliers entering domestic EV supply chains.
Market Restraints
- Specialized glass input costs:Acoustic-damping interlayers and UV-blocking films concentrate pricing power with chemical suppliers in Germany and Japan.
- Regional supplier concentration:Mechanism and rail assembly capacity clusters in Lower Saxony and Michigan, exposing OEMs to single-source logistics risk.
- NHTSA roof-crush testing variance:Divergent interpretation of Federal Motor Vehicle Safety Standard 216a load-deflection protocols creates certification friction for multi-region platforms.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced glazing and mechanism manufacturing attract module assembly investment away from traditional export bases.
- Electrochromic tint convergence:Integration of SPD-suspension film with panoramic glass creates premium pricing tiers in executive electric sedans.
- Direct OEM-webstore channel:Replacement sunroof module sales bypass traditional aftermarket distributors, capturing margin in collision repair segments.
Industry Challenges
- Homologation engineer scarcity:Deep expertise in ECE R43 fragmentation testing and NHTSA rollover simulation commands wage premiums that strain supplier R&D budgets.
- Cleanroom assembly capex:Electrochromic film lamination requires particulate-controlled production environments that smaller mechanism suppliers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Panoramic Sunroof Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Luxurious, Standard Technology: Glass, Fabric, Composite, Polycarbonate End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Deployment: Fixed, Sliding, Pop-up, Retractable |
| Companies Covered | AISIN Corporation, CIE Automotive SA, Webasto SE, BOS GmbH & Co. KG, Yachiyo Industry Co. Ltd., Inalfa Roof Systems Group BV, Magna International Inc., AGC Inc., Inteva Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Panoramic Sunroof Market Emerging Trajectories
Material science and regulatory pressure are splitting the sunroof market into two parallel tracks: lightweight polycarbonate for electric vehicles and acoustic-optimized glass for internal-combustion luxury segments.
Electrochromic tinting technology is bifurcating the premium glass segment. Suspended-particle-device films embedded between laminated plies enable real-time opacity control without mechanical shades. European luxury OEMs specify this feature as standard in flagship electric SUVs, compressing demand for traditional fabric sunshades and forcing mechanism suppliers to reposition around fixed-glass module assembly.
REACH restrictions on polycarbonate additive chemistries are reshaping formulation R&D. ECHA scrutiny of bisphenol-A alternatives in UV-stabilizer compounds pushes suppliers toward bio-based interlayer testing. German OEMs face the tightest compliance timelines, accelerating qualification of non-phthalate plasticizers in sliding rail components ahead of scheduled restriction reviews.
Fleet procurement of panoramic modules is fragmenting across channel types. Rental and mobility-service operators now specify damage-resistant polycarbonate variants with extended warranty terms, displacing traditional glass in high-utilization vehicle pools. This pattern concentrates in California and Nordic markets where subscription-model vehicle access has achieved critical penetration.
Automotive Panoramic Sunroof Market Segmentation
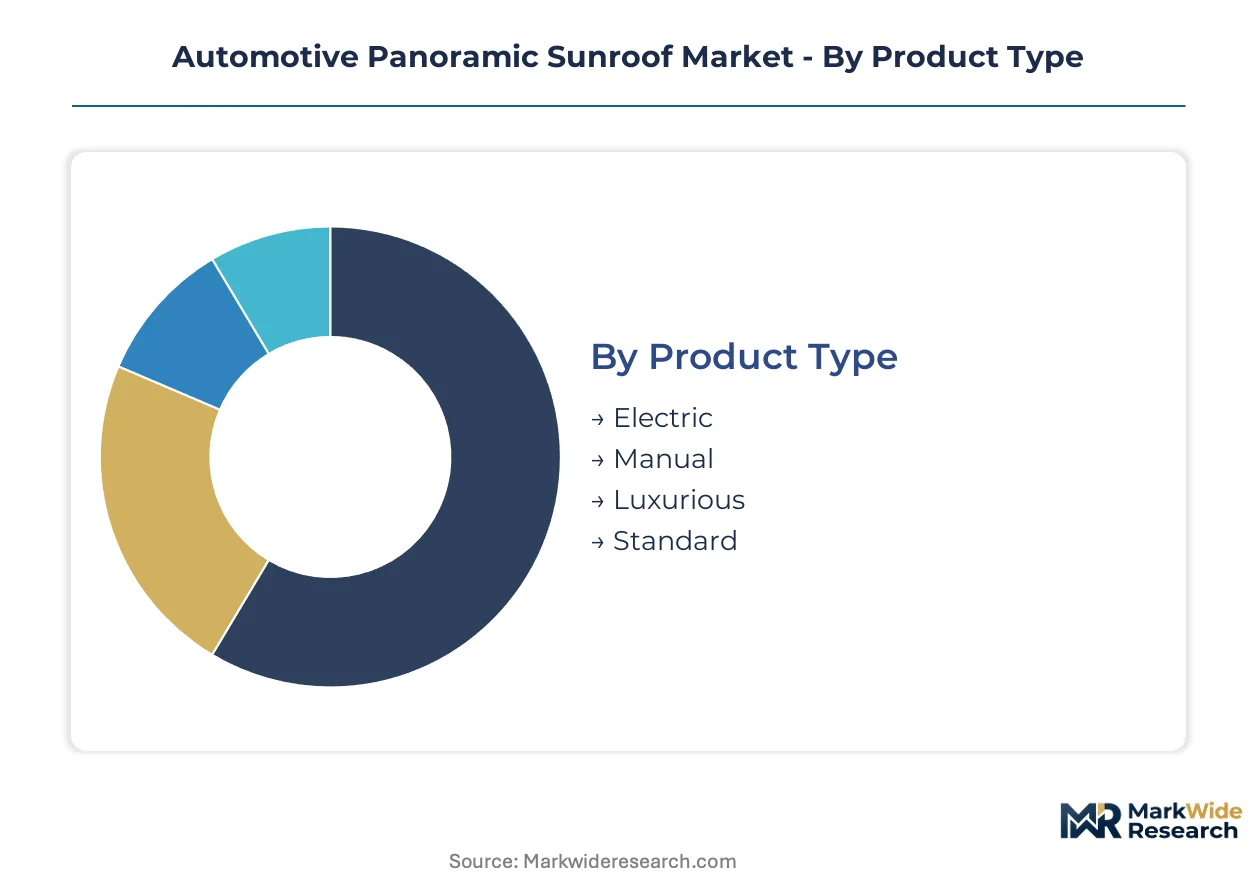
Segmentation in the automotive panoramic sunroof market reveals how procurement decisions split across powertrain architectures, material specifications, and channel structures. OEMs now configure platform sourcing differently for battery-electric versus internal-combustion nameplates, while regulatory pressure on glazing fragmentation reshapes supplier qualification criteria.
Product Type:
Margin pools concentrate in hands-free deployment systems where mechanism integration commands premium pricing over manual alternatives.
- Electric:Motorized deployment with rain-sensing closure and programmable vent positions dominates premium SUV and electric sedan fitments. Battery-electric architectures in Germany and China specify these variants as baseline equipment, driven by consumer expectation of seamless cabin automation.
- Luxurious:Multi-panel configurations with electrochromic tint layers and embedded LED ambient lighting capture the highest unit economics. European luxury OEMs specify these for flagship electric SUVs, where daylighting customization supports brand differentiation.
- Manual:Hand-crank or lever-actuated mechanisms persist in entry-level compact vehicles where cost engineering outweighs convenience features.
- Standard:Single-panel fixed or basic sliding configurations serve fleet procurement and mid-tier internal-combustion nameplates with constrained option budgets.
Electric holds installed capacity. Luxurious is rotating up the share rankings.
Technology:
Material selection now tracks powertrain weight budgets more closely than traditional luxury positioning.
- Polycarbonate:Injection-molded composite structures with UV-stabilizer packages achieve 40-50% mass reduction versus laminated glass. Battery-electric platforms in China and the United States specify polycarbonate for mid-tier SUVs where range optimization overrides acoustic performance priorities.
- Glass:Laminated safety glass with acoustic-damping interlayers and infrared-reflective coatings retains dominance in internal-combustion luxury segments. German OEMs specify these for executive sedans where cabin quietness and thermal management justify weight penalties.
- Composite:Hybrid glass-polycarbonate laminates with structural interlayers bridge mass and optical performance requirements in premium electric crossovers.
- Fabric:Retractable textile sunshades with manual or motorized deployment serve as secondary glare-control layers across all material substrates.
Glass retains the revenue base. Polycarbonate is climbing the fastest.
End User:
Channel concentration determines how module specifications flow from design to assembly.
- OEMs:Vehicle manufacturers with captive sunroof engineering teams in Stuttgart, Detroit, and Shanghai define platform architectures and approve supplier qualifications. Direct procurement relationships concentrate volume with Webasto SE and Magna International Inc.
- Tier-1 Suppliers:Module integrators purchasing glass, mechanisms, and seals from sub-tiers for just-in-sequence delivery to assembly plants. Inalfa Roof Systems Group BV operates primarily through this channel across Asian vehicle platforms.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities receiving pre-certified sunroof modules for line-fit installation.
- Aftermarket Providers:Collision repair specialists and accessory retailers sourcing replacement modules through distributor networks or direct OEM webstore channels.
OEMs control specification authority. Tier-1 Suppliers are gaining share fastest.
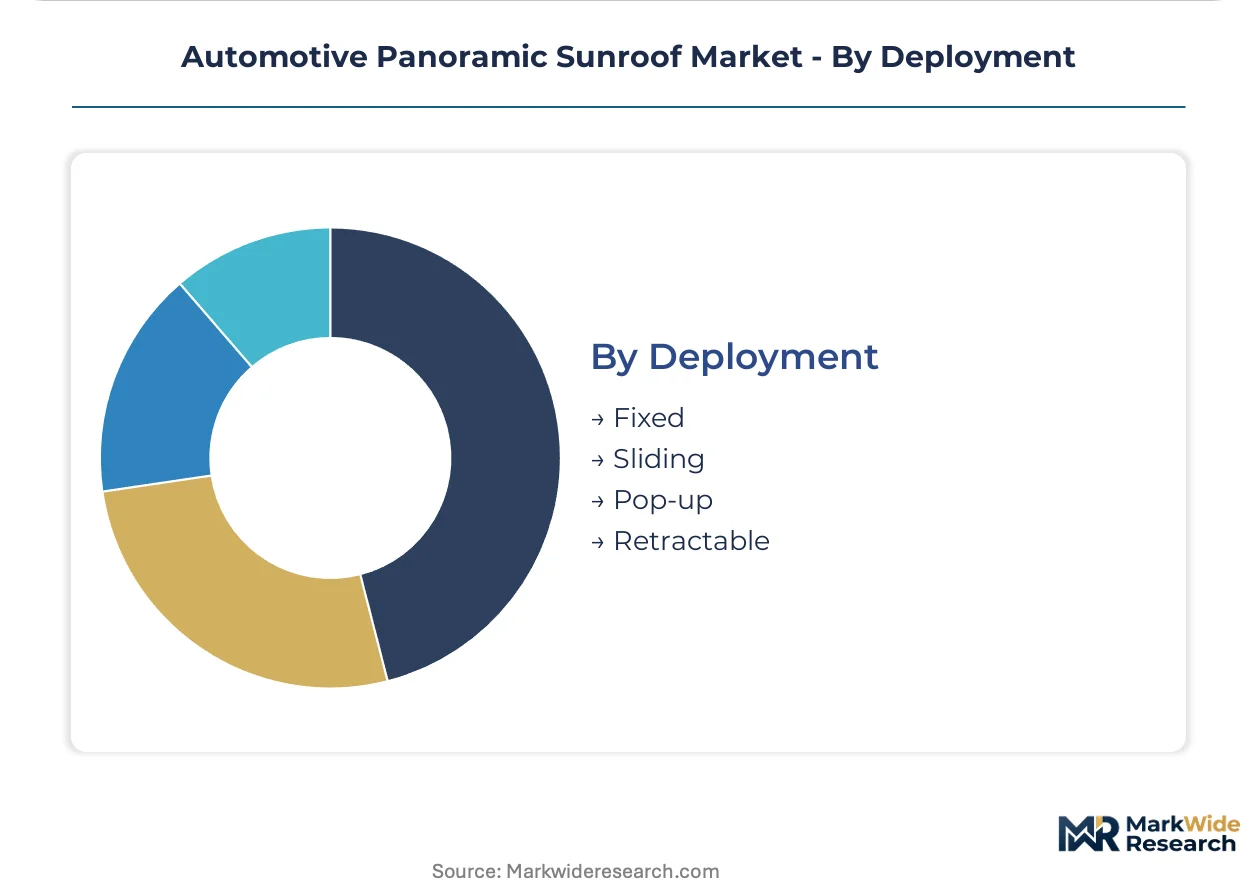
Deployment:
Mechanism complexity separates fixed-glass value pools from actuated systems requiring rail, motor, and seal integration.
- Sliding:Dual-rail mechanisms enabling front-to-rear panel translation with anti-pinch safety compliance. European and Chinese electric SUVs specify these variants for venting utility without aerodynamic penalty of pop-up configurations.
- Fixed:Stationary glass or polycarbonate panels with integrated electrochromic tint layers eliminate mechanism cost and weight. Battery-electric architectures prioritize these for structural simplicity and headroom optimization.
- Pop-up:Hinged rear-edge lift mechanisms for passive ventilation, declining in new platform designs due to wind noise and seal durability concerns.
- Retractable:Full panel stowage into roof cassette with fabric or rigid shade closure, commanding highest mechanism complexity and service frequency exposure.
Sliding maintains volume leadership. Fixed is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers export finished panoramic modules to assembly plants in China and the United States, establishing the dominant east-west trade corridor in automotive glazing systems.
China
Domestic electric vehicle brands specify polycarbonate panoramic roofs for range optimization in mid-tier SUVs. MIIT enforces GB 9656 certification timelines that foreign suppliers must navigate for market entry. Shanghai and the Yangtze River Delta concentrate module assembly capacity serving BYD, NIO, and Tesla Gigafactory Shanghai.
Germany
Luxury OEMs in Stuttgart and Munich mandate electrochromic glass for flagship electric SUV nameplates. ECE R43 fragmentation standards and EU General Safety Regulation ejection-mitigation rules shape supplier qualification. Lower Saxony hosts mechanism and rail assembly clusters supplying Volkswagen Group and BMW.
United States
Detroit-based OEMs prioritize fixed-glass polycarbonate configurations for battery-electric truck and SUV platforms. NHTSA Federal Motor Vehicle Safety Standard 216a roof-crush protocols create certification friction for multi-region vehicle programs. Michigan's supplier corridor around Lansing and Detroit anchors North American module integration.
Japan
Domestic OEMs emphasize acoustic-optimized laminated glass for executive hybrid sedans. METI vehicle-type certification aligns with international glazing standards while preserving domestic testing protocols. Kanto region engineering centers coordinate tier-1 supplier relationships with Aisin and Yachiyo Industry.
India
Mid-tier SUV procurement from Mahindra and Tata Motors pulls sliding-system demand into domestic supply chains. PLI scheme production-linked incentives for advanced auto components attract glazing and mechanism manufacturing investment. Maharashtra and Gujarat host emerging module assembly operations serving Maruti Suzuki and Hyundai Motor India.
Automotive Panoramic Sunroof Market Vendor Landscape
Listed leaders compete with private specialists across capital access and engineering agility dimensions. The vendor base splits between consolidated module integrators and focused mechanism suppliers. Three archetypes dominate: full-system platform owners, sliding-specialization houses, and glass-chemistry originators. Capacity expansion and strategic partnerships constitute the primary competitive moves reshaping supply relationships.
Among European-based platform owners, Webasto SE exemplifies full-system integration capability spanning glass lamination and mechanism assembly. Magna International Inc. anchors North American supply through vertically controlled module production. Inalfa Roof Systems Group BV occupies the sliding-system specialization tier across Asian vehicle programs. These three represent distinct strategic positions without implying specific market shares or financial performance.
| Leading Market Players |
|---|
| AISIN Corporation |
| CIE Automotive SA |
| Webasto SE |
| BOS GmbH & Co. KG |
| Yachiyo Industry Co. Ltd. |
| Inalfa Roof Systems Group BV |
| Magna International Inc. |
| AGC Inc. |
| Inteva Products LLC |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Chinese glazing facilities shapes price floors across electric and internal-combustion nameplates, concentrating margin pressure on mechanism suppliers without captive glass lamination. Scale economies in polycarbonate resin processing tilt procurement power toward chemical suppliers in Japan and Germany, forcing module integrators to absorb input volatility or pass through via contract escalators.
Pricing Analysis
Next-generation electrochromic glass commands premium positioning over current-generation fixed polycarbonate and prior-generation manual sliding systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and acoustic performance tier, with ECE R43 fragmentation compliance separating top-tier from mid-tier quotations. Cost compression in standard manual configurations is intensifying because Chinese domestic EV brands negotiate volume offtakes with mechanism suppliers. Fleet procurement managers exhibit highest price sensitivity, while European luxury OEM platform engineers prioritize electrochromic tint integration over unit cost.
Supply Chain Analysis
Germany and China anchor finished module assembly, while Japan and South Korea supply acoustic-damping interlayers and UV-stabilizer chemistries. Polycarbonate resin, laminated glass substrates, and electrochromic SPD film draw from concentrated petrochemical and specialty chemical feedstocks. Single-source vulnerability concentrates in Lower Saxony rail-mechanism machining capacity, exposing multi-region platforms to logistics disruption. Distribution runs through just-in-sequence Tier-1 integrators delivering pre-certified modules to OEM assembly plants in Michigan, Shanghai, and Stuttgart.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive panoramic sunroof market exhibits cyclical recovery characteristics tied to electric vehicle platform launch cadence, with battery-electric architecture proliferation driving replacement demand for lighter polycarbonate configurations.
For Market Incumbents: Shield margin pools by deepening backward integration into electrochromic film lamination, countering specialty chemical supplier pricing power. Consolidate mechanism assembly capacity in Michigan and Lower Saxony to reduce logistics exposure for North American and European OEM programs. Certification investment in GB 9656 and NHTSA 216a parallel homologation defends against emerging Asian module integrators. For New Entrants and Emerging Players: Aftermarket direct-to-consumer module replacement represents the most penetrable service-layer gap, where incumbent OEMs under-serve collision repair channels with slow distributor turnaround. Target India PLI scheme incentives for glazing and mechanism manufacturing, leveraging production-linked cost advantages against established export bases. Go-to-market angle: certified remanufactured modules with extended warranty terms for fleet and mobility-service operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrochromic glass specialists with locked-in platform supply agreements across German luxury OEM electric SUV programs. Long-term viability over the next decade hinges on polycarbonate formulation R&D capabilities and REACH-compliant additive pipelines. Acquisition target archetype: mid-cap mechanism suppliers with cleanroom lamination capacity and MIIT certification track records. Watch electrochromic tint penetration rates in executive electric sedans as inflection indicator for premium glass margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces mechanism engineering overhead across multiple OEM electric SUV nameplates. |
| Backward Integration into Film Lamination | Captures margin from SPD-suspension and electrochromic interlayer suppliers. |
| Geographic Manufacturing Footprint | India PLI scheme incentives attract module assembly away from traditional German and Chinese bases. |
| Long-term Supply Agreement | Locks in polycarbonate resin pricing with Japanese petrochemical suppliers for battery-electric platforms. |
| Green Certification Program | REACH-compliant bio-based UV-stabilizer formulations qualify for EU Green Deal procurement preferences. |
Methodological Framework
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distribution managers, and homologation specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from vehicle production databases, IHS Markit registration data, MIIT type-approval filings, and SEC supplier disclosures. Bottom-up module shipment estimates triangulated against top-down OEM production schedules across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from installed base evolution and replacement cycle assumptions, with electric vehicle penetration rates and polycarbonate weight-reduction targets as core forecast inputs.
Underlying assumptions cover ECE R43 and NHTSA 216a regulatory stability, with deviation risk concentrated in REACH restriction timelines and MIIT certification process changes. Recalibration cycles align with material shifts in battery-electric platform launch schedules and electrochromic tint technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Car Oxygen Bar Market