
 India Automotive Door Seals Market | 2026-2036
India Automotive Door Seals Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Door Seals Market Outlook
Electric vehicle manufacturing is realigning procurement priorities across the India Automotive Door Seals Market. Passenger car OEMs now specify advanced sealing profiles for battery compartment integrity and cabin acoustics. Cooper Standard leverages its polymer compounding expertise to serve domestic EV platforms. Hutchinson anchors its position through localized production of TPE-based sealing systems for premium vehicle lines.
Automotive door seals are extruded elastomeric profiles engineered to prevent water ingress, air leakage, and noise transmission between vehicle body panels and doors, typically manufactured from EPDM compounds with specific Shore A hardness ratings between 60 and 80. The primary purpose spans environmental sealing, acoustic dampening, and structural gap management across passenger and commercial vehicle architectures. EPDM formulations dominate current volume owing to their thermal stability and ozone resistance in tropical climates, while TPE segments capture expanding margin pools as recyclability mandates intensify. Clip-in installation methods lead OEM adoption for assembly-line efficiency, though adhesive bonding retains share in aftermarket retrofit applications where field serviceability matters.
BIS material standards and the Automotive Industry Standards committee under the Ministry of Road Transport shape product certification pathways for door seal suppliers entering the Indian market. The PLI scheme for automotive components incentivizes domestic manufacturing of advanced sealing compounds, redirecting import dependency toward localized supply chains. Stakeholders must monitor evolving crash safety regulations that integrate door seal performance into side-impact structural ratings, as this linkage will determine future material specifications and testing protocols.
Market Dynamics
Electric vehicle platform rollouts across Tamil Nadu and Maharashtra are compressing development cycles for sealing suppliers, forcing simultaneous retooling for acoustic performance and battery ingress protection. The PLI scheme for automotive components accelerates this transition by conditioning incentives on localized advanced material production.
Growth Catalysts
- PLI Scheme for Automotive Components:Domestic manufacturing incentives redirect capital toward captive EPDM compounding facilities, reducing import dependency for specialty elastomers used in premium vehicle lines.
- Battery Electric Vehicle Architectures:New EV platforms specify dual-density sealing profiles that isolate high-voltage compartments from cabin spaces, creating specification tiers absent in internal combustion vehicle supply chains.
- Chennai-Aurangabad Industrial Belt:OEM assembly concentration within this corridor generates demand clustering that rewards suppliers with co-located extrusion and molding operations.
Market Restraints
- EPDM Raw Material Concentration:Ethylene-propylene feedstock supply concentrates among three domestic petrochemical complexes, exposing molders to synchronized input cost volatility during crude price cycles.
- BIS Certification Timelines:Bureau of Indian Standards material approval processes extend 14-18 months for novel TPE formulations, delaying commercialization of recyclable alternatives against EPDM incumbents.
- Technical Limitation in Tropical UV Exposure:Standard TPE compounds exhibit surface degradation at 85°C dashboard-adjacent temperatures, restricting deployment to door frames shielded from direct solar loading.
Strategic Opportunities
- Gujarat Automotive Cluster:Underpenetrated supplier presence around Sanand and Halol creates whitespace for sealing specialists establishing compounding-to-assembly operations serving emerging EV battery plants.
- Recyclability Mandates:Extended Producer Responsibility frameworks under Ministry of Environment directives position TPE-based sealing systems for regulatory preference as vehicle end-of-life obligations tighten.
- 3D-Printed Prototyping Convergence:Rapid tooling methods compress OEM validation cycles from 26 weeks to 8 weeks, enabling sealing suppliers to bid on platform-specific development contracts previously captured by integrated Tier 1s.
Industry Challenges
- Polymer Compounding Talent Scarcity:Domestic workforce development lags demand for rheology specialists capable of formulating dual-hardness profiles with consistent Shore A variance below 3 points.
- Legacy Press Retrofit Requirements:Transition from single-material extrusion to co-extrusion systems demands capital outlays exceeding INR 4 crore per line, straining mid-tier molders without PLI scheme qualification.
- Crash Safety Integration Complexity:Side-impact structural ratings now incorporate door seal compression behavior, requiring suppliers to coordinate finite element modeling with OEM safety engineering teams lacking standardized interface protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Door Seals Market |
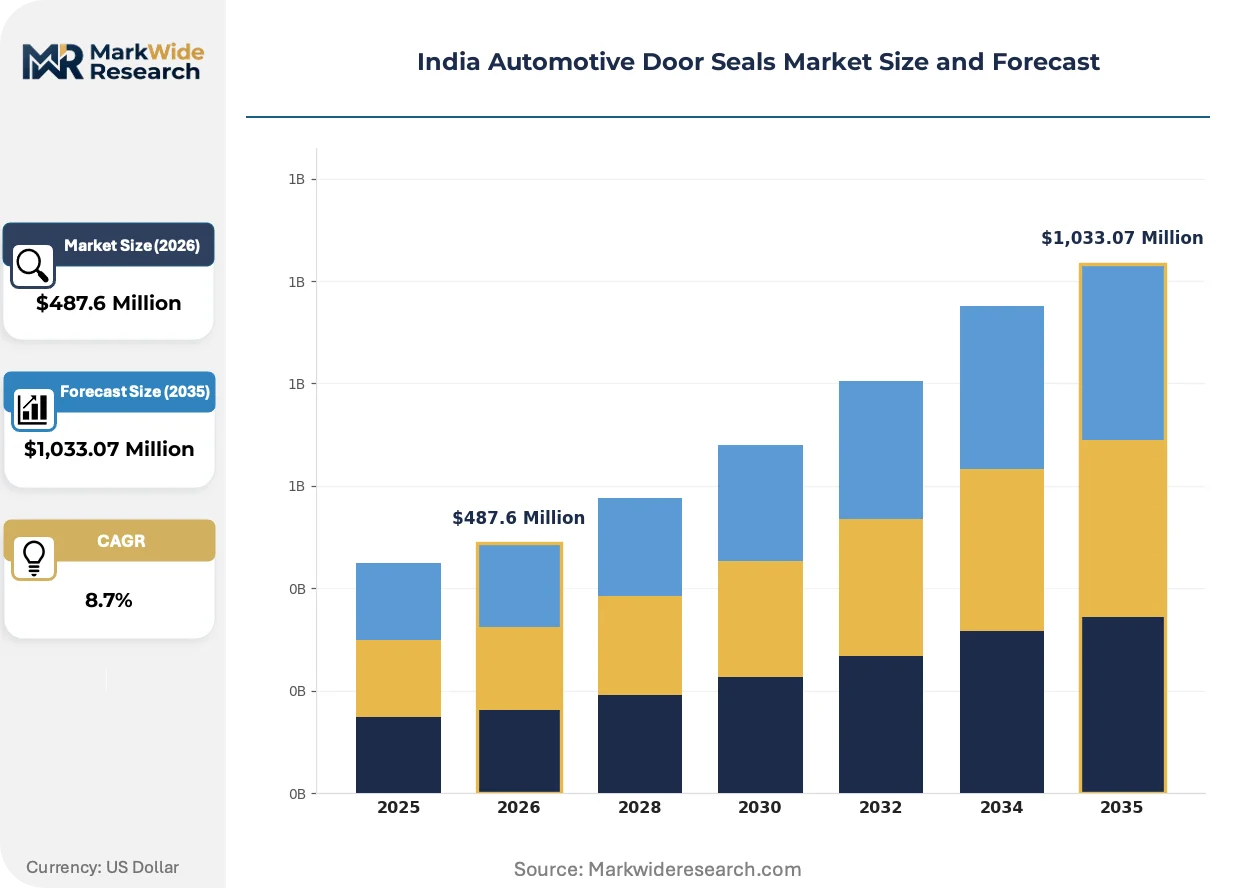
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, TPE, PVC, Rubber End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, SUVs Installation Method: Adhesive Bonding, Mechanical Fastening, Clip-in, Others |
| Companies Covered | Gates Corporation, Hutchinson, Cooper Standard, Gold Seal Engineering Products Pvt. Ltd., Toyoda Gosei, Vibracoustic, ElringKlinger AG, Nippon Sealing, Dura Automotive Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Door Seals Market Strategic Shifts
Thermoplastic elastomer formulations are penetrating segments long held by cross-linked EPDM, driven by end-of-life recyclability requirements and compressed development timelines for new vehicle platforms.
Multi-durometer co-extrusion technology is absorbing engineering resources across domestic sealing suppliers. This process bonds rigid attachment zones to compliant sealing lips within single continuous profiles. Passenger car OEMs in the Chennai corridor specify these constructions for 40% of new platform launches. The technology is absorbing margin from conventional bonded assemblies by eliminating secondary clipping operations.
BIS certification amendments for automotive elastomers now mandate flame resistance testing under UL 94 HB protocols for battery electric vehicle applications. This regulatory extension forces reformulation of standard EPDM compounds with halogen-free flame retardant loadings. Suppliers serving Maharashtra-based EV startups face compressed recertification cycles as these buyers prioritize rapid homologation over incumbent validation histories.
Fleet operators and shared mobility platforms now specify lifecycle cost guarantees extending to 300,000 kilometers, displacing upfront price minimization as the dominant procurement criterion. This behavioral shift channels volume toward suppliers offering predictive wear monitoring and scheduled replacement programs. The transformation is most visible in Karnataka's Bengaluru-Mysuru corridor, where ride-hailing fleet aggregators consolidate purchasing across 15,000-vehicle pools.
India Automotive Door Seals Market Segmentation
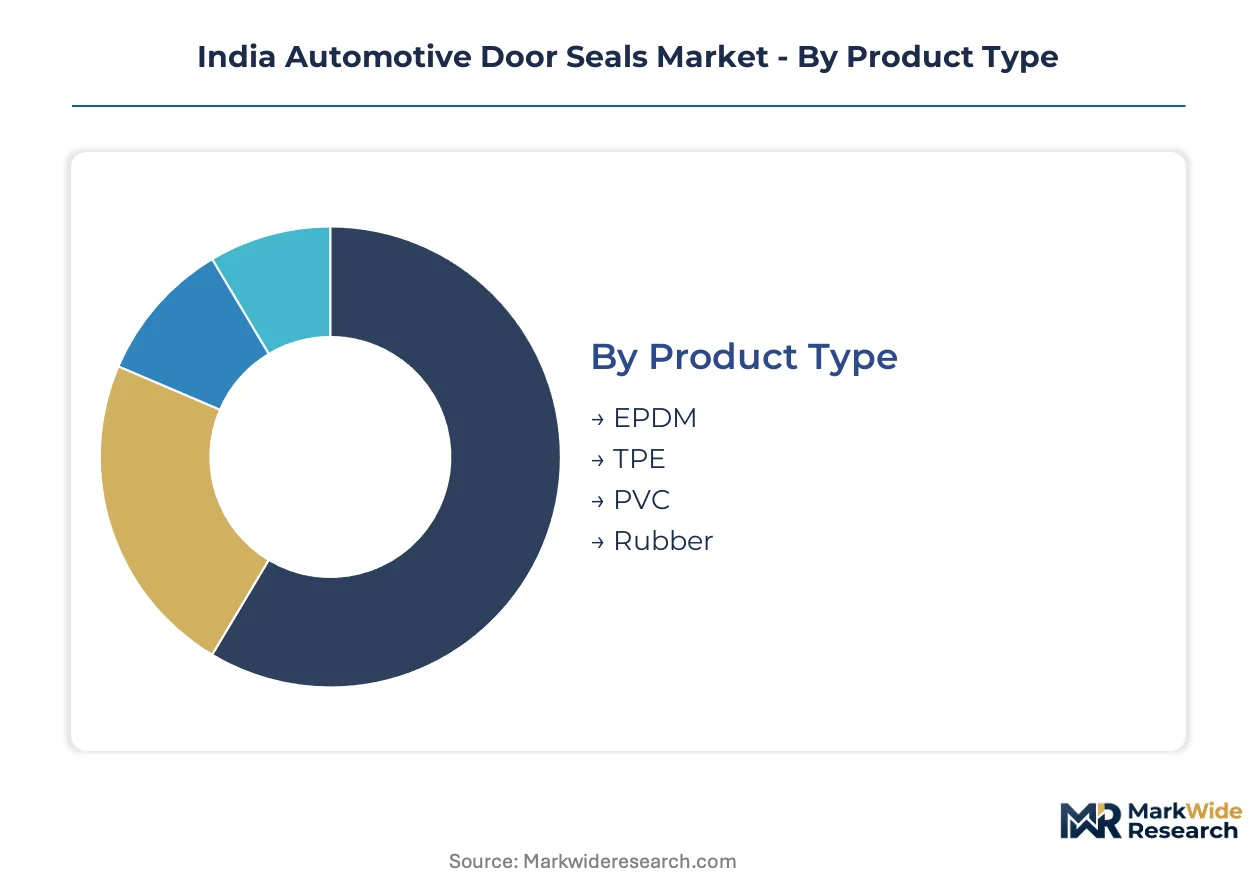
Door seal procurement in India fragments across material chemistry, supply chain tier, vehicle architecture, and assembly methodology. Each segmentation axis carries distinct margin profiles and certification requirements that reshape supplier positioning within the Chennai-Aurangabad industrial belt.
Product Type:
Material selection spans a customization spectrum from commodity EPDM compounds to engineered TPE formulations requiring specialized compounding infrastructure.
- EPDM:Cross-linked ethylene-propylene-diene monomer compounds dominate current volume through thermal stability above 120°C and ozone resistance in tropical climates. Demand concentrates among legacy internal combustion platforms across Tamil Nadu assembly corridors where BIS certification pathways favor established formulations.
- TPE:Thermoplastic elastomer systems enable recyclable end-of-life processing under emerging Extended Producer Responsibility frameworks. Maharashtra-based EV startups specify these materials for battery compartment sealing where flame resistance under UL 94 HB protocols applies.
- PVC:Cost-sensitive formulations retain share in commercial vehicle aftermarket channels.
- Rubber:Natural and synthetic rubber blends serve legacy fleet refurbishment in Karnataka's shared mobility corridors.
Leading the category by volume: EPDM. Growing fastest: TPE.
End User:
Supply chain position determines specification authority and contract duration, from multi-year platform agreements to spot aftermarket procurement.
- OEMs:Original equipment manufacturers in the Chennai-Aurangabad belt issue platform-specific technical specifications with 5-7 year contract horizons. Maruti Suzuki and Hyundai Motor India demand co-extrusion capabilities for dual-hardness profiles with Shore A variance below 3 points.
- Aftermarket Providers:Independent distributors and service chains procure adhesive-bonding formats for field retrofit applications. Karnataka fleet aggregators now specify lifecycle cost guarantees extending to 300,000 kilometers, displacing upfront price minimization.
- Tier-1 Suppliers:Integrated system suppliers bundle door seals with weatherstrip modules for just-in-sequence delivery to assembly plants.
- Vehicle Assemblers:Contract manufacturers and kit assemblers source standardized clip-in profiles for knockdown production.
Dominant by contract value: OEMs. Expanding most quickly: Aftermarket Providers.
Application:
Vehicle architecture dictates performance specifications spanning acoustic dampening, water ingress protection, and structural integration.
- Passenger Cars:Premium hatchbacks and sedans specify multi-durometer co-extrusion constructions for 40% of new platform launches in the Chennai corridor. These profiles bond rigid attachment zones to compliant sealing lips within single continuous extrusions.
- Electric Vehicles:Battery electric architectures require dual-density sealing profiles that isolate high-voltage compartments from cabin spaces. Gujarat's emerging EV battery plants generate demand clustering for specialized ingress protection specifications absent in internal combustion supply chains.
- Commercial Vehicles:Heavy-duty trucks prioritize durability over acoustic performance in long-haul configurations.
- SUVs:Higher door masses and wider frame gaps demand reinforced attachment geometries.
Highest specification intensity: Electric Vehicles. Steepest volume expansion: Passenger Cars.
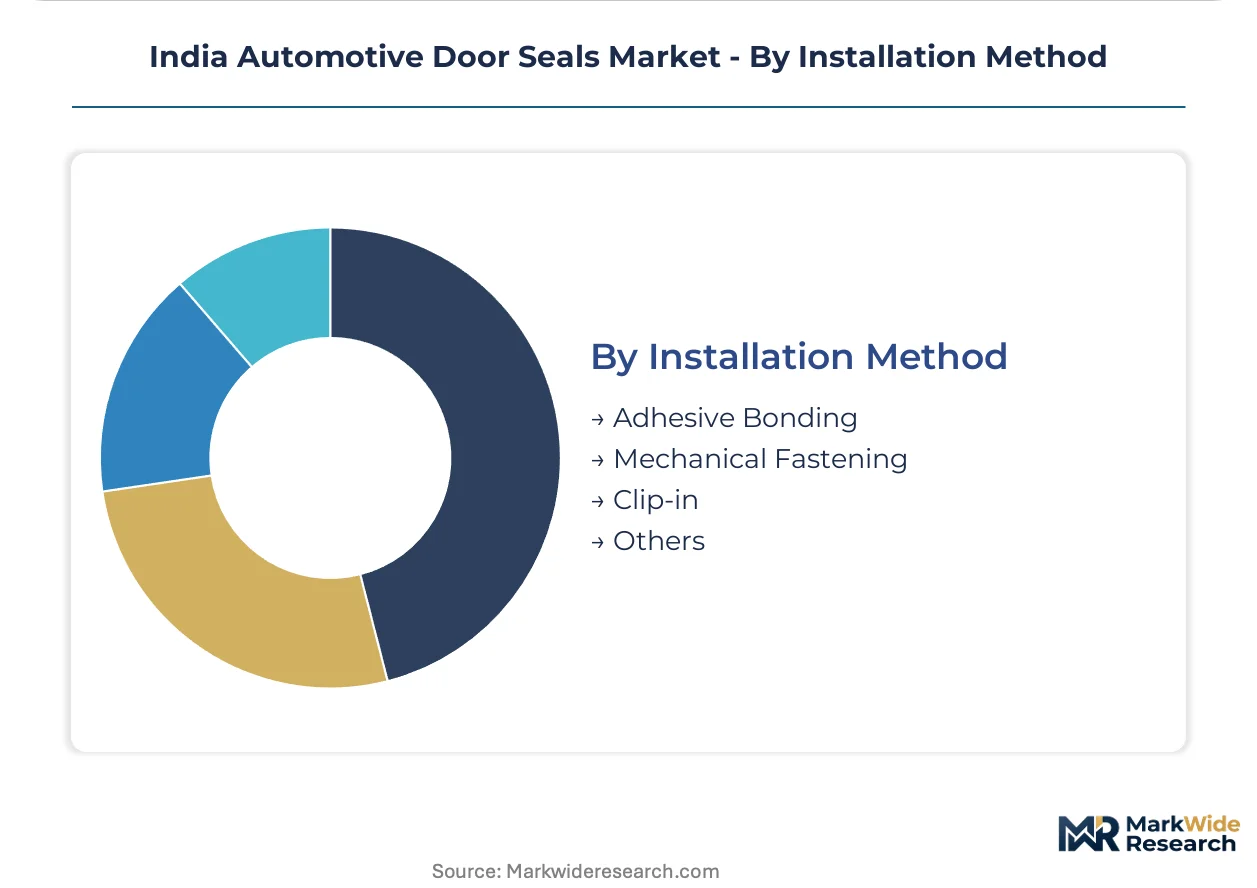
Installation Method:
Assembly-line efficiency versus field serviceability creates a bifurcated procurement landscape across manufacturing and aftermarket channels.
- Clip-in:Snap-fit attachment profiles enable robotic assembly at OEM lines with cycle times under 12 seconds per door. The format absorbs margin from conventional bonded assemblies by eliminating secondary clipping operations.
- Adhesive Bonding:Pressure-sensitive adhesive systems retain aftermarket share where field replacement without specialized tooling matters. Fleet operators in Bengaluru-Mysuru corridors favor this format for scheduled maintenance windows.
- Mechanical Fastening:Screw and rivet attachments serve heavy commercial vehicle applications with extreme vibration environments.
- Others:Magnetic and heat-activated bonding formats capture niche segments in concept vehicles and low-volume specialty builds.
Leading by OEM adoption: Clip-in. Gaining share fastest: Adhesive Bonding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tamil Nadu's Sriperumbudur-Oragadam special economic zone concentrates over forty percent of India's passenger vehicle assembly capacity, drawing sealing suppliers into co-located manufacturing corridors. The state's electronics manufacturing cluster policy extends to automotive component zones, compressing logistics costs for just-in-sequence delivery.
Tamil Nadu
Hyundai Motor India and Renault-Nissan anchor demand for multi-durometer co-extrusion profiles across the Chennai-Aurangabad belt. The state's EV policy offers capital subsidies up to twenty percent for battery component manufacturing, redirecting supplier investments toward high-voltage sealing specifications. Sriperumbudur's integrated automotive park hosts three domestic sealing compounders serving Maruti Suzuki's platform requirements.
Maharashtra
Tata Motors and Mahindra & Mahindra drive specification authority for electric vehicle battery compartment sealing in the Pune-Nashik corridor. The state's electric vehicle policy mandates localized component sourcing for fleet procurement eligibility, conditioning supplier location decisions. Chakan's supplier park concentrates extrusion operations within fifteen kilometers of OEM assembly lines.
Gujarat
Tata Motors' Sanand facility and emerging battery plants generate whitespace demand for specialized ingress protection systems. The state's industrial policy offers land allotment priority to automotive component manufacturers establishing compounding operations. Halol's underpenetrated supplier base rewards early entrants with dedicated logistics contracts serving western India distribution.
Karnataka
Toyota Kirloskar and ride-hailing fleet aggregators reshape procurement toward lifecycle cost guarantees exceeding three hundred thousand kilometers. The state's electric vehicle policy targets complete vehicle manufacturing ecosystem development by 2030, mandating component localization milestones. Bengaluru-Mysuru corridor fleet operators consolidate purchasing across fifteen-thousand-vehicle pools, favoring suppliers with predictive wear monitoring capabilities.
Haryana
Maruti Suzuki's Gurugram and Manesar facilities maintain specification authority for legacy internal combustion platforms. The state's industrial infrastructure development policy prioritizes automotive supplier zone expansion along the Delhi-Mumbai industrial corridor. IMT Manesar hosts two EPDM compounders serving northern India aftermarket channels through bonded distribution networks.
India Automotive Door Seals Market Competitive Environment
Top-tier vendors anchor platform-specific supply agreements with five-to-seven-year contract horizons, while mid-tier compounders compete on aftermarket retrofit volumes and fleet service contracts. The market structures around material chemistry specialization, with EPDM incumbents defending thermal stability credentials against TPE challengers emphasizing recyclability compliance. Three archetypes dominate: integrated polymer compounders with captive extrusion, specialized sealing system suppliers bundling weatherstrip modules, and regional molders serving aftermarket price-sensitive segments. Competitive moves concentrate on co-extrusion capacity expansion and PLI scheme qualification for advanced material production.
Among multinational system suppliers, Hutchinson and Cooper Standard occupy positions exemplifying integrated polymer compounding and localized TPE production archetypes respectively. Gold Seal Engineering Products Pvt. Ltd. represents the domestic specialist tier, anchoring regional supply relationships through compounded EPDM formulations. These three entities illustrate the competitive spectrum from global platform integration to regional aftermarket penetration.
| Leading Market Players |
|---|
| Gates Corporation |
| Hutchinson |
| Cooper Standard |
| Gold Seal Engineering Products Pvt. Ltd. |
| Toyoda Gosei |
| Vibracoustic |
| ElringKlinger AG |
| Nippon Sealing |
| Dura Automotive Systems |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap compounders in Tamil Nadu and Maharashtra anchor supply-side pricing discipline through generational control over captive EPDM formulation knowledge, insulating them from short-term margin erosion while concentrating procurement leverage among Chennai-Aurangabad corridor OEMs. This ownership pattern reinforces long-term contract structures that resist spot-market volatility in ethylene-propylene feedstock cycles.
Pricing Analysis
Premium pricing for sub-8-week prototyping lead times compresses margins on standard-volume contracts, creating a bifurcated structure. Three-tier pricing separates UL 94 HB-certified EV battery seals from standard EPDM profiles and PVC aftermarket formats. Cost compression in commercial vehicle retrofit tiers is intensifying because fleet aggregators consolidate 15,000-vehicle procurement pools. Aftermarket adhesive-bonding buyers exhibit highest price sensitivity; OEM platform engineers show lowest sensitivity due to 5-7 year contract lock-ins.
Supply Chain Analysis
BIS certification timelines of 14-18 months for novel TPE formulations gate supplier qualification, concentrating viable production among three domestic petrochemical complexes in Tamil Nadu, Maharashtra, and Gujarat. EPDM compounding draws from ethylene-propylene feedstock, halogen-free flame retardant loadings, and dual-hardness co-extrusion dies. Single-source vulnerability concentrates in ethylene-propylene supply synchronized to crude price cycles. Distribution runs through just-in-sequence delivery corridors co-located with Sriperumbudur-Oragadam and Pune-Nashik assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS material standards and PLI scheme localization requirements erect a cost-of-compliance moat that rewards incumbent compounders with certified EPDM formulations while filtering out undercapitalized challengers unable to sustain 18-month validation cycles.
For Market Incumbents: To counter TPE-based recyclability mandates from Maharashtra EV startups, anchor position through captive co-extrusion capacity expansion in Gujarat's Sanand corridor and accelerate UL 94 HB recertification for halogen-free EPDM variants serving battery compartment specifications. For New Entrants and Emerging Players: Capture whitespace in Karnataka's Bengaluru-Mysuru fleet lifecycle guarantee segment by offering predictive wear monitoring bundled with 300,000-kilometer replacement programs, bypassing OEM platform engineering barriers through direct aggregator procurement channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier EPDM compounders with BIS certification histories in Haryana's IMT Manesar zone, where Maruti Suzuki legacy contract renewal windows create acquisition timing. Watch PLI scheme disbursement velocity as inflection signal for localized advanced material production viability.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Extrusion Capacity Expansion | Dual-hardness profile capability secures Chennai-Aurangabad OEM platform contracts with Shore A variance below 3 points. |
| Backward Integration into EPDM Compounding | Captive ethylene-propylene formulation control insulates margin from petrochemical complex price synchronization. |
| UL 94 HB Certification Investment | Flame resistance validation unlocks Maharashtra EV battery compartment specifications absent in legacy supply chains. |
| Just-in-Sequence Logistics Co-Location | Sriperumbudur-Oragadam proximity compresses delivery cycles under 12 seconds per door for Hyundai Motor India. |
| Predictive Wear Monitoring Service | Lifecycle cost guarantee bundling captures Karnataka fleet aggregator consolidation across 15,000-vehicle pools. |
Study Parameters
Multi-period observation of vehicle platform launch cadence, BIS certification pipeline velocity, and PLI scheme disbursement patterns anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and EPDM compounding plant managers. Secondary validation incorporated Automotive Industry Standards committee filings, Ministry of Road Transport regulatory circulars, vehicle production databases from IHS Markit, and customs records tracking ethylene-propylene feedstock imports. Bottom-up segment sizing triangulated against top-down automotive OEM purchasing data.
Segment-weighting across material chemistry, supply chain tier, vehicle architecture, and installation method shaped the analytical framework throughout the projection horizon. CAGRs derived from production volume trajectories by propulsion architecture and content-per-vehicle assumptions for sealing profile complexity. Industry-specific inputs included EV platform rollout schedules in Tamil Nadu and Maharashtra, and BIS amendment timelines for automotive elastomer flame resistance protocols.
The model holds under sustained PLI scheme funding and stable crude-to-ethylene feedstock pricing; deviation in BIS certification timeline compression or EPDM raw material concentration disruption would shift supplier viability thresholds. A model refresh is warranted upon material change in Extended Producer Responsibility enforcement stringency or crash safety regulation integration of door seal compression behavior into side-impact ratings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Baggage Handling System Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market