
 Overhead Console Market | 2026-2036
Overhead Console Market Size, Share, and Industry Trends Forecast 2026-2036
Overhead Console Market Analysis
Fleet operators and luxury automotive OEMs are reorganizing procurement priorities around modular overhead console architectures. Yanfeng Automotive Interiors leverages integrated electronics expertise to capture design-in relationships with premium vehicle platforms. Magna International Inc. sustains manufacturing scale across North American and European assembly corridors. Johnson Controls International plc anchors its position through thermal and acoustic management technologies bundled with overhead systems.
An overhead console is a cabin-mounted assembly, typically molded from ABS or polycarbonate blends, that houses lighting controls, storage compartments, and electronic interfaces above the occupant seating area. The unit serves as both a functional storage surface and a routing hub for wiring harnesses connecting to dome lamps and sunroof motors. Premium and modular product types command the strongest margin pools as automakers shift from fixed configurations to scalable architectures that accommodate feature upgrades across trim levels. Composite and plastic materials dominate volume production while metal substrates retain share in commercial vehicle applications where durability requirements exceed weight sensitivity.
NHTSA and FMVSS 302 in the United States, ECE R21 and REACH across Europe, and China's GB standards for interior component safety collectively govern material flammability, head impact criteria, and chemical substance restrictions in overhead console manufacturing. OEMs must certify each design against these overlapping regimes before platform approval, extending development timelines and favoring suppliers with established homologation capabilities. Stakeholders should monitor regulatory divergence between crash safety and sustainability mandates as the primary uncertainty affecting platform investment decisions.
Market Dynamics
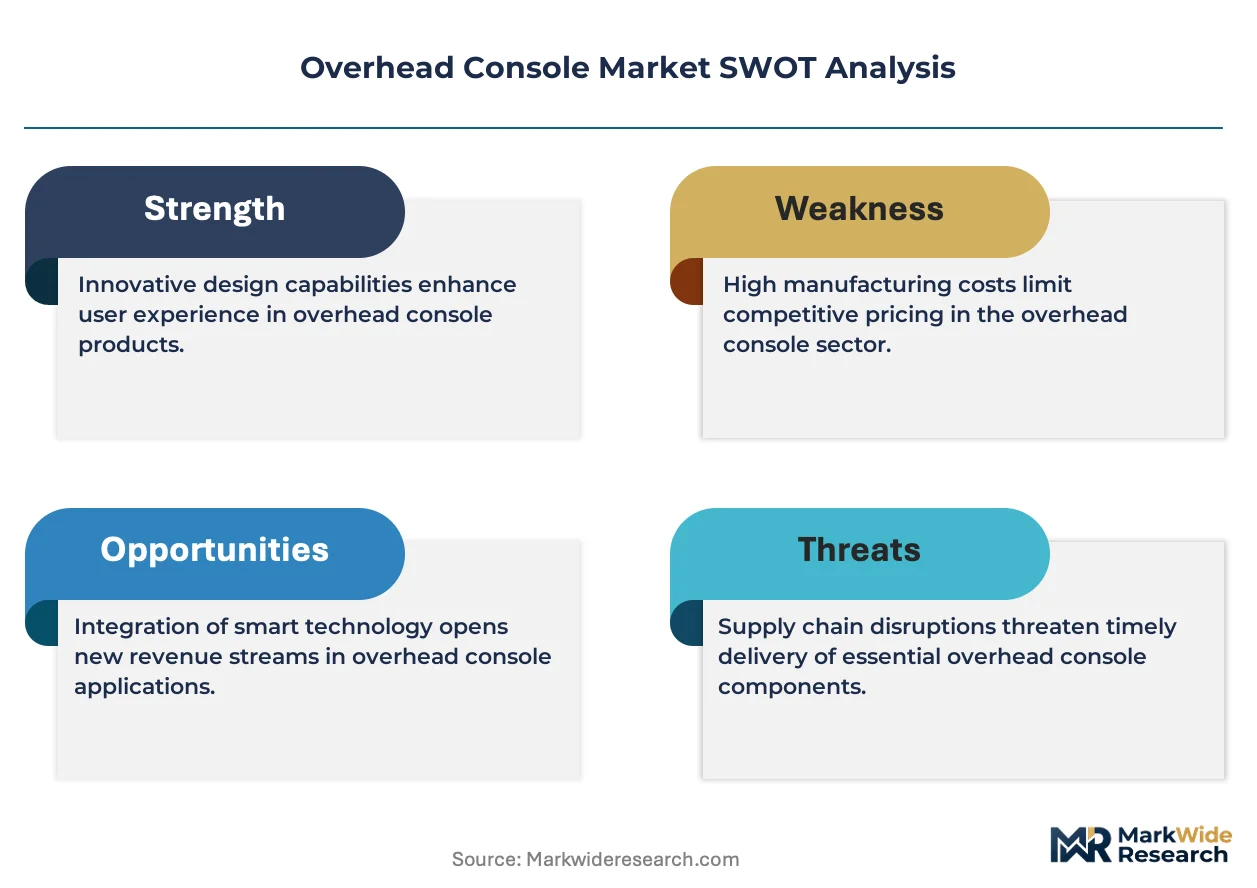
Modular overhead console architectures are restructuring supplier-OEM relationships as automakers demand scalable platforms that accommodate feature upgrades across trim levels without complete redesign cycles.
Growth Catalysts
- FMVSS 302 Compliance:United States flammability mandates are accelerating adoption of engineered thermoplastics with inherent fire-retardant properties in premium vehicle programs.
- Ambient Lighting Integration:Luxury OEM specifications now require LED-embedded console assemblies, expanding value-per-unit and design-in opportunities for electronics-capable suppliers.
- Germany Premium Cluster:Stuttgart and Munich-based automakers are standardizing overhead electronics modules across entire nameplates, creating volume pull for tier-one interior systems.
Market Restraints
- ABS Resin Volatility:Crude oil-linked feedstock costs for acrylonitrile and butadiene create margin compression for molded component producers without long-term supply agreements.
- Homologation Timeline Friction:Overlapping NHTSA head-impact criteria and ECE R21 safety certifications extend platform approval cycles, freezing design iterations for 18-24 months.
- Polycarbonate Substitution Pressure:Lower-cost PP-EPDM blends are capturing share in economy vehicle segments where optical clarity requirements are minimal.
Strategic Opportunities
- India Premium Passenger Segment:Domestic OEMs are localizing overhead console production for compact SUVs, creating white space for modular architecture suppliers with JIS-standard experience.
- REACH Chemical Compliance:European substance restrictions are favoring suppliers with established material traceability systems, creating competitive moats against unqualified entrants.
- Smart Surface Convergence:Capacitive touch interfaces and haptic feedback systems are merging with traditional console housings, enabling new pricing tiers for integrated human-machine interface modules.
Industry Challenges
- Tooling Amortization Burden:Multi-cavity injection molds for complex console geometries require capital deployment exceeding typical component categories, squeezing mid-tier suppliers.
- Electronics-Wiring Integration Complexity:Legacy harness routing protocols conflict with modular plug-and-play architectures, forcing costly vehicle-level electrical system redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overhead Console Market |
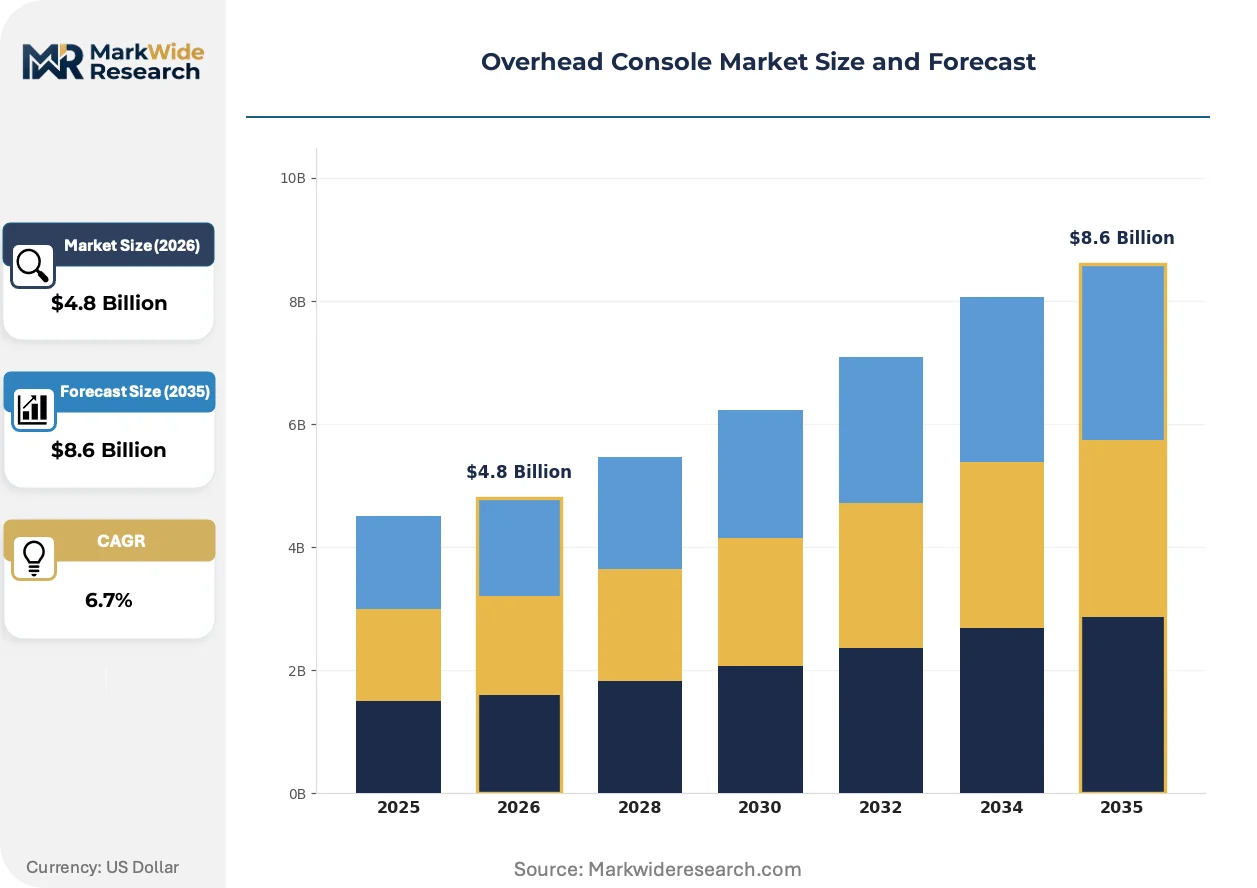
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Premium, Modular, Integrated Material: Plastic, Metal, Composite, Fabric Application: Automotive, Aircraft, Marine, Commercial Vehicles End User: OEMs, Aftermarket, Fleet Operators, Distributors |
| Companies Covered | Johnson Controls International plc, Yanfeng Automotive Interiors, Magna International Inc., Lear Corporation, Hella GmbH & Co. KGaA, Grupo Antolin, Continental AG, Visteon Corporation, Gentex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overhead Console Market Emerging Trajectories
Overhead console engineering is pivoting from passive storage housings to active electronic interface platforms, with material science and regulatory compliance converging to reshape competitive requirements.
Polycarbonate-ABS blends with enhanced thermal stability are bifurcating the material landscape. Tier-one suppliers serving German luxury OEMs have adopted these engineered thermoplastics for heat-resistant LED integration zones. The technology is bifurcating supplier tiers into electronics-capable integrators versus commodity molders.
REACH substance restrictions and GB standards for interior component safety are tightening material disclosure requirements. European and Chinese regulators now mandate full chemical composition documentation for flame-retardant additives. Premium vehicle programs in both jurisdictions are responding by qualifying alternative halogen-free formulations ahead of compliance deadlines.
Fleet operators are consolidating procurement around single-source modular platform suppliers capable of spanning multiple vehicle nameplates. Direct OEM contracts are displacing tier-two distributor relationships in North American commercial vehicle segments. This concentration is most visible among rental and logistics fleets operating standardized light-truck platforms across multi-state networks.
Overhead Console Market Segmentation
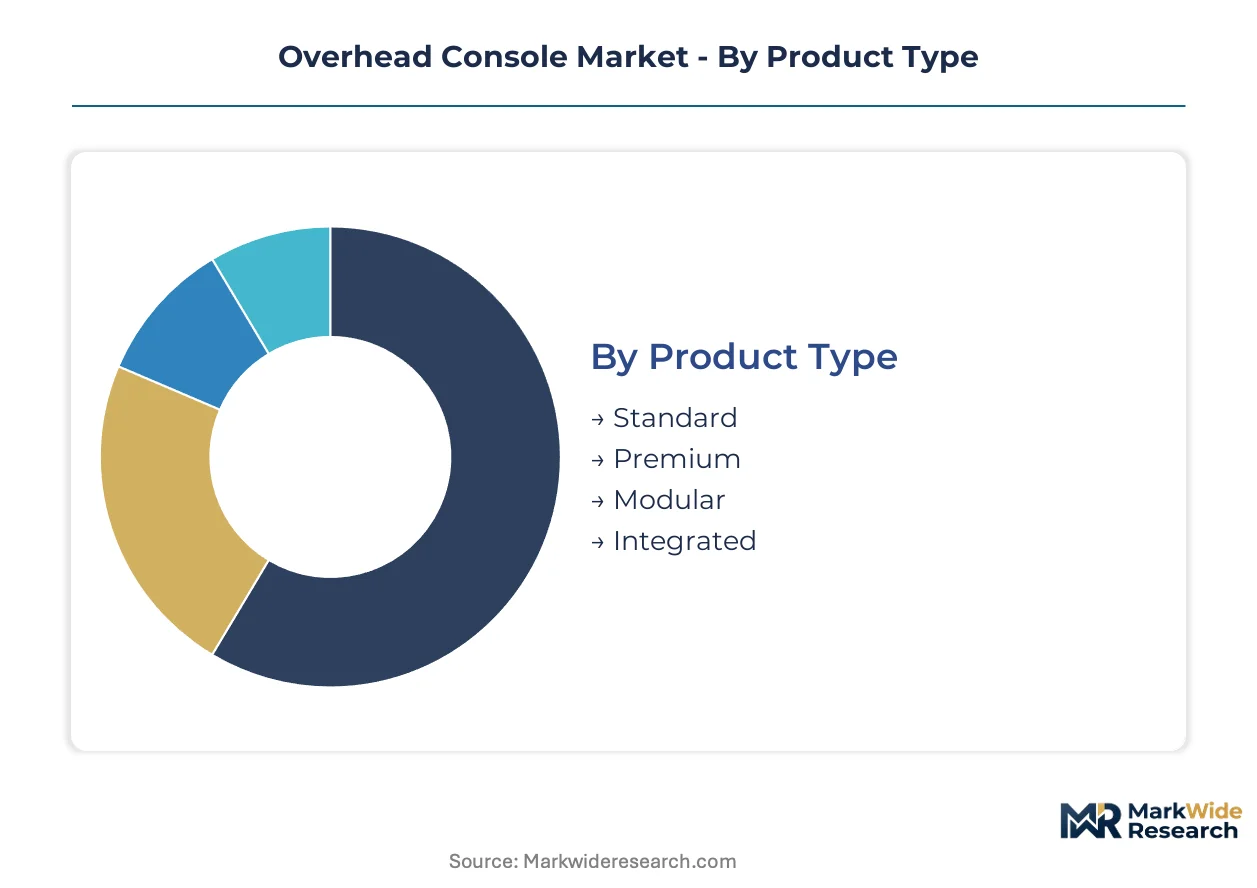
Overhead console procurement patterns diverge sharply across vehicle tiers and material specifications. Suppliers must align production capabilities with distinct certification requirements and volume scales that separate premium automotive programs from commercial vehicle fleets.
Product Type:
Modular architectures face intensifying substitution pressure from integrated electronic platforms as OEMs consolidate wiring and interface functions into single assemblies.
- Standard:Fixed-configuration housings molded from ABS blends serve economy vehicle nameplates where feature content remains static across model years. Demand concentrates in high-volume compact car production across Mexico and Eastern European assembly corridors, constrained by polycarbonate substitution in adjacent segments.
- Premium:LED-embedded assemblies with soft-touch surfaces and ambient lighting zones command design-in relationships with German and Japanese luxury nameplates. Stuttgart-based OEMs now specify these units across entire vehicle families, pulling volume toward electronics-capable tier-one suppliers.
- Modular:Scalable platforms accommodate feature upgrades across trim levels without tooling redesign, capturing fleet operator procurement consolidation in North American light-truck segments.
- Integrated:Combined storage-electronics units merge capacitive touch interfaces with traditional console functions, gaining specification in electric vehicle platforms where cabin space optimization is critical.
Standard configurations retain volume leadership; Integrated represents the fastest-growing trajectory.
Material:
Cost tier stratification separates commodity resin suppliers from engineered thermoplastic specialists serving regulatory-intensive applications.
- Plastic:ABS and polycarbonate blends dominate passenger vehicle production, with FMVSS 302 compliance mandating fire-retardant formulations in United States-bound nameplates. REACH substance restrictions are accelerating halogen-free additive qualification cycles.
- Metal:Aluminum and steel substrates persist in commercial vehicle and marine applications where impact resistance exceeds weight sensitivity. Fleet operators in United States logistics corridors specify metal-reinforced units for durability under severe duty cycles.
- Composite:Glass-fiber-reinforced polymers bridge weight and strength requirements in aircraft cabin retrofits.
- Fabric:Textile-wrapped surfaces serve aftermarket customization channels and premium automotive programs seeking acoustic dampening.
Plastic commands the widest specification base; Composite is climbing the fastest in aerospace retrofit demand.
Application:
Volume concentration patterns differ materially between passenger automotive scale and specialized transport durability requirements.
- Automotive:Passenger vehicle nameplates generate the foundational demand pool, with overhead electronics integration expanding across compact SUV and electric vehicle platforms. German and Japanese OEMs drive specification complexity through ambient lighting mandates.
- Aircraft:Cabin retrofit programs and new narrow-body deliveries require lightweight assemblies meeting FAA flammability and smoke toxicity standards. Composite material adoption is accelerating in this channel.
- Marine:Salt-corrosion resistance dictates sealed housing designs for recreational and commercial vessel applications.
- Commercial Vehicles:Fleet-standardized platforms across United States rental and logistics networks favor modular architectures with standardized wiring protocols.
Automotive anchors absolute volume; Aircraft is expanding most quickly on narrow-body delivery schedules.
End User:
Procurement authority is concentrating at the OEM level as direct supplier relationships displace tier-two distributor networks.
- OEMs:Original equipment manufacturers hold design control and volume commitment, with German and Japanese automakers standardizing overhead electronics modules across nameplate families. NHTSA and ECE R21 homologation requirements favor suppliers with established certification track records.
- Aftermarket:Customization channels and vehicle retrofit programs serve aging fleet populations, with fabric-wrapped and ambient lighting upgrades gaining traction in premium vehicle segments.
- Fleet Operators:Rental and logistics consolidators in United States multi-state networks are single-sourcing modular platforms across standardized light-truck nameplates.
- Distributors:Tier-two channels are losing share to direct OEM contracts, though regional distributors persist in fragmented aftermarket geographies.
OEMs retain procurement dominance; Fleet Operators are gaining share fastest through consolidation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tier-one suppliers export modular overhead console architectures to United States-based luxury OEMs, establishing the primary transatlantic trade corridor in cabin electronics integration.
United States
NHTSA FMVSS 302 flammability mandates and head-impact criteria drive material selection toward engineered thermoplastics with inherent fire-retardant properties. Detroit-based OEMs consolidate procurement around single-source modular platform suppliers capable of spanning multiple light-truck nameplates. Michigan and Ohio assembly corridors concentrate electronics-capable tier-one manufacturing.
Germany
Stuttgart and Munich-based automakers standardize LED-embedded overhead electronics modules across entire vehicle families, pulling volume toward suppliers with homologation expertise. ECE R21 safety certifications and REACH chemical substance restrictions govern material disclosure requirements. Bavaria and Baden-Württemberg host the densest concentration of interior systems engineering.
Japan
Domestic OEMs specify premium overhead console configurations with integrated ambient lighting for compact SUV and electric vehicle platforms. METI industrial standards and JIS certification protocols shape supplier qualification timelines. Aichi Prefecture and the Kanto region anchor production of electronics-integrated cabin modules.
China
GB standards for interior component safety mandate full chemical composition documentation for flame-retardant additives in overhead console manufacturing. Domestic OEMs localize production for premium passenger segments while importing modular architectures from German and Japanese partners. Yangtze River Delta and Pearl River Delta clusters concentrate molded component fabrication.
India
Compact SUV localization programs create procurement opportunities for modular architecture suppliers with JIS-standard experience. BIS certification requirements and PLI scheme incentives favor domestic manufacturing scale-up. Maharashtra and Tamil Nadu assembly corridors attract tier-one interior systems investment.
Overhead Console Market Vendor Landscape
Listed leaders compete with private specialists across electronics integration capabilities, creating a tiered structure where scale-driven manufacturers and niche technology providers occupy distinct competitive positions. Consolidation pressures favor suppliers with established NHTSA and ECE R21 homologation track records. Three archetypes dominate: electronics-capable integrators serving luxury OEMs, commodity molders focused on high-volume economy segments, and modular platform specialists targeting fleet operator consolidation. M&A activity concentrates on acquiring homologation expertise, while strategic partnerships address electronics-wiring integration complexity.
Among the electronics-capable integrators, Yanfeng Automotive Interiors and Johnson Controls International plc exemplify the tier-one archetype with bundled thermal, acoustic, and electronic management capabilities. Magna International Inc. represents the scale-driven manufacturing archetype with North American and European assembly corridor presence. These three entities anchor the competitive landscape through distinct positioning: Yanfeng through integrated electronics expertise, Johnson Controls through technology bundling, and Magna through manufacturing scale across premium vehicle platforms.
| Leading Market Players |
|---|
| Johnson Controls International plc |
| Yanfeng Automotive Interiors |
| Magna International Inc. |
| Lear Corporation |
| Hella GmbH & Co. KGaA |
| Grupo Antolin |
| Continental AG |
| Visteon Corporation |
| Gentex Corporation |
| Others |
Supply Flow & Price Mechanics
PP-EPDM blend substitution for polycarbonate in economy vehicle segments is simultaneously redrawing supply geography toward Southeast Asian resin producers and compressing pricing economics for commodity molders serving cost-sensitive OEM programs. This material shift bifurcates procurement patterns, with premium platforms absorbing engineered thermoplastic premiums while standard nameplates chase feedstock cost advantages.
Pricing Analysis
Current-generation LED-embedded premium assemblies command substantial premiums over prior-generation fixed-configuration housings, while next-generation integrated smart-surface modules are establishing new pricing tiers through capacitive interface bundling. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FMVSS 302 and ECE R21 compliance tiers separating price bands. Cost compression in economy segments is intensifying because PP-EPDM substitution erodes polycarbonate volume leverage. Fleet operators exhibit highest price sensitivity through consolidated procurement mandates, while German luxury OEMs demonstrate lowest sensitivity via design-in relationships with electronics-capable integrators.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta and Pearl River Delta ports to North American assembly corridors are constraining just-in-time delivery windows for molded component suppliers. Supply concentrates in China, Germany, and Mexico, with ABS resin and polycarbonate feedstock drawing from petrochemical corridors in South Korea and Thailand. Single-source vulnerability sits with specialized LED driver module suppliers serving premium electronics integration zones. Distribution runs through tier-one interior systems integrators with direct OEM contracts displacing tier-two distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation across standardized light-truck platforms has shifted buyer power decisively toward volume aggregators, fragmenting pricing leverage for undifferentiated component suppliers.
For Market Incumbents: Secure NHTSA and ECE R21 homologation track records as defensive moats against emerging electronics-capable entrants from Asia-Pacific. Acquire backward integration into ABS compound formulation to offset crude oil-linked feedstock volatility. Channel control through direct OEM relationships represents the critical lever for margin defense against distributor displacement. For New Entrants and Emerging Players: Differentiate on REACH-compliant halogen-free material traceability systems to capture specification share in European premium vehicle programs. Target India's compact SUV localization white space through JIS-standard modular architecture partnerships. A fleet operator direct-contract go-to-market angle bypasses entrenched tier-two distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed commodity molders lacking electronics integration capabilities and facing margin compression from resin volatility. Long-term viability favors suppliers with homologation expertise and scalable modular platforms across the analysis window. Monitor fleet operator single-sourcing announcements as inflection signals for platform consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Enables scalable feature upgrades across trim levels without tooling redesign cycles. |
| Electronics Integration Partnership | Merges capacitive touch interfaces with traditional console housings for EV platforms. |
| REACH-Compliant Material Transition | Qualifies halogen-free flame-retardant formulations ahead of European substance restrictions. |
| Geographic Manufacturing Footprint | Localizes production in Maharashtra and Tamil Nadu corridors for India premium segments. |
| Homologation Capability Buildout | Accelerates NHTSA and ECE R21 certification timelines to capture design-in relationships. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-one supplier procurement leads, fleet operator consolidation managers, and aftermarket distribution channel heads converged on the working assumptions governing volume and value trajectories. Primary field engagement combined with secondary validation from vehicle production databases, customs and trade flow records, regulatory filing repositories, and interior systems engineering disclosures established foundational inputs. Bottom-up segment sizing and top-down macroeconomic triangulation cross-verified output ranges.
Segmentation dimensions modeled span product type, material specification, application vehicle class, and end-user procurement authority across the projection horizon. CAGRs derived from regression analysis against historical production volumes and content-per-vehicle trends. Industry-specific forecast inputs incorporate OEM platform lifecycle schedules and fleet operator standardization mandates.
The analysis sits within stated boundaries; outcomes outside sustained modular architecture adoption or regulatory divergence between crash safety and sustainability mandates would require recalibration. Forecasts reflect documented assumptions about resin cost trajectories and homologation timeline stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Door Frame Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Train Seat Materials Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
LED Fog Lamp Market