
 Automotive Electric Actuator Market | 2026-2036
Automotive Electric Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric Actuator Market Analysis
Aftermarket service revenue is rewriting how actuator suppliers capture lifetime value from electrified vehicle fleets. Robert Bosch GmbH leverages its remanufacturing network to extend actuator service coverage across hybrid platforms. Continental AG anchors its position through direct OEM channel control in European powertrain electronics. Denso Corporation competes on manufacturing scale in brushless DC motor assemblies for thermal management actuators.
An automotive electric actuator is an electromechanical device that converts electrical energy into precise mechanical motion, typically operating at voltages between 12V and 48V with positional accuracy within 0.1 millimeters to control valves, throttles, and HVAC flaps in vehicle systems. Its primary purpose is to enable automated, software-controlled responses to sensor inputs without hydraulic or pneumatic intermediaries. Smart actuators lead product type margins by integrating position feedback and diagnostic protocols that reduce wiring complexity. Rotary actuators dominate volume in turbocharger wastegate and throttle body applications where angular positioning replaces legacy cable linkages.
The US NHTSA and EPA jointly shape actuator demand through fuel economy enforcement and emissions test protocols that require precision airflow control. Europe's ECHA REACH restrictions on heavy metals in electronics push suppliers toward lead-free solder and rare-earth-reduced motor designs. China's MIIT enforces GB standards for new energy vehicle electromagnetic compatibility that filter non-compliant actuator imports. Stakeholders must monitor how software-defined vehicle architectures shift actuator procurement from hardware-specified components to firmware-updatable smart modules.
Market Dynamics
Software-defined vehicle architectures are collapsing the traditional hardware procurement model for electric actuators, forcing tier-one suppliers to restructure R&D roadmaps around firmware-updatable smart modules rather than fixed electromechanical specifications.
Growth Catalysts
- ADAS Integration Mandates:OEM procurement for advanced driver assistance systems is accelerating as automakers electrify powertrain architectures and require precision electromechanical control for automated steering and braking functions.
- China's Component Localization:MIIT mandates on new energy vehicle component localization are redirecting supply chain investment toward domestic actuator manufacturing capabilities.
- Brushless DC Motor Advances:Manufacturing scale improvements in brushless DC motor assemblies are reducing unit costs for thermal management actuators deployed across hybrid and battery-electric platforms.
Market Restraints
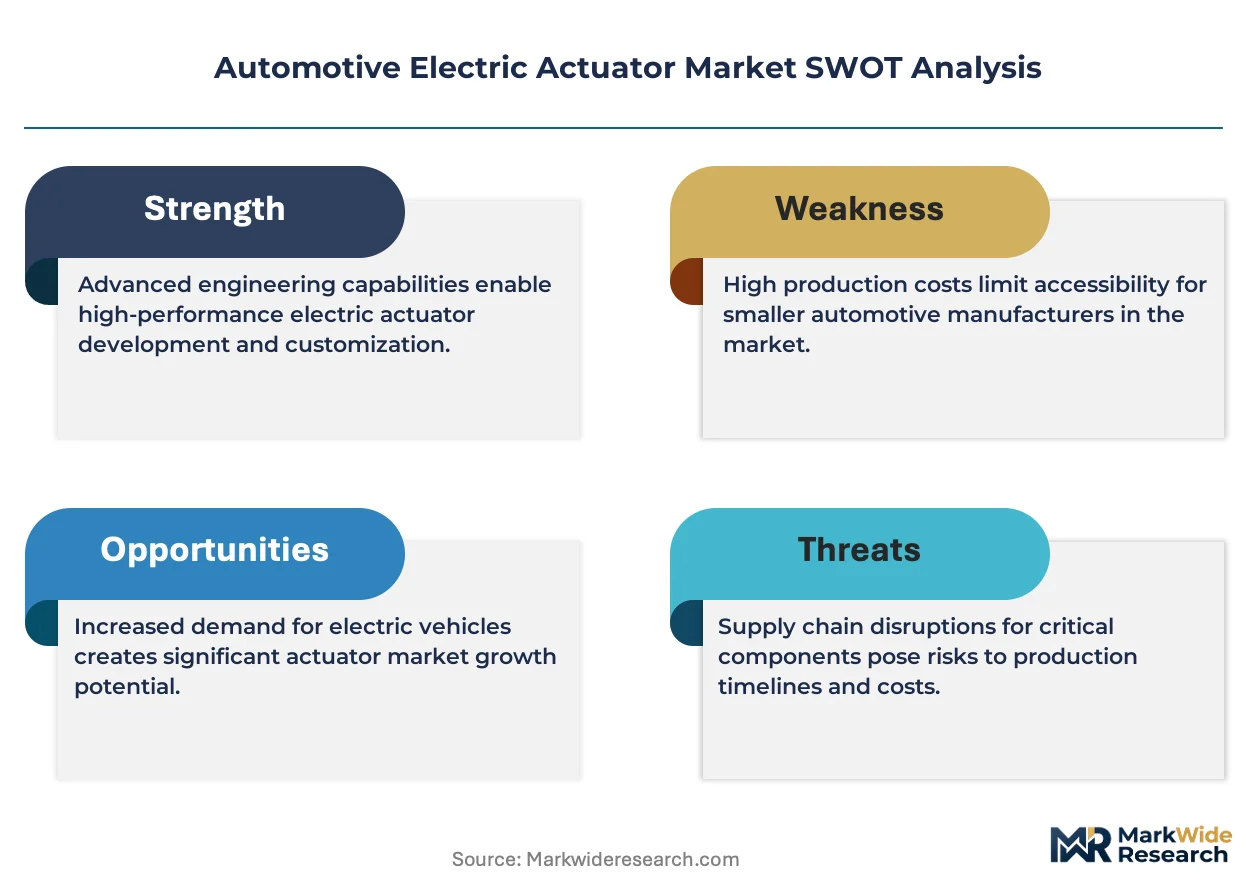
- Rare Earth Supply Concentration:Permanent magnet motors depend on neodymium and dysprosium processing concentrated in China, creating input cost volatility and geopolitical exposure for motor suppliers.
- REACH Compliance Burden:Europe's ECHA REACH restrictions on heavy metals in electronics force redesign cycles for lead-free solder and rare-earth-reduced motor designs, extending certification timelines.
- Hydraulic Actuator Residual Demand:Heavy commercial vehicles and off-highway equipment continue specifying hydraulic actuators for high-torque applications, limiting electric actuator penetration in these segments.
Strategic Opportunities
- Remanufacturing Service Networks:Aftermarket revenue capture through remanufacturing programs extends lifetime value from electrified vehicle fleets as hybrid platforms age and require actuator replacement.
- 48V Mild-Hybrid Expansion:European OEM platforms are expanding 48V electrical architectures that demand higher-voltage actuators for turbocharger wastegate and active grille shutter applications.
- GB Standard Compliance Export:China's MIIT enforcement of GB standards for electromagnetic compatibility creates a regulatory moat for domestic suppliers qualified under these protocols.
Industry Challenges
- Embedded Software Talent Scarcity:Smart actuator development requires mechatronics engineers proficient in control algorithms and automotive cybersecurity, a skill set concentrated at premium technology employers.
- Legacy Platform Integration Complexity:Firmware-updatable actuators must maintain backward compatibility with 12V electrical architectures and legacy vehicle communication buses, multiplying validation requirements.
- ISO 26262 Certification Timelines:Functional safety certification for automotive-grade actuators demands extensive failure mode analysis and hardware-in-the-loop testing that extends product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Actuator Market |
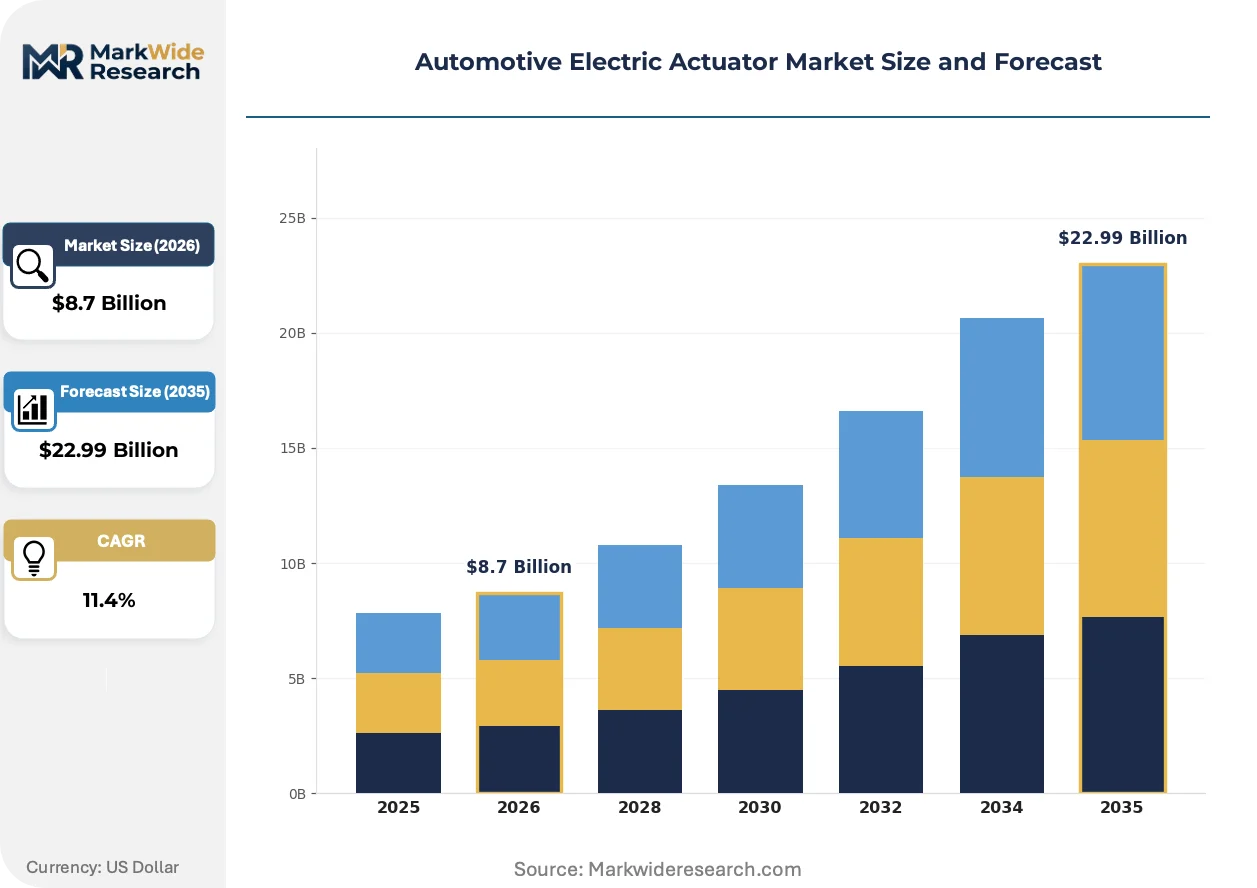
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Smart Actuators, Piezoelectric Actuators Technology: Electric, Electromechanical, Digital, Analog End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Johnson Electric Holdings Limited, HELLA GmbH & Co. KGaA, Mitsubishi Electric Corporation, BorgWarner Inc., Nidec Corporation, Stoneridge Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Actuator Market Emerging Trajectories
Actuator intelligence migration from centralized vehicle controllers to edge devices is compressing wiring harness complexity while elevating cybersecurity requirements for electromechanical suppliers.
Integrated position sensing with LIN bus communication is collapsing the discrete sensor-and-actuator supply chain into single-module procurement. European OEMs are specifying these smart actuators for HVAC flap control and active aerodynamics. This consolidation is eliminating separate sensor suppliers from tier-two positions and capturing margin previously distributed across multiple component vendors.
The US NHTSA and EPA joint enforcement of fuel economy test protocols is mandating precision airflow control that only closed-loop electric actuators can deliver. Powertrain engineers must demonstrate calibration accuracy within tight tolerances during regulatory audits. This pressure is accelerating rotary actuator deployment in throttle body and variable valve timing systems across Detroit Three production lines.
Fleet operators are unbundling actuator maintenance from comprehensive vehicle service contracts and negotiating direct aftermarket relationships with remanufacturing specialists. Commercial vehicle leasing companies in Germany are leading this shift, specifying actuator service level agreements separate from powertrain warranties. This disintermediation threatens traditional dealer service revenue streams and redirects parts margin toward authorized remanufacturing networks.
Automotive Electric Actuator Market Segmentation
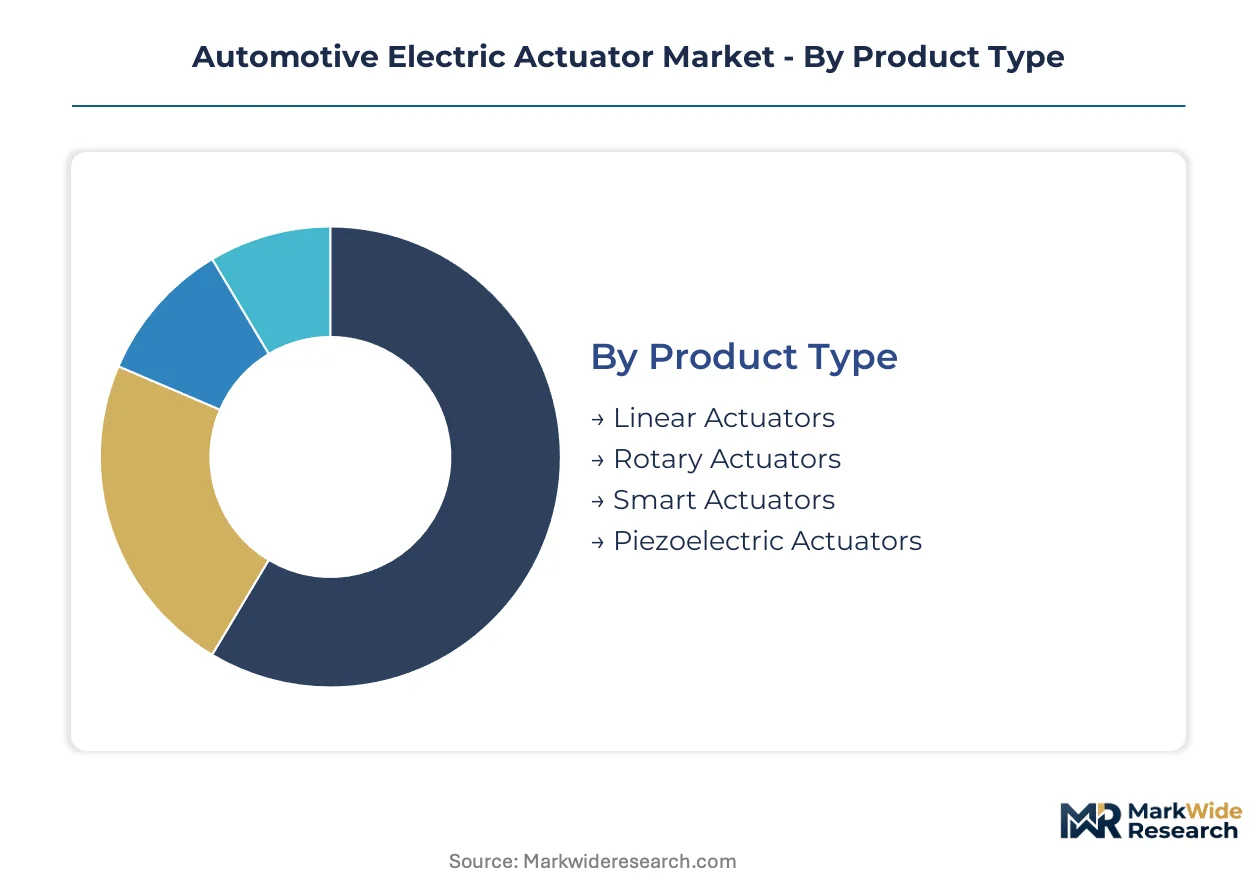
Segmentation reveals how actuator suppliers must align technical specifications with procurement channels and end-user requirements. Product architecture, control technology, and distribution pathways each create distinct margin profiles and competitive moats.
Product Type:
Actuator form factors span the motion spectrum from linear displacement to intelligent closed-loop systems.
- Linear Actuators:Convert rotational motor output into precise axial movement through lead screw or ball screw mechanisms, typically achieving positional accuracy within 0.1 millimeters. Demand concentrates in Germany's automotive engineering corridor for active grille shutter and HVAC vent applications, where thermal management efficiency drives specification.
- Rotary Actuators:Deliver angular positioning through direct-drive or geared motor assemblies, replacing legacy cable linkages in throttle body and turbocharger wastegate systems. OEM procurement for these units is accelerating across Detroit Three production lines as US NHTSA fuel economy enforcement mandates precision airflow control.
- Smart Actuators:Integrate position feedback sensors, LIN bus communication, and diagnostic protocols that reduce wiring complexity while enabling firmware updates.
- Piezoelectric Actuators:Utilize ceramic crystal deformation under electric field for nanometer-scale precision in fuel injection and optical alignment applications.
The dominant share belongs to Rotary Actuators, while Smart Actuators are gaining share fastest as software-defined vehicle architectures elevate edge intelligence requirements.
Technology:
Control methodology determines integration complexity and supplier R&D allocation.
- Electric:Pure motor-driven systems operating at 12V to 48V with straightforward PWM control, dominating volume in cost-sensitive thermal management applications.
- Electromechanical:Hybrid designs combining electric motors with mechanical reduction stages for high-torque positioning in active suspension and steering column adjustments.
- Digital:Microcontroller-based actuators with embedded software enabling position logging, predictive maintenance alerts, and over-the-air calibration updates.
- Analog:Legacy voltage-controlled designs maintaining backward compatibility with older vehicle electrical architectures and avoiding cybersecurity certification burdens.
Digital technology commands premium positioning, while Electromechanical systems are expanding most quickly through 48V mild-hybrid platform proliferation.
End User:
Procurement authority fragments across vehicle lifecycle stages and ownership models.
- OEMs:Direct specification of actuators for new vehicle platforms with multi-year supply agreements and integrated software validation requirements.
- Aftermarket Providers:Remanufacturing specialists and independent distributors capturing replacement demand as hybrid fleets age and actuator service intervals compress.
- Fleet Operators:Commercial vehicle leasing companies unbundling actuator maintenance from comprehensive service contracts and negotiating direct remanufacturing relationships.
- Vehicle Assemblers:Contract manufacturers and regional assembly plants sourcing actuators through tier-one supplier channels with localized logistics requirements.
OEMs retain volume leadership, though Fleet Operators are climbing the fastest as electrified commercial vehicle penetration deepens.
Distribution Channel:
Channel strategy shapes margin capture and technical support intensity.
- Direct Sales:Tier-one suppliers like Robert Bosch GmbH and Continental AG maintaining OEM channel control with embedded engineering support and joint development programs.
- Distributors:Industrial electronics distributors stocking standardized actuator SKUs for tier-two suppliers and regional vehicle assemblers with shorter lead time requirements.
- Online Retail:E-commerce platforms serving independent repair shops and enthusiast segments with catalog-actuator replacements and cross-reference tools.
- Specialty Stores:Automotive parts retailers with counter service and technical diagnostics for walk-in aftermarket demand.
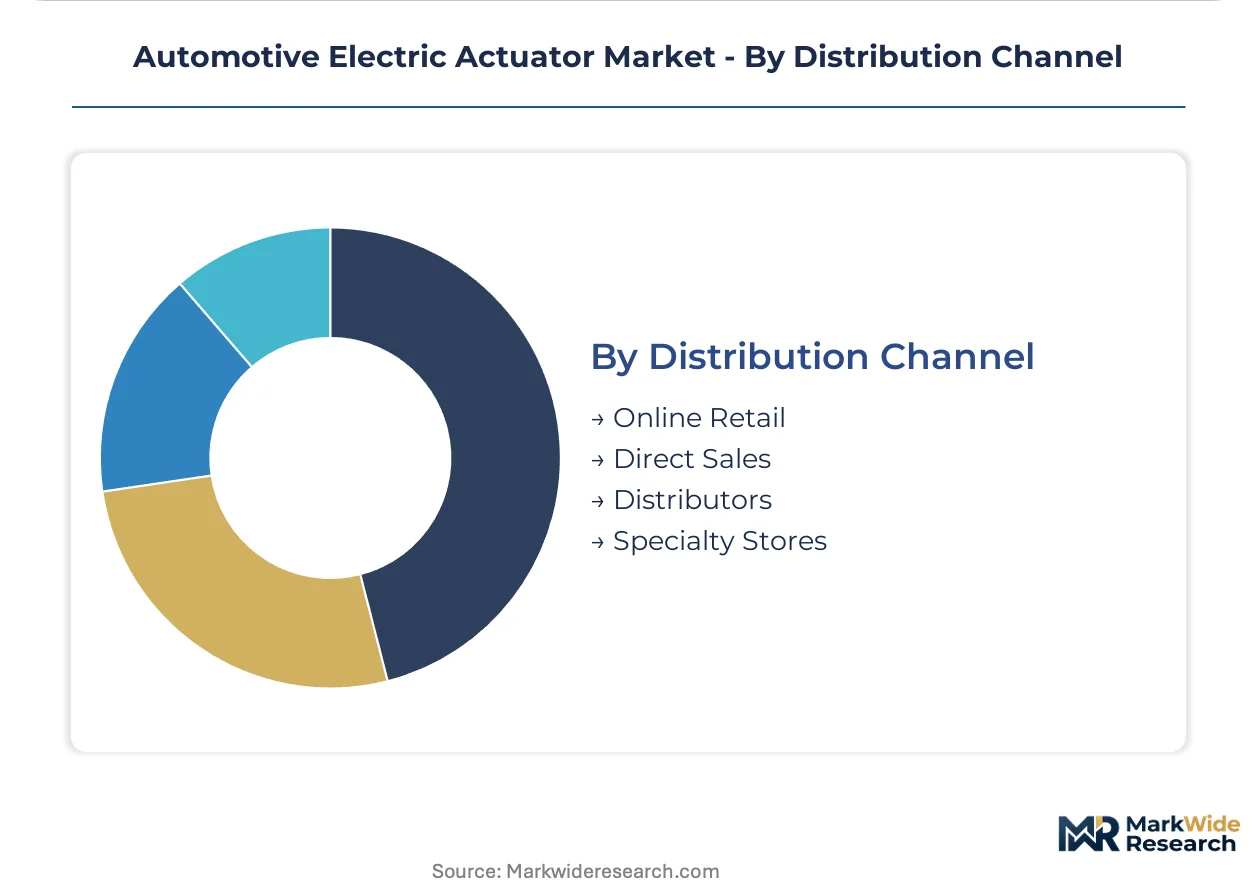
Direct Sales anchors revenue concentration, while Online Retail is expanding most quickly as fleet procurement digitizes and small-volume buyers bypass traditional distribution tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in automotive electric actuator procurement varies sharply by geography, with European OEMs absorbing premium costs for functional safety certification while Asian markets prioritize unit economics in thermal management applications.
Germany
Precision electromechanical production for turbocharger wastegate and throttle body systems drives actuator demand across Bavaria and Baden-Württemberg. The KBA enforces type approval protocols that filter non-compliant component imports. Stuttgart's automotive engineering corridor anchors tier-one supplier R&D facilities developing firmware-updatable smart actuators for 48V mild-hybrid platforms.
China
New energy vehicle production scaling and domestic supply chain localization redirect investment toward brushless DC motor manufacturing. MIIT mandates on component localization enforce GB standards for electromagnetic compatibility that reshape procurement patterns. Shanghai and Shenzhen manufacturing clusters concentrate domestic actuator capacity serving BYD, NIO, and Xpeng electrification programs.
United States
Detroit Three electrification roadmaps and ADAS integration requirements accelerate precision airflow control actuator deployment. Joint NHTSA and EPA fuel economy enforcement mandates closed-loop electric actuators for throttle body and variable valve timing calibration. Michigan's automotive supplier corridor hosts engineering centers developing rotary actuators for turbocharger wastegate replacement of cable linkages.
Japan
Hybrid platform heritage and thermal management actuator specialization sustain manufacturing scale in brushless DC motor assemblies. METI industrial policy supports rare-earth-reduced motor designs to mitigate supply concentration risk. Nagoya and Tokyo industrial zones concentrate Denso and Mitsubishi Electric production facilities serving Toyota and Honda electrification architectures.
South Korea
Battery-electric platform proliferation and active grille shutter specification expand 48V actuator demand across Hyundai-Kia production lines. MFDS automotive component quality frameworks align with international functional safety standards. Gyeonggi-do manufacturing complexes host supplier parks producing electromechanical actuators for thermal management and active aerodynamics systems.
Automotive Electric Actuator Market Vendor Landscape
Capability concentration sits with tier-one integrated system suppliers holding OEM channel control and joint development programs; scale advantage sits with diversified electromechanical component manufacturers serving multiple automotive platforms. The market structures around three strategic archetypes: full-system integrators with embedded software validation capabilities, precision motor specialists leveraging manufacturing scale, and remanufacturing service networks capturing aftermarket revenue. Dominant competitive moves include backward integration into brushless DC motor production and geographic expansion through tier-two supplier partnerships in China and India.
Among German-based integrated suppliers, Robert Bosch GmbH and Continental AG occupy positions exemplifying full-system capability with direct OEM channel relationships. Denso Corporation represents the precision manufacturing scale archetype, anchoring high-volume production of thermal management actuators. These three entities illustrate how competitive positioning fragments between firmware-integrated system control and manufacturing scale economics, with each archetype defending margin through distinct capability moats rather than overlapping product competition.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Johnson Electric Holdings Limited |
| HELLA GmbH & Co. KGaA |
| Mitsubishi Electric Corporation |
| BorgWarner Inc. |
| Nidec Corporation |
| Stoneridge Inc. |
| Others |
Supply Flow & Price Mechanics
Rare-earth magnet processing concentration in China feeds directly into margin capture by domestic brushless DC motor suppliers serving thermal management actuators. Permanent magnet cost volatility propagates downstream to tier-one suppliers defending position through remanufacturing service attach and firmware-update revenue streams.
Pricing Analysis
Aftermarket service contracts and remanufacturing programs drive lifetime value capture as hybrid fleets age and actuator replacement intervals compress. Three-tier pricing structure across premium certified, standard OEM, and economy aftermarket levels segments buyer archetypes by functional safety requirements and software validation depth. Cost compression in economy thermal management actuators is intensifying because Chinese domestic suppliers leverage MIIT localization mandates to undercut import pricing. Fleet operators exhibit highest price sensitivity, while European OEMs absorb certification premiums for ISO 26262-compliant smart actuators.
Supply Chain Analysis
Tariff exposure between China and Western automotive markets dominates supply chain risk planning for permanent magnet motors and precision gear assemblies. Manufacturing gravity centers on China, Germany, and Japan for brushless DC motor production, with Mexico emerging as a near-shore alternative for Detroit Three supply security. Raw material dependencies rest on neodymium and dysprosium from Chinese processing facilities, copper windings from Chilean-Chilean smelters, and engineered plastics from German petrochemical complexes. Single-source vulnerability in rare-earth magnet supply creates input cost volatility. Distribution runs through tier-one direct sales channels with embedded engineering support, bypassing traditional distributor markups for high-volume OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remanufacturing service networks and firmware-update subscriptions expand faster than hardware unit sales, repositioning actuator suppliers as recurring-revenue platforms rather than discrete component vendors.
For Market Incumbents: Pre-empt margin erosion from Chinese domestic suppliers by capturing aftermarket channel control through authorized remanufacturing networks and multi-year service level agreements with fleet operators. Backward integration into brushless DC motor production in Germany and Mexico defends cost position against rare-earth supply volatility. ISO 26262 functional safety certification investments create regulatory moats that emerging competitors cannot replicate without extended timelines. For New Entrants and Emerging Players: Establish a beachhead in 48V mild-hybrid thermal management actuators where European OEMs source second-source suppliers to reduce Bosch-Continental concentration risk. Target Chinese domestic NEV platforms requiring GB-standard electromagnetic compliance as a qualification barrier against Western imports. Lead with LIN-integrated smart actuator designs that collapse discrete sensor supply chains and capture margin from tier-two component vendors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision motor specialists holding captive rare-earth magnet supply relationships and 48V platform qualification. Long-term viability hinges on firmware-updatable actuator portfolios replacing fixed electromechanical specifications across the analysis window. Watch for inflection when fleet operators unbundle actuator maintenance from powertrain warranties and negotiate direct remanufacturing relationships, signaling aftermarket revenue capture acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless DC Motors | Captive magnet supply from Chinese processors reduces input cost volatility for thermal management actuators. |
| Remanufacturing Network Expansion | Bosch and Continental service coverage extends across aging hybrid platforms in Germany's automotive corridor. |
| 48V Mild-Hybrid Platform Qualification | European OEM turbocharger wastegate specifications demand higher-voltage actuators with precision positioning. |
| GB Standard Compliance Investment | MIIT electromagnetic compatibility protocols filter non-compliant imports from China's NEV supply chain. |
| Firmware-Update Capability Development | Software-defined vehicle architectures shift procurement from hardware-specified to updatable smart modules. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from tier-one suppliers, and MIIT regulatory announcements. Interviews with OEM platform engineers, tier-one supplier procurement directors, aftermarket distributor operations heads, and fleet maintenance managers informed demand-side validation. Bottom-up unit volume estimates triangulate against top-down market value reconstructions across product type and technology segments.
Forecast inputs include vehicle electrification roadmaps from Detroit Three and European OEMs, ADAS penetration curves, and 48V mild-hybrid platform proliferation timelines across the projection horizon. Segmentation dimensions span actuator product architecture, control technology methodology, end-user procurement authority, and regional production cluster. CAGRs derive from regression analysis of historical content-per-vehicle trends and forward platform specifications. Rare-earth magnet price indices and REACH compliance cost burdens inform margin compression scenarios.
Sensitivities concentrate around MIIT localization enforcement intensity, NHTSA fuel economy test protocol revisions, and rare-earth export restriction escalations. Forecasts reflect assumptions about software-defined vehicle adoption rates and remanufacturing service penetration without guaranteed realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market