
 Automotive Seat Covers Market | 2026-2036
Automotive Seat Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Covers Market Intelligence
Buyer concentration among commercial fleet operators is realigning procurement volumes toward large-scale, long-term supply contracts with tier-one suppliers. Lear Corporation anchors North American OEM channel relationships through captive manufacturing scale and just-in-time delivery systems. Adient plc leverages its integrated seating architecture portfolio to bundle seat covers with complete seat system programs. Covercraft Industries competes in the aftermarket through specialized pattern libraries serving restoration and custom vehicle builders.
Automotive seat covers are protective and aesthetic layers engineered from textiles, synthetics, or leather substrates, typically specified to meet abrasion resistance thresholds above 50,000 Martindale cycles and flammability ratings under FMVSS 302. Their primary purpose spans cabin protection, occupant comfort modulation, brand differentiation, and regulatory compliance for interior surface durability. Leather and neoprene material categories command premium positioning in luxury and performance vehicle configurations, while polyester and fabric alternatives dominate high-volume OEM and fleet replacement cycles. The SUV and pickup vehicle type segments sustain above-average cover replacement frequency due to higher utilitarian duty cycles and aftermarket personalization rates.
The US NHTSA enforces FMVSS 302 flammability standards that constrain substrate and coating chemistries available to domestic manufacturers, while EPA regulations on volatile organic compound emissions from adhesives and finishes shape material selection across production facilities. REACH compliance in Europe restricts certain phthalate plasticizers and flame retardants common in vinyl formulations, redirecting formulation R&D toward bio-based polyurethane alternatives. Stakeholders must monitor evolving chemical restriction schedules across multiple jurisdictions to preempt supply chain disruption and secure type-approval continuity for export-bound production.
Market Dynamics
Commercial fleet operators are consolidating procurement around multi-year supply contracts, compressing supplier margins while demanding accelerated pattern-to-production cycles and embedded sustainability certification.
Growth Catalysts
- EPA volatile organic compound emission limits:Manufacturers are reformulating solvent-free polyurethane coatings to maintain domestic production eligibility, creating first-mover advantages for compliant suppliers.
- Commercial fleet protective upholstery programs:Light-duty and medium-duty vehicle operators are mandating seat cover replacement cycles to preserve residual asset values and reduce total cost of ownership.
- Neoprene substrate innovation:Advanced closed-cell foam laminates are penetrating performance vehicle configurations where abrasion resistance and moisture barrier properties command specification priority.
Market Restraints
- Petrochemical input cost volatility:Polyester yarn and synthetic leather substrates face margin pressure from propylene and ethylene derivative price swings.
- REACH chemical restriction schedules:Phased prohibitions on phthalate plasticizers and halogenated flame retardants force continuous formulation redevelopment for European-bound production.
- Technical limitation in bio-based polyurethane durability:Plant-derived polyol alternatives currently fail to match petroleum-based equivalents for UV stability and hydrolysis resistance above 80,000 Martindale cycles.
Strategic Opportunities
- Underpenetrated Mexico aftermarket:Rising vehicle parc and limited domestic manufacturing capacity create import substitution potential for pattern-matched cover suppliers.
- India OEM-supplied channel expansion:Passenger vehicle production growth and cabin quality upgrade cycles favor localized cut-and-sew operations with just-in-time logistics.
- EU Green Deal sustainable material mandates:Recycled PET content thresholds and end-of-life recyclability requirements favor suppliers with certified circular material flows.
Industry Challenges
- Pattern digitization and automated nesting skill gaps:Legacy manual pattern libraries require costly CAD migration and technician retraining to achieve material yield targets.
- FMVSS 302 certification timeline compression:Accelerated vehicle launch schedules compress flammability testing and documentation cycles, risking production line stoppage.
- Multi-jurisdiction chemical compliance synchronization:Divergent restriction timelines across EPA, REACH, and China's GB standards fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Covers Market |
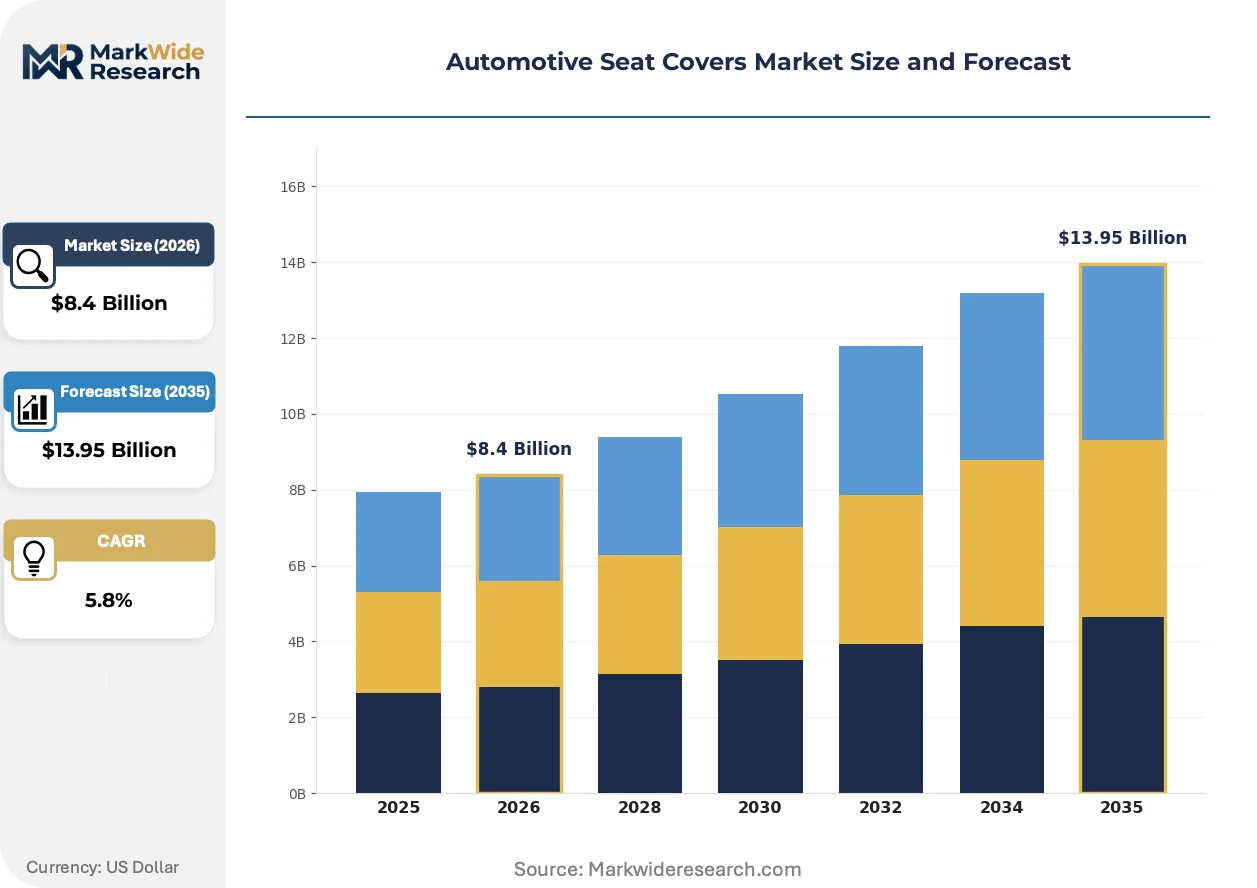
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Polyester, Vinyl, Neoprene, Fabric, Suede Vehicle Type: SUVs, Sedans, Pickups, Coupes, Convertibles, Vans Distribution Channel: OEM, Aftermarket Retailers, E-commerce, Specialty Stores, Wholesalers End User: Commercial Fleets, Private Vehicles, Luxury Vehicle Owners, Rental Agencies, Taxi Operators |
| Companies Covered | Covercraft Industries, Coverking Inc., Lear Corporation, Sage Automotive Interiors Inc., WeatherTech, Faurecia, Toyota Boshoku Corporation, Adient plc, Katzkin Leather, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Covers Market Strategic Shifts & Innovations
Digital pattern engineering and sustainable material substitution are converging to redefine production economics and specification authority across both OEM and aftermarket channels.
Smart textile interfaces incorporating pressure-sensitive conductive yarns are integrating occupant monitoring functions directly into seat cover substrates. Tier-one seating suppliers are adopting these systems for premium vehicle programs where biometric feedback and occupancy detection justify unit cost premiums. This convergence is integrating sensor hardware into previously passive upholstery components, compressing the traditional separation between seating structure and electronic architecture.
REACH authorization requirements for Substances of Very High Concern are restricting legacy flame retardant chemistries in vinyl formulations sold across European markets. Manufacturers are pivoting toward phosphorus-based alternatives and intumescent coating systems to maintain type-approval continuity. Aftermarket suppliers serving restoration and custom vehicle builders face the steepest reformulation burden due to smaller batch economics and pattern fragmentation.
Fleet maintenance departments are unbundling seat cover replacement from comprehensive vehicle service contracts, creating direct procurement relationships with specialized suppliers. This disintermediation is visible most acutely in North American commercial vehicle operations where total cost of ownership analytics now isolate upholstery lifecycle costs. Specialized pattern libraries and rapid-turn custom fabrication capabilities are displacing generic catalog offerings in this segment.
Automotive Seat Covers Market Segmentation
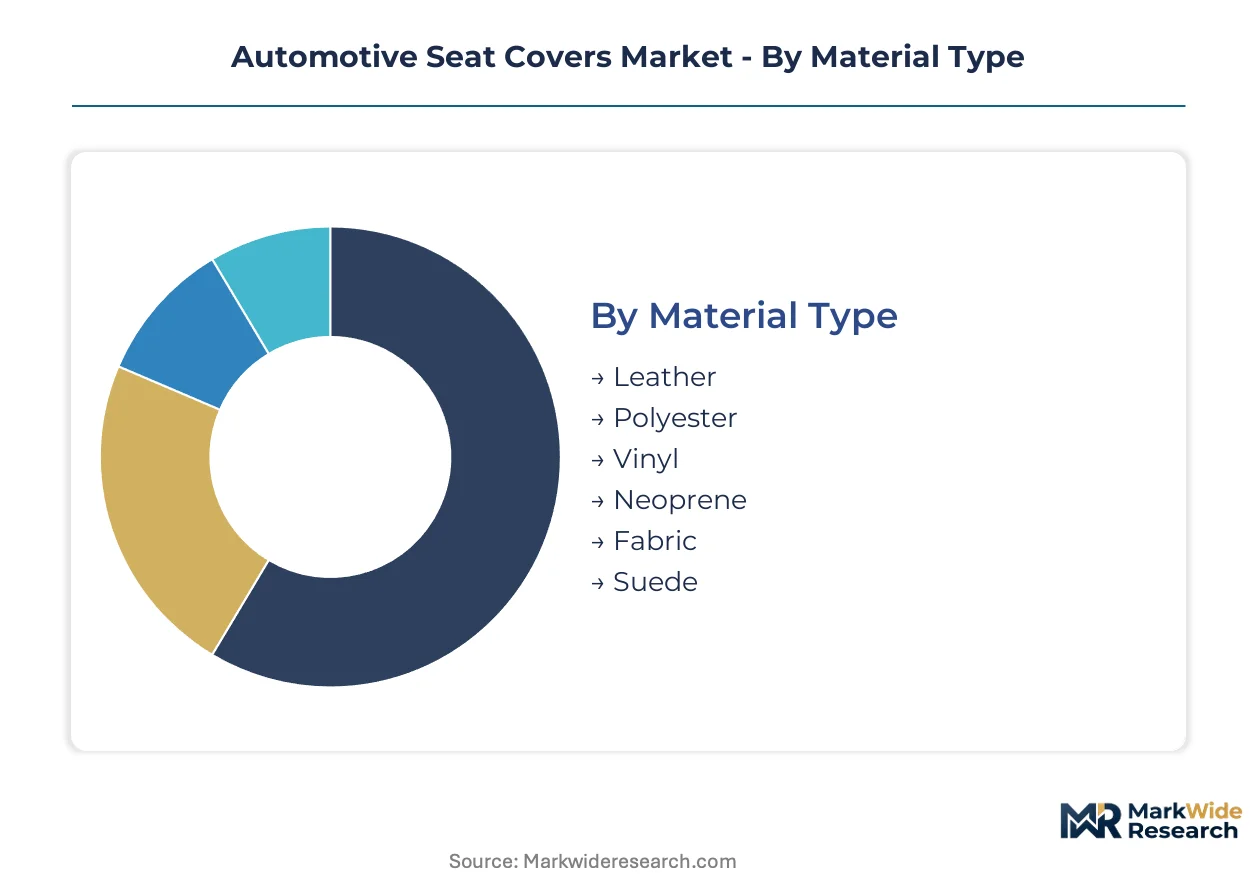
Seat cover procurement splits sharply between specification-driven OEM programs and price-sensitive aftermarket replacement cycles. Material chemistry and vehicle duty cycle together determine replacement frequency, margin structure, and regulatory compliance burden across each segment cluster.
Material Type:
Leather and polyester command divergent positions on the cost-performance spectrum, with premium substrates absorbing regulatory compliance costs while commodity materials compete on yield efficiency.
- Leather:Full-grain and corrected-grain hides specified above 1.2mm thickness for luxury OEM programs. Demand concentrates in German and Italian premium vehicle manufacturing where REACH-compliant vegetable tanning processes offset synthetic restrictions.
- Polyester:Woven and knitted constructions dominate fleet replacement programs across the United States and Mexico. Recycled PET content thresholds under EU Green Deal mandates are redirecting procurement toward certified circular supply chains.
- Vinyl:PVC substrates with phthalate-free plasticizers serve price-sensitive aftermarket channels in India and China.
- Neoprene:Closed-cell foam laminates penetrate performance vehicle configurations requiring moisture barrier properties.
- Fabric:Blended natural-synthetic weaves occupy mid-tier OEM and aftermarket positioning.
- Suede:Alcantara and microfiber alternatives target premium interior upgrade programs.
Today's leader: Leather. Tomorrow's challenger: Polyester with certified recycled content.
Vehicle Type:
Utilitarian duty cycles and personalization rates vary dramatically across body styles, with workhorse platforms sustaining above-average cover replacement frequency.
- SUVs:Three-row configurations generate multi-zone cover demand with distinct abrasion requirements per seating position. Fleet operators in Texas and California mandate protective upholstery programs for light-duty SUV classes to preserve residual asset values.
- Sedans:Standardized bench and bucket seat patterns enable economies of scale in high-volume OEM supply. Production concentration in China and India favors localized cut-and-sew operations with compressed logistics cycles.
- Pickups:Commercial and personal-use duty cycles drive the steepest replacement frequency among all body styles. Aftermarket personalization rates exceed 40% in North American markets.
- Coupes:Limited production volumes favor specialized pattern libraries and custom fabrication.
- Convertibles:UV degradation exposure accelerates cover replacement cycles in sun-belt geographies.
- Vans:Last-mile delivery configurations prioritize durability over aesthetic specification.
Pickups generate the highest per-vehicle replacement revenue. Sedans deliver the steepest volume expansion trajectory.
Distribution Channel:
Channel selection determines margin capture, technical specification authority, and customer relationship durability.
- OEM:Direct supply contracts with seating integrators require FMVSS 302 certification and just-in-time delivery systems. Lear Corporation and Adient plc anchor North American procurement through captive manufacturing scale.
- Aftermarket Retailers:Pattern-matched catalog offerings serve restoration and replacement demand through brick-and-mortar networks. Wholesalers in Mexico and India consolidate fragmented local supply.
- E-commerce:Direct-to-consumer platforms are displacing generic catalog offerings with vehicle-specific fitment tools. Amazon and specialized automotive marketplaces capture share in United States and European replacement cycles.
- Specialty Stores:Custom vehicle builders and restoration shops demand rapid-turn fabrication capabilities.
- Wholesalers:Bulk procurement relationships with fleet maintenance departments unbundle upholstery from comprehensive service contracts.
OEM contracts defend margin stability. E-commerce channels are gaining share fastest in aftermarket replacement.
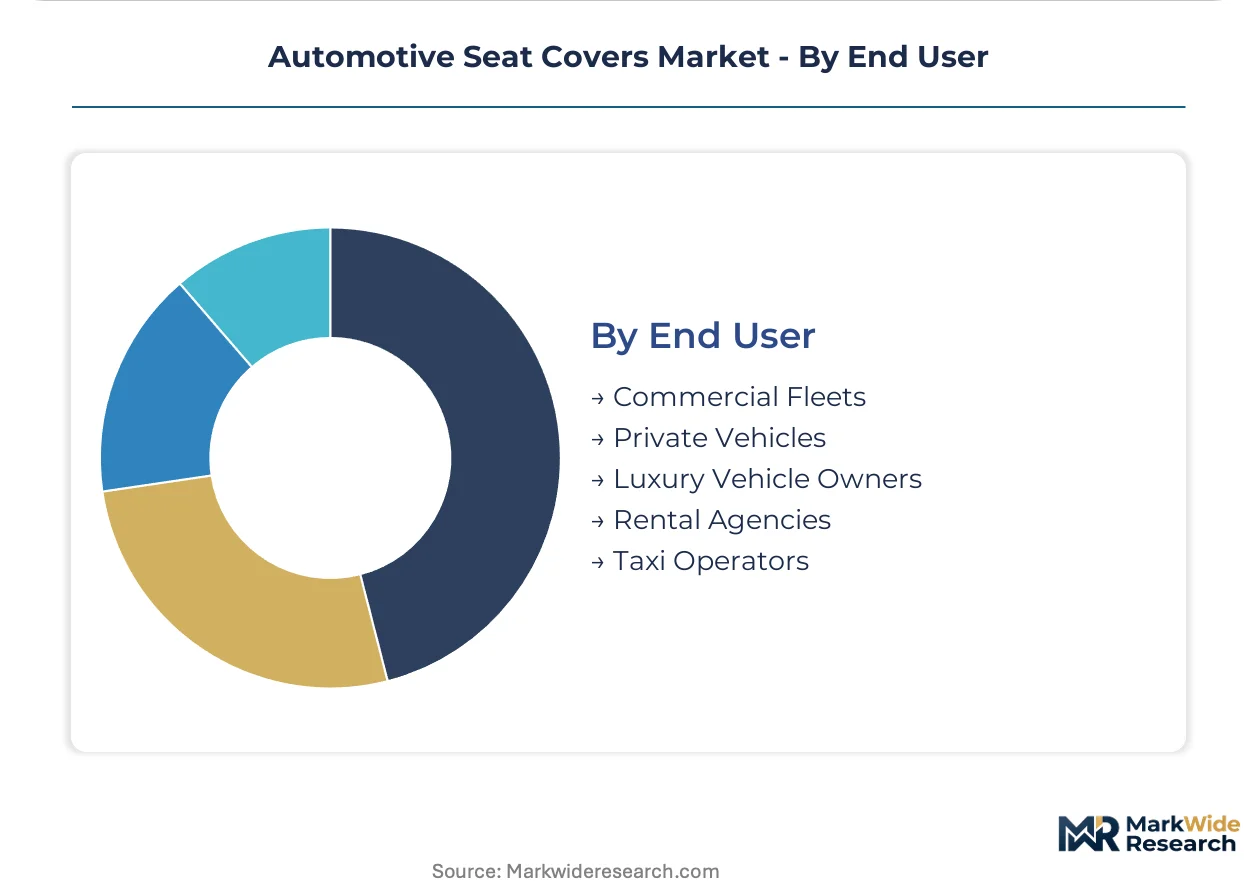
End User:
Procurement sophistication and total cost of ownership analytics separate institutional buyers from individual consumers.
- Commercial Fleets:Light-duty and medium-duty operators mandate scheduled replacement cycles based on mileage thresholds and residual value preservation. United States-based logistics companies consolidate procurement around multi-year supply contracts.
- Private Vehicles:Individual owners prioritize aesthetic customization and protective functionality. Aftermarket personalization rates vary by geography and vehicle age.
- Luxury Vehicle Owners:Premium OEM programs and bespoke aftermarket services target cabin quality upgrade cycles. German and British marques specify leather and suede configurations.
- Rental Agencies:High-turnover fleets prioritize rapid replacement and standardized durability.
- Taxi Operators:Urban ride-hail and traditional taxi services in India and Mexico drive utilitarian cover demand.
Commercial fleets anchor procurement volume. Luxury vehicle owners sustain premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled cut-and-sew technicians and automotive upholstery specialists concentrate in manufacturing corridors tied to vehicle assembly clusters and leather processing centers across five national markets.
United States
Commercial fleet operators in Texas and California mandate protective upholstery programs for light-duty SUVs and pickups to preserve residual asset values. NHTSA enforces FMVSS 302 flammability standards that constrain substrate chemistries available to domestic manufacturers. Detroit's automotive supplier corridor anchors OEM supply relationships through just-in-time delivery systems serving Ford, General Motors, and Stellantis assembly plants.
Germany
Premium vehicle manufacturers specify full-grain leather configurations above 1.2mm thickness for luxury OEM programs. REACH authorization requirements for Substances of Very High Concern restrict legacy flame retardant chemistries in vinyl formulations sold across European markets. Stuttgart and Munich anchor the supplier ecosystem where vegetable tanning processes offset synthetic restrictions for export-bound production.
China
Passenger vehicle production growth and cabin quality upgrade cycles favor localized cut-and-sew operations with compressed logistics cycles. GB standards on interior air quality and flammability shape material selection across production facilities in Shanghai and Guangzhou. The Yangtze River Delta manufacturing cluster concentrates pattern-matched cover suppliers serving both domestic OEM channels and aftermarket replacement demand.
India
Urban ride-hail and traditional taxi services in Mumbai and Delhi drive utilitarian cover demand with rapid replacement cycles. BIS certification requirements for automotive textiles create compliance thresholds for domestic manufacturers and importers. The Tamil Nadu automotive belt around Chennai hosts localized fabrication operations supplying Maruti Suzuki, Hyundai, and Tata Motors assembly programs.
Mexico
Rising vehicle parc and limited domestic manufacturing capacity create import substitution potential for pattern-matched cover suppliers serving aftermarket channels. The country's national automotive regulator enforces NOM standards on interior materials that align with USMCA trade bloc requirements. Nuevo León's industrial corridor around Monterrey concentrates warehousing and distribution nodes for North American cross-border supply.
Automotive Seat Covers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The market structure separates seating integrators with captive manufacturing scale from independent pattern houses serving fragmented aftermarket demand. Three archetypes dominate: OEM-direct seating system suppliers, specialized leather upholstery fabricators, and catalog-based aftermarket distributors. Competitive moves center on multi-year fleet supply contract consolidation and rapid-turn custom fabrication capability expansion.
Among North American OEM channel suppliers, Lear Corporation and Adient plc occupy positions representing integrated seating architecture providers. Covercraft Industries sits within the aftermarket specialist tier alongside pattern-matched catalog competitors. Faurecia exemplifies the European diversified automotive supplier archetype with cross-border manufacturing footprints.
| Leading Market Players |
|---|
| Covercraft Industries |
| Coverking Inc. |
| Lear Corporation |
| Sage Automotive Interiors Inc. |
| WeatherTech |
| Faurecia |
| Toyota Boshoku Corporation |
| Adient plc |
| Katzkin Leather, Inc. |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility propagates through polyester yarn and synthetic leather substrate tiers, compressing margins at mid-market suppliers while premium leather configurations absorb cost swings through long-term hide supply contracts with tanneries in Italy and Brazil. Fleet procurement teams exploit this divergence by unbundling seat cover replacement from comprehensive vehicle service agreements, shifting price discovery toward direct supplier negotiations.
Pricing Analysis
Bundled comprehensive service contracts and unbundled direct procurement now split the commercial fleet segment, with the latter gaining share fastest. Three-tier pricing structure across premium, standard, and economy levels separates FMVSS 302-certified OEM supply from aftermarket pattern-matched catalogs and generic universal-fit imports. Cost compression in polyester and vinyl tiers is intensifying because propylene derivative price swings transfer immediately to contract renegotiations. Commercial fleet operators exhibit the highest price sensitivity, while luxury vehicle owners sustain premium positioning for full-grain leather configurations.
Supply Chain Analysis
Domestic-content mandates under USMCA trade provisions are redirecting cut-and-sew operations toward Mexico and away from Asian export platforms. Manufacturing gravity centers on China for high-volume OEM supply, Mexico for North American aftermarket distribution, and Italy for premium leather finishing. Raw material dependencies span Brazilian hide processors, South Korean synthetic fiber producers, and German polyurethane coating specialists. Single-source vulnerability concentrates in phthalate-free plasticizer formulations where REACH-compliant European suppliers dominate. Distribution runs through tier-one seating integrators for OEM channels and fragmented wholesale networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive seat covers function as a regulatory compounder where tightening FMVSS 302 flammability standards and EPA volatile organic compound limits continuously refresh replacement demand across fleet and consumer segments.
For Market Incumbents: Hedge against margin erosion in polyester commodity tiers by securing captive tannery relationships for leather supply and accelerating solvent-free polyurethane coating certification. Fleet procurement consolidation threatens mid-tier suppliers without multi-year contract scale. Backward integration into pattern digitization capabilities defends specification authority against automated nesting specialists.
For New Entrants and Emerging Players: Capture the underpenetrated Mexico aftermarket where rising vehicle parc and limited domestic manufacturing capacity create import substitution openings. Rapid-turn custom fabrication for restoration and performance vehicle builders offers the most penetrable entry point. Direct e-commerce fitment tools bypass fragmented wholesale channels and establish immediate consumer relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where fleet procurement teams demand pattern libraries with embedded sustainability certification and just-in-time logistics integration. Long-term viability favors suppliers with certified circular material flows and multi-jurisdiction chemical compliance infrastructure. Watch for EPA enforcement actions on volatile organic compound emissions as the signal indicating accelerated reformulation investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Pattern Digitization Investment | CAD migration and automated nesting reduce material waste and compress pattern-to-production cycles for fleet contracts. |
| Solvent-Free Coating Certification | EPA-compliant polyurethane formulations secure domestic production eligibility and create first-mover advantages. |
| Recycled PET Supply Chain Integration | EU Green Deal mandates on circular content thresholds favor suppliers with certified post-consumer material flows. |
| Mexico Distribution Hub Establishment | USMCA-aligned warehousing in Nuevo León captures cross-border aftermarket demand with compressed logistics cycles. |
| Smart Textile Sensor Partnership | Pressure-sensitive conductive yarn integration positions seat covers as biometric monitoring platforms for premium OEM programs. |
Research Approach
Multiple input streams — structured interviews with tier-one supplier procurement directors, aftermarket distributor operations heads, and fleet maintenance managers; secondary validation through vehicle production databases, IHS Markit registration data, and customs trade records; and regulatory filing analysis across EPA, NHTSA, and REACH dockets — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured pattern-to-production cycle times, material yield benchmarks, and certification timeline compression pressures. Secondary sources included SEC 10-K disclosures from seating integrators, automotive textile trade association reports, and chemical restriction schedule publications from ECHA.
Historical volume trajectories were cross-referenced against panel input from OEM platform engineers and aftermarket catalog managers to construct the analytical framework. Segmentation dimensions modeled span material chemistry tier, vehicle duty cycle classification, distribution channel structure, and end-user procurement sophistication. CAGRs were derived from fitted growth curves applied to baseline penetration rates and replacement frequency assumptions. Industry-specific forecast inputs incorporated fleet vehicle retention period trends and cabin quality upgrade cycle acceleration in emerging production centers.
Petrochemical price volatility, regulatory enforcement timing shifts, and automotive production schedule disruptions are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Automotive Intelligent Lighting System Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Films Market