
 Rear-Wheel Steering Actuator Systems for SUVs Market | 2026-2036
Rear-Wheel Steering Actuator Systems for SUVs Market Size, Share, and Industry Trends Forecast 2026-2036
Rear-Wheel Steering Actuator Systems for SUVs Market Insights
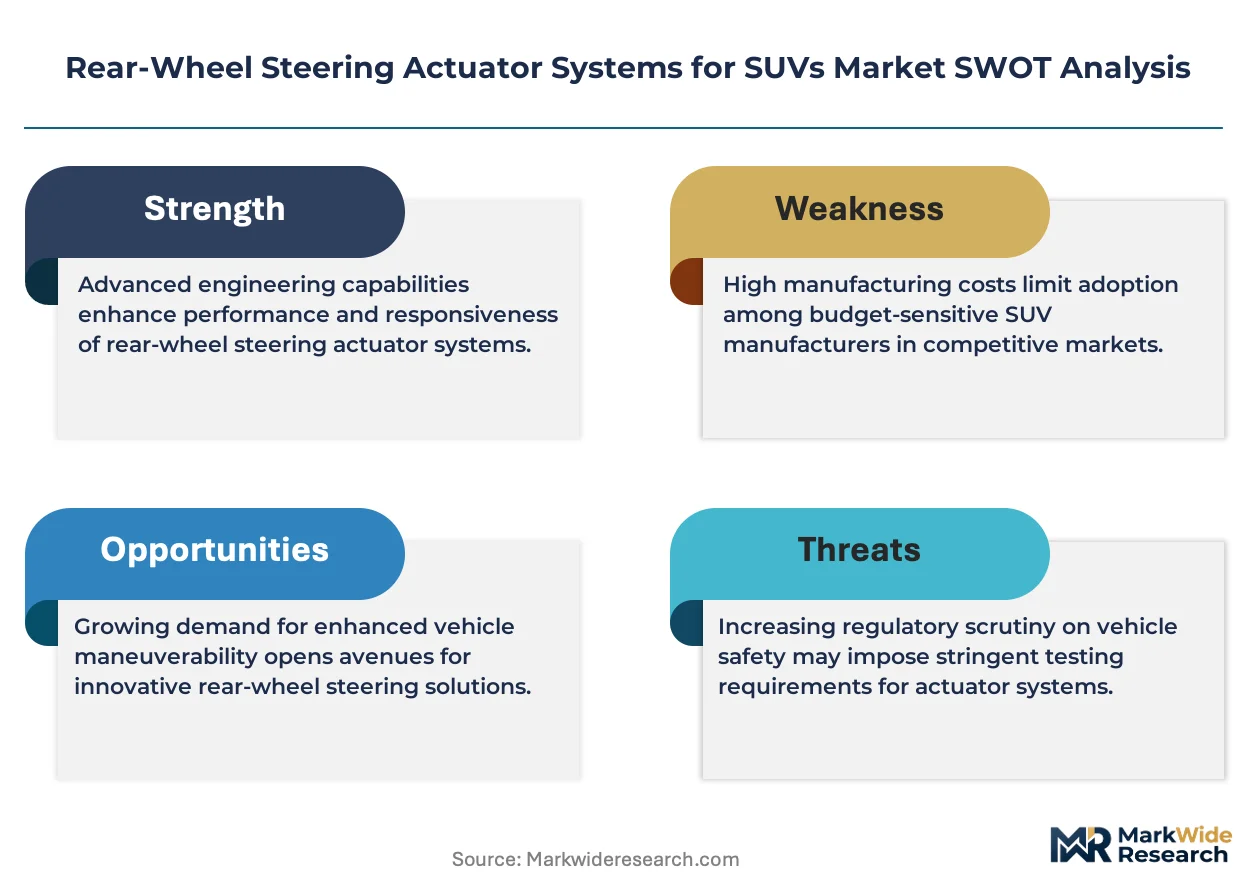
The divergence between premium and commodity tiers is hardening as OEMs demand sub-degree steering precision for luxury SUVs while entry-level models retain fixed rear axles. ZF Friedrichshafen leverages its integrated chassis portfolio to supply full electromechanical systems for high-end platforms. Nexteer Automotive anchors its position through advanced torque-overlay algorithms that enable variable steering ratios. Robert Bosch competes with modular actuator architectures that reduce integration complexity for Tier-1 customers.
Rear-wheel steering actuator systems for SUVs are electromechanical or electro-hydraulic assemblies that articulate rear wheels through angles typically between 2.5 and 10 degrees, using brushless DC motors or servo motors to generate precise torque response within milliseconds. Their primary purpose is to reduce turning radius at low speeds and enhance high-speed lane stability. Electric actuator configurations now lead volume shipments due to simpler packaging and elimination of hydraulic fluid circuits. Brushless DC motor technology dominates the motor segment because of superior power density and thermal efficiency under sustained load cycles. Servo motor variants represent the fastest-growing technology category as closed-loop position control enables predictive steering strategies.
NHTSA in the United States and the EU's General Safety Regulation mandate advanced driver-assistance capabilities that effectively require precise rear-axle articulation for automatic emergency steering interventions. REACH and RoHS in Europe restrict hazardous substances in actuator electronics and motor windings, forcing suppliers to reformulate insulation coatings and solder compositions. Stakeholders must monitor how software-defined vehicle architectures will shift actuator control from dedicated ECUs to centralized compute platforms.
Market Dynamics
Electrification of chassis systems is compressing actuator control architectures from distributed ECUs toward centralized domain controllers, forcing suppliers to requalify software stacks for real-time steering intervention.
Growth Catalysts
- EU Green Deal fleet standards:CO2 reduction mandates compel automakers to deploy rear-wheel steering as a lightweight alternative to longer wheelbases for urban maneuverability.
- Urban SUV density:Parking-space constraints in Stuttgart, Ingolstadt, and Munich assembly corridors drive specification of sub-5-meter turning-circle systems.
- Brushless DC motor maturation:Power density gains above 5 kW per liter enable packaging within compact rear-axle modules without hydraulic assist.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese processing hubs compress motor supplier margins unpredictably.
- Stuttgart-Ingolstadt supplier concentration:Tier-1 actuator assembly clusters within 200 kilometers of these cities create single-source vulnerability for European OEM programs.
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for steering actuators extends development cycles 18-24 months beyond conventional chassis components.
Strategic Opportunities
- Software-defined vehicle convergence:Centralized compute platforms from NVIDIA and Qualcomm create openings for actuator suppliers to deliver steering-as-a-service subscriptions.
- Indian premium SUV assembly:Localized production of luxury SUVs near Pune and Chennai lacks rear-wheel steering penetration versus German equivalents.
- EU General Safety Regulation phase-in:Automatic emergency steering mandates effective 2024-2026 create regulatory pull for predictive rear-axle articulation systems.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineers with ISO 26262 and AUTOSAR expertise command premium compensation in Munich and Stuttgart labor markets.
- Legacy chassis integration friction:Mechanical rear-axle architectures in existing SUV platforms resist electromechanical retrofit without full platform redevelopment.
- Cybersecurity certification complexity:UN R155 and R156 homologation for over-the-air steering updates requires new validation protocols absent from traditional actuator testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rear-Wheel Steering Actuator Systems for SUVs Market |
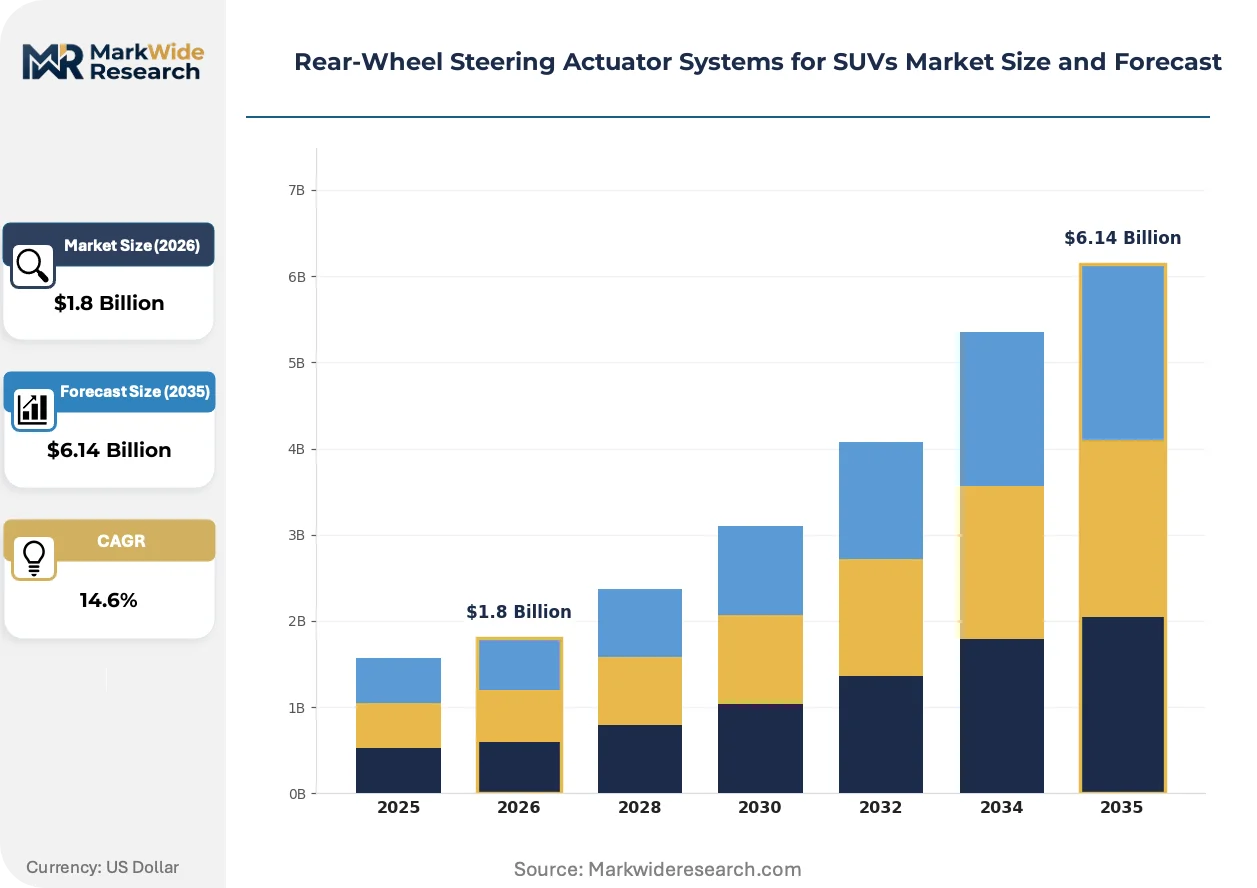
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuator, Hydraulic Actuator, Electro-Hydraulic Actuator, Pneumatic Actuator Technology: Brushless DC Motor, Stepper Motor, Piezoelectric, Servo Motor, Linear Actuation Application: Sports Utility Vehicles, Heavy-Duty Trucks, Light Commercial Vehicles, Off-Road Vehicles, Specialty Vehicles End User: OEM Suppliers, Tier-1 Integrators, Vehicle Assembly Plants, Aftermarket Manufacturers |
| Companies Covered | ZF Friedrichshafen, Nexteer Automotive, Robert Bosch, JTEKT, Schaeffler, Hyundai Mobis, Hitachi Astemo, HL Mando, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rear-Wheel Steering Actuator Systems for SUVs Market Trends and Innovations
Actuator control logic is migrating from dedicated motor-drive ECUs toward zonal compute nodes, collapsing hardware boundaries between steering, braking, and suspension domains. This architectural shift compresses supplier value capture toward software and calibration IP.
Brushless DC motor technology is consolidating electromechanical actuator designs across premium SUV platforms. BMW and Mercedes-Benz specification engineers now mandate integrated motor-gearbox units with position feedback resolution below 0.1 degrees. The technology is consolidating three previously separate component categories—motor, reducer, and sensor—into single-source modules that reduce Tier-2 supplier count per axle.
REACH substance restrictions on lead-based solder and specific phthalate plasticizers in motor windings force reformulation of insulation systems. German suppliers operating under ECHA enforcement timelines have accelerated halogen-free coating adoption by 18 months versus original transition schedules. High-voltage actuator variants for 800V architectures face the steepest compliance burden due to thermal class upgrades required simultaneously.
Fleet procurement of rear-wheel steering is unbundling from complete chassis contracts into separately negotiated actuator supply agreements. Procurement directors at Volkswagen Group and Stellantis now benchmark motor-inverter integration costs against standalone module pricing from ZF and Bosch. This pattern is most visible in Germany, where platform-sharing across Audi, Porsche, and Bentley creates volume leverage for component-level sourcing.
Rear-Wheel Steering Actuator Systems for SUVs Market Segmentation
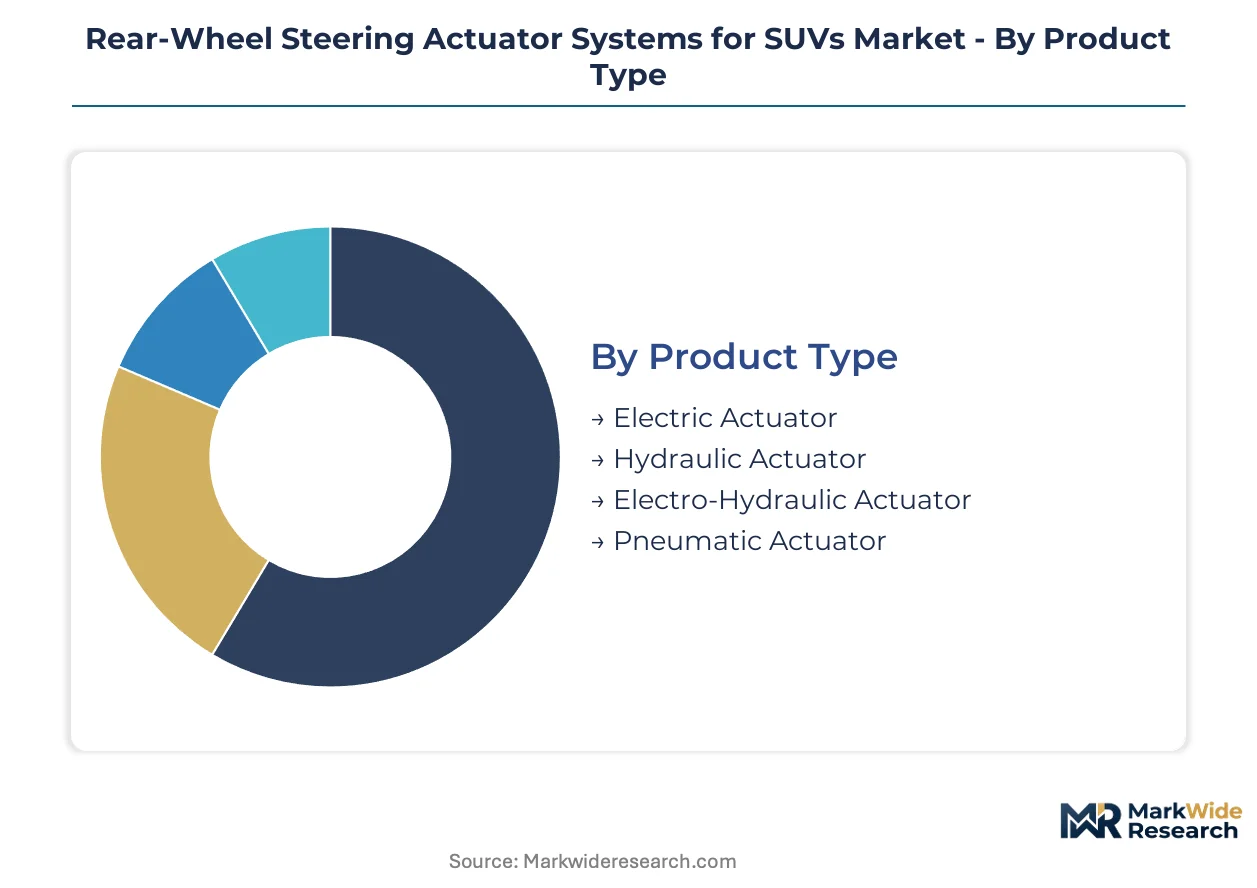
Rear-wheel steering actuator architectures fragment across four distinct dimensions. Product type and technology choices determine packaging constraints and thermal performance. Application scope and end-user channel structure dictate procurement economics and qualification timelines.
Product Type:
Supply concentration in electromechanical systems has compressed Tier-2 vendor counts per axle module.
- Electric Actuator:Brushless DC motor drives integrated gearbox units delivering position feedback below 0.1 degrees. Demand clusters around Stuttgart and Ingolstadt assembly corridors where BMW and Mercedes-Benz specify sub-5-meter turning-circle systems for urban SUV maneuverability.
- Hydraulic Actuator:Pressurized fluid circuits with servo-valve control enable higher torque density for heavy SUV platforms. Fleet procurement in Germany unbundles these from complete chassis contracts into separately negotiated supply agreements.
- Electro-Hydraulic Actuator:Hybrid architectures combining electric motor priming with hydraulic force multiplication.
- Pneumatic Actuator:Compressed air systems limited to specialty off-road applications with existing air suspension infrastructure.
Today's leader: Electric Actuator. Tomorrow's challenger: Electro-Hydraulic Actuator.
Technology:
Cost tier differentiation separates premium integrated motor-gearbox units from commodity motor-only supply.
- Brushless DC Motor:Power density above 5 kW per liter enables compact rear-axle packaging without hydraulic assist. German suppliers under ECHA enforcement timelines accelerated halogen-free insulation coating adoption.
- Servo Motor:Closed-loop position control enables predictive steering strategies for automatic emergency steering interventions. Volume demand is climbing the fastest as EU General Safety Regulation mandates phase in.
- Stepper Motor:Open-loop position control for cost-sensitive actuator variants with relaxed precision requirements.
- Piezoelectric:Ultrafast response actuation for niche high-bandwidth steering correction applications.
- Linear Actuation:Direct-drive architectures eliminating rotary-to-linear conversion losses in select SUV platforms.
Brushless DC Motor captures current volume. Servo Motor presents the steepest expansion trajectory.
Application:
Volume concentration in luxury SUVs drives specification of sub-degree steering precision versus commodity fixed-axle alternatives.
- Sports Utility Vehicles:Premium platforms from Audi, Porsche, and Bentley create component-level sourcing leverage through platform-sharing. EU Green Deal CO2 fleet standards compel rear-wheel steering deployment as lightweight alternatives to extended wheelbases.
- Heavy-Duty Trucks:Articulation angles up to 10 degrees reduce low-speed turning radius for urban delivery configurations. Specification engineers mandate integrated motor-gearbox units with thermal class upgrades for 800V architectures.
- Light Commercial Vehicles:Fleet procurement patterns favor modular actuator architectures reducing integration complexity.
- Off-Road Vehicles:Ruggedized actuator housings with IP6K9K sealing for dust and high-pressure washdown exposure.
- Specialty Vehicles:Custom stroke lengths and mounting geometries for armored and limousine conversions.
Sports Utility Vehicles anchor present revenue. Heavy-Duty Trucks represent the fastest-climbing application tier.
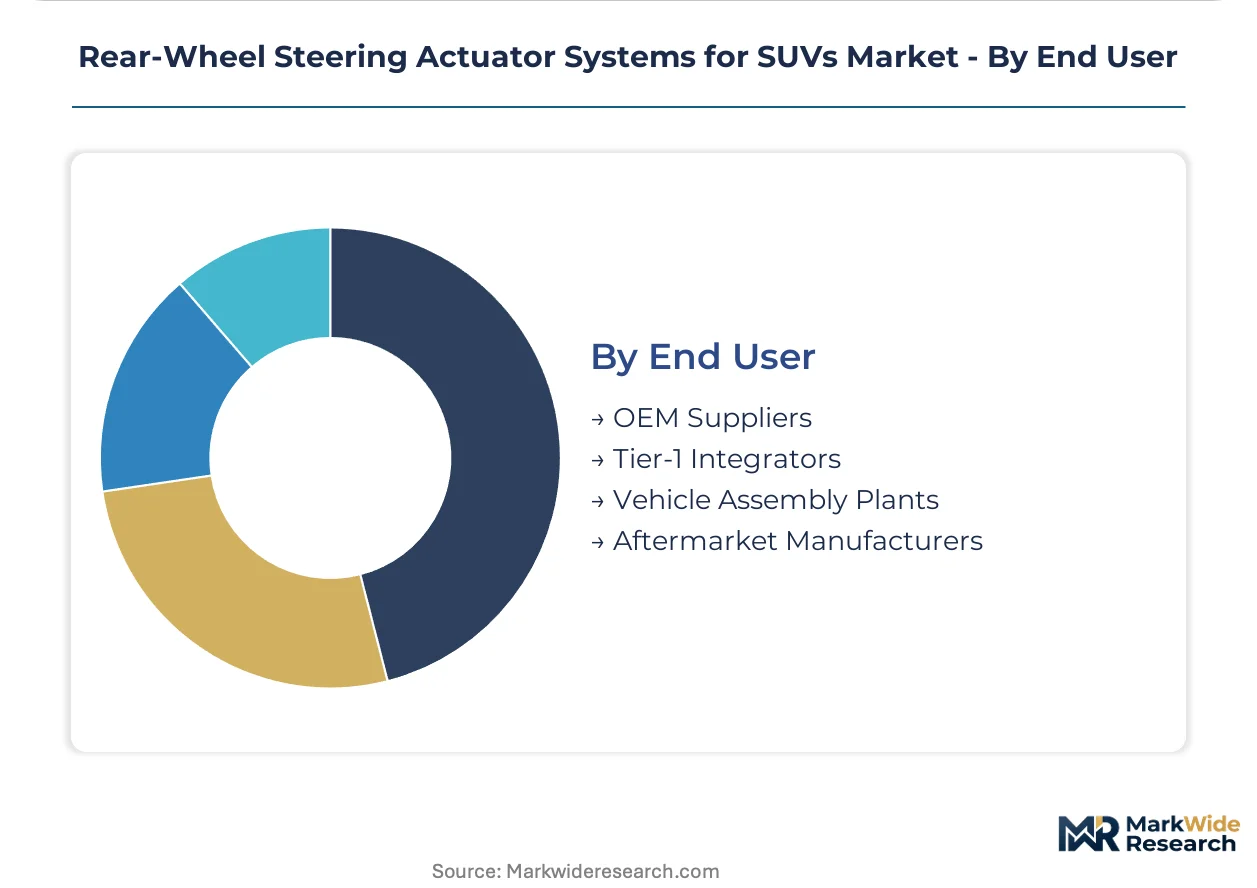
End User:
Customer type stratification separates consolidated OEM direct procurement from fragmented aftermarket channels.
- OEM Suppliers:Volkswagen Group and Stellantis procurement directors benchmark motor-inverter integration costs against standalone module pricing. Long-term supply agreements span full platform lifecycles with penalty clauses for ASIL-D qualification delays.
- Tier-1 Integrators:ZF Friedrichshafen and Robert Bosch compete on modular actuator architectures reducing customer engineering burden. Embedded software talent scarcity in Munich and Stuttgart labor markets compresses margin structures.
- Vehicle Assembly Plants:Just-in-sequence delivery requirements within 200-kilometer supplier radius of Stuttgart and Ingolstadt.
- Aftermarket Manufacturers:Retrofit kit demand constrained by legacy chassis integration friction and cybersecurity certification complexity under UN R155.
OEM Suppliers dominate contract value. Tier-1 Integrators gain share through software-defined vehicle convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional safety engineers with ISO 26262 and AUTOSAR expertise cluster in Munich and Stuttgart, anchoring European actuator development while Asian manufacturing centers scale brushless DC motor production for export markets.
Germany
Premium SUV assembly plants from Audi, Porsche, and BMW concentrate procurement decisions around Stuttgart and Ingolstadt. NHTSA-equivalent KBA vehicle safety standards mandate precise rear-axle articulation for automatic emergency steering compliance. The 200-kilometer supplier radius around these cities creates just-in-sequence delivery networks for electromechanical actuator modules.
United States
Full-size SUV platforms from Detroit manufacturers specify rear-wheel steering for suburban maneuverability and trailer-towing stability. NHTSA advanced driver-assistance mandates drive integration of predictive steering algorithms into chassis domain controllers. Michigan-based engineering centers source motor-gearbox units through cross-border supply agreements with Ontario fabricators.
China
Domestic premium SUV brands accelerate specification of rear-axle steering to compete with German luxury imports. MIIT new energy vehicle regulations incentivize lightweight chassis technologies that reduce CO2 fleet emissions. Yangtze River Delta manufacturing clusters around Shanghai produce brushless DC motors with power density gains above 5 kW per liter for compact packaging.
Japan
Keiretsu-affiliated suppliers integrate rear-wheel steering into hybrid SUV platforms for domestic and Southeast Asian export markets. METI carbon neutrality roadmaps push automakers toward electromechanical actuator designs eliminating hydraulic fluid circuits. Nagoya-area precision manufacturing bases supply integrated motor-gearbox units with position feedback resolution below 0.1 degrees.
South Korea
Hyundai and Kia premium SUV platforms adopt rear-axle articulation to reduce turning radius in dense Seoul urban environments. MFDS automotive safety standards align with EU General Safety Regulation phase-in timelines for automatic emergency steering. Busan-Ulsan industrial corridors host motor winding facilities reformulating insulation coatings under REACH-equivalent substance restrictions.
Rear-Wheel Steering Actuator Systems for SUVs Market Competitive Landscape
Top-tier vendors anchor integrated chassis portfolios, while mid-tier specialists compete on modular actuator architectures and software calibration IP. The vendor base separates into three strategic tiers: full-system integrators supplying electromechanical platforms, component specialists delivering motor-gearbox modules, and software-focused firms enabling predictive steering algorithms. Consolidation pressures favor suppliers with captive motor manufacturing and functional safety certification capabilities. Dominant competitive moves include strategic partnerships for 800V high-voltage architectures and technology licensing for centralized domain controller integration.
Within the full-system integrator tier, ZF Friedrichshafen and Robert Bosch exemplify European engineering-origin suppliers with chassis portfolio breadth. Nexteer Automotive occupies a position among North American-headquartered specialists emphasizing torque-overlay control software. These three anchors represent divergent strategic postures: integrated manufacturing depth versus software-defined vehicle convergence versus regional OEM relationship density.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Nexteer Automotive |
| Robert Bosch |
| JTEKT |
| Schaeffler |
| Hyundai Mobis |
| Hitachi Astemo |
| HL Mando |
| Continental |
| Others |
Pricing and Supply Chain Analysis
OEM procurement directors at Volkswagen Group and Stellantis unbundling rear-wheel steering from complete chassis contracts forces Tier-1 suppliers to quote motor-inverter modules separately, compressing margins on standalone actuator sales while elevating software calibration IP as the residual value capture point.
Pricing Analysis
The bundled-versus-unbundled service split now defines competitive positioning. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified integrated motor-gearbox units from commodity motor-only supply and aftermarket retrofit kits. Price differentiation reflects certification grade and volume scale, with full-platform procurement commanding 40-60% unit cost advantages over spot purchases. Pricing pressure stems from rare-earth magnet cost volatility in Chinese processing hubs. Fleet procurement directors at luxury OEMs exhibit lowest price sensitivity; aftermarket manufacturers face acute margin compression.
Supply Chain Analysis
Rare-earth magnet supply rests on Chinese mining and separation facilities, with secondary concentration in Japanese magnet fabrication and German motor winding operations. Brushless DC motor production draws from neodymium-dysprosium feedstocks, halogen-free insulation coatings, and precision gearbox forgings. Single-source vulnerability concentrates within the 200-kilometer Stuttgart-Ingolstadt supplier radius. Distribution runs through just-in-sequence networks to assembly plants, with Tier-1 integrators maintaining 48-hour delivery windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as EU General Safety Regulation mandates for automatic emergency steering create regulatory pull through the projection horizon, embedding rear-wheel steering as standard equipment across premium SUV platforms.
For Market Incumbents: Anticipate margin compression from software-defined vehicle architectures collapsing dedicated ECU value capture. Defend position by deepening captive motor manufacturing in Germany and accelerating ISO 26262 ASIL-D certification pipelines. Prioritize strategic partnerships with NVIDIA and Qualcomm for centralized domain controller integration before control logic migrates entirely to zonal compute nodes. For New Entrants and Emerging Players: Predictive steering algorithms offering torque-overlay capabilities present the most penetrable technology-first wedge. Target Indian premium SUV assembly near Pune and Chennai, where localized production lacks rear-wheel steering penetration versus German equivalents. Pursue joint development agreements with domestic brands seeking feature parity with German luxury imports. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier component specialists possessing halogen-free insulation coating capabilities and functional safety certification infrastructure. Long-term viability favors suppliers with backward integration into rare-earth magnet sourcing or alternative motor topologies reducing rare-earth dependency. Watch for MIIT new energy vehicle regulation tightening in China as inflection indicator for accelerated domestic specification.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Centralized compute platforms from NVIDIA and Qualcomm collapse actuator ECU boundaries toward zonal nodes. |
| Geographic Manufacturing Footprint | Indian premium SUV assembly near Pune and Chennai lacks rear-wheel steering supplier presence versus German corridors. |
| Platform Standardization | Audi, Porsche, and Bentley platform-sharing creates volume leverage for component-level actuator sourcing. |
| Long-term Supply Agreement | Volkswagen Group procurement benchmarks motor-inverter integration costs against standalone module pricing. |
| Backward Integration | Rare-earth magnet cost volatility rewards suppliers with captive neodymium-dysprosium sourcing or reduced-rare-earth motor designs. |
Research Methodology
Coverage spans Germany, United States, China, Japan, and South Korea, with primary inputs from each combining structured interviews with Tier-1 supplier procurement teams, OEM platform engineers, aftermarket distributors, and embedded software talent in Munich and Stuttgart labor markets. Secondary validation draws from vehicle production databases, IHS Markit registration data, SEC filings from listed suppliers, and ECHA REACH substance restriction timelines. Bottom-up actuator unit economics triangulate against top-down SUV platform penetration assumptions.
Granularity-level modeling operates at vehicle class, propulsion architecture, and motor technology tier. Segmentation dimensions include electromechanical versus electro-hydraulic product type, brushless DC versus servo motor technology, and OEM direct versus Tier-1 integrator channel structure. CAGRs derive from unit shipment trajectories and content-per-vehicle value capture across the analysis window. Industry-specific inputs incorporate EU Green Deal CO2 fleet standard compliance timelines and NHTSA advanced driver-assistance mandate phase-ins.
The model holds under steady regulatory enforcement and rare-earth supply continuity; deviation in Chinese export restrictions or accelerated software-defined vehicle adoption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding platform-sharing intensity and motor-gearbox integration rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Thrust Bearings Market
Vehicle Components
Car Modification Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Navigation Light Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Tailgate Chip Spreader Market
Vehicle Components
Engine Valve Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market