
 Auto Internal Connector Market | 2026-2036
Auto Internal Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Internal Connector Market Insights
Capital-intensity divergence between high-volume stamping houses and precision-contact specialists is collapsing as both camps invest in automated crimping and laser-welding lines. TE Connectivity Ltd. leverages captive metallurgy and die-casting scale to dominate engine-bay connector supply. Yazaki Corporation anchors its position through backward integration into copper-smelting and wire-harness assembly. Hirose Electric Co., Ltd. competes on miniaturized board-to-board interfaces for camera and sensor modules.
An auto internal connector is an electromechanical coupling device engineered to transmit signal or power between subsystems within a vehicle, typically rated for temperatures spanning minus 40 to 150 degrees Celsius and sealed to IP6K9K standards against fluid ingress. Its primary purpose is to maintain circuit integrity across vibration, thermal cycling, and electromagnetic interference in confined engine compartments and passenger cabins. Wire-to-board connectors command the largest revenue pool due to proliferation of electronic control units, while board-to-board variants represent the fastest-expanding category as zonal E/E architectures consolidate computing. Cable assemblies sustain premium pricing through customized shielding and overmolding for high-voltage battery loops.
NHTSA Federal Motor Vehicle Safety Standards, EPA greenhouse-gas regulations, and ISO 26262 functional-safety mandates collectively dictate connector material selection, flame-retardancy grades, and traceability requirements across the US automotive supply base. The EU Green Deal and REACH chemical restrictions further constrain halogenated plastics and certain tin-lead plating processes in European-sold vehicles. Stakeholders must monitor how 800-volt platform rollouts and zonal gateway consolidation redefine contact-density specifications and thermal-management demands.
Market Dynamics
Zonal E/E architectures are collapsing distributed wiring harnesses into centralized compute nodes, forcing connector suppliers to redesign contact-density specifications and thermal-management protocols for gateway consolidation.
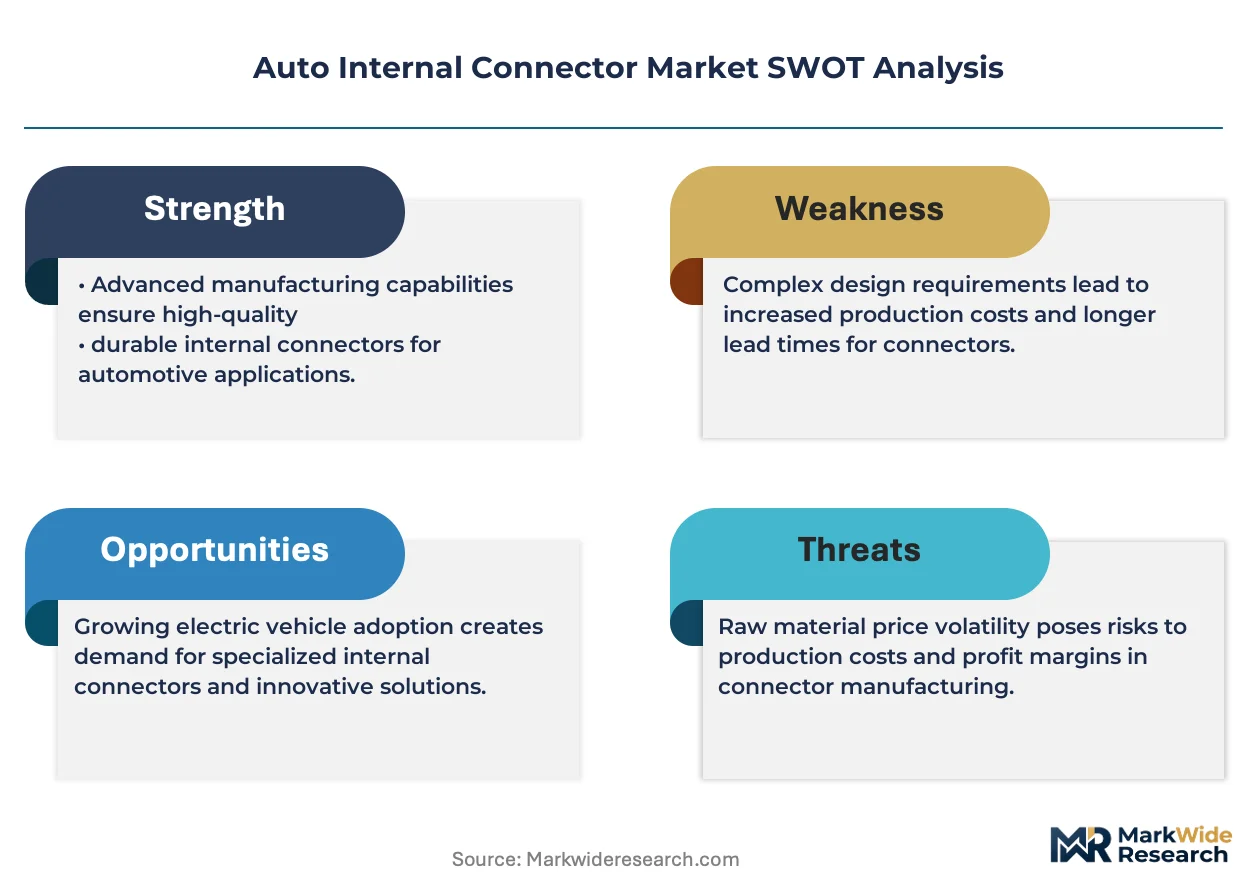
Growth Catalysts
- EPA Fuel-Economy Mandates:US greenhouse-gas regulations compel lightweight aluminum and composite connector housings to reduce vehicle mass and improve fleet efficiency ratings.
- Copper-Smelting Backward Integration:Japanese wire-harness assemblers securing captive metal supply chains insulate procurement from London Metal Exchange volatility and spot-market disruptions.
- 800-Volt Platform Rollouts:High-voltage battery loops in electric powertrains demand upgraded terminal plating and insulation systems rated for sustained thermal stress above 150 degrees Celsius.
Market Restraints
- Lithium and Rare-Earth Price Volatility:Battery-grade material cost swings transmit upstream through cable assembly pricing, compressing connector margin structures for tier-two suppliers.
- Halogenated Plastic Bans:EU REACH chemical restrictions eliminate legacy flame-retardant resins from European-sold vehicles, forcing compound reformulation and requalification cycles.
- Stamping House Consolidation:High-volume metal-forming capacity concentrates in German and Chinese manufacturing clusters, creating single-source vulnerability for precision-contact substrates.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for domestic manufacturing attract connector assembly investment away from traditional East Asian export bases.
- Camera Module Miniaturization:Board-to-board interconnects for advanced driver-assistance systems represent underpenetrated specification tiers with premium pricing power.
- ISO 26262 Functional-Safety Certification:Traceability mandates for ASIL-rated connectors create compliance-based differentiation against uncertified commodity suppliers.
Industry Challenges
- Automated Crimping Technician Shortage:Precision-assembly lines for laser-welded terminals require skilled operators scarce in emerging manufacturing regions.
- IP6K9K Requalification Timelines:Fluid-ingress testing protocols for engine-bay applications extend product-development cycles and delay platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Internal Connector Market |
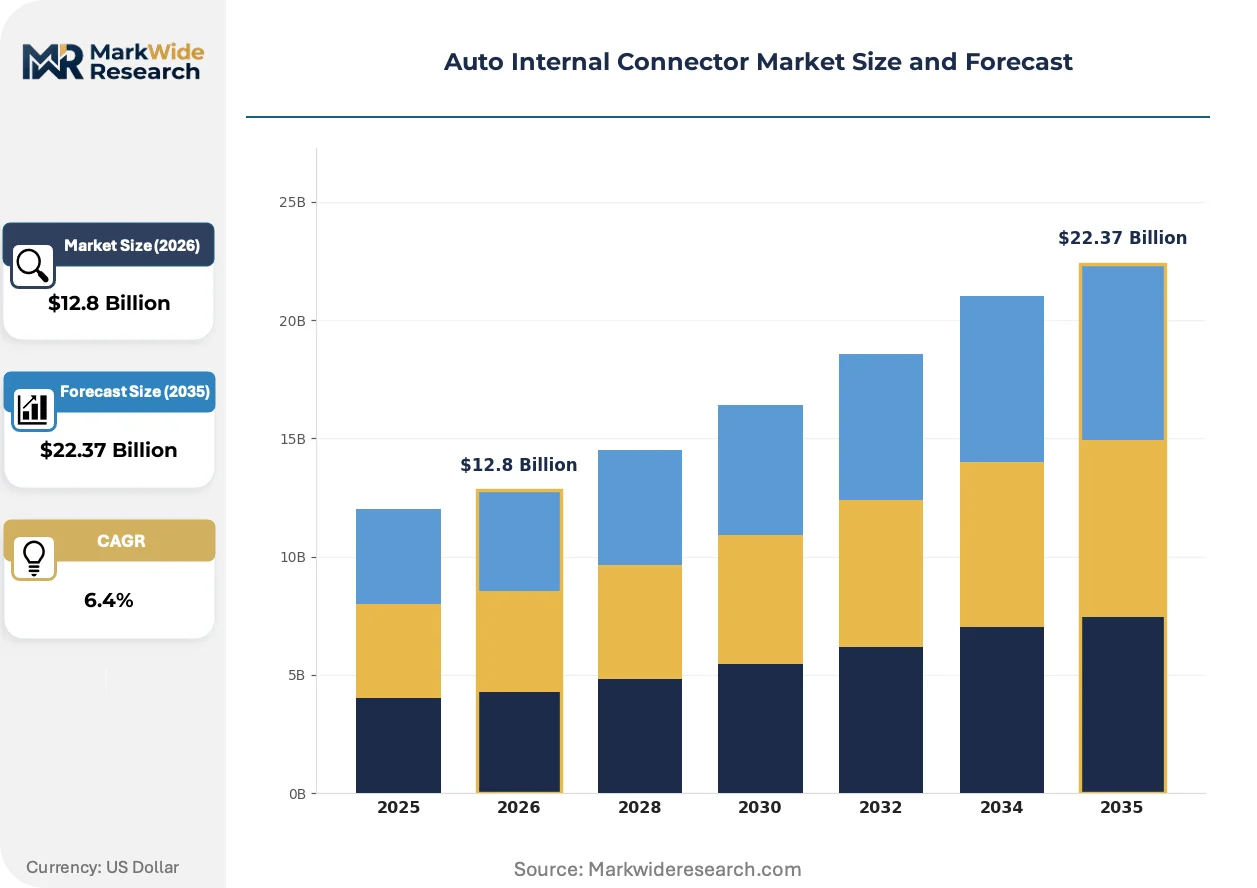
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire-to-Wire, Wire-to-Board, Board-to-Board, Cable Assemblies Material: Plastic, Metal, Copper, Rubber Application: Engine Control, Infotainment Systems, Power Distribution, Chassis End User: OEMs, Aftermarket Suppliers, Vehicle Manufacturers, Tier-1 Suppliers |
| Companies Covered | TE Connectivity Ltd., Aptiv PLC, Amphenol Corporation, Yazaki Corporation, Molex, Sumitomo Electric Industries, Hirose Electric Co., Ltd., Kyocera Corporation, Rosenberger Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Internal Connector Market Trends and Innovations
Connector architectures are fragmenting into modular, software-defined configurations that separate mechanical housing from electrical performance, enabling over-the-air specification updates without physical replacement.
Multi-layer flexible printed circuit interconnects are decomposing traditional wire-to-board assemblies in cabin electronics. Tier-one suppliers adopting these substrates for infotainment backplanes reduce harness mass by sixty percent. This transition is decomposing the revenue pool for discrete crimped terminals while expanding laminate processing capacity.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are accelerating sealed-connector redesigns using dry-film lubricants and alternative elastomer compounds. Manufacturers serving the European passenger-car market must eliminate perfluorinated materials from grommet and seal geometries by mandated deadlines. German OEMs are pushing this requirement into global platform specifications to avoid regional SKU proliferation.
Fleet operators and contract manufacturers are consolidating connector procurement through direct long-term agreements with metallurgy houses, bypassing traditional distribution channels. Tier-two harness assemblers now face disintermediation as buyers seek volume commitments on copper and tin-plated terminals. This pattern is most pronounced in China's Yangtze River Delta automotive cluster, where state-owned vehicle groups centralize component sourcing.
Auto Internal Connector Market Segmentation
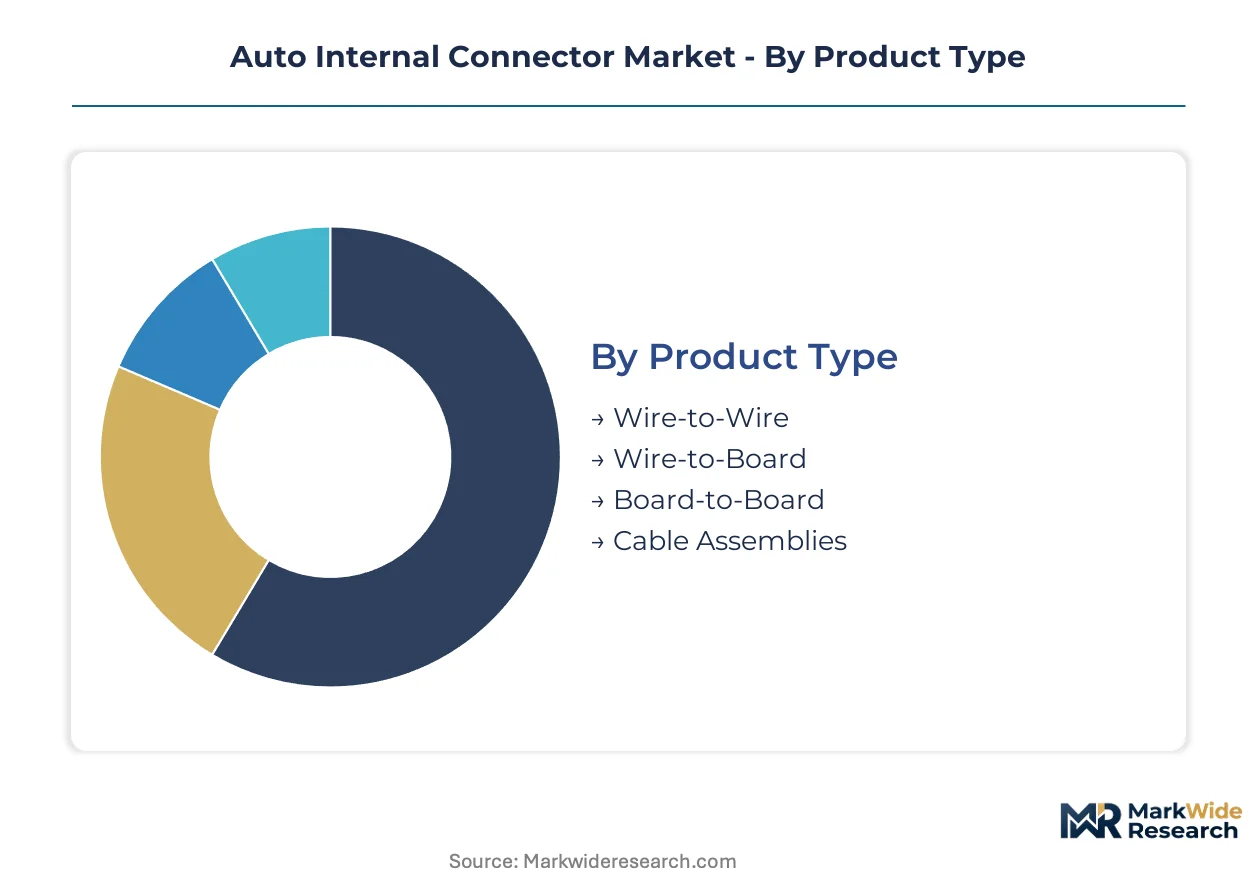
Connector specification tiers diverge sharply in margin structure, with high-voltage and miniaturized variants commanding premiums over commodity crimp terminals. Understanding where value concentrates across product architectures, material grades, and application tiers enables targeted capacity allocation and qualification investments.
Product Type:
Premium margin pools sit in assemblies requiring customized shielding and thermal management, while standard crimp terminals face pricing compression from stamping scale economies.
- Wire-to-Wire:Crimp-terminated couplings linking harness segments within distributed electrical architectures. Demand concentrates in legacy ICE powertrains across German and Japanese OEM supply chains, where NHTSA safety mandates on circuit integrity sustain qualification barriers for new entrants.
- Wire-to-Board:Electromechanical interfaces between cable harnesses and printed circuit substrates, typically housing 2 to 120 contact positions. This segment captures the largest revenue pool due to ECU proliferation in zonal E/E architectures, with procurement volumes centering on China's Yangtze River Delta automotive cluster.
- Board-to-Board:Direct PCB interconnects eliminating intermediate wiring. Miniaturized variants for camera and sensor modules are expanding most quickly as ADAS penetration deepens.
- Cable Assemblies:Pre-terminated harnesses with integrated shielding and overmolding for high-voltage battery loops. Customized configurations for 800-volt platforms sustain premium pricing through proprietary terminal plating specifications.
The dominant share belongs to Wire-to-Board, while Board-to-Board is closing the gap fastest.
Material:
Raw material selection dictates thermal ceiling, flame-retardancy rating, and regulatory compliance scope across regional sales footprints.
- Plastic:Injection-molded housings in PBT, PA66, and high-temperature thermoplastics. REACH chemical restrictions in Europe are forcing compound reformulation away from halogenated flame retardants, extending requalification timelines for suppliers serving EU-destined vehicle platforms.
- Metal:Die-cast aluminum and zinc alloy shells for engine-bay shielding and structural retention. Demand clusters in powertrain applications where EPA fuel-economy mandates drive lightweighting substitutions for heavier brass housings.
- Copper:Electrical-grade alloys for terminal contacts and current-carrying elements. Japanese wire-harness assemblers have secured captive smelting capacity to insulate procurement from London Metal Exchange volatility.
- Rubber:Elastomer seals and grommets rated for IP6K9K fluid ingress protection. EU F-Gas Regulation phase-down schedules are accelerating redesigns using dry-film lubricants to replace perfluorinated compounds.
Plastic retains volume leadership, though Metal is gaining share fastest on powertrain lightweighting requirements.
Application:
Functional criticality and environmental exposure severity determine qualification rigor and supplier switching costs.
- Engine Control:Sealed interconnects for ECUs, sensors, and actuators in underhood environments. ISO 26262 ASIL ratings create compliance-based differentiation, with procurement concentrated among German powertrain specialists.
- Infotainment Systems:Board-to-board and wire-to-board interfaces for display modules, head units, and telematics. Multi-layer flexible printed circuits are decomposing traditional discrete terminal demand in cabin electronics.
- Power Distribution:High-current terminals for battery management, inverter, and charging systems. 800-volt platform rollouts are forcing thermal-management specification upgrades above legacy 150-degree Celsius ratings.
- Chassis:Vibration-resistant couplings for braking, steering, and suspension control modules. Functional-safety traceability mandates under NHTSA guidelines sustain premium pricing for certified suppliers.
Engine Control holds the largest installed base, yet Power Distribution shows the steepest expansion trajectory on electrification capex.
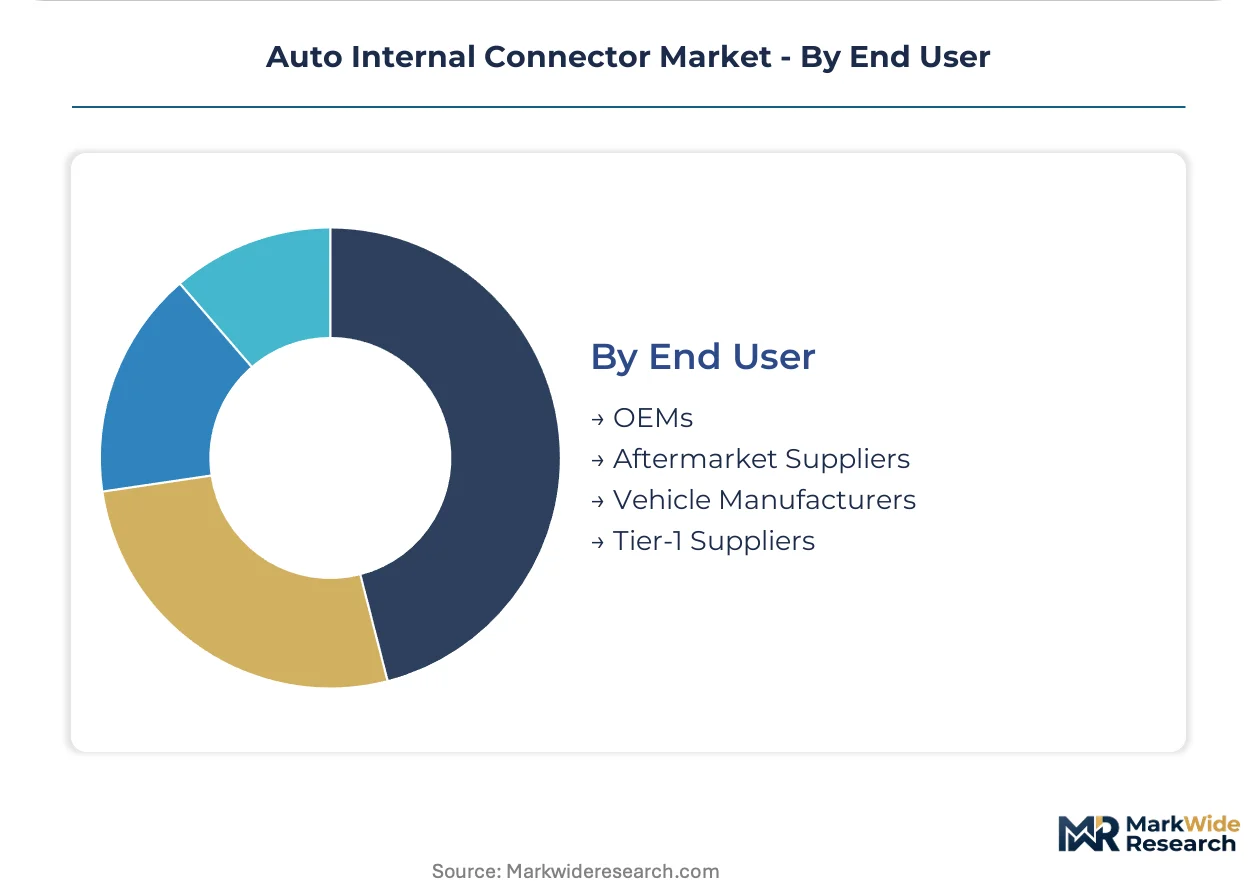
End User:
Procurement authority and technical specification control vary sharply across the supply chain hierarchy.
- OEMs:Vehicle brand owners defining platform-level connector specifications and approving supplier qualifications. Direct long-term agreements with metallurgy houses are consolidating procurement authority, bypassing traditional distribution channels.
- Aftermarket Suppliers:Independent distributors and repair network servicers. Replacement demand for legacy harness architectures sustains revenue for crimp-terminal specialists with broad vehicle coverage.
- Vehicle Manufacturers:State-owned and private vehicle groups in China centralizing component sourcing through Yangtze River Delta procurement consortia.
- Tier-1 Suppliers:Wire-harness assemblers and subsystem integrators. Automated crimping technician shortages constrain capacity expansion in emerging manufacturing regions.
OEMs dominate specification authority, while Tier-1 Suppliers face margin compression from upstream disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connector procurement patterns diverge sharply across automotive manufacturing clusters, with electrification intensity dictating specification complexity and thermal-management requirements in each geography.
China
State-owned vehicle groups in the Yangtze River Delta centralize sourcing through procurement consortia, consolidating demand for high-voltage interconnects in 800-volt battery platforms. MIIT dual carbon goals accelerate domestic connector qualification for export-bound EVs. Shanghai and Suzhou manufacturing corridors concentrate precision-stamping capacity for wire-harness assemblers serving both local OEMs and German joint ventures.
Germany
Powertrain specialists in Bavaria and Baden-Württemberg drive demand for ISO 26262 ASIL-rated engine-bay connectors as zonal E/E architectures consolidate ECU functions. KBA type-approval protocols enforce traceability mandates that extend development timelines for new entrants. Stuttgart and Wolfsburg industrial corridors anchor Continental and Bosch procurement networks for sealed interconnect systems.
United States
Detroit Three OEMs leverage NHTSA Federal Motor Vehicle Safety Standards to sustain qualification barriers against Asian competitors in legacy ICE harness architectures. EPA greenhouse-gas regulations compel lightweight aluminum housing substitutions in Michigan and Ohio assembly plants. Mexican maquiladora corridors absorb wire-to-board volume for cross-border just-in-sequence delivery.
Japan
Wire-harness assemblers in Aichi and Shizuoka prefectures have secured captive copper-smelting capacity to insulate procurement from London Metal Exchange volatility. METI industrial policy supports domestic qualification for next-generation camera-module miniaturization. Toyota and Honda keiretsu networks concentrate board-to-board specification authority within Nagoya manufacturing clusters.
India
Tamil Nadu and Maharashtra automotive corridors attract connector assembly investment under PLI scheme production-linked incentives, diverting capacity from traditional East Asian export bases. BIS certification timelines for IP6K9K sealing standards delay platform launches for European OEMs sourcing locally. Chennai and Pune industrial zones concentrate tier-one harness operations for Maruti Suzuki and Hyundai Motor India.
Auto Internal Connector Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages in metallurgy and die-casting separating the two groups. The upper tier commands specification authority through captive raw-material supply chains and automated assembly lines. Three archetypes populate the competitive map: diversified interconnect conglomerates with multi-industry portfolios, wire-harness integrators with backward metal control, and precision-contact specialists focused on miniaturized board-to-board interfaces. Consolidation pressure manifests through direct long-term agreements between OEMs and metallurgy houses, plus automated crimping capacity expansion in low-cost manufacturing regions.
Among diversified interconnect conglomerates, TE Connectivity Ltd. and Amphenol Corporation exemplify scale-driven positioning through multi-platform supply relationships. Yazaki Corporation anchors the wire-harness integrator archetype with demonstrated upstream control over copper supply chains. Hirose Electric Co., Ltd. occupies the precision-contact specialist tier, representing miniaturization capabilities for sensor-module applications. These three patterns illustrate how competitive advantage concentrates across metallurgy access, assembly automation, and specification intimacy with tier-one subsystem integrators.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| Aptiv PLC |
| Amphenol Corporation |
| Yazaki Corporation |
| Molex |
| Sumitomo Electric Industries |
| Hirose Electric Co., Ltd. |
| Kyocera Corporation |
| Rosenberger Group |
| Others |
Pricing and Supply Chain Analysis
Aluminum housing substitution for legacy brass die-castings simultaneously redistributes procurement leverage toward Yangtze River Delta stamping clusters and compresses margin structures for European suppliers facing REACH compliance adders. This lightweighting imperative under EPA fuel-economy mandates forces tier-two suppliers to absorb compound reformulation costs while German OEMs consolidate volume commitments with metallurgy houses.
Pricing Analysis
Long-term offtake agreements between Detroit Three OEMs and copper-smelting houses dominate procurement structures, displacing spot-market transactions for battery-grade terminal plating. Three-tier pricing structure across ASIL-certified, industrial-grade, and commodity crimp terminals reflects ISO 26262 traceability premiums and volume scale discounts. Cost compression in standard wire-to-wire assemblies intensifies because stamping capacity concentrates in Chinese and German manufacturing corridors. Aftermarket distributors exhibit highest price sensitivity due to inventory holding costs, while OEM platform engineers prioritize qualification reliability over unit economics.
Supply Chain Analysis
Straits of Malacca transit lanes for copper concentrate shipments from Indonesian smelters to Japanese wire-harness assemblers constitute a logistics chokepoint with tariff exposure to ASEAN trade rule changes. Manufacturing capacity clusters in China, Germany, and Japan, with precision-stamping feedstock drawing from Zambian and Chilean cathode sources. Single-source vulnerability pervades high-temperature thermoplastic compounds subject to EU F-Gas Regulation phase-down schedules. Distribution runs through tier-one harness assemblers with direct OEM relationships, bypassing traditional component distributors in the Yangtze River Delta automotive cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-layer flexible printed circuit substitution for discrete wire-to-board assemblies threatens incumbent connector suppliers with revenue pool decomposition in cabin electronics segments. Defense against this displacement requires targeted capability investments and specification control strategies.
For Market Incumbents: Shield revenue concentration in engine-bay applications by deepening captive metallurgy access and accelerating IP6K9K requalification timelines for 800-volt thermal specifications. Secure backward integration into copper-smelting capacity to insulate procurement from London Metal Exchange volatility and spot-market disruptions threatening margin structures. For New Entrants and Emerging Players: Camera module miniaturization for advanced driver-assistance systems represents an under-served specification tier where precision-contact specialists command premium pricing power. Target board-to-board interconnect qualification for sensor modules in Nagoya manufacturing clusters, leveraging ISO 26262 functional-safety certification as a compliance-based differentiation mechanism against commodity suppliers. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down deadlines reshape the acquisition landscape by elevating compound reformulation capabilities above pure stamping scale. Prioritize targets with demonstrated dry-film lubricant expertise and alternative elastomer seal geometries. Watch MIIT dual carbon goal implementation timelines as the inflection signal for Chinese domestic qualification requirements on export-bound EV platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Smelting | Captive metal supply chains insulate Yazaki and Japanese keiretsu networks from LME price volatility. |
| ISO 26262 ASIL Certification Investment | Traceability mandates create compliance-based differentiation for engine-bay connector suppliers serving German OEMs. |
| 800-Volt Thermal Specification Upgrade | Upgraded terminal plating and insulation systems capture premium pricing in battery loop cable assemblies. |
| India PLI Scheme Manufacturing Footprint | Production-linked incentives divert connector assembly investment from East Asian export bases to Tamil Nadu corridors. |
| Multi-Layer Flexible Circuit Partnership | Laminate processing alliances decompose discrete terminal demand while preserving specification influence in infotainment backplanes. |
Research Methodology
A standing panel of OEM platform engineers, tier-one harness procurement managers, copper-smelting operations directors, and automotive regulatory affairs specialists provided ongoing calibration against secondary validation from SEC 10-K filings, MIIT production databases, IHS Markit vehicle registration data, and EU REACH substance restriction updates. This primary fieldwork combined with customs trade records and KBA type-approval documentation enabled bottom-up and top-down triangulation across connector specification tiers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling covering wire-to-board, board-to-board, wire-to-wire, and cable assembly architectures alongside material grade, application criticality, and regional production cluster dimensions. CAGRs derived from platform-level content-per-vehicle trajectories incorporated 800-volt rollout schedules, zonal E/E architecture adoption curves, and ADAS penetration assumptions without year-specific pinning.
Underlying assumptions cover electrification capex continuity, copper price band stability, and REACH compliance timeline adherence, with deviation risk concentrated in rare-earth material cost swings and automated crimping technician availability in emerging manufacturing regions. Practitioners should keep alternative scenarios live as EU F-Gas Regulation enforcement intensity and MIIT dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Automotive HVAC Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Float Glass for Automotive Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market