
 Saudi Arabia Automotive Sensors Market | 2026-2036
Saudi Arabia Automotive Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Automotive Sensors Market Analytics
Single-source procurement for advanced driver-assistance chipsets is decoupling as domestic vehicle assemblers diversify supplier bases to mitigate semiconductor shortage risks. Robert Bosch GmbH leverages its manufacturing scale to anchor the pressure sensor segment for engine management systems. Infineon Technologies AG differentiates through MEMS fabrication capabilities that sustain its position in safety-critical applications.
Saudi Arabia automotive sensors are electromechanical transducers that convert physical quantities—temperature, pressure, proximity, or gas composition—into electrical signals for vehicle electronic control units, typically operating across temperature ranges from minus 40 to 150 degrees Celsius. These devices enable real-time monitoring of engine performance, occupant protection, and emissions compliance in internal combustion and electrified powertrains. Pressure sensors dominate the product type landscape due to their ubiquity in fuel injection and tire pressure monitoring systems, while MEMS technology captures expanding margin pools through miniaturization and batch fabrication economies. The safety systems application category is outpacing engine control in growth velocity as regulatory mandates for automatic emergency braking and lane-keeping assistance proliferate.
The Saudi Standards, Metrology and Quality Organization enforces vehicle safety and electromagnetic compatibility standards that dictate sensor calibration protocols for OEM certification. SFDA oversight of automotive electronics imports adds a compliance layer that shapes tier-1 supplier qualification timelines. Stakeholders must monitor how Saudi Arabia's local content requirements under Vision 2030 industrial policy reshape sourcing decisions for foreign sensor manufacturers serving domestic vehicle assemblers.
Market Dynamics
Electrification mandates under Saudi Vision 2030 are forcing sensor architecture redesigns as domestic assemblers pivot from internal combustion to hybrid and battery-electric platforms. This transition compresses development cycles and recalibrates supplier qualification criteria across the Riyadh-Jeddah corridor.
Growth Catalysts
- Euro-equivalent emission norms:SFDA-enforced standards accelerate oxygen sensor replacement cycles in legacy fleets and mandate denser emissions monitoring arrays in new vehicle platforms.
- Autonomous driving feature deployment:Luxury passenger vehicle OEMs expand LiDAR and radar sensor suites for highway pilot and parking assistance functions.
- Industrial cluster concentration:Tier-1 supplier parks co-located with vehicle assembly plants in the Riyadh-Jeddah corridor reduce logistics friction and enable just-in-sequence delivery models.
Market Restraints
- Semiconductor input volatility:Foundry capacity constraints for MEMS wafers and ASICs create order backlog uncertainty for safety-critical sensor modules.
- Single-source supply concentration:Advanced driver-assistance chipsets remain concentrated among a limited set of fabrication facilities, exposing domestic assemblers to allocation risk.
- Technical integration complexity:Legacy 12-volt electrical architectures in existing Saudi vehicle fleets resist seamless integration with 48-volt sensor networks required for advanced safety systems.
Strategic Opportunities
- Eastern Province industrial zones:Greenfield manufacturing sites near Jubail offer tariff-advantaged production bases for sensor exporters serving Gulf Cooperation Council markets.
- Local content incentive alignment:Vision 2030 industrial policy creates procurement preference structures for foreign manufacturers establishing domestic assembly or testing operations.
- Connected vehicle data monetization:Telematics sensor networks enable aftermarket service revenue streams through predictive maintenance and usage-based insurance partnerships.
Industry Challenges
- Calibration technician scarcity:SFDA certification protocols for electromagnetic compatibility testing require specialized expertise that outpaces domestic training program output.
- Legacy system integration friction:Retrofitting advanced driver-assistance sensors into existing vehicle platforms demands extensive harness redesign and control unit reprogramming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Automotive Sensors Market |
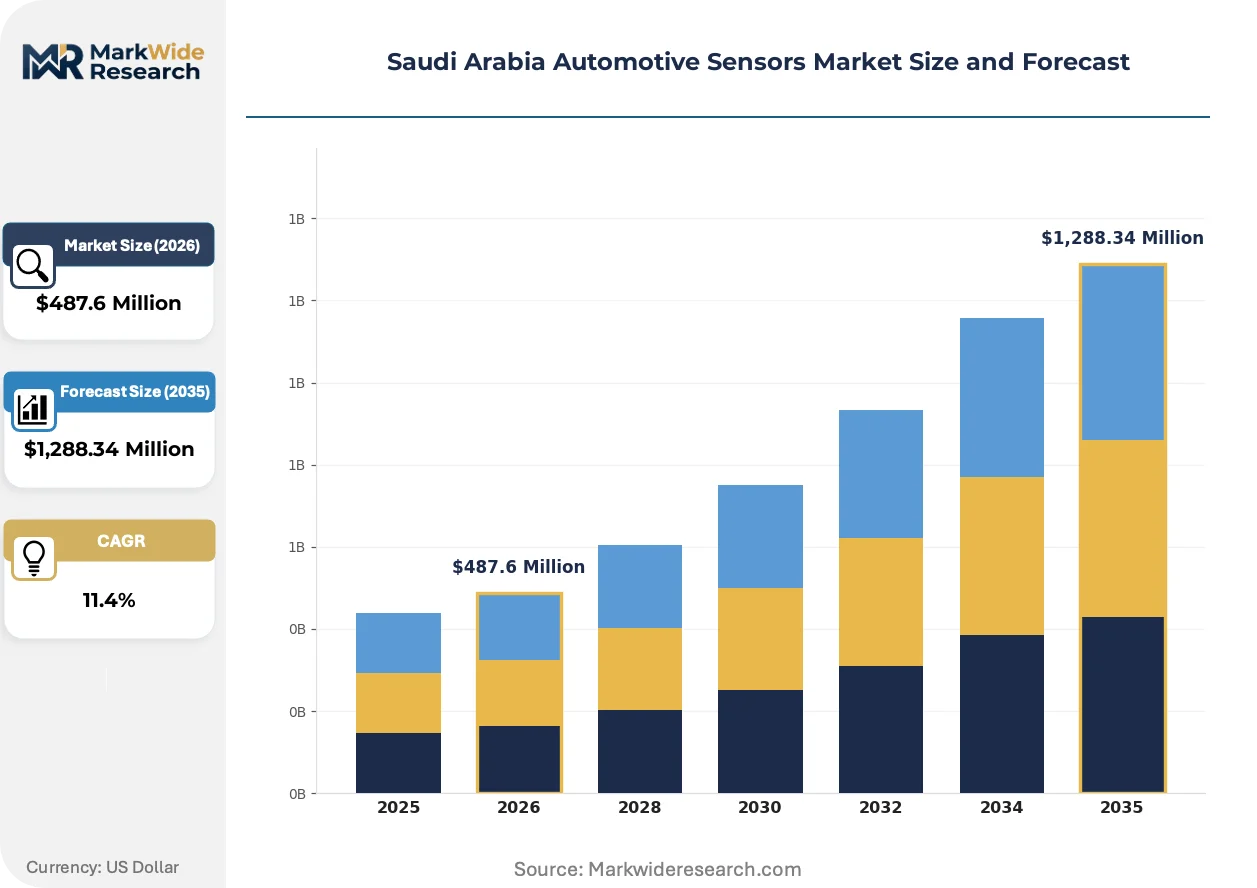
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Proximity Sensors, Oxygen Sensors Technology: MEMS, Capacitive, Ultrasonic, Optical Application: Engine Control, Safety Systems, Navigation, Comfort Features End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Infineon Technologies AG, Texas Instruments Incorporated, Continental AG, Sensata Technologies, Inc, BorgWarner Inc, Analog Devices, Inc, ZF Friedrichshafen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Automotive Sensors Market Evolving Landscape
Sensor fusion architectures are displacing discrete component strategies as Saudi OEMs consolidate multiple physical sensing modalities into unified perception stacks. This convergence compresses bill-of-materials complexity while elevating software calibration requirements.
Solid-state LiDAR is absorbing market share from mechanical spinning units in premium vehicle segments. Domestic luxury assemblers specify chip-scale photonic devices for highway automation suites. The technology is absorbing margin pools previously captured by precision motor suppliers and reducing sensor package volumes by two-thirds.
Saudi Standards, Metrology and Quality Organization mandates for vehicle cybersecurity management systems now extend to sensor data integrity protocols. OEMs must demonstrate tamper-evident logging for safety-critical inputs. The regulation accelerates hardware security module integration in brake and steering angle sensors.
Fleet operators in the Kingdom are consolidating sensor procurement under long-term service agreements rather than transactional component purchases. Tier-1 suppliers respond with guaranteed uptime contracts bundled with predictive replacement scheduling. This shift concentrates buying power among Saudi ride-hail and logistics platforms.
Saudi Arabia Automotive Sensors Market Segmentation
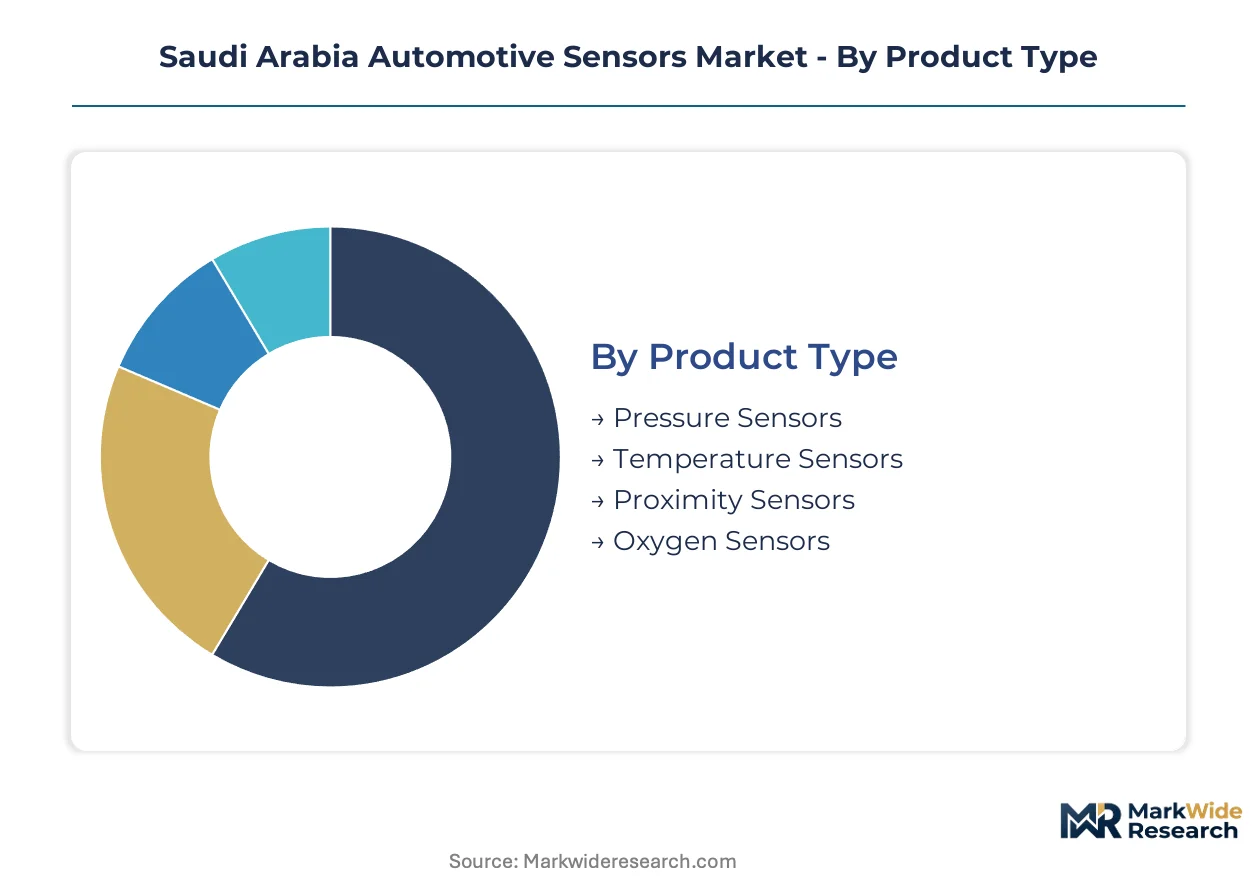
Sensor procurement patterns across the Riyadh-Jeddah corridor fragment along technology maturity curves and regulatory compliance tiers. Domestic vehicle assemblers calibrate supplier qualification criteria differently across each dimension, creating distinct margin pools and technical barriers to entry.
Product Type:
Supply concentration in pressure sensor fabrication anchors the segment, with Bosch and Continental capturing dominant share through scale economies in piezoresistive wafer production.
- Pressure Sensors:Piezoresistive MEMS elements measure manifold absolute pressure, fuel rail pressure, and tire pressure across minus 40 to 150 degrees Celsius operating ranges. Riyadh-based engine management system integrators source these most heavily for direct injection platforms under SFDA emission enforcement. Robert Bosch GmbH leverages its Reutlingen wafer fab to lock in multi-year supply agreements with domestic assemblers.
- Temperature Sensors:Thermistor-based and RTD devices monitor coolant, exhaust gas, and battery thermal states in electrified powertrains. Jeddah vehicle assembly plants specify these for hybrid transition programs under Vision 2030 electrification mandates, with procurement concentrating among suppliers offering AEC-Q200 automotive qualification.
- Proximity Sensors:Inductive and capacitive variants detect parking obstacles and automatic door activation triggers. Tier-1 supplier parks near King Abdullah Economic City consolidate procurement for luxury SUV platforms.
- Oxygen Sensors:Zirconia and wideband lambda probes enable closed-loop fuel trim compliance with Euro-equivalent norms. Replacement cycle acceleration in legacy fleets drives aftermarket volume concentration.
Today's leader: Pressure Sensors. Tomorrow's challenger: Oxygen Sensors.
Technology:
Cost tier stratification separates MEMS batch fabrication from discrete component assembly, with capital intensity determining supplier eligibility for safety-critical contracts.
- MEMS:Micro-electromechanical systems integrate mechanical elements, sensors, actuators, and electronics on silicon substrates through semiconductor batch processing. The Riyadh-Jeddah corridor sources these primarily for airbag accelerometers and gyroscopic stability control, with Infineon Technologies AG dominating through its Dresden 200mm MEMS foundry capacity.
- Capacitive:Electrode-gap variation detects pressure, humidity, and touch inputs with low power consumption. Domestic comfort feature integration favors these for climate control and infotainment interfaces.
- Ultrasonic:Piezoelectric transducers emit high-frequency pulses for parking assistance and blind-spot detection. Eastern Province logistics vehicle fleets specify these for warehouse maneuvering safety.
- Optical:Photodiode and CMOS image sensor arrays enable ambient light detection and driver monitoring systems. Solid-state LiDAR adoption in luxury segments absorbs expanding margin pools.
MEMS commands current procurement volumes. Optical architectures are climbing the fastest as LiDAR penetrates highway automation suites.
Application:
Volume distribution tilts toward powertrain management, though regulatory mandates are recalibrating growth trajectories across the four functional categories.
- Engine Control:Sensors monitor combustion parameters, exhaust composition, and thermal states to optimize fuel efficiency and emission compliance. SFDA-enforced Euro-equivalent standards sustain replacement demand across Saudi Arabia's legacy internal combustion fleet while hybrid platforms require expanded sensor arrays for thermal and electrical state monitoring.
- Safety Systems:Accelerometers, gyroscopes, radar, and camera modules enable automatic emergency braking, lane-keeping assistance, and occupant protection deployment. Domestic luxury OEMs specify dense sensor suites for highway pilot functions, with calibration protocols mandated under Saudi Standards, Metrology and Quality Organization electromagnetic compatibility certification.
- Navigation:GPS receivers, magnetometers, and inertial measurement units support positioning and heading determination. Fleet telematics integration drives consolidation under long-term service agreements.
- Comfort Features:Ambient light, humidity, and occupancy sensors automate climate and lighting adjustment. Premium vehicle segments specify these for differentiation.
Engine Control retains installed base dominance. Safety Systems are gaining share fastest through regulatory mandate proliferation.
End User:
Customer type determines contract structure, with OEMs demanding qualification depth and aftermarket providers prioritizing inventory velocity.
- OEMs:Original equipment manufacturers specify sensor performance standards, calibration protocols, and multi-year supply agreements for new vehicle platforms. Domestic luxury passenger vehicle producers in the Riyadh-Jeddah corridor consolidate procurement under single-source arrangements that are now diversifying to mitigate semiconductor allocation risk.
- Tier-1 Suppliers:System integrators combine sensors with control electronics and software for just-in-sequence delivery to vehicle assembly plants. Supplier park co-location in King Abdullah Economic City reduces logistics friction.
- Aftermarket Providers:Independent distributors and service networks supply replacement sensors for legacy fleet maintenance. Oxygen sensor replacement cycle acceleration under emission enforcement concentrates demand here.
- Vehicle Assemblers:Domestic manufacturing operations source complete sensor modules for local production platforms. Vision 2030 local content requirements reshape sourcing decisions toward domestic testing and assembly operations.
Tier-1 Suppliers intermediate current procurement flows. Vehicle Assemblers are emerging as direct procurement nodes through localization incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Riyadh-Jeddah corridor anchors Saudi Arabia's automotive sensor demand through co-located vehicle assembly plants and tier-1 supplier parks. Domestic production clusters concentrate procurement flows for engine management and safety-critical modules. SFDA emission enforcement and Vision 2030 electrification mandates reshape regional sourcing patterns across the Kingdom's industrial zones.
Riyadh
Domestic vehicle assemblers in Riyadh consolidate sensor procurement for luxury passenger platforms with dense ADAS suites. Saudi Standards, Metrology and Quality Organization electromagnetic compatibility certification dictates supplier qualification timelines for OEMs operating in the capital region. King Abdullah Financial District proximity attracts tier-1 system integrators establishing technical centers for calibration protocol development.
Eastern Province
Jubail industrial city offers tariff-advantaged manufacturing bases for sensor exporters serving Gulf Cooperation Council markets. The zone's petrochemical infrastructure supports specialty polymer feedstock for sensor housings and connector systems. Domestic assemblers source pressure sensors for engine management from operations co-located with downstream material processing.
Western Region
Jeddah vehicle assembly plants specify temperature sensors for hybrid transition programs under Vision 2030 electrification timelines. King Abdullah Economic City supplier parks enable just-in-sequence delivery models that reduce logistics friction for safety system modules. Proximity to Red Sea shipping lanes accelerates import clearance for MEMS wafer substrates.
NEOM Northwest
The giga-project's autonomous mobility pilot programs generate specification pull for solid-state LiDAR and sensor fusion architectures. NEOM's regulatory sandbox allows testing of cybersecurity-hardened sensor data protocols ahead of nationwide SFDA mandates. Domestic technology partners establish validation facilities for perception stack integration in controlled environment deployments.
Saudi Arabia Automotive Sensors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue MEMS fabrication specialization and optical sensing architectures. The supplier base concentrates around semiconductor-scale manufacturers with automotive qualification depth and system integrators with software calibration capabilities. Two strategic archetypes dominate: scale-driven component fabricators leveraging wafer fab capacity, and application-focused specialists bundling sensors with predictive analytics. Capacity expansion and strategic partnerships represent the dominant competitive moves as domestic assemblers diversify supplier bases to mitigate allocation risk.
Among German-based industrial conglomerates, Robert Bosch GmbH and Continental AG exemplify scale-driven archetypes with captive semiconductor fabrication and tier-1 system integration capabilities. Infineon Technologies AG, also German-headquartered, occupies a position within the MEMS specialization tier through foundry-scale production of safety-critical microelectromechanical elements. These three entities anchor the competitive structure by representing distinct capability configurations—vertically integrated system supply, component-scale manufacturing, and semiconductor-process specialization—that domestic vehicle assemblers evaluate against Vision 2030 localization incentives.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Infineon Technologies AG |
| Texas Instruments Incorporated |
| Continental AG |
| Sensata Technologies, Inc |
| BorgWarner Inc |
| Analog Devices, Inc |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
Sovereign-backed industrial development funds and family-owned component distributors anchor Saudi Arabia's automotive sensor procurement landscape, concentrating buying power among Riyadh-Jeddah corridor assemblers while transmitting Vision 2030 localization incentives into supplier pricing discipline.
Pricing Analysis
MEMS wafer foundry costs and AEC-Q200 automotive qualification tiers transmit directly into sensor module pricing, with three-tier pricing structure across premium, standard, and economy levels separating safety-critical brake sensors from aftermarket replacement oxygen probes. SFDA electromagnetic compatibility certification requirements widen spreads between qualified and unqualified suppliers. Pricing pressure stems from semiconductor input volatility as foundry allocation constraints compress margins on radar and LiDAR chipsets. Fleet operators consolidating under long-term service agreements exhibit lowest price sensitivity, while independent aftermarket distributors face acute cost compression.
Supply Chain Analysis
Vision 2030 local content requirements are reshaping sourcing decisions toward domestic testing and assembly operations, yet silicon wafer fabrication remains concentrated in Germany, Taiwan, and South Korea. Piezoresistive MEMS elements, zirconia ceramic substrates, and photonic integrated circuits constitute critical input dependencies. Single-source vulnerability in advanced driver-assistance chipsets exposes domestic assemblers to allocation risk during foundry capacity crunches. Distribution runs through tier-1 supplier parks co-located with vehicle assembly plants in King Abdullah Economic City, enabling just-in-sequence delivery models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's automotive sensor market reads as a late-cycle quality story, with luxury OEM demand shifting toward dense LiDAR and sensor fusion specifications that reward calibration expertise over commodity volume.
For Market Incumbents: Anticipate semiconductor allocation volatility by diversifying foundry relationships beyond single-source MEMS contracts, while deepening software calibration capabilities to defend margin pools against emerging optical sensing specialists. SFDA cybersecurity mandates for sensor data integrity protocols create certification barriers that favor incumbents with established electromagnetic compatibility testing infrastructure. For New Entrants and Emerging Players: Capture white-space opportunity in solid-state LiDAR integration services for NEOM autonomous mobility pilots, where regulatory sandbox testing precedes nationwide SFDA mandates. The aftermarket oxygen sensor replacement cycle under Euro-equivalent emission enforcement offers the most penetrable volume tier for distributors with SFDA import clearance capabilities. Lead with predictive maintenance analytics bundled with sensor hardware to differentiate from transactional component vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-2 MEMS fabricators lacking automotive qualification depth but possessing transferable batch processing expertise. Long-term viability hinges on Saudi Arabia's electrification trajectory and the speed of hybrid platform sensor architecture redesigns. Watch for inflection in domestic vehicle assembler direct procurement patterns as Vision 2030 localization incentives mature beyond pilot programs.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Secures wafer allocation from Dresden or Reutlingen facilities for safety-critical sensor volumes. |
| SFDA Certification Investment | Accelerates electromagnetic compatibility approval timelines for OEM qualification cycles. |
| NEOM Validation Facility | Positions sensor fusion architectures for regulatory sandbox testing ahead of nationwide mandates. |
| Long-Term Service Agreement | Locks fleet operator procurement under guaranteed uptime contracts with predictive replacement scheduling. |
| Local Assembly Operation | Aligns with Vision 2030 content requirements to secure preferential procurement from domestic vehicle assemblers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and SFDA regulatory affairs specialists with secondary validation against vehicle production databases, IHS Markit registration data, customs import records, and Saudi Standards, Metrology and Quality Organization certification filings. Bottom-up sensor shipment estimates triangulated against top-down vehicle assembly forecasts across the analysis window.
Historical reference periods anchored the projection horizon to pre-pandemic baseline volumes and post-recovery normalization trends. The analytical framework modeled segmentation dimensions spanning product type, technology node, application function, propulsion architecture, and regional production cluster. CAGRs derived from fitted growth curves incorporating content-per-vehicle trajectories for electrified platforms and regulatory mandate implementation schedules. Industry-specific inputs included SFDA emission enforcement timelines and Vision 2030 industrial policy incentive structures.
Semiconductor foundry capacity constraints, SFDA regulatory interpretation shifts, and domestic vehicle assembler localization decisions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about electrification penetration and tier-1 supplier consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market