
 Voice Coil Motor Driver Market | 2026-2036
Voice Coil Motor Driver Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Coil Motor Driver Market Analytics
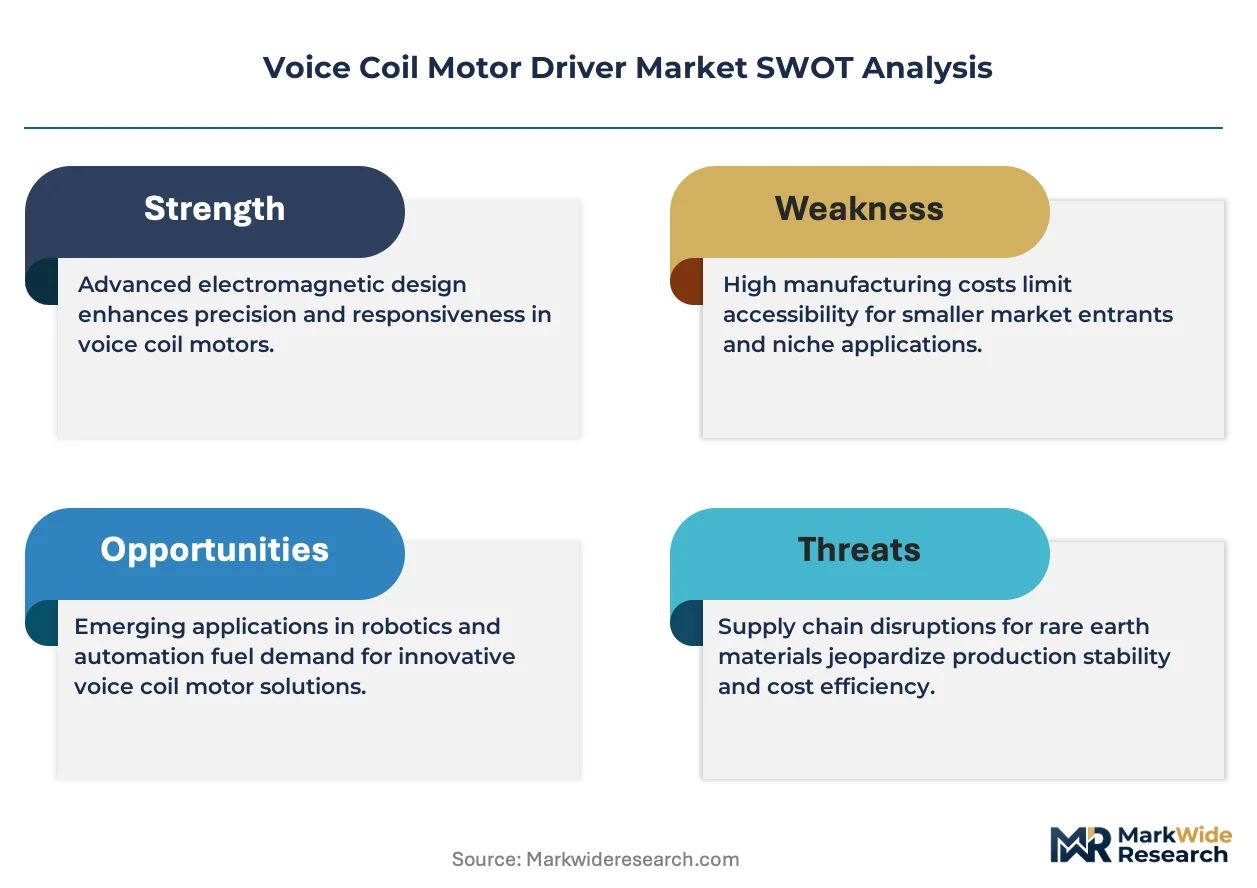
Medical device deployment is expanding as the fastest-growing end-use vertical for voice coil motor drivers, displacing traditional audio equipment applications in revenue priority. Texas Instruments Inc. leverages its analog semiconductor heritage to dominate precision current-control architectures. STMicroelectronics NV anchors European supply through its integrated manufacturing footprint in France and Italy. Allegro MicroSystems Inc. specializes in sensor-integrated driver solutions for closed-loop positioning systems.
A voice coil motor driver is an electronic power stage that converts control signals into precise current waveforms to energize the copper coil of a voice coil actuator, typically operating at bandwidths exceeding 1 kHz with sub-micrometer positioning resolution for industrial and medical motion systems. Linear motor drivers command the largest application share in robotics and semiconductor wafer handling where direct-drive precision eliminates mechanical backlash. Digital technology adoption is accelerating fastest among new designs as factory automation networks demand real-time position feedback over industrial Ethernet protocols.
FDA device classification rules in the United States and EU MDR conformity requirements in Europe impose electromagnetic compatibility and biocompatibility standards that filter non-compliant driver suppliers from medical equipment supply chains. REACH substance restrictions and RoHS lead-free soldering mandates reshape component material selections across European and Asian manufacturing bases. Stakeholders must monitor how IEC motor efficiency standards and emerging ISO functional-safety certifications recalibrate R&D investment thresholds for next-generation product portfolios.
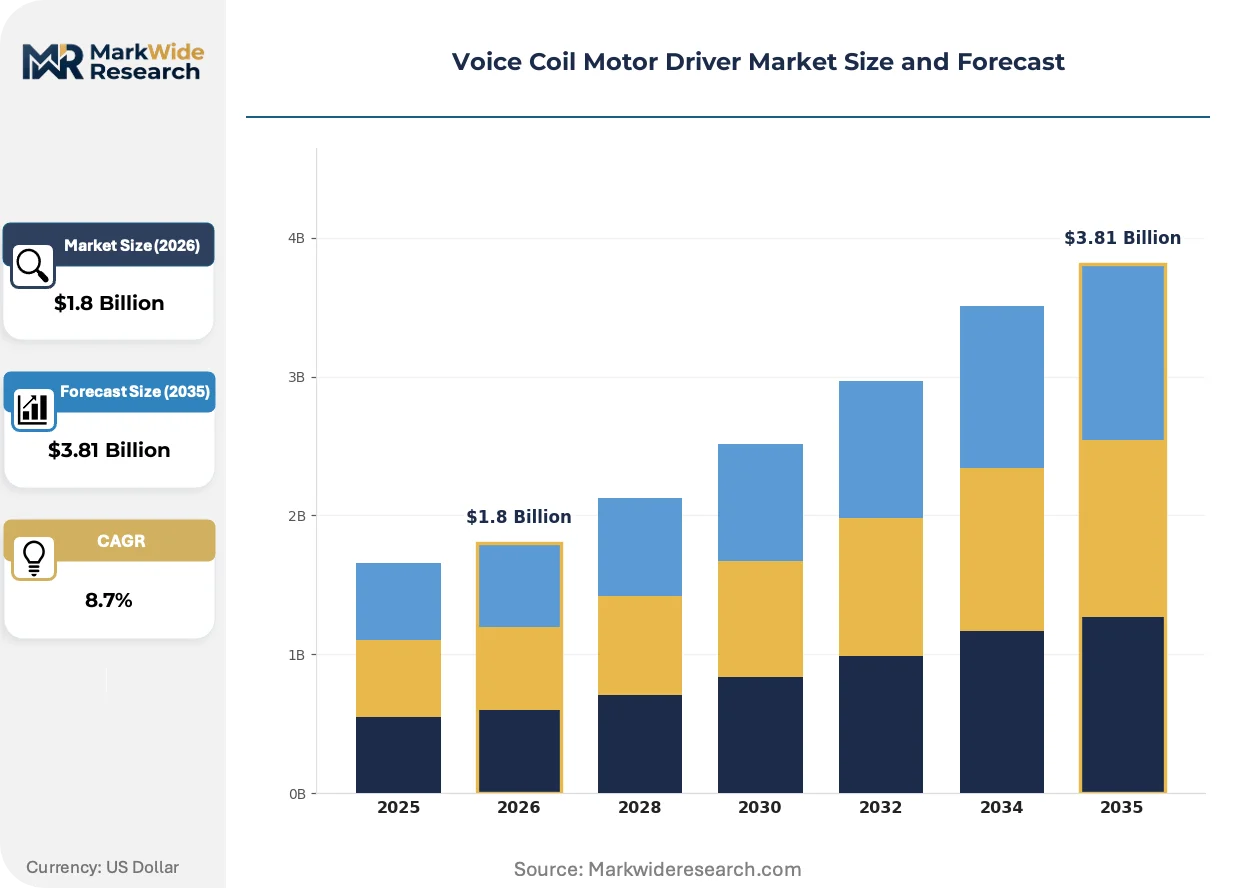
Market Dynamics
Precision motion control requirements in surgical robotics are compressing development cycles for voice coil motor drivers, forcing suppliers to integrate sensor fusion and real-time feedback architectures into compact form factors.
Growth Catalysts
- Surgical Robotics Procurement:Medical device OEMs in Germany and the United States are qualifying voice coil motor drivers for robotic-assisted surgery platforms requiring sub-micrometer positioning accuracy.
- EU F-Gas Regulation:Electromagnetic component manufacturers must reformulate thermal interface materials to comply with phased fluorinated gas restrictions, creating replacement demand for compliant driver assemblies.
- Semiconductor Wafer Handling:Linear motor drivers with direct-drive architectures are eliminating mechanical backlash in vacuum chamber robotics, with Taiwan and South Korea fabs leading adoption.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese export controls destabilize voice coil actuator cost structures for precision driver manufacturers.
- REACH Substance Restrictions:ECHA candidate list expansions for SVHCs complicate solder alloy selections and encapsulant formulations in European production facilities.
- Gallium Nitride Substitution:Wide-bandgap power electronics threaten incumbent silicon-based motor driver architectures in high-frequency applications above 10 kHz bandwidth.
Strategic Opportunities
- India Medical Device PLI:Production-linked incentive schemes for domestic manufacturing of high-value medical electronics attract driver suppliers to establish Bengaluru and Hyderabad assembly operations.
- Digital Twin Convergence:Voice coil motor drivers with embedded edge computing are absorbing predictive maintenance algorithms, enabling real-time coil thermal modeling for semiconductor equipment.
- EU MDR Certification Services:Third-party conformity assessment bodies in Germany and the Netherlands are expanding electromagnetic compatibility testing capacity for surgical motor systems.
Industry Challenges
- Motion Control Firmware Talent:Scarcity of engineers proficient in field-oriented control algorithms and real-time Linux kernels delays product validation timelines for mid-tier driver developers.
- IEC 61508 Functional Safety:SIL-2 and SIL-3 certification requirements for surgical robotics extend validation cycles by 12-18 months, straining R&D budgets before revenue recognition.
- Legacy Analog Integration:Brownfield semiconductor fabs with 1990s-era motion controllers resist Ethernet-based real-time protocols, forcing hybrid driver architectures with dual interface support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Coil Motor Driver Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Motors, Rotary Motors, Micro Motors, Actuators Application: Robotics, Automotive Systems, Audio Equipment, Medical Devices End User: Manufacturing, Healthcare, Consumer Electronics, Aerospace Technology: Electromagnetic, Digital, Analog, Hybrid |
| Companies Covered | ABB Ltd., Analog Devices Inc., Texas Instruments Inc., STMicroelectronics NV, Infineon Technologies AG, NXP Semiconductors NV, Allegro MicroSystems Inc., Renesas Electronics Corp., Microchip Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Coil Motor Driver Market Evolving Landscape
Voice coil motor driver architectures are converging around intelligent power stages with embedded sensing, compressing the traditional separation between motion controller and amplifier electronics.
Silicon carbide MOSFETs are absorbing gate driver losses in high-bandwidth voice coil applications, enabling switching frequencies above 100 kHz with reduced thermal dissipation. Semiconductor wafer handling equipment manufacturers in Japan and Taiwan are qualifying these power stages for vacuum-compatible motor drivers. The technology is absorbing market share from conventional IGBT modules in precision positioning systems where power density constraints dominate.
EU MDR conformity requirements are forcing electromagnetic compatibility redesigns for surgical motor drivers, with notified bodies in Germany and Italy expanding testing capacity for active implantable adjacent devices. The regulation mandates biocompatibility assessments for encapsulant materials in prolonged patient contact scenarios. Driver suppliers with pre-certified component libraries are compressing OEM time-to-market for robotic surgery platforms.
Buyer concentration among medical device OEMs is consolidating vendor qualification lists, with tier-one surgical robotics manufacturers in the United States and Germany demanding captive engineering support and dedicated production lines. Distributors with value-added assembly capabilities are displacing pure component resellers in European supply chains. The shift is most visible in Stuttgart's industrial automation corridor, where integrated motion solution providers are absorbing procurement functions previously managed by purchasing consortia.
Voice Coil Motor Driver Market Segmentation
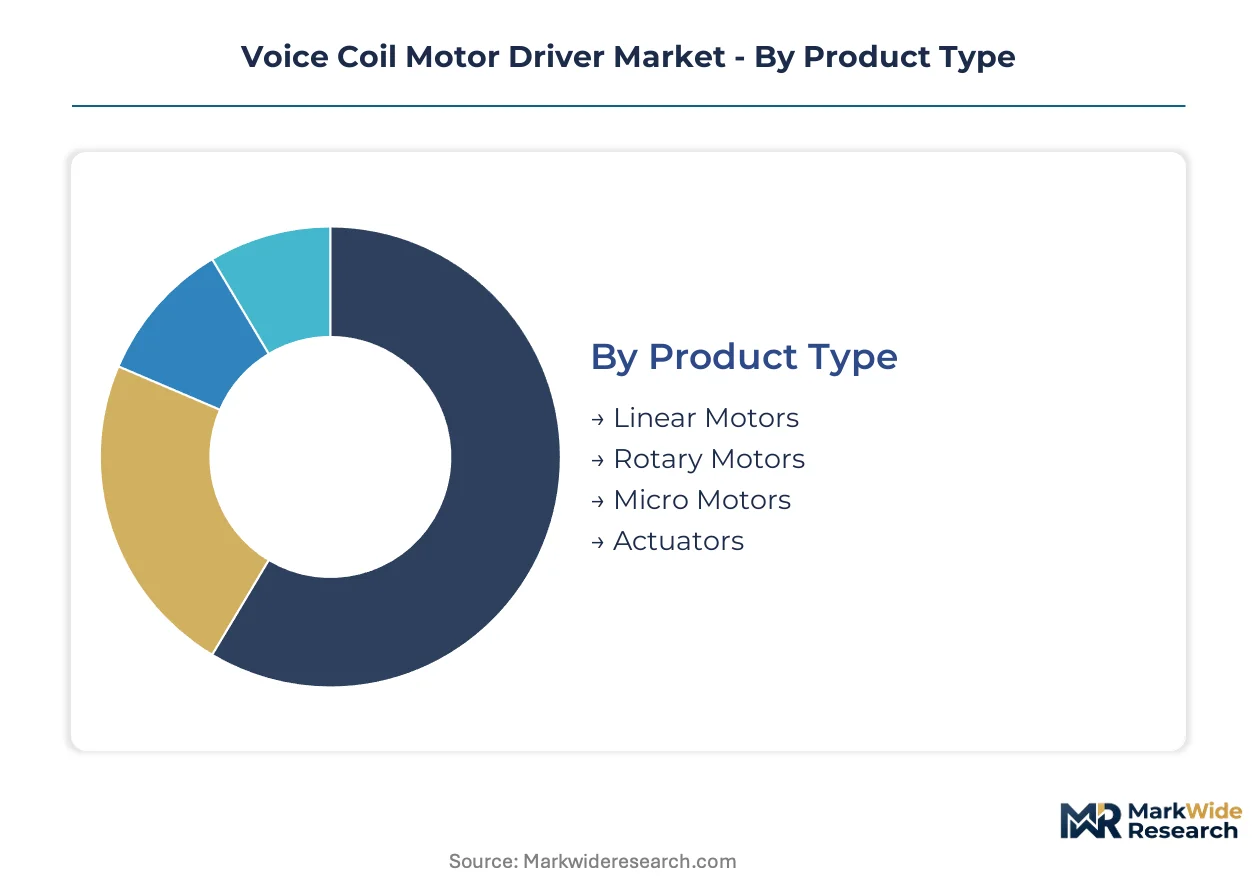
Voice coil motor driver architectures fragment across integration depths, from standalone amplifier modules to fully embedded sensor-fusion systems. Procurement patterns diverge sharply between precision medical applications demanding closed-loop control and cost-sensitive audio equipment favoring open-loop simplicity.
Product Type:
Integration depth spans standalone driver boards for retrofit installations to chip-scale packages embedding controller, amplifier, and diagnostic logic in single silicon.
- Linear Motors:Direct-drive architectures eliminate mechanical transmission elements, achieving sub-micrometer positioning resolution through current-mode control. Semiconductor wafer handling equipment in Taiwan and South Korea fabs absorbs the highest shipment volumes, driven by vacuum-compatible motion requirements.
- Rotary Motors:Limited-angle torque motors enable high-bandwidth gimbal positioning for optical stabilization systems. Automotive camera module manufacturers in Germany and Japan qualify these drivers for advanced driver-assistance systems requiring millisecond response times.
- Micro Motors:Miniaturized voice coil actuators power autofocus mechanisms in smartphone camera modules.
- Actuators:Integrated electromagnetic assemblies combine coil, magnet, and position feedback in sealed packages for surgical robotics.
Volume placements concentrate in Linear Motors; the faster expansion belongs to Actuators.
Application:
Cost tier separation distinguishes premium precision systems from mass-market commodity drivers, with certification requirements widening the price gap.
- Robotics:Multi-axis coordination demands real-time EtherCAT or PROFINET connectivity in driver firmware. Collaborative robot manufacturers in Germany's Stuttgart automation corridor specify SIL-2 functional safety architectures.
- Medical Devices:Surgical robotics platforms require FDA and EU MDR electromagnetic compatibility certification. Robotic-assisted surgery OEMs in the United States and Germany compress supplier qualification timelines through pre-certified component libraries.
- Automotive Systems:Active suspension and steering column modules tolerate wider temperature ranges than industrial counterparts.
- Audio Equipment:Headphone and loudspeaker drivers prioritize cost minimization over positioning precision.
Medical Devices command the steepest expansion trajectory; Automotive Systems anchor current volume.
End User:
Customer type determines procurement modality, from consolidated OEM direct purchasing to fragmented distributor channels serving maintenance-repair-overhaul demand.
- Healthcare:Hospital networks and surgical device manufacturers impose biocompatibility assessments on encapsulant materials. EU MDR notified bodies in Germany and Italy expand testing capacity for active implantable adjacent devices.
- Manufacturing:Industrial automation integrators specify motion control stacks with predictive maintenance algorithms. Semiconductor equipment builders in Japan absorb drivers with embedded edge computing for real-time coil thermal modeling.
- Consumer Electronics:Smartphone and wearable manufacturers drive high-volume, low-margin procurement through Asian contract manufacturers.
- Aerospace:Satellite pointing mechanisms and aircraft actuators demand radiation-hardened or extended-temperature components.
Manufacturing holds current volume leadership; Healthcare is climbing the fastest.
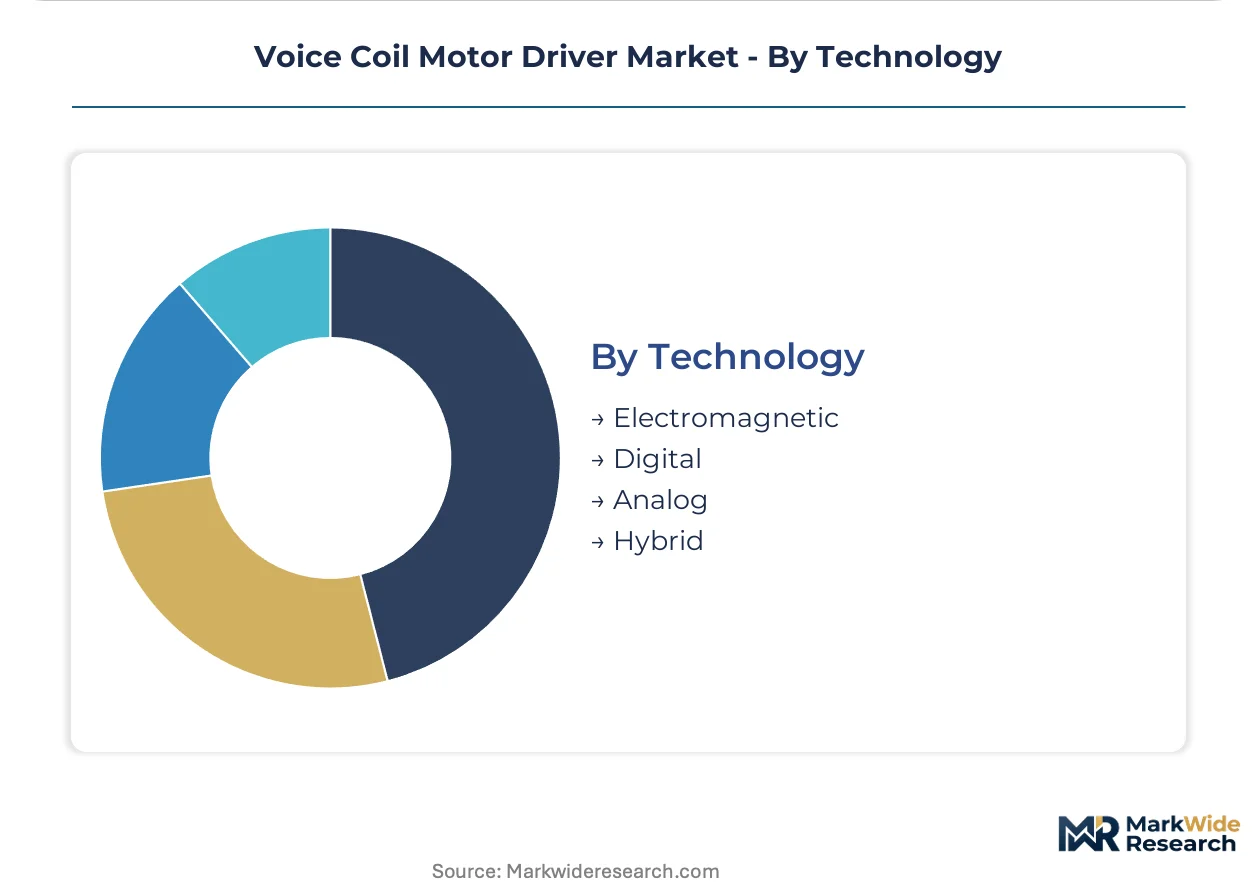
Technology:
Maturity gradients separate legacy analog architectures from digitally-native designs adopting wide-bandgap power stages.
- Digital:Field-programmable gate arrays and ARM-based microcontrollers execute field-oriented control algorithms with cycle times below 50 microseconds. Factory automation networks in Germany demand real-time position feedback over industrial Ethernet protocols.
- Electromagnetic:Core physics of voice coil actuation underlies all driver categories, with copper coil and permanent magnet configurations varying by force constant requirements.
- Analog:Operational amplifier-based current loops persist in cost-constrained audio and basic positioning applications.
- Hybrid:Mixed-signal architectures combine analog power stages with digital supervisory controllers for legacy system compatibility.
Analog retains volume concentration in retrofit installations; Digital is gaining share fastest among new designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China and India's production-linked incentive corridors are concentrating voice coil motor driver assembly capacity alongside precision manufacturing clusters in Germany and the United States.
United States
FDA device classification rules and electromagnetic compatibility mandates filter non-compliant suppliers from medical equipment supply chains. The agency's 510(k) clearance pathways compress development timelines for surgical robotics OEMs. Boston's medical device corridor absorbs precision drivers for robotic-assisted surgery platforms requiring sub-micrometer positioning accuracy.
Germany
EU MDR conformity requirements and REACH substance restrictions reshape component material selections across manufacturing bases. The notified bodies in Munich and Stuttgart expand electromagnetic compatibility testing capacity for active implantable adjacent devices. Baden-Württemberg's automation corridor concentrates procurement for collaborative robot manufacturers demanding SIL-2 functional safety architectures.
China
MIIT industrial standards and dual carbon goals accelerate domestic substitution in precision motor control electronics. The Yangtze River Delta special economic zones absorb high-volume driver production for consumer electronics and semiconductor equipment. Shenzhen's electronics manufacturing clusters integrate voice coil actuators into smartphone camera autofocus mechanisms.
India
CDSCO medical device regulations and PLI schemes for high-value electronics attract driver suppliers to establish domestic assembly. The Bengaluru and Hyderabad technology corridors concentrate production for surgical motor systems and industrial automation. Karnataka's special economic zones offer tax incentives for precision electromagnetic component manufacturing.
Japan
METI industrial technology roadmaps and JIS standards govern precision motion control component specifications. The Chubu region around Nagoya anchors semiconductor wafer handling equipment manufacturing with vacuum-compatible driver requirements. Tokyo's precision engineering clusters absorb silicon carbide MOSFET power stages for high-bandwidth positioning systems.
Voice Coil Motor Driver Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated semiconductor incumbents dominating precision medical applications while fragmented Asian fabricators serve cost-sensitive consumer electronics. The vendor base organizes around three strategic archetypes: analog heritage specialists with integrated manufacturing footprints, fabless designers licensing proprietary control algorithms, and sensor-integrated solution providers. Competitive moves concentrate on strategic partnerships for medical certification pre-qualification and geographic expansion into India's PLI corridors.
Among analog heritage specialists, Texas Instruments Inc. and STMicroelectronics NV exemplify the integrated manufacturing archetype with European and North American production footprints. Allegro MicroSystems Inc. occupies a position within the sensor-integrated tier, representing closed-loop positioning system providers. These three anchors illustrate how competitive positioning diverges between precision medical certification pathways and high-volume consumer electronics cost structures.
| Leading Market Players |
|---|
| ABB Ltd. |
| Analog Devices Inc. |
| Texas Instruments Inc. |
| STMicroelectronics NV |
| Infineon Technologies AG |
| NXP Semiconductors NV |
| Allegro MicroSystems Inc. |
| Renesas Electronics Corp. |
| Microchip Technology Inc. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between EU MDR-compliant surgical motor drivers and unqualified industrial variants manifests in pricing premiums exceeding threefold for pre-certified component libraries, while supply chains for the former concentrate around Germany's notified-body ecosystem and Stuttgart automation corridor versus dispersed Asian fabrication for commodity audio drivers.
Pricing Analysis
Lead-time-driven pricing stratification rewards medical device OEMs willing to accept 12-18 month SIL-2 validation cycles with locked contract rates, while spot-market procurement for consumer electronics drivers faces compression from gallium nitride substitution threats. Price differentiation hinges on FDA 510(k) pre-certification status and REACH SVHC-compliant material traceability. Cost compression in standard-grade linear motor drivers intensifies as Taiwanese fabs absorb volume production. Healthcare procurement committees exhibit lowest price sensitivity given patient-safety liability exposure, whereas smartphone contract manufacturers operate on single-digit margin tolerance.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one surgical robotics demand through captive engineering support agreements, while distributor networks with value-added assembly capabilities serve mid-tier industrial automation integrators. Manufacturing concentrates in Germany's Baden-Württemberg corridor, Taiwan's semiconductor equipment cluster, and China's Yangtze River Delta special economic zones. Neodymium and dysprosium magnet supply rests on Chinese export control volatility. Single-source vulnerability in rare earth processing creates exposure to geopolitical disruption. Distribution runs through consolidated medical device OEM procurement offices and fragmented Asian electronics manufacturing service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voice coil motor driver supply is tightening around qualified silicon carbide MOSFET capacity and IEC 61508 SIL-certified firmware engineering talent, propping pricing power for incumbents with pre-validated architectures.
For Market Incumbents: Deploy backward integration into wide-bandgap semiconductor sourcing to secure silicon carbide MOSFET allocation before gallium nitride substitution accelerates. Capture channel control through dedicated production line commitments to tier-one surgical robotics OEMs in Boston and Stuttgart. Consolidate position by acquiring sensor-fusion firmware specialists facing talent scarcity in field-oriented control algorithms. For New Entrants and Emerging Players: Distributor partnerships with EU MDR notified-body consulting services offer the most penetrable entry vector for pre-certification component libraries targeting mid-tier surgical motor system builders. White-space concentration sits with India's PLI-corridor assembly operations for domestic medical device manufacturing. Target Bengaluru and Hyderabad technology corridors with CDSCO-compliant driver platforms. For Investors and Strategic Acquirers: Re-rating potential sits with sensor-integrated solution providers given EU MDR conformity requirement acceleration and buyer consolidation around pre-certified vendor lists. Long-term viability favors archetypes with captive firmware IP and established notified-body relationships. Watch for inflection in gallium nitride power stage adoption rates above 10 kHz bandwidth applications.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Pre-Certification Investment | Compresses OEM time-to-market for robotic surgery platforms requiring biocompatible encapsulant assessments. |
| Silicon Carbide Power Stage Qualification | Enables switching frequencies above 100 kHz for vacuum-compatible semiconductor wafer handling equipment. |
| India PLI Corridor Manufacturing Setup | Captures production-linked incentives for domestic surgical motor system assembly in Karnataka special economic zones. |
| Sensor-Fusion Firmware Acquisition | Addresses scarcity of engineers proficient in real-time Linux kernels and field-oriented control algorithms. |
| REACH-Compliant Material Reformulation | Ensures thermal interface material continuity under phased EU F-Gas Regulation fluorinated gas restrictions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with surgical robotics OEM procurement directors, biomedical engineers, semiconductor equipment plant managers, and EU MDR notified-body technical assessors. FDA 510(k) clearance databases, ECHA SVHC candidate list updates, MIIT industrial standards publications, and German automation corridor trade statistics provided validation anchors. Bottom-up shipment estimates from driver module manufacturers reconciled with top-down medical device capital expenditure surveys.
Data-stream reconciliation across product type, application tier, technology maturity, and end-user procurement modality generated volume and value outputs over the projection horizon. Segmentation modeling incorporated integration depth, certification grade, and regional regulatory cluster dimensions. CAGRs derived from weighted average of historical shipment momentum and forward-looking OEM qualification pipeline visibility. Forecast inputs included surgical robotics platform deployment schedules and semiconductor fab capital expenditure cycles.
Several conditions sit outside the modeled scope, including unannounced gallium nitride power electronics breakthroughs, abrupt Chinese rare earth export restrictions, and EU MDR notified-body capacity bottlenecks. Forecasts reflect assumptions regarding SIL certification timeline stability and REACH substance list expansion cadence. Periodic stress-testing of base assumptions is recommended against IEC standard revision announcements and medical device OEM consolidation activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Logging Device Market
Automotive Electronics & Wiring
Construction Machinery Wiring Harness Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Automotive Micro Switch Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Mexico Automotive Camera Market