
 Automotive Halogen Lights Market | 2026-2036
Automotive Halogen Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Halogen Lights Market Outlook
EU REACH compliance is broadening the cost-of-entry calculus for halogen lamp suppliers serving European automotive OEMs. Koito Manufacturing Co., Ltd. leverages its integrated filament production to sustain cost leadership in headlamp assemblies. HELLA GmbH & Co. KGaA anchors its competitive position through specialized fog light modules for commercial vehicle platforms. Valeo SA competes by controlling distribution channels across European aftermarket retailers.
Automotive halogen lights are tungsten-filament lamps filled with halogen gas that regenerates evaporated tungsten onto the filament, extending operational life to approximately 1,000 hours while producing 16-22 lumens per watt for vehicle illumination. Their primary commercial purpose remains cost-effective forward and signal lighting for internal combustion engine vehicles where LED retrofit economics remain unfavorable. Headlight applications occupy the largest volume share as replacement cycles align with vehicle aging patterns across developing markets. Aftermarket retailers represent the fastest-growing end user channel as independent service networks expand in regions with high vehicle parc density. Indicator light segments lead margin pools due to specialized amber filtration requirements and lower price elasticity.
The US NHTSA Federal Motor Vehicle Safety Standard 108 governs headlamp photometric performance and replacement equivalence, while India's BIS mandates luminous flux and color temperature thresholds for type-approved automotive lamps. EPA hazardous substance rules in the US and EU RoHS restrictions on mercury content shape material selection and recycling obligations for halogen bulb manufacturers. Stakeholders must monitor regulatory divergence between LED mandate timelines and halogen phase-out schedules to calibrate production capacity and aftermarket inventory commitments.
Market Dynamics
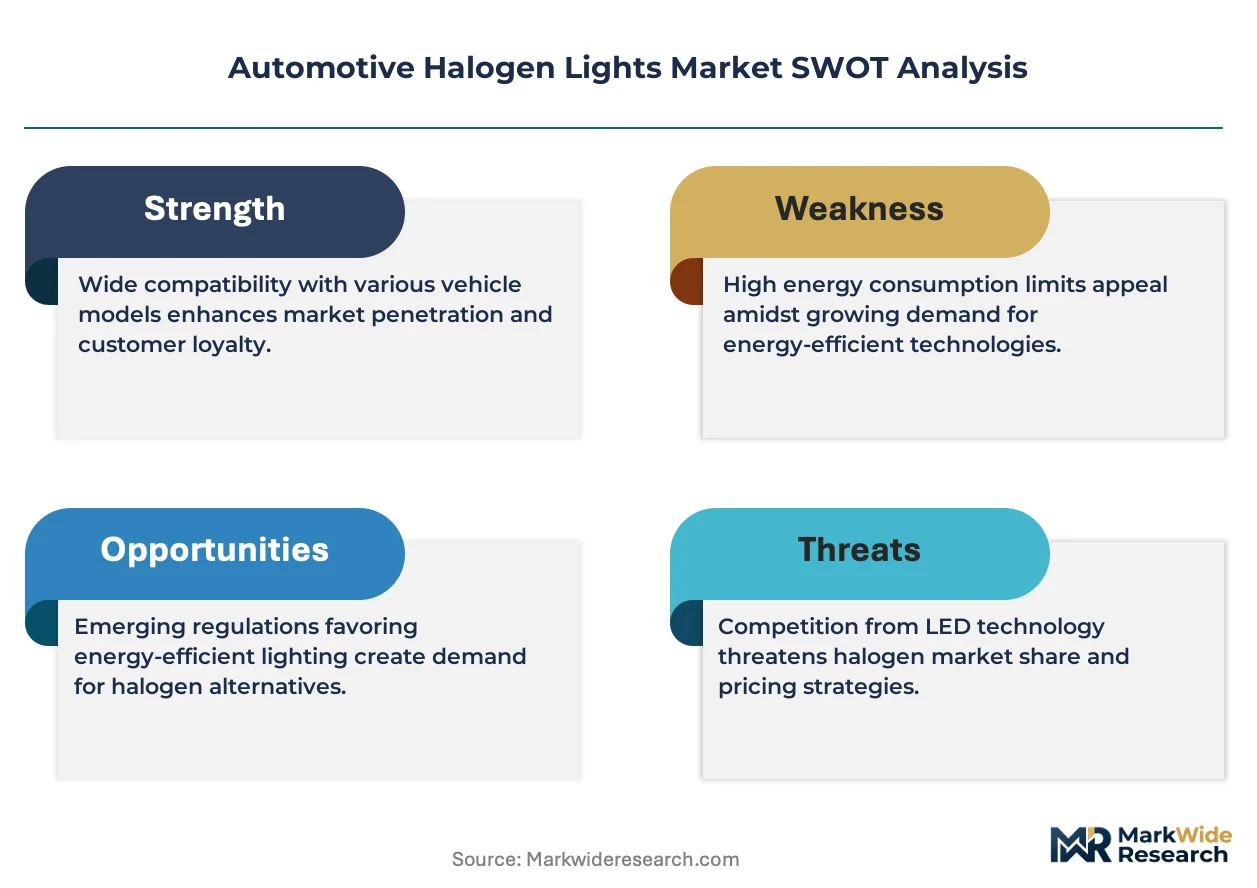
The automotive halogen lights market faces structural compression from LED cost curves falling below replacement-equivalence thresholds in developed economies, while developing markets sustain demand through vehicle parc aging and aftermarket service network expansion.
Growth Catalysts
- Vehicle Parc Aging:Southeast Asian commercial fleets and passenger vehicle pools are extending replacement cycles, driving consistent aftermarket bulb demand through independent service networks.
- BIS Certification Tightening:India's Bureau of Indian Standards is elevating luminous flux and color temperature requirements, filtering substandard imports and consolidating compliant supplier positions.
- Commercial Vehicle Fog Light Demand:Heavy-duty truck platforms in Indonesia and Vietnam require specialized halogen fog modules where LED retrofit economics remain unfavorable for fleet operators.
Market Restraints
- Tungsten Filament Input Volatility:Raw material price swings for tungsten concentrates from Chinese mining operations compress margin stability for filament manufacturers.
- EU REACH Compliance Burden:European Chemicals Agency registration requirements for halogen lamp components broaden administrative overhead for suppliers serving automotive OEMs.
- LED Substitution Acceleration:Solid-state lighting platforms are capturing new vehicle platform designs, constraining halogen's addressable market to replacement and legacy fleet segments.
Strategic Opportunities
- Indonesian Domestic Fleet Maintenance:Archipelago geography and dispersed service infrastructure favor halogen bulb stocking by regional distributors over integrated LED system repairs.
- EU RoHS Material Exemption Windows:Temporary regulatory allowances for specific halogen applications in commercial vehicles create supply continuity opportunities for compliant manufacturers.
- Aftermarket Channel Digitization:E-commerce platforms serving independent garages in India and Southeast Asia are expanding SKU breadth for certified replacement bulbs.
Industry Challenges
- Filament Engineering Talent Scarcity:Specialized glass-to-metal sealing and coil-winding expertise is concentrating among aging workforces in Japan and Germany.
- Dual Certification Timeline Compression:Simultaneous BIS and NHTSA approval processes for export-oriented Indian manufacturers extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Halogen Lights Market |
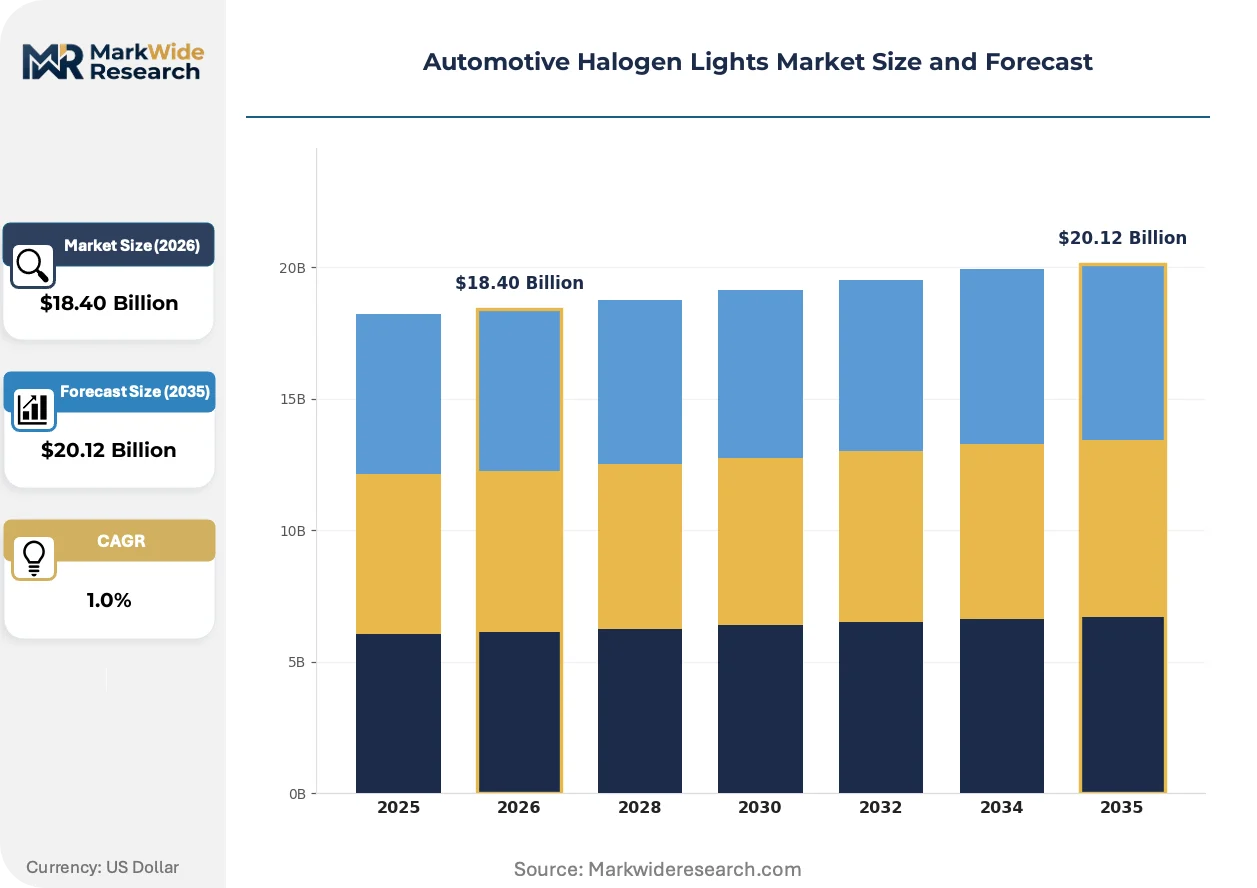
| Market Size in 2026 | $18.40 Billion |
| Market Size in 2035 | $20.12 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlight, Fog Light, Taillight, Indicator Light Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, SUVs Technology: Conventional, Xenon, LED, Others End User: OEMs, Aftermarket Retailers, Service Centers, Automotive Manufacturers |
| Companies Covered | ams OSRAM AG, Koito Manufacturing Co., Ltd., HELLA GmbH & Co. KGaA, Valeo SA, Stanley Electric Co., Ltd., Koninklijke Philips N.V., Robert Bosch GmbH, Magneti Marelli, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Halogen Lights Market Strategic Shifts
Halogen lamp engineering is pivoting toward precision filament architectures and gas-fill optimization to defend performance parity against LED encroachment in cost-sensitive vehicle segments.
Long-life halogen designs with enhanced regenerative cycles are rewriting durability expectations for commercial vehicle operators. Fleet managers in Indonesia and India are specifying 2,000-hour rated bulbs for heavy-duty applications. This technology is compressing replacement frequency and reshaping distributor inventory turnover models.
EU REACH substance restrictions are tightening material disclosure requirements for halogen lamp coatings and base materials. Automotive OEMs serving European markets are demanding full supply chain transparency for tungsten sourcing and glass composition. Aftermarket suppliers are responding by consolidating certified material streams and abandoning non-compliant product lines.
Independent garage networks across Southeast Asia are consolidating procurement through digital platforms that aggregate demand for certified replacement bulbs. Traditional distributor hierarchies are flattening as regional service chains negotiate direct supply relationships with BIS-approved manufacturers. This channel restructuring is most visible in India's tier-2 and tier-3 cities where vehicle density is rising fastest.
Automotive Halogen Lights Market Segmentation
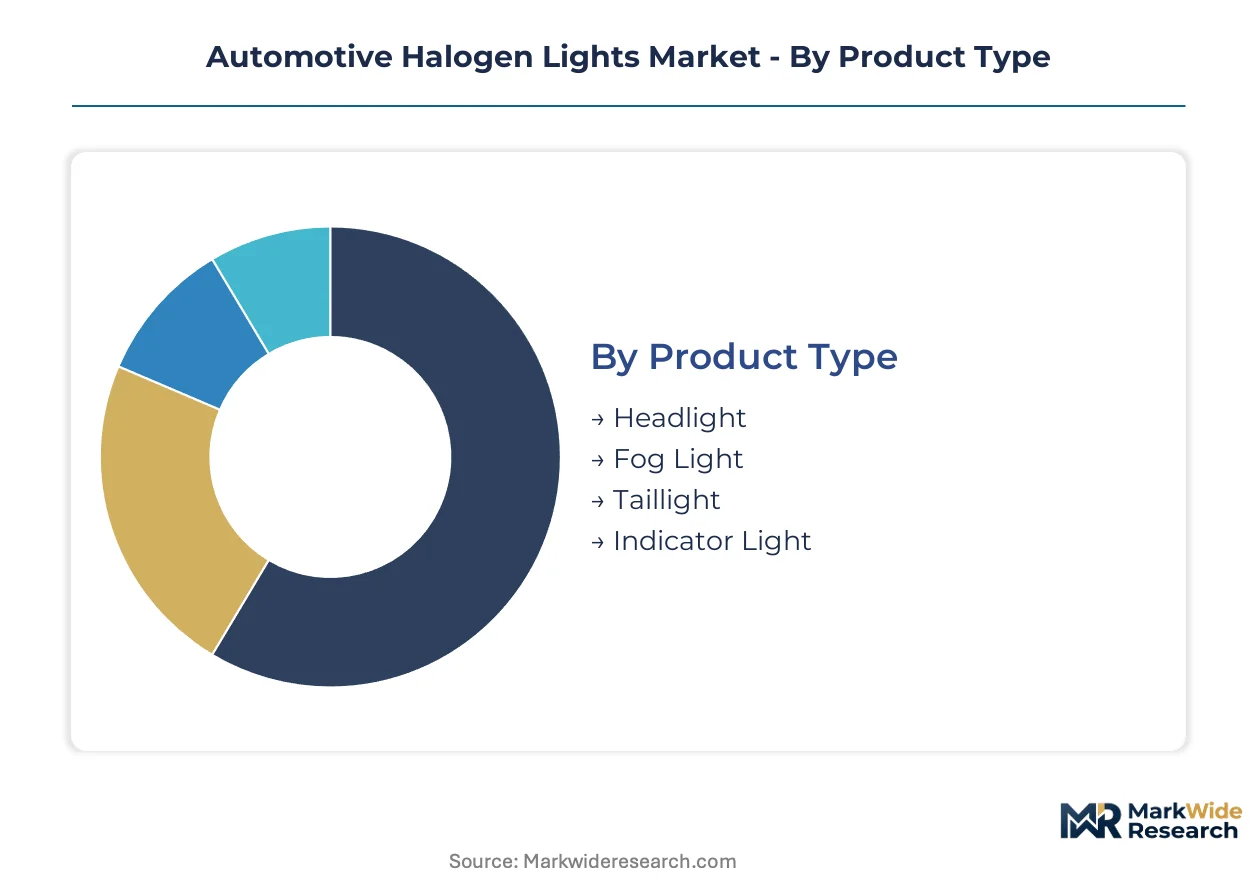
Segmentation in automotive halogen lights reveals distinct replacement-cycle economics across vehicle types and procurement channels. Upgrade timing varies dramatically between commercial fleet operators and individual owners, shaping inventory strategies for bulb manufacturers and distributors.
Product Type:
Replacement-cycle intensity differs sharply across lamp positions, with forward illumination demanding more frequent service than signal functions.
- Headlight:Dual-filament H4 and H7 configurations dominate forward lighting specifications, with tungsten regenerative cycles optimized for 1,000-hour operational life. Demand concentrates in Indonesia's aging passenger vehicle fleet where LED retrofit costs exceed vehicle residual values.
- Fog Light:Specialized H11 and H8 modules feature amber-selective coatings for low-visibility penetration in tropical climates. Heavy-duty truck operators across Vietnam specify these for monsoon-season fleet readiness, sustaining volume despite LED pressure in premium segments.
- Taillight:P21/5W dual-intensity bulbs serve brake and position functions through standardized bayonet bases.
- Indicator Light:PY21W amber filtration requires specialized glass doping for color compliance.
Headlight sits at the top of the volume ranking, with Fog Light climbing the fastest.
Application:
Cost-tier differentiation separates fleet procurement from retail replacement, with commercial operators prioritizing bulk pricing over premium specifications.
- Passenger Vehicles:Sedan and hatchback parc aging across India's tier-2 cities sustains consistent demand for H4 headlamp replacements. Independent service networks stock standardized wattages to capture walk-in maintenance traffic.
- Commercial Vehicles:Heavy-duty platforms in Indonesia's archipelago logistics sector require vibration-resistant filament mountings. Fleet managers negotiate annual supply contracts with BIS-certified manufacturers, bypassing distributor markups.
- Two-Wheelers:Motorcycle headlamp specifications favor HS1 and H4 variants with compact reflector integration.
- SUVs:Higher mounting positions extend bulb thermal stress cycles.
Commercial Vehicles command the largest procurement volumes, while Two-Wheelers show steepest expansion trajectory in replacement frequency.
Technology:
Application-specific performance requirements drive technology selection, with halogen defending position where luminous efficacy thresholds remain modest.
- Conventional:Standard tungsten-halogen regeneration cycles deliver 16-22 lumens per watt at manufacturing cost points below solid-state alternatives. India's BIS certification tightening filters substandard imports, consolidating compliant supplier positions in domestic aftermarket channels.
- Xenon:Gas-discharge alternatives with electronic ballast requirements capture premium retrofit segments.
- LED:Solid-state platforms displace halogen in new vehicle platforms across developed economies.
- Others:Emerging laser-excited phosphor systems occupy concept-stage applications.
Conventional technology retains dominant share in replacement markets, with LED gaining share fastest in OEM forward lighting specifications.
End User:
Channel digitization is flattening traditional distribution hierarchies, with procurement authority shifting toward consolidated service networks.
- OEMs:Vehicle assemblers in Thailand and Indonesia specify halogen modules for entry-grade platforms where LED economics remain unfavorable. Koito Manufacturing and HELLA anchor supply relationships through integrated filament production and specialized fog light engineering.
- Aftermarket Retailers:E-commerce platforms serving India's independent garages aggregate demand for certified replacement bulbs. Regional distributors in Southeast Asia expand SKU breadth to capture service network consolidation.
- Service Centers:Franchise maintenance chains negotiate direct supply relationships with BIS-approved manufacturers.
- Automotive Manufacturers:Component system integrators specify bulb specifications for headlamp assemblies.
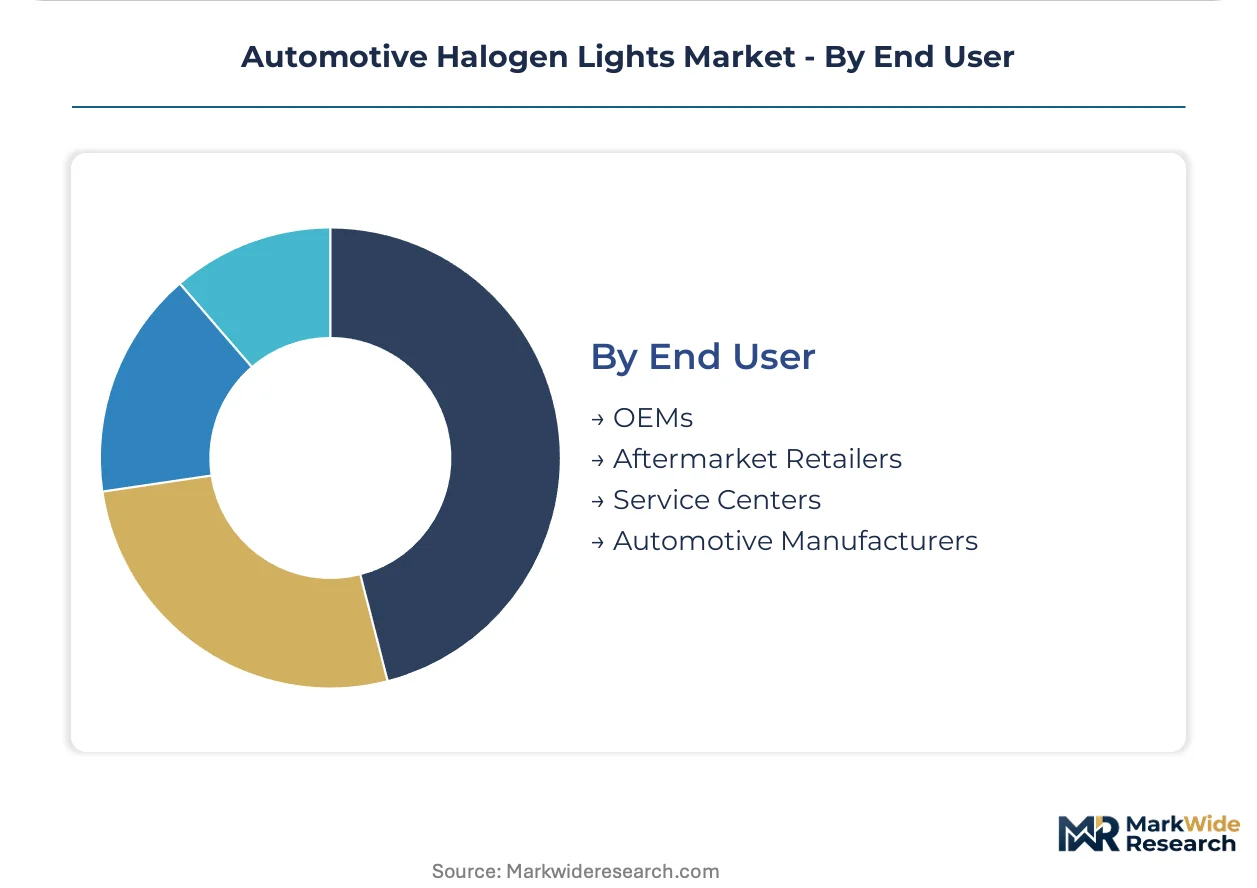
Aftermarket Retailers represent the fastest-growing channel, with OEMs retaining highest absolute volume through platform lifecycle commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive halogen lighting technology achieved commercial scale through German engineering refinements in the 1960s, establishing tungsten-halogen regeneration as the dominant forward illumination standard for internal combustion vehicles. Production expertise subsequently dispersed to Japan and emerging Asian manufacturing centers.
Indonesia
Archipelago logistics operators sustain demand for heavy-duty truck fog modules as dispersed service infrastructure favors replaceable bulb stocking over integrated LED repairs. BIS certification alignment for export-oriented suppliers tightens import quality filters. Jakarta and Surabaya anchor distributor networks serving domestic fleet maintenance channels.
India
Tier-2 and tier-3 city vehicle density drives replacement frequency for H4 headlamp specifications in aging passenger fleets. BIS luminous flux and color temperature mandates elevate compliance costs for substandard imports. Pune and Chennai manufacturing clusters consolidate certified supplier positions for aftermarket digitization.
Germany
EU REACH substance disclosure requirements burden halogen lamp coating and base material sourcing for automotive OEM suppliers. KBA type-approval processes govern photometric performance equivalence for replacement markets. Bavaria and Baden-Württemberg retain specialized glass-to-metal sealing expertise concentrated among aging technical workforces.
United States
NHTSA Federal Motor Vehicle Safety Standard 108 enforcement maintains replacement-equivalence thresholds constraining non-compliant bulb imports. EPA hazardous substance rules shape tungsten sourcing disclosure and end-of-life recycling obligations. Michigan and Ohio automotive corridors sustain demand for legacy fleet maintenance in commercial vehicle segments.
Japan
Integrated filament production capabilities defend cost positions in headlamp assembly supply relationships. METI industrial standards coordinate with international type-approval frameworks for export-oriented manufacturers. Aichi Prefecture and Kanto manufacturing belts concentrate specialized coil-winding and gas-fill optimization expertise.
Automotive Halogen Lights Market Competitive Environment
The competitive structure tilts toward integrated lighting system specialists with captive filament production capabilities. Supplier concentration remains moderate, with tier-one automotive component groups and specialized lamp manufacturers dividing OEM and aftermarket channels. Two strategic archetypes dominate: vertically integrated Japanese and German specialists controlling upstream tungsten processing, and diversified European component groups leveraging distribution scale. Competitive moves center on BIS certification pre-positioning for Indian market access and direct supply relationship cultivation with Indonesian fleet operators.
Among integrated specialists, Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. exemplify the captive filament production archetype, while HELLA GmbH & Co. KGaA occupies a position within the European diversified component tier. Valeo SA represents distribution channel control strategies across aftermarket retail networks. These three anchors illustrate divergent defensive positioning against LED substitution pressure.
| Leading Market Players |
|---|
| ams OSRAM AG |
| Koito Manufacturing Co., Ltd. |
| HELLA GmbH & Co. KGaA |
| Valeo SA |
| Stanley Electric Co., Ltd. |
| Koninklijke Philips N.V. |
| Robert Bosch GmbH |
| Magneti Marelli |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Specialized glass-to-metal sealing expertise concentrated in Bavaria and Aichi Prefecture creates labor-cost differentials that widen pricing spreads between premium OEM-grade and economy aftermarket halogen bulbs. Tungsten filament coil-winding technical wages in Japan run substantially above Southeast Asian assembly rates, compressing margin structures for suppliers without captive upstream production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified OEM supply from uncertified gray-market imports. Price differentiation rests on luminous flux compliance grade and volume procurement scale. Cost compression in economy tiers is intensifying because Indian distributors aggregate demand through digital platforms. Fleet operators in Indonesia exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while independent garages in tier-3 Indian cities remain most price-sensitive.
Supply Chain Analysis
Regional distribution centers in Jakarta and Surabaya anchor hub-and-spoke patterns serving Indonesia's archipelago logistics sector. Manufacturing concentrates in Japan, Germany, and India, with tungsten concentrate sourcing drawing from Chinese mining operations. Supply chain risk centers on single-source dependency for specialized glass doping materials. Distribution runs through certified importer-distributor hierarchies in India and direct fleet supply contracts in Southeast Asian commercial vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification tightening functions as a regulatory compounder, elevating compliance costs that filter substandard competitors and consolidate positions among pre-certified suppliers.
For Market Incumbents: Extend filament engineering talent retention programs in Japan and Germany to defend proprietary coil-winding capabilities against LED substitution pressure. Deepen backward integration into tungsten concentrate sourcing to buffer margin volatility from Chinese mining price swings. Prioritize BIS certification maintenance as a barrier against emerging Indian domestic competitors. For New Entrants and Emerging Players: Independent garage networks in India's tier-2 cities represent an underserved buyer archetype with fragmented procurement and limited BIS-certified supplier access. White-space targets include direct e-commerce supply relationships bypassing traditional distributor markups, and specialized fog light modules for Vietnamese heavy-duty truck fleets. A certification-first go-to-market angle unlocks aftermarket digitization platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Indian manufacturers with BIS approval but limited export relationships. Long-term viability framing treats halogen as a cash-cow replacement market with declining OEM exposure but stable aftermarket demand through vehicle parc aging. Watch LED cost curve trajectories in Indonesia as the inflection signal for replacement-market substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Pre-Positioning | India's tightening standards filter substandard imports and consolidate compliant supplier market positions. |
| Filament Engineering Talent Retention | Specialized glass-to-metal sealing expertise concentration in Japan and Germany defends proprietary production capabilities. |
| Direct Fleet Supply Relationships | Indonesian commercial vehicle operators negotiate annual contracts bypassing distributor markups for heavy-duty fog modules. |
| Aftermarket Channel Digitization | E-commerce platforms serving independent garages in India aggregate demand and flatten traditional distribution hierarchies. |
| Tungsten Concentrate Backward Integration | Captive sourcing from Chinese mining operations buffers margin volatility for integrated Japanese and German specialists. |
Study Parameters
Bottom-up aftermarket channel modeling reconciled against top-down OEM supply tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads combined with secondary validation from vehicle production databases, IHS Markit registration data, BIS certification records, and customs trade filings. Triangulation across these sources ensures segment-level precision.
Historical trendline analysis of replacement cycle frequency and vehicle parc aging patterns informed projection frameworks across the modeling period. Segmentation dimensions include lamp position, vehicle class, procurement channel, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for LED substitution elasticity and certification timeline compression. Industry-specific forecast inputs incorporate BIS approval velocity and tungsten concentrate price volatility assumptions.
Underlying measurement precision varies by segment; headlight and fog light replacement volumes carry tighter precision than indicator light margin estimates due to data availability. Forecasts reflect documented assumptions around regulatory divergence and technology substitution curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Automotive Fuse Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Global Vehicle Camera Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
India ECU Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
Latin America Automotive Camera Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
Drive by Wire Market