
 North America Automotive Display Market | 2026-2036
North America Automotive Display Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Display Market Analytics
Mexican display module assembly capacity is recalibrating as automakers regionalize cockpit electronics production. Continental AG leverages its Guadalajara operations to anchor North American supply for instrument cluster modules. Visteon Corporation competes through specialized software-defined display platforms that integrate advanced driver-assistance system alerts. Robert Bosch GmbH sustains engineering presence in Detroit to navigate OEM validation cycles for head-up display calibration.
North America automotive display encompasses in-vehicle visual interface systems ranging from thin-film transistor liquid-crystal displays measuring 10 to 17 inches diagonally to micro-projected augmented-reality head-up displays with 10,000 candela per square meter luminance, manufactured through photolithographic patterning on glass substrates bonded to capacitive touch sensor layers. These systems render vehicle telemetry, navigation, and entertainment content to drivers and passengers. Center console displays occupy the dominant revenue position as OEMs standardize portrait-oriented touchscreens across mid-range passenger vehicle trims. OLED technology leads growth trajectory due to self-emissive pixel architecture enabling curved form factors and superior contrast ratios for luxury vehicle cabins.
NHTSA enforces Federal Motor Vehicle Safety Standard 101 governing driver information readability and distraction mitigation, while EPA fuel economy testing protocols indirectly incentivize lightweight display module designs. Transport Canada mandates bilingual labeling on all displays sold in Canadian vehicle configurations, creating incremental software localization requirements. Stakeholders must monitor pending NHTSA rulemaking on automated driving system human-machine interface standards to anticipate next-generation display architecture investments.
Market Dynamics
The central structural force reshaping the North America automotive display market is the collision between NHTSA's tightening distracted-driving enforcement and OEMs' competitive push for larger, more immersive cockpit screens. This tension is forcing suppliers to engineer novel optical solutions that maintain visual clarity while satisfying federal safety constraints.
Growth Catalysts
- FMVSS 101 Compliance Engineering:NHTSA's updated readability standards are compelling Tier-1 suppliers to invest in advanced anti-glare coatings and adaptive brightness algorithms, creating premium technology tiers.
- Electric Vehicle Cabin Differentiation:Battery-electric platforms from Detroit engineering centers are standardizing 15-inch portrait displays as trim-level differentiators, pulling demand for curved OLED substrates.
- Michigan Corridor Cluster Density:The Detroit-to-Ann Arbor engineering concentration enables same-day prototype iteration cycles between OEM validation labs and display integrators.
Market Restraints
- Indium Tin Oxide Supply Concentration:Transparent conductor layer sourcing depends heavily on Asian smelter capacity, exposing module assemblers to price volatility and logistics bottlenecks.
- NHTSA Placement Geometry Constraints:Federal Motor Vehicle Safety Standard 101's sight-line restrictions limit maximum display angles and positions, constraining industrial design freedom for curved form factors.
- Automotive-Grade OLED Burn-In Risk:Static navigation elements and instrument cluster gauges accelerate pixel degradation in self-emissive panels, raising warranty reserve requirements.
Strategic Opportunities
- Software-Defined Display Platforms:Over-the-air updateable instrument clusters enable subscription revenue models and post-sale feature activation for Mexican assembly plants serving US cross-border logistics.
- Transport Canada Bilingual Mandate:Mandatory French-English interface localization creates specialized software service contracts for tier suppliers serving the Ontario-Quebec vehicle configuration market.
- Augmented Reality HUD Convergence:The fusion of waveguide optics with ADAS sensor fusion algorithms opens new content monetization channels for navigation and hazard alerting.
Industry Challenges
- Photolithography Cleanroom Capex Burden:Gen 6 glass substrate processing requires billion-dollar fab investments that strain mid-tier supplier balance sheets.
- Automotive AEC-Q100 Qualification Timelines:The 12-18 month validation cycle for display driver ICs delays platform launches and traps engineering resources.
- Legacy CAN Bus Integration Complexity:New display architectures must bridge to 20-year-old vehicle network protocols, multiplying software validation test matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Display Market |
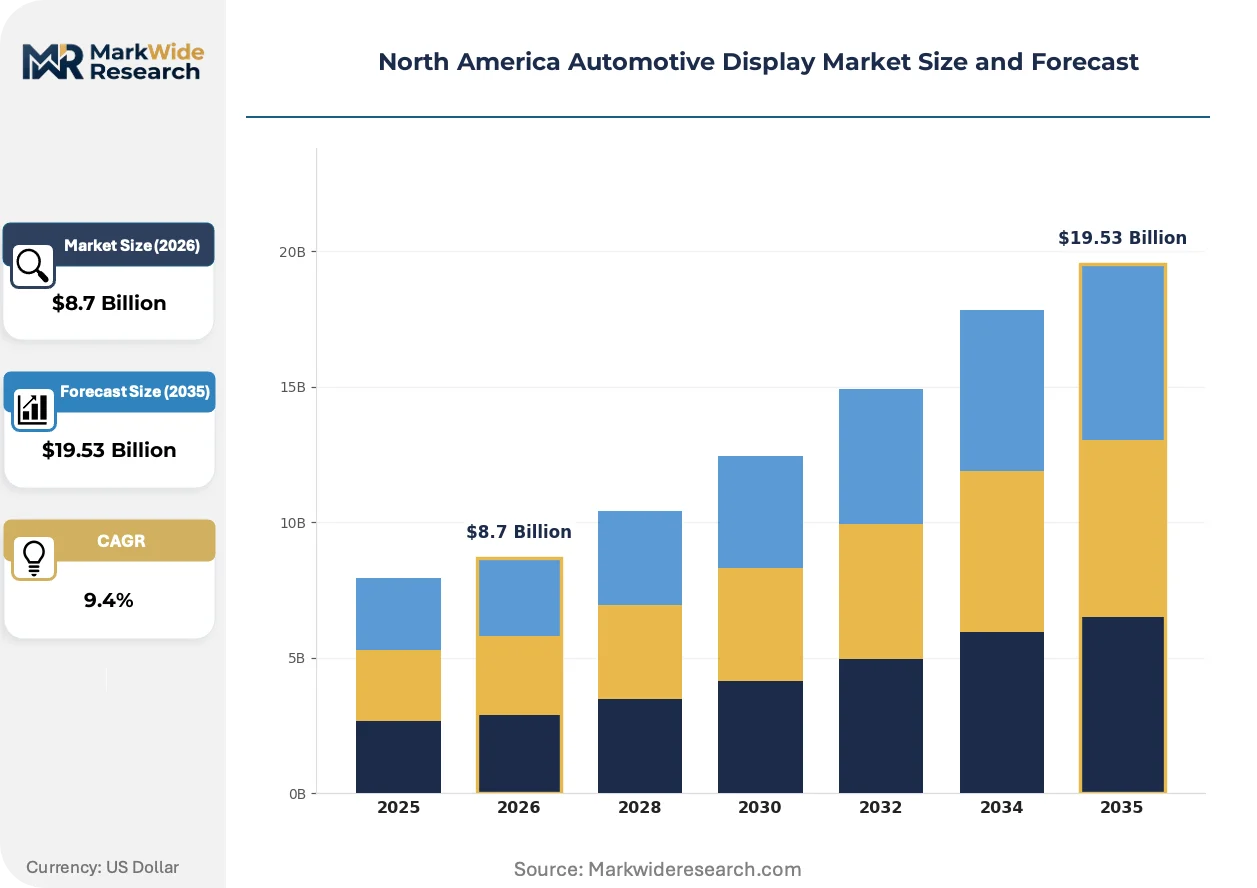
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Up Displays, Center Consoles, Instrument Clusters, Rear-Seat Entertainment Technology: LCD, OLED, LED, Projection End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Electric Vehicles |
| Companies Covered | Continental AG, LG Display, Visteon Corporation, Denso Corporation, Robert Bosch GmbH, HARMAN International, Panasonic Corporation, Nippon Seiki, Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Display Market Evolving Landscape
Display technology evolution in North American vehicles is accelerating toward immersive, software-centric cockpit experiences that redefine human-machine interaction paradigms. Three convergent developments are restructuring supplier competitive positions.
OLED display technology is overtaking traditional thin-film transistor liquid-crystal alternatives in premium vehicle segments. Self-emissive pixel architecture eliminates backlight assemblies, enabling sub-5mm panel thickness and true black states for night driving. Luxury OEMs in California design studios are specifying curved OLED arrays spanning pillar-to-pillar, compressing the addressable market for conventional edge-lit LCD modules.
NHTSA's pending rulemaking on automated driving system human-machine interface standards is forcing architectural pre-investment. The regulator's draft guidelines for conditional automation handover protocols mandate redundant visual alerting pathways, compelling dual-display redundancy in Level 2+ vehicle platforms. Tier-1 engineering centers in suburban Detroit are staffing specialized HMI validation teams to navigate anticipated 2025-2026 compliance deadlines.
Buyer specifications for display content unbundling are fragmenting traditional all-in-one module procurement. Fleet operators and premium retail buyers now source bare display panels separately from software layers and touch sensor integration, compressing margins for vertically integrated suppliers. This disintermediation is most visible in Michigan's Tier-1 supplier ecosystem, where engineering services contracts are displacing hardware-only purchase orders.
North America Automotive Display Market Segmentation
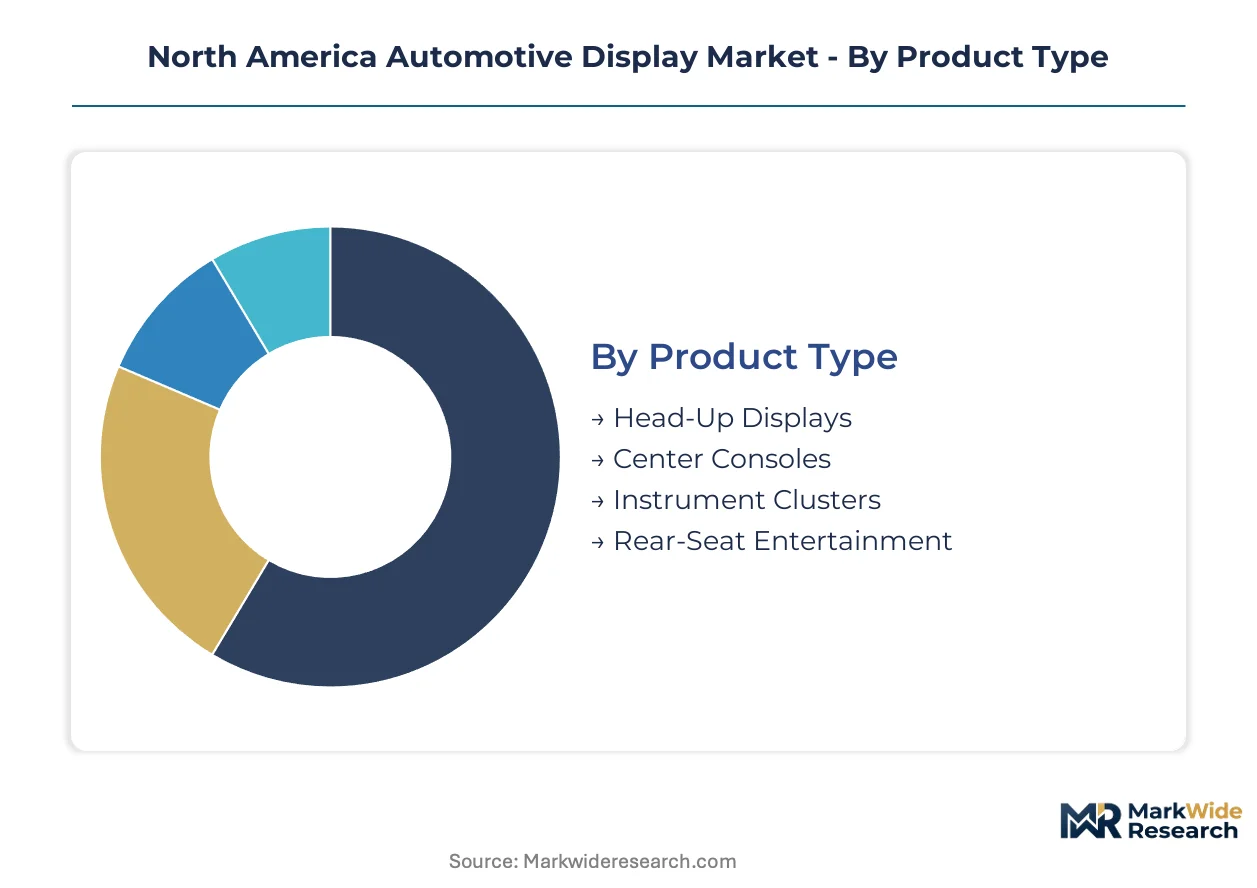
Segmentation in the North America automotive display market reveals how regulatory pressure and electrification reshape procurement patterns across distinct technology tiers. Suppliers calibrate their portfolio mix against divergent margin profiles between mass-market LCD volumes and premium OLED niches.
Product Type:
Volume concentration clusters in standardized center console formats, while premium differentiation migrates toward augmented-reality projection systems commanding higher engineering fees.
- Center Consoles:Portrait-oriented touchscreens measuring 10 to 17 inches diagonally dominate module shipments to Detroit engineering centers. Michigan OEM validation labs specify these units across mid-range passenger vehicle trims, pulling demand for bonded capacitive touch sensor layers.
- Head-Up Displays:Micro-projected augmented-reality systems with 10,000 candela per square meter luminance enable windshield-projected navigation and ADAS alerts. California design studios specify waveguide optics for luxury electric platforms, though NHTSA placement geometry constraints limit maximum projection angles.
- Instrument Clusters:Software-defined digital gauge modules replace analog dials in next-generation platforms.
- Rear-Seat Entertainment:Overhead and headrest-mounted displays serve premium family vehicle configurations with declining attach rates.
Today's leader: Center Consoles. Tomorrow's challenger: Head-Up Displays.
Technology:
Cost tier stratification separates mature LCD manufacturing from emerging OLED investments requiring billion-dollar fab commitments.
- LCD:Thin-film transistor liquid-crystal displays with edge-lit backlight assemblies anchor mass-market procurement. Mexican assembly plants in Guadalajara process Gen 6 glass substrates for standardized center console modules serving US cross-border logistics.
- OLED:Self-emissive pixel architecture eliminates backlight assemblies, enabling sub-5mm panel thickness and curved form factors. Luxury OEMs in suburban Detroit specify pillar-to-pillar arrays, though static navigation elements accelerate pixel degradation risks.
- LED:Direct-lit backlighting variants serve commercial vehicle applications requiring extreme temperature tolerance.
- Projection:DLP and laser-phosphor engines power head-up display subsystems with specialized optical path engineering.
LCD commands current volume. OLED claims the steepest expansion trajectory as electrification reshapes cabin design priorities.
End User:
Customer type determines contract structure, with captive OEM engineering centers diverging from independent Tier-1 module integrators on validation timeline risk allocation.
- OEMs:Detroit-based engineering centers maintain in-house display architecture teams for flagship electric platforms. Direct procurement of bare panels enables software layer unbundling, compressing margins for vertically integrated suppliers.
- Tier-1 Suppliers:Specialized integrators cluster in Michigan's Detroit-to-Ann Arbor corridor, offering same-day prototype iteration cycles. These firms absorb AEC-Q100 qualification timelines for display driver ICs, trapping engineering resources across 12-18 month validation cycles.
- Aftermarket Providers:Independent installers serve vehicle modification and repair channels with reduced certification burdens.
- Vehicle Assemblers:Final assembly plants in Mexico and the southern United States specify pre-integrated cockpit modules for line-fit installation.
OEM direct sourcing expands fastest. Tier-1 integrators defend position through specialized HMI validation capabilities.
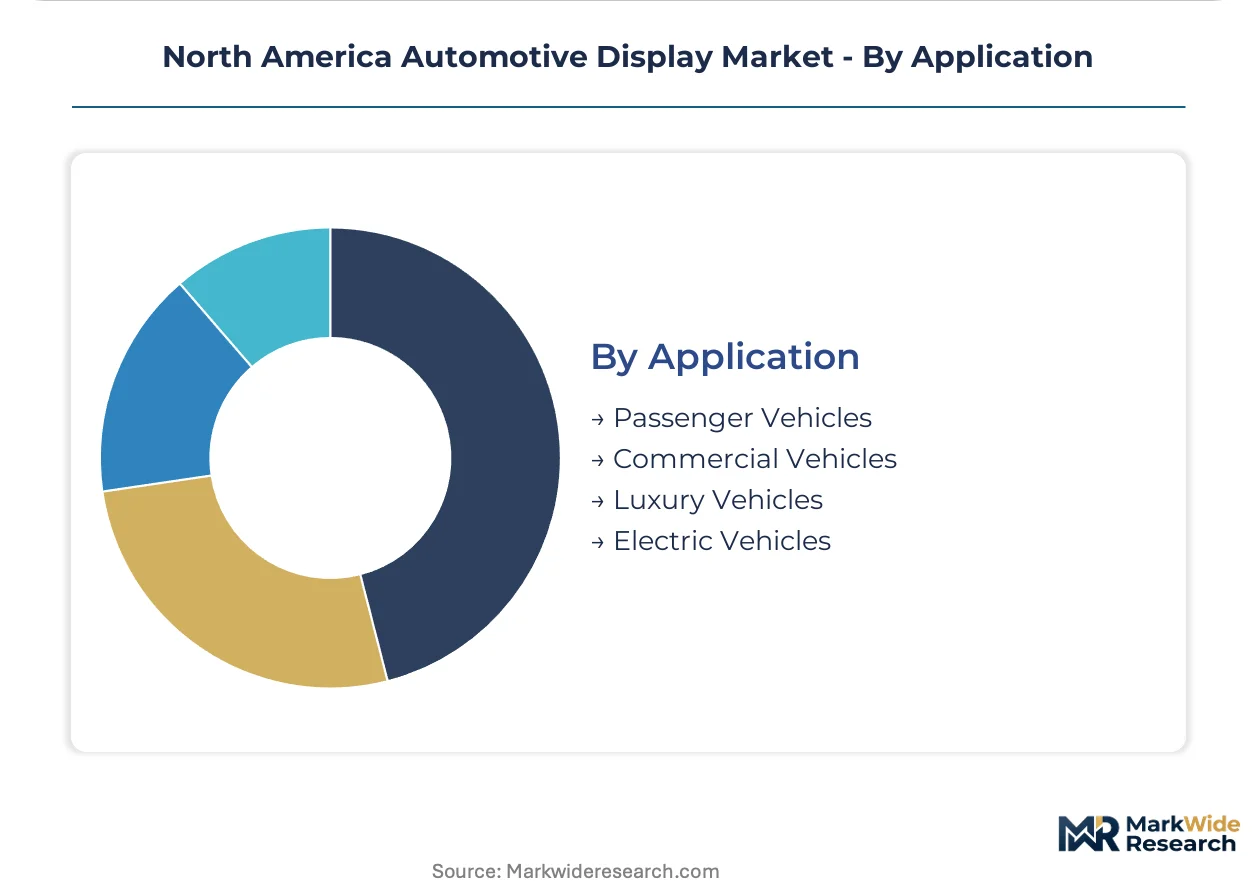
Application:
Vehicle electrification intensity correlates directly with display specification sophistication, creating divergent content and brightness requirements across powertrain categories.
- Electric Vehicles:Battery-electric platforms standardize 15-inch portrait displays as trim-level differentiators, pulling demand for curved OLED substrates from California design studios. NHTSA distracted-driving guidelines force adaptive brightness algorithm investments.
- Luxury Vehicles:Premium cabins specify pillar-to-pillar OLED arrays with true black states for night driving. Transport Canada bilingual labeling mandates create incremental software localization requirements for Ontario-Quebec configurations.
- Passenger Vehicles:Mid-range internal combustion platforms anchor LCD volume procurement with standardized center console formats.
- Commercial Vehicles:Fleet operators source ruggedized displays with extreme temperature tolerance and simplified touch interfaces for vocational applications.
Electric Vehicles drive technology migration. Luxury Vehicles concentrate premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing automotive display assembly capacity across North America as automakers seek compliance-cost differentials between jurisdictions while maintaining proximity to Detroit engineering validation centers.
United States
Michigan's Detroit-to-Ann Arbor corridor concentrates OEM engineering centers and Tier-1 display integration facilities enabling same-day prototype iteration cycles. NHTSA enforces Federal Motor Vehicle Safety Standard 101 governing driver information readability and distraction mitigation, compelling adaptive brightness algorithm investments. California design studios specify pillar-to-pillar OLED arrays for luxury electric platforms.
Canada
Transport Canada mandates bilingual French-English labeling on all displays sold in Canadian vehicle configurations, creating incremental software localization requirements for Ontario-Quebec market configurations. Ontario-based engineering services firms specialize in HMI validation for cross-border supply chains. Quebec's software development clusters support interface localization for North American OEMs.
Mexico
Guadalajara hosts display module assembly operations serving US cross-border logistics with cost-optimized production configurations. Mexican manufacturing benefits from proximity to Texas and California final assembly plants while navigating USMCA rules-of-origin compliance. Jalisco's electronics manufacturing corridor attracts cockpit electronics regionalization investments from multinational Tier-1 suppliers.
North America Automotive Display Market Competitive Landscape
German and Japanese producers anchor one tier; South Korean and American specialists hold differentiated positions in display technology and cockpit integration. The supplier base exhibits tiered concentration with consolidated module integrators competing against specialized optical component vendors. Strategic archetypes include vertically integrated display panel manufacturers, software-defined cockpit platform developers, and precision optics engineering houses. Capacity expansion and strategic technology licensing represent the dominant competitive moves reshaping supplier positioning.
Among Germany-based diversified suppliers, Continental AG and Robert Bosch GmbH exemplify the integrated systems archetype spanning display modules through full cockpit electronics. LG Display represents the panel-specialist tier with captive substrate manufacturing capabilities. Visteon Corporation anchors the American software-centric positioning focused on digital cockpit platforms. These three companies collectively illustrate how geographic origin and corporate structure shape competitive differentiation in display procurement.
| Leading Market Players |
|---|
| Continental AG |
| LG Display |
| Visteon Corporation |
| Denso Corporation |
| Robert Bosch GmbH |
| HARMAN International |
| Panasonic Corporation |
| Nippon Seiki |
| Hyundai Mobis |
| Others |
Value Network & Pricing Analysis
Captive integration into glass substrate manufacturing anchors both supply security and pricing power for North American automotive display producers navigating NHTSA compliance costs and Mexican assembly economics. This structural choice separates premium OLED panel suppliers from LCD module assemblers exposed to Asian indium tin oxide price volatility.
Pricing Analysis
Direct-to-OEM channel discounts compress distributor margins for high-volume center console contracts while specialized HUD integrators retain pricing power through optical engineering premiums. Three-tier pricing structure across premium OLED, standard LCD, and economy LED tiers reflects certification grade differentiation and volume scale. Cost compression in mass-market LCD segments intensifies because Mexican assembly plants optimize for USMCA rules-of-origin compliance. Fleet procurement teams demonstrate highest price sensitivity, whereas luxury OEM studios prioritize form factor innovation over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Detroit engineering centers while specialized integrators serve tier-2 volume requirements through distributor networks. Raw material flows draw from South Korean and Taiwanese glass substrate foundries, Japanese display driver IC fabricators, and Chinese indium tin oxide refiners. Photolithography equipment sourcing rests on Dutch and Japanese capital equipment vendors, creating single-source vulnerability for Gen 6 fab expansions. Distribution runs through Michigan corridor logistics hubs for just-in-time delivery to assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexican manufacturing cost arbitrage against Michigan engineering proximity creates geographic-arbitrage positioning for suppliers balancing USMCA compliance with NHTSA validation access. Labor rate differentials between Guadalajara assembly and Detroit prototyping centers enable tiered cost structures.
For Market Incumbents: Lock in software-defined display platform architecture to defend against emerging optical component specialists capturing HUD content monetization. Prioritize backward integration into touch sensor bonding capacity to control AEC-Q100 qualification timelines that trap engineering resources. Secure dual-source indium tin oxide supply agreements to mitigate Asian smelter concentration risk. For New Entrants and Emerging Players: Augmented-reality waveguide optics offer technology-first wedge positioning against established windshield projection incumbents. Target commercial vehicle fleet configurations with ruggedized LED alternatives where OLED burn-in risk deters adoption. Pursue Transport Canada bilingual software localization contracts as specialized service entry point. For Investors and Strategic Acquirers: Roll-up economics work for software-centric cockpit platform developers because OEM direct sourcing trends fragment hardware-only vendor margins. Five-to-ten year viability favors acquisition targets with validated HMI engineering teams and Mexican assembly footprint. Monitor NHTSA automated driving system HMI rulemaking finalization as demand inflection signal for dual-display redundancy architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Display Platform Investment | Enables subscription revenue models for over-the-air instrument cluster updates. |
| Mexican Manufacturing Footprint Expansion | Secures USMCA rules-of-origin compliance for cross-border OEM supply. |
| OLED Burn-In Mitigation R&D Partnership | Addresses warranty reserve risks from static navigation element degradation. |
| Dual-Source Indium Tin Oxide Supply Agreement | Reduces exposure to Asian smelter price volatility and logistics bottlenecks. |
| Transport Canada Bilingual Localization Service | Captures specialized software contracts for Ontario-Quebec vehicle configurations. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market informing demand calibration. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations specialists combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and customs trade records. Bottom-up module shipment estimates and top-down OEM content-per-vehicle analysis underwent triangulation against capacity announcements.
Rate-of-change decomposition across the analysis window segmented growth by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from installed base replacement cycles, electrification penetration curves, and display size expansion trajectories. Forecast inputs incorporated NHTSA regulatory timeline assumptions and Mexican assembly capacity buildout schedules.
The model holds under stable USMCA trade provisions and NHTSA rulemaking implementation schedules; deviation in tariff structures or automated driving system HMI standard delays would shift capacity investment timing. Forecasts reflect documented assumptions regarding OLED yield improvement rates and indium tin oxide price elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market