
 Automotive Human Interface System Market | 2026-2036
Automotive Human Interface System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Human Interface System Market Analytics
Modular bundling of voice, gesture, and haptic controls into unified cockpit platforms is broadening buyer choice across vehicle segments. Continental AG leverages its integrated hardware-software stack to dominate European OEM supply chains. Harman International sustains its position through R&D intensity in acoustic interface design. Aptiv PLC specializes in AI-driven predictive interaction systems for premium automakers.
Automotive human interface systems encompass the hardware and software architectures that enable occupants to command vehicle functions through touch, voice, gesture, or tactile feedback, typically operating on embedded processors with sub-50 millisecond latency requirements and CAN/LIN bus or Ethernet backbone connectivity; their primary purpose is to minimize driver cognitive load while expanding functionality access. Touchscreen interfaces occupy the largest installed base across infotainment applications, though voice recognition systems represent the fastest-expanding segment as natural language processing improves. Gesture-based controls capture concentrated margin pools in luxury vehicle lines where differentiation commands premium positioning.
NHTSA guidelines on driver distraction, EU General Safety Regulation mandates for driver monitoring, and China's MIIT connected vehicle standards collectively shape product design requirements and market access conditions for interface system suppliers. ECE R79 steering equipment regulations further constrain how haptic feedback systems may interact with vehicle control surfaces. Stakeholders must monitor evolving type-approval harmonization between North American and European frameworks to anticipate compliance-driven redesign cycles.
Market Dynamics
Multimodal interface consolidation is compressing supplier tiers as cockpit domain controllers absorb discrete ECU functions, forcing hardware-software bundling decisions that reshape procurement relationships between Tier 1 integrators and semiconductor vendors.
Growth Catalysts
- NHTSA Distraction Guidelines:Federal mandates for reduced manual input complexity accelerate voice and gesture adoption across US OEM portfolios, creating compliance-driven refresh cycles for interface architectures.
- EU General Safety Regulation:Driver monitoring requirements mandate camera-based attention tracking, expanding sensor fusion demand and integrated HMI platform scope for European vehicle programs.
- Natural Language Processing:Edge-deployed transformer models enable offline intent recognition, removing cloud latency barriers and opening voice interfaces to mass-market vehicle segments previously limited to premium lines.
Market Restraints
- Semiconductor Supply Concentration:Advanced driver-assistance SoC and neural processing unit fabrication concentrates at TSMC and Samsung Foundry, exposing interface system delivery timelines to single-source geographic risk.
- ECE R79 Steering Interface Constraints:Haptic feedback integration with steering columns faces type-approval friction, limiting deployment of force-feedback control surfaces in European markets.
- Touchscreen Reliance:Visual-manual interface dominance persists in cost-optimized segments, delaying multimodal migration and compressing margin pools for advanced interface suppliers.
Strategic Opportunities
- India Connected Vehicle Deployment:MIIT-aligned local standards and domestic production incentives create entry pathways for interface platforms adapted to tropical climate durability and multilingual voice requirements.
- Rear-Seat Entertainment Convergence:Shared mobility fleet operators in China demand occupant-agnostic control architectures, opening white space for gesture and voice systems that bypass personalized profile dependencies.
- ISO 26262 Functional Safety Certification:ASIL-D rated interface controllers command premium positioning in safety-critical domains, rewarding suppliers that invest in fault-tolerant software stacks and redundant hardware pathways.
Industry Challenges
- Embedded Software Talent Scarcity:Real-time operating system expertise and automotive cybersecurity certification capacity lag demand, extending development timelines for safety-rated interface platforms.
- Legacy Bus Architecture Integration:CAN FD and LIN protocol coexistence with Ethernet backbone requirements complicates gateway design, forcing bridge hardware additions that inflate unit costs and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Human Interface System Market |
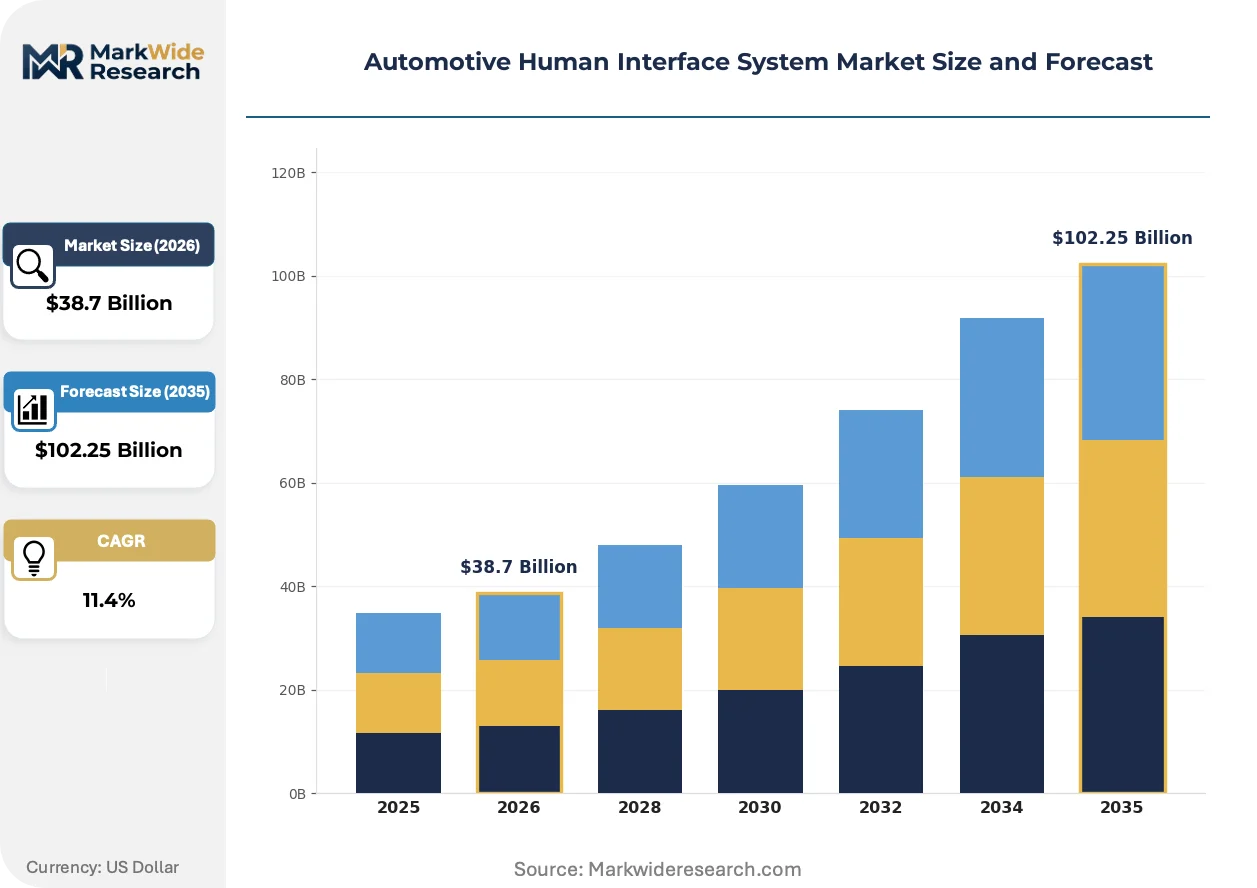
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen, Voice Recognition, Gesture-Based, Haptic Feedback End User: Original Equipment Manufacturers, Aftermarket Consumers, Fleet Operators, Automotive Software Developers Technology: Embedded Systems, Bluetooth Connectivity, Artificial Intelligence, Cloud Integration Application: Infotainment, Navigation, Climate Control, Vehicle Diagnostics |
| Companies Covered | Continental AG, Harman International Industries, Aptiv PLC, Denso Corporation, Visteon Corporation, Synaptics Incorporated, Robert Bosch GmbH, Panasonic Holdings Corporation, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Human Interface System Market Evolving Landscape
Edge AI inference is redistributing computational workload from centralized cloud services to vehicle-mounted processors, enabling responsive interfaces that operate independent of connectivity quality and reshaping supplier value capture toward silicon and software stacks.
Neural processing units embedded within cockpit domain controllers are decentralizing voice recognition and gesture classification from smartphone tethering and remote servers. Mid-tier OEMs in Germany and the United States are adopting these architectures for 2027 model year programs, compressing the premium-mass market feature gap and forcing cloud-dependent service providers to reposition around data monetization rather than latency-critical functions.
EU AI Act risk classification for biometric identification systems is imposing documentation and conformity assessment burdens on driver monitoring deployments. Tier 1 suppliers serving European OEMs are restructuring software development processes to satisfy high-risk system traceability requirements, with camera-based attention tracking modules facing extended homologation timelines compared to equivalent programs for US markets under NHTSA voluntary guidelines.
Fleet procurement of standardized interface platforms is displacing retail-consumer-driven feature differentiation in urban mobility segments. Shared vehicle operators in China and the United States are specifying hardware-minimal, software-upgradeable cockpits that prioritize sanitization-friendly surfaces and universal accessibility over brand-specific design language, channeling R&D investment toward modularity and away from luxury differentiation.
Automotive Human Interface System Market Segmentation
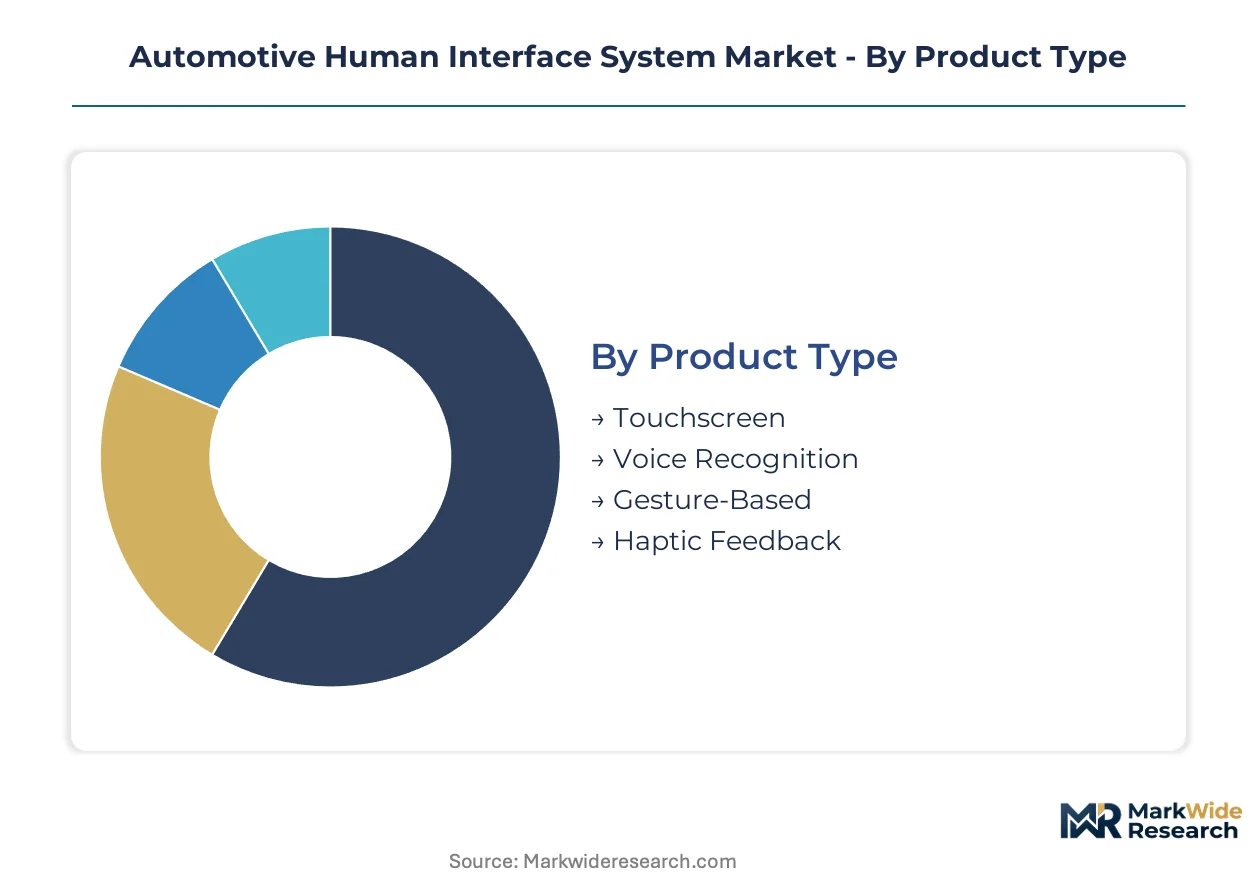
Interface architectures in vehicles refresh on 4-6 year model cycles, creating discrete upgrade windows that reshape segment prioritization. Tier 1 suppliers calibrate R&D allocation across product types and end-user channels based on these procurement rhythms.
Product Type:
Replacement cycles for cockpit hardware accelerate as multimodal bundles displace single-mode legacy units, compressing the effective lifespan of installed interfaces.
- Touchscreen:Capacitive and resistive display panels dominate instrument panel real estate, with 10-15 inch diagonal formats now standard in mid-tier vehicles. OEMs in Germany and the United States specify these for infotainment hubs, though NHTSA distraction guidelines pressure designers toward simplified menu hierarchies.
- Voice Recognition:Natural language processing engines deployed on edge processors enable offline command interpretation without cloud dependency. Demand concentrates in premium passenger vehicles where hands-free operation addresses EU General Safety Regulation driver monitoring requirements.
- Gesture-Based:Time-of-flight cameras and radar sensors detect hand motions for climate and media control.
- Haptic Feedback:Force-actuated control surfaces provide tactile confirmation of virtual button presses.
Touchscreen sits at the top of the volume ranking, with Voice Recognition climbing the fastest.
End User:
Procurement authority fragments across direct OEM supply, post-sale retrofit, fleet standardization, and software platform licensing.
- Original Equipment Manufacturers:Vehicle assemblers specify integrated cockpit domain controllers through multi-year supply agreements. German and US automakers drive specification complexity, binding Tier 1 integrators to ASIL-D functional safety certification for safety-critical interfaces.
- Fleet Operators:Shared mobility providers in China demand occupant-agnostic hardware with sanitization-friendly surfaces and universal accessibility features. Procurement volumes scale with urban mobility deployment timelines.
- Aftermarket Consumers:Retail purchasers upgrade legacy vehicles with add-on voice modules and touchscreen retrofits.
- Automotive Software Developers:Third-party application vendors license SDK access to embedded interface platforms.
Original Equipment Manufacturers capture the dominant revenue share, while Fleet Operators gain share fastest as mobility-as-a-service expands.
Technology:
Compute distribution across edge, device, and cloud layers determines latency performance and connectivity dependency.
- Embedded Systems:Real-time operating systems on automotive-grade microcontrollers execute interface logic with deterministic sub-50 millisecond response. These architectures dominate safety-critical applications where ISO 26262 compliance is mandatory.
- Artificial Intelligence:Neural processing units accelerate intent recognition and predictive interaction models. Edge deployment in cockpit domain controllers removes cloud latency barriers for voice and gesture classification.
- Bluetooth Connectivity:Short-range wireless protocols enable smartphone tethering for secondary display mirroring.
- Cloud Integration:Remote servers host natural language model updates and personalized profile synchronization.
Embedded Systems anchor current installations, with Artificial Intelligence expanding most quickly as NPU silicon costs decline.
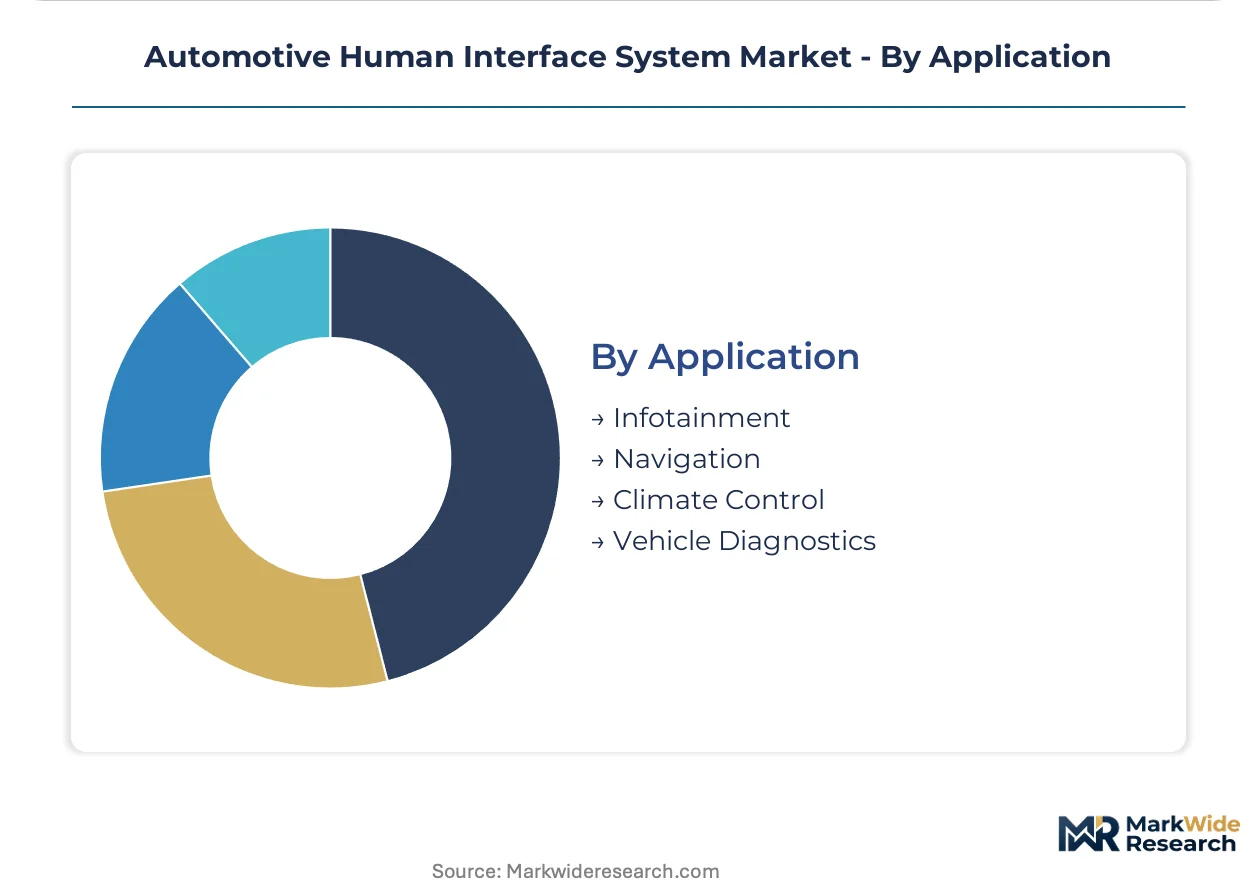
Application:
Functional domain prioritization reflects regulatory pressure on driver attention and passenger experience differentiation.
- Infotainment:Media playback, smartphone integration, and streaming services command the largest interface real estate allocation. Touchscreen and voice modalities compete for dominance here, with EU AI Act biometric provisions adding compliance complexity to camera-based gesture control.
- Navigation:Turn-by-turn guidance systems integrate augmented reality head-up displays and voice-prompted route modification. German OEMs lead specification of these features for highway-intensive driving patterns.
- Climate Control:HVAC adjustment interfaces migrate from physical knobs to haptic surfaces and voice commands.
- Vehicle Diagnostics:Predictive maintenance alerts and system status displays serve fleet operators with uptime-critical requirements.
Infotainment leads by installed base, with Navigation showing the steepest expansion trajectory as augmented reality display costs fall.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive human interface development through its integrated cockpit supply chains, establishing the technical foundations that shaped interface architectures worldwide. The industry's geographic footprint now concentrates where premium vehicle production and regulatory pressure intersect most intensely.
Germany
Premium OEM procurement drives multimodal interface adoption across Bavarian and Baden-Württemberg production clusters. ECE R79 steering equipment regulations constrain haptic feedback deployment, forcing redesign cycles for force-actuated control surfaces. Stuttgart-area suppliers integrate camera-based driver monitoring to satisfy EU General Safety Regulation mandates.
United States
NHTSA distraction guidelines accelerate voice and gesture system refresh cycles across Detroit and Silicon Valley development centers. Federal mandates for reduced manual input complexity reshape infotainment architectures. Michigan-based Tier 1 integrators bind semiconductor vendors to ASIL-D certification timelines for safety-critical interfaces.
China
MIIT connected vehicle standards and domestic production incentives expand interface platform deployment in Yangtze River Delta manufacturing zones. Fleet operators in Shanghai demand occupant-agnostic control architectures for shared mobility applications. Shenzhen-based electronics clusters supply neural processing units for edge-deployed voice recognition.
Japan
METI automotive digitization programs channel R&D investment toward predictive interaction systems in Nagoya and Tokyo development corridors. Domestic OEMs specify embedded processors with sub-50 millisecond latency for safety-critical domains. Kansai-region suppliers specialize in acoustic interface design for premium export programs.
India
PLI scheme incentives and MIIT-aligned local standards create entry pathways for interface platforms adapted to tropical climate durability. Multilingual voice requirements drive natural language processing customization in Tamil Nadu and Maharashtra assembly corridors. Domestic production of cockpit domain controllers accelerates in Bangalore electronics clusters.
Automotive Human Interface System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across functional safety certification tiers, with ASIL-D rated interface controllers commanding procurement preference in European and North American OEM programs. The supplier base organizes into three strategic archetypes: integrated hardware-software stack providers, acoustic interface specialists, and AI-driven predictive interaction developers. Competitive positioning hinges on backward integration into semiconductor sourcing and strategic partnerships with cockpit domain controller fabricators.
Within the integrated systems tier, Continental AG and Robert Bosch GmbH exemplify European-origin suppliers that anchor OEM supply chains through bundled cockpit platforms. Aptiv PLC occupies a position among AI-specialized developers serving premium automaker programs. These three entities represent the dominant competitive archetypes: full-stack integrators leveraging hardware-software bundling, diversified automotive suppliers with captive electronics capabilities, and focused interaction technology developers targeting predictive interface domains.
| Leading Market Players |
|---|
| Continental AG |
| Harman International Industries |
| Aptiv PLC |
| Denso Corporation |
| Visteon Corporation |
| Synaptics Incorporated |
| Robert Bosch GmbH |
| Panasonic Holdings Corporation |
| Valeo SA |
| Others |
Value Network & Pricing Analysis
Premium passenger vehicle OEM procurement concentration in Germany and the United States anchors contract-based long-term supply agreements for cockpit domain controllers, with ASIL-D certification tiers commanding substantial premiums over uncertified alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified interface controllers from ISO 26262-compliant mid-tier units and uncertified aftermarket modules. Price differentiation hinges on functional safety certification grade and volume scale commitments in multi-year OEM contracts. Cost compression in the standard tier is intensifying because NPU silicon costs are declining faster than system integration expenses. Fleet operators in China exhibit the highest price sensitivity, while German premium OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Shanghai orchestrate hub-and-spoke patterns for cockpit hardware fulfillment. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with neural processing units and automotive-grade microcontrollers drawing from TSMC and Samsung Foundry capacity. Supply chain risk centers on single-source geographic vulnerability for advanced driver-assistance SoCs. Distribution runs through Tier 1 integrator warehouses directly to OEM assembly plants, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
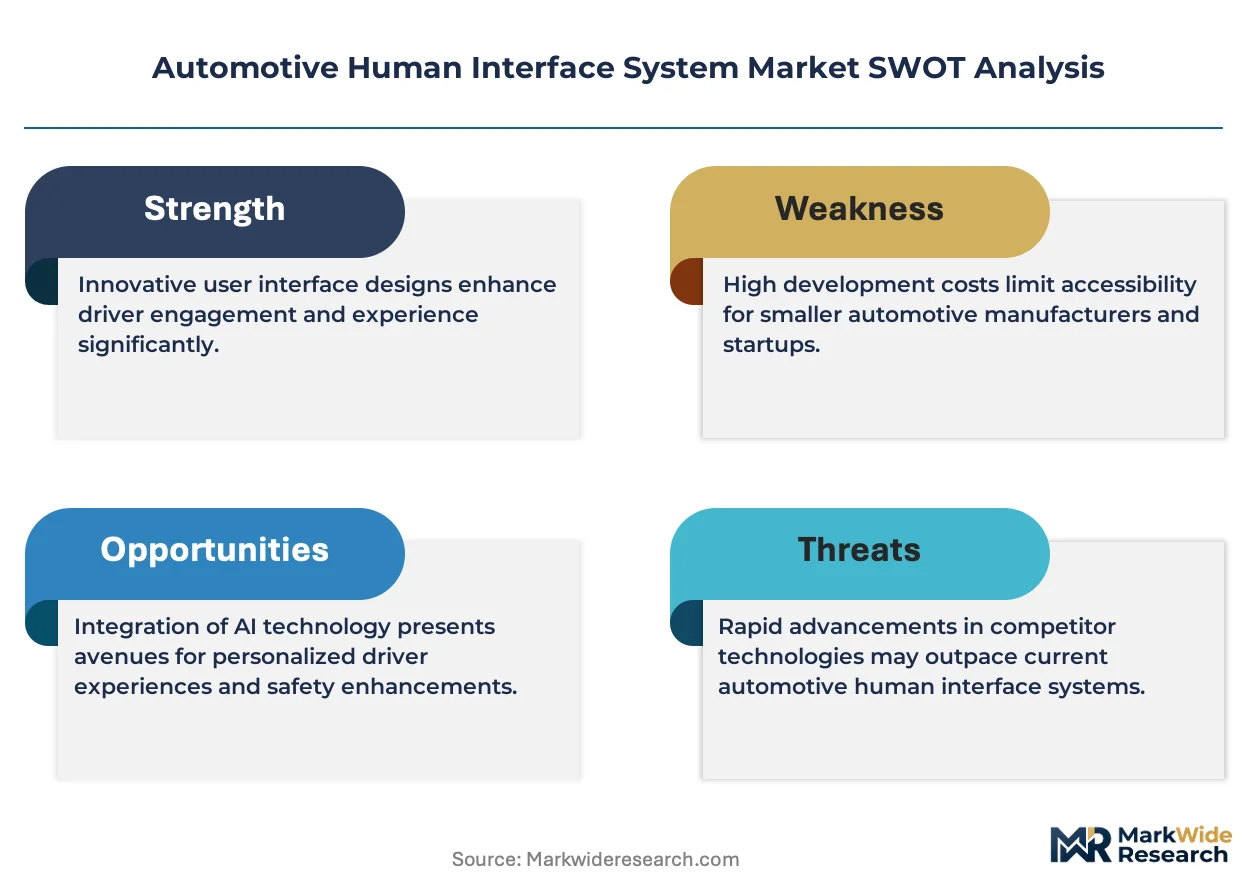
Interface system suppliers can exploit geographic arbitrage between EU AI Act compliance costs in Europe and MIIT-aligned production incentives in China, capturing margin expansion from divergent regulatory investment requirements.
For Market Incumbents: Acquire embedded software talent pools with automotive cybersecurity certification capacity to offset scarcity-driven development timeline extensions. Consolidate procurement relationships with cockpit domain controller fabricators to defend against silicon vendor direct engagement. Secure backward integration into NPU sourcing to mitigate TSMC concentration risk. For New Entrants and Emerging Players: Edge-deployed transformer models for offline voice recognition offer a technology-first wedge into India's multilingual aftermarket and fleet retrofit segments. Target shared mobility operators in China with occupant-agnostic gesture architectures that bypass personalized profile dependencies. Pursue white-label partnerships with domestic electronics clusters in Shenzhen and Bangalore to accelerate market entry. For Investors and Strategic Acquirers: Semiconductor vendors with automotive-grade fabrication capacity are the most active acquirer in this space, seeking software stacks to complete integrated hardware-software offerings. Long-term viability favors suppliers with ASIL-D certification infrastructure and established OEM supply agreements over pure-play software entrants. Watch for MIIT connected vehicle standard harmonization with EU frameworks as the inflection signal for cross-regional platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces OEM integration costs across vehicle segments while compressing supplier tier margins. |
| Software-Defined Vehicle Investment | Enables over-the-air feature activation for NHTSA-compliant voice interfaces without hardware swaps. |
| Battery Supply Agreement | Secures stable power electronics for edge AI inference in electrified vehicle architectures. |
| Geographic Manufacturing Footprint | Positions production near Yangtze River Delta clusters serving MIIT-connected vehicle deployment. |
| Charging Infrastructure Partnership | Integrates human interface systems with fleet management platforms for uptime-critical operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and cockpit domain controller fabricators with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings, and MIIT connected vehicle standard disclosures. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across the analysis window.
Comparable-period anchoring linked projection models to historical refresh cycles spanning 4-6 year automotive model generations. Segmentation dimensions modeled include interface modality, vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from installed base evolution and replacement rate assumptions, with edge AI deployment timelines and regulatory compliance deadlines serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply concentration, ECE R79 regulatory amendments, and EU AI Act enforcement trajectories. Outputs reflect documented assumptions around model cycle timing and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Split-View Camera Module Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Global Vehicle Camera Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market