
 Global Automotive Cockpit Electronics Market | 2026-2036
Global Automotive Cockpit Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Cockpit Electronics Market Analysis
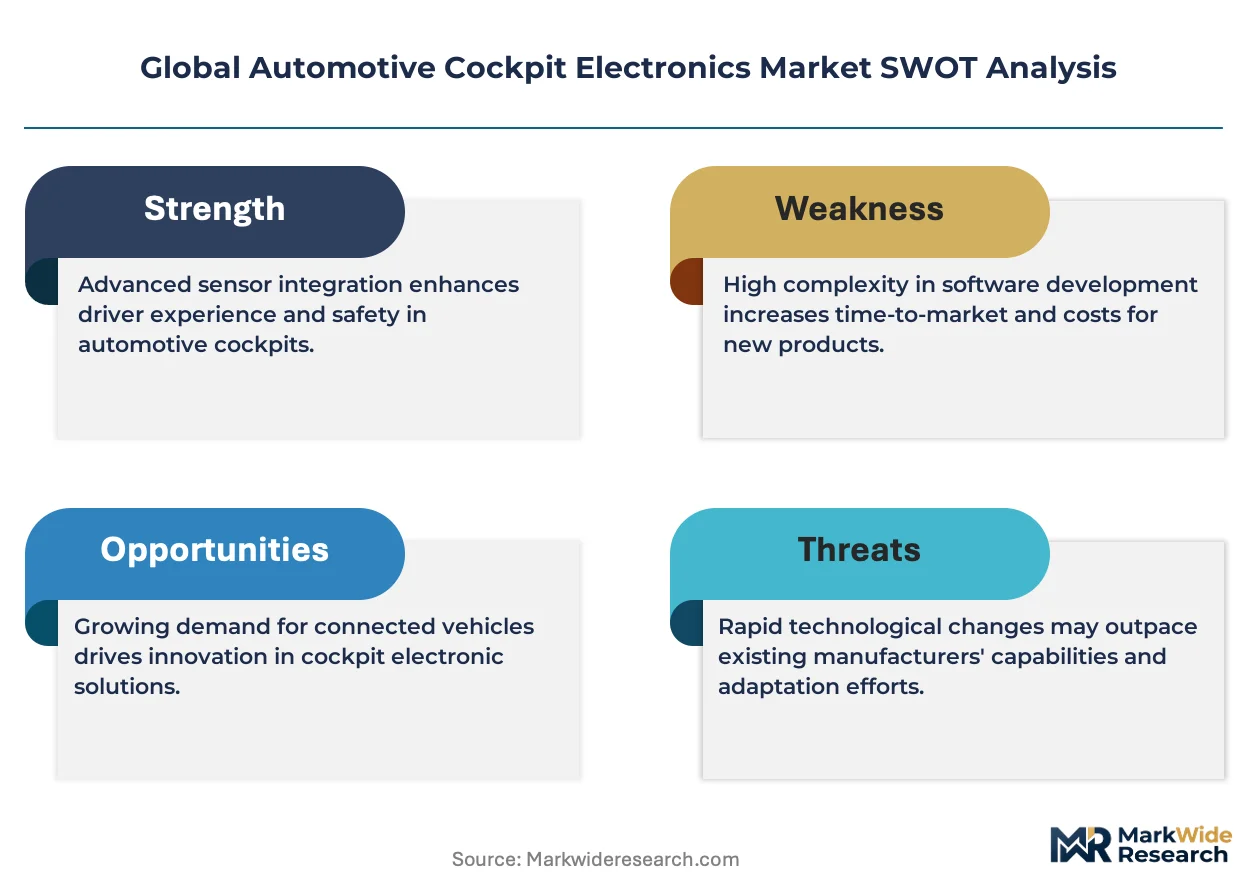
Electric vehicle OEM demand for full-digital cockpit architectures is hardening as legacy automakers accelerate their electrification roadmaps. Continental AG leverages its cross-domain computing expertise to supply integrated cockpit platforms spanning infotainment and instrument cluster functions. Robert Bosch GmbH sustains development intensity in augmented reality head-up displays, competing for flagship programs at German and Asian premium brands. Visteon Corporation anchors its growth in cockpit domain controllers, specializing in software-defined architectures that consolidate multiple ECUs.
Automotive cockpit electronics encompass the integrated hardware-software systems governing information display, driver interaction, and occupant connectivity within the vehicle cabin, typically incorporating multi-core processors, high-resolution display panels, and real-time operating systems to render navigation, vehicle status, and entertainment content. These systems serve the primary commercial purpose of differentiating vehicle interiors while reducing driver distraction through unified human-machine interfaces. Infotainment systems occupy the largest value pool as consumers prioritize seamless smartphone integration and streaming services. Head-up displays represent the fastest-expanding product category, with augmented reality overlays displacing conventional combiner units in premium segments. Touchscreen technology dominates interface design, though voice recognition is gaining share as automakers seek hands-free compliance with distracted-driving regulations.
The U.S. NHTSA enforces distraction-mitigation guidelines that shape touchscreen response-time requirements and voice-control mandate thresholds, while the EU's GDPR and forthcoming AI Act impose data-governance standards on biometric driver-monitoring cameras and in-cabin sensing algorithms. Japan's METI coordinates domestic standards for cybersecurity management systems that Tier-1 suppliers must embed in connected cockpit modules. Stakeholders must monitor divergence between regional software-certification regimes and assess whether cockpit-domain consolidation or federated architectures better serve multi-market compliance.
Market Dynamics
Domain controller consolidation is compressing cockpit electronics architectures from distributed ECU networks to centralized compute platforms, forcing Tier-1 suppliers to restructure software and hardware roadmaps around zonal electronics strategies.
Growth Catalysts
- EU AI Act compliance deadlines:Biometric driver-monitoring mandates in Germany and France are accelerating camera-module and edge-AI processor procurement for occupant-sensing systems.
- China EV platform standardization:Domestic brands are specifying full-cockpit domain controllers from local suppliers, creating concentrated demand pull for integrated instrument cluster-infotainment systems.
- Silicon carbide power semiconductors:Wider bandgap devices are enabling higher-resolution displays and faster processor clocks without thermal throttling, supporting 4K panel adoption.
Market Restraints
- Display panel supply concentration:Korean and Taiwanese OLED manufacturers control premium automotive-grade supply, creating allocation risk during consumer electronics demand surges.
- NHTSA distraction-mitigation thresholds:Response-time requirements for touchscreen interfaces impose rigid design constraints that lengthen development cycles and freeze feature specifications.
- Automotive-grade GPU foundry access:Advanced node capacity at TSMC and Samsung Foundry prioritizes consumer and data center customers, constraining head-up display graphics processor availability.
Strategic Opportunities
- India passenger vehicle digitization:Maruti Suzuki and Tata Motors are upgrading entry and mid-range trims with digital instrument clusters, opening volume tier previously served by analog gauges.
- Japan METI cybersecurity certification:Mandatory SBOM (software bill of materials) requirements for connected cockpit modules create first-mover advantage for suppliers with pre-certified platforms.
- AR-HUD windshield integration:Windshield laminates with embedded waveguide optics are converging with DLP and laser scanning projection to enable larger field-of-view overlays without dashboard volume increase.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise for instrument cluster and HUD systems concentrates at German and Japanese suppliers, constraining program staffing.
- Hypervisor software integration:Consolidating infotainment, instrument cluster, and ADAS visualization on single domain controllers requires real-time OS partitioning that extends validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Cockpit Electronics Market |
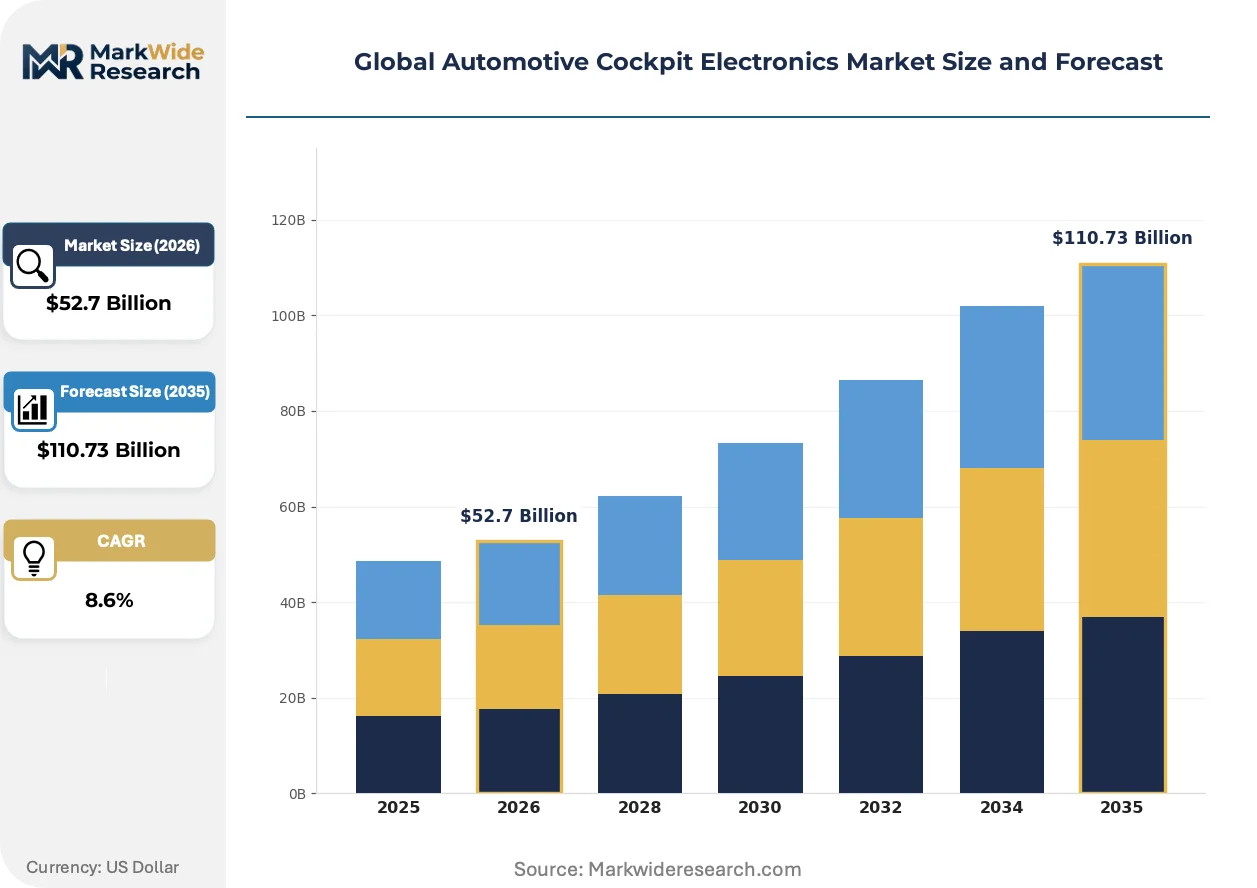
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infotainment Systems, Instrument Clusters, Head-Up Displays, Advanced Driver Assistance Systems Technology: Touchscreen, Voice Recognition, Augmented Reality, Gesture Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Form Factor: Integrated Solutions, Modular Platforms, Standalone Devices, Embedded Systems |
| Companies Covered | Continental AG, Robert Bosch GmbH, Visteon Corporation, Denso Corporation, Harman International, Aptiv, Panasonic Corporation, Alpine Electronics Inc., Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Cockpit Electronics Market Emerging Trajectories
Software-defined cockpit architectures are decoupling hardware refresh cycles from vehicle model years, enabling over-the-air feature activation and subscription revenue models that reshape supplier-OEM commercial relationships.
Single-chip cockpit domain controllers from Qualcomm and Samsung are unifying digital cluster, center stack, and passenger entertainment processing onto unified compute fabrics. Premium EV OEMs in Germany and South Korea are adopting these consolidated platforms for 2026-2028 vehicle programs. This unification is compressing Tier-1 hardware margins while elevating software integration and personalization service contracts as value pools.
The EU's forthcoming AI Act imposes conformity assessment requirements for biometric inference algorithms used in driver-monitoring cameras. Tier-1 suppliers must document training data provenance and algorithmic transparency for type-approval in Germany, France, and Italy. Cockpit module manufacturers are responding by segregating EU-bound software builds from other markets and establishing algorithm audit trails.
Fleet operators and mobility service providers are demanding configurable cockpit layouts that rebrand interfaces across vehicle classes without hardware changes. Rental and ride-hail companies in the United States and United Kingdom are specifying white-label HMI frameworks that deploy fleet-specific graphics skins through OTA updates. This behavior is most visible in commercial EV deployments where shared-ownership models dominate procurement.
Global Automotive Cockpit Electronics Market Segmentation
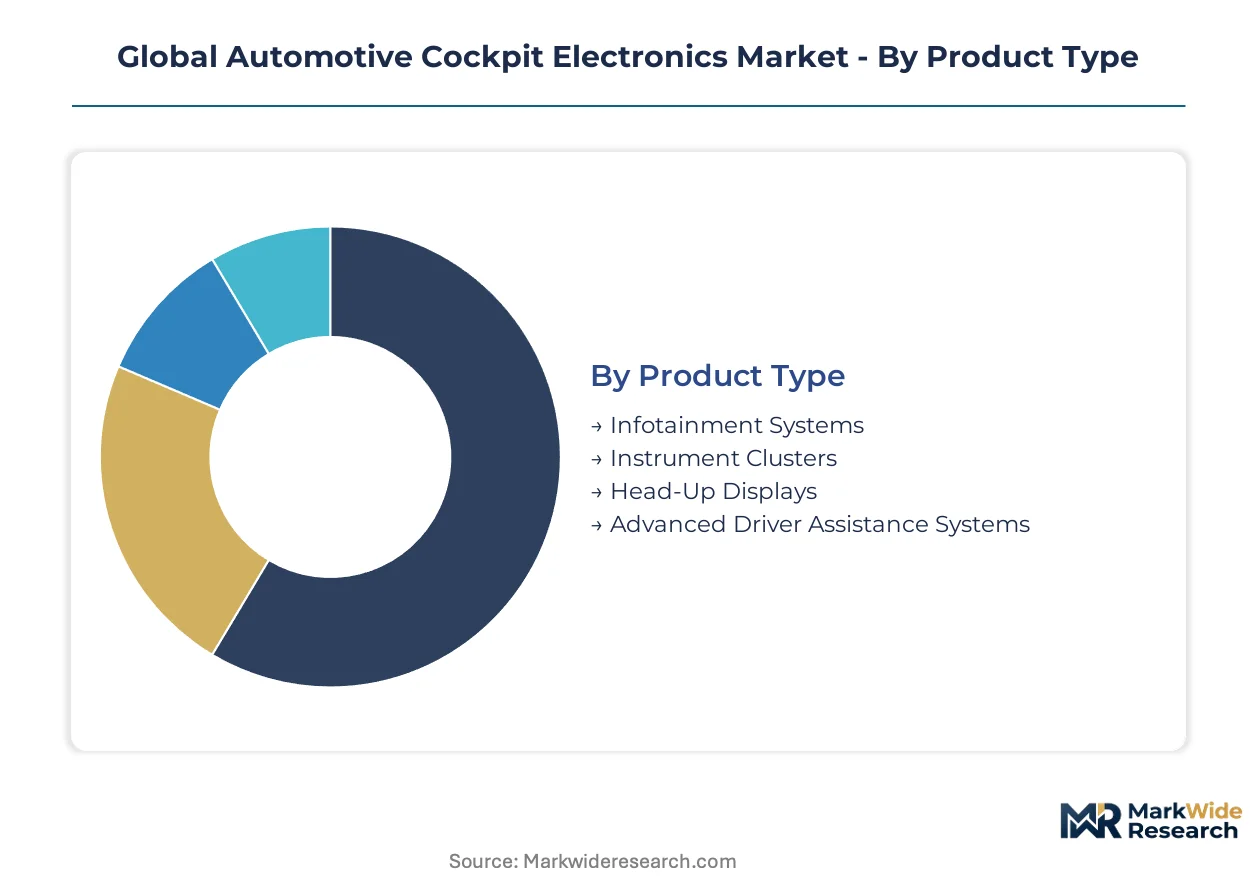
Automotive cockpit electronics segment along four intersecting dimensions that determine procurement patterns and margin structures. Product type and technology choices cascade through form factor decisions, while end-user channel selection locks in development roadmaps and certification requirements. Understanding these segment boundaries clarifies where standardization yields scale and where customization commands premium positioning.
Product Type:
Customization intensity varies sharply across this category, with integrated multi-function platforms demanding bespoke software stacks while discrete modules permit greater hardware reuse.
- Infotainment Systems:Multi-core processor platforms running Android Automotive or proprietary OS environments, consolidating navigation, media streaming, and smartphone mirroring. Demand concentrates at German premium OEMs and Chinese EV brands seeking over-the-air update capabilities to sustain subscription revenue streams.
- Head-Up Displays:Projection optics combining DLP or laser scanning with windshield waveguide integration, rendering vehicle speed and navigation cues within driver sightlines. AR-enabled variants are climbing the fastest in South Korean and German flagship programs where field-of-view expansion justifies unit cost premiums.
- Instrument Clusters:Digital TFT or OLED panel arrays replacing analog gauges, governed by ASIL-B functional safety requirements.
- Advanced Driver Assistance Systems:Sensor fusion modules processing camera and radar inputs for cockpit visualization of lane-keeping and collision warnings.
Most installed capacity flows through Infotainment Systems. Expansion is steepest in Head-Up Displays.
Technology:
Cost tier separation runs from commodity touch controllers through premium AR optics, with voice recognition occupying a mid-tier position shaped by cloud-service dependencies.
- Touchscreen:Capacitive multi-layer panels with haptic feedback mechanisms, dominating center-stack interfaces across all vehicle classes. Volume procurement concentrates at Chinese EV manufacturers specifying 15-inch and larger diagonal formats that consume panel supply from Korean and Taiwanese foundries.
- Augmented Reality:Spatial computing overlays integrating real-time navigation and ADAS alerts into windshield-projected imagery. German and South Korean premium OEMs are gaining share fastest in this segment as windshield-embedded waveguide manufacturing scales beyond prototype volumes.
- Voice Recognition:Natural language processing engines with edge-AI acceleration for offline command execution.
- Gesture Control:Time-of-flight camera arrays detecting hand motions for climate and media adjustments.
Touchscreen captures the largest share of current bill-of-materials spend. Augmented Reality is expanding most quickly as projection technology matures.
End User:
Customer type determines certification burden and contract structure, with OEM direct relationships demanding full design responsibility while aftermarket channels permit specification shortcuts.
- OEMs:Vehicle manufacturers specifying complete cockpit platforms with multi-year program commitments and exclusive supply arrangements. German and Japanese OEMs are concentrating procurement of domain controller architectures that consolidate infotainment and instrument cluster functions onto unified compute substrates.
- Tier-1 Suppliers:System integrators sourcing sub-assemblies for resale to vehicle manufacturers under directed-buy arrangements.
- Aftermarket Providers:Independent distributors retrofitting digital clusters and infotainment units to existing vehicle fleets.
- Vehicle Assemblers:Contract manufacturers building to third-party designs with limited specification authority.
Program volume flows predominantly through OEMs. Tier-1 Suppliers are gaining share fastest as domain controller consolidation elevates integration complexity.
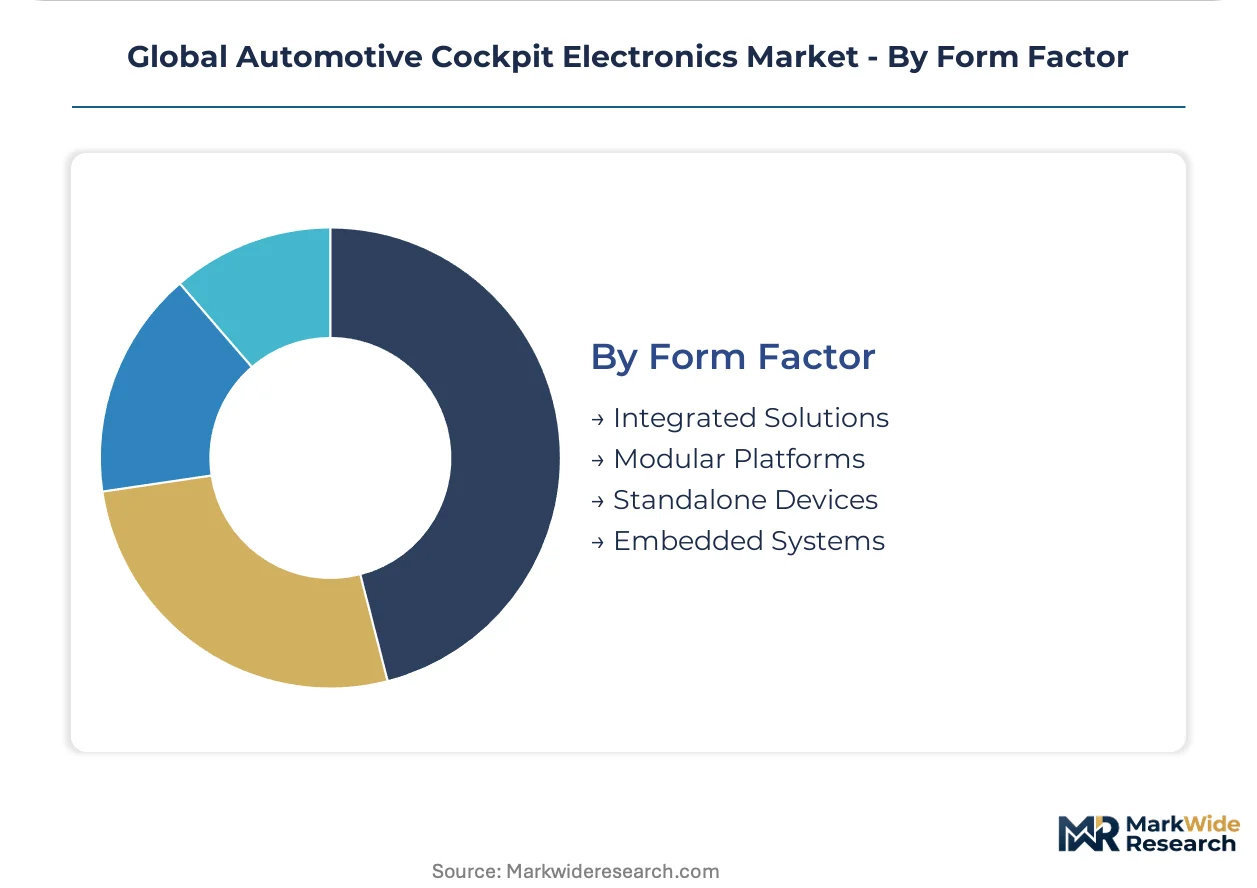
Form Factor:
Supply concentration favors integrated solutions from established Tier-1s, while modular platforms enable second-source strategies that reduce procurement risk.
- Integrated Solutions:Single-vendor platforms combining hardware, software, and HMI design as unified deliverables. Chinese EV brands are specifying these most intensively to compress development timelines and accelerate model-year refresh cycles.
- Modular Platforms:Standardized hardware interfaces permitting software and display panel swaps without architectural redesign.
- Standalone Devices:Discrete units operating independently of vehicle network integration.
- Embedded Systems:Fixed-function modules with limited configurability, common in entry-segment vehicles.
Manufacturing capacity concentrates in Integrated Solutions. Modular Platforms are climbing the fastest as OEMs seek supplier diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cockpit electronics procurement as Tier-1 suppliers migrate engineering capacity toward jurisdictions with harmonized certification regimes and concentrated EV platform demand.
United States
NHTSA distraction-mitigation guidelines are accelerating voice-control and head-up display adoption at Detroit-based OEMs. The Inflation Reduction Act's domestic content incentives are pulling domain controller assembly toward Michigan and Ohio supplier parks. Detroit's automotive corridor is consolidating software-defined cockpit engineering for 2026-2028 electric truck programs.
Germany
KBA type-approval requirements for driver-monitoring systems are hardening procurement specifications at Stuttgart and Munich premium brands. The EU AI Act's biometric inference mandates are forcing algorithm audit trails for camera-equipped cockpit modules. Bavaria's Ingolstadt and Munich tech clusters are scaling AR-HUD waveguide manufacturing for flagship sedan launches.
China
Domestic EV brands are specifying full-cockpit domain controllers from local Tier-1 suppliers at volumes unmatched elsewhere. MIIT cybersecurity standards for connected vehicles are accelerating hardware refresh cycles beyond typical model-year cadences. Shenzhen and Shanghai supplier ecosystems are shipping integrated instrument cluster-infotainment platforms to BYD, NIO, and XPeng.
Japan
METI cybersecurity certification with mandatory SBOM requirements is creating first-mover advantage for pre-certified cockpit module suppliers. Domestic OEMs are consolidating infotainment and instrument cluster functions onto unified compute substrates for 2027 vehicle programs. Nagoya's Chubu region is anchoring cockpit domain controller production for Toyota and Honda electrification roadmaps.
South Korea
Hyundai Motor Group and Kia are adopting single-chip cockpit domain controllers for 2026-2028 EV platforms at scale unmatched by European peers. MFDS-aligned software certification is streamlining export compliance for EU-bound vehicle programs. Seoul Capital Area suppliers are shipping augmented reality head-up display systems for Genesis and Ioniq flagship models.
Global Automotive Cockpit Electronics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform suppliers commanding premium positioning in domain controller categories while modular component vendors compete on volume. The vendor base concentrates among German and Japanese conglomerates with cross-domain computing expertise, Korean electronics groups with display panel integration capabilities, and emerging Chinese specialists capturing domestic EV procurement. Three archetypes dominate: full-stack platform integrators, display-centric subsystem suppliers, and software-defined architecture specialists. Capacity expansion and strategic partnerships represent the dominant competitive vectors as firms seek to secure foundry access and pre-certify platforms for multi-market compliance.
Within the full-stack platform tier, Continental AG and Robert Bosch GmbH exemplify the German engineering conglomerate archetype with cross-domain expertise spanning powertrain and chassis systems. Visteon Corporation occupies a position representing the cockpit-specialist archetype, with corporate roots and naming convention indicating US-based incorporation. These three entities anchor the competitive structure, with Continental and Bosch leveraging diversified industrial footprints while Visteon exemplifies focused cockpit-domain positioning.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Visteon Corporation |
| Denso Corporation |
| Harman International |
| Aptiv |
| Panasonic Corporation |
| Alpine Electronics Inc. |
| Hyundai Mobis |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ASIL-D instrument clusters and commodity infotainment modules manifests in divergent margin structures and supply chain configurations across German, Japanese, and Chinese supplier ecosystems. Premium safety-critical hardware commands foundry priority and captive silicon allocation, while standard-grade touchscreen controllers face price erosion from panel oversupply in Korean and Taiwanese manufacturing hubs.
Pricing Analysis
Distributor markups compress as OEMs consolidate procurement through direct Tier-1 relationships for domain controller platforms. Three-tier pricing structure across premium AR-HUD, standard digital cluster, and economy analog-replacement tiers reflects ASIL certification burden and GPU foundry access constraints. Cost compression in mid-grade infotainment stems from Android Automotive license commoditization. Fleet operators exhibit highest price sensitivity, while German premium OEMs absorb silicon premiums for windshield-integrated waveguide optics.
Supply Chain Analysis
Ocean freight volatility from Asia-Pacific to Europe and North America amplifies landed cost variance for 15-inch and larger display panels. Manufacturing concentrates in China, South Korea, and Taiwan for OLED substrates, with Germany and Japan anchoring ASIL-certified processor packaging. Raw material dependencies span silicon carbide wafers, rare-earth phosphors for laser scanning, and automotive-grade epoxy laminates. Single-source vulnerability concentrates at TSMC advanced nodes for cockpit domain controller SoCs. Distribution runs through OEM-directed Tier-1 supply arrangements with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-defined service layers as hardware commoditization accelerates, with domain controller consolidation shifting value capture toward OTA-enabled feature activation and subscription billing architectures.
For Market Incumbents: Deploy hypervisor certification investments to lock in OEM platform decisions before EU AI Act enforcement hardens compliance requirements. Consolidate software engineering capacity in Germany and Japan to defend against Chinese domain controller specialists capturing domestic EV procurement. Threaten margin compression from Qualcomm and Samsung single-chip unification demands counter by anchoring long-term service contracts with personalized HMI skin libraries. For New Entrants and Emerging Players: Begin with white-label HMI framework development targeting United States and United Kingdom fleet operators seeking rebrandable cockpit interfaces without hardware redesign. Most penetrable segment sits in commercial EV ride-hail and rental deployments where shared-ownership models dominate procurement. Go-to-market angle emphasizes OTA deployment velocity and SBOM pre-certification for Japan METI compliance acceleration. For Investors and Strategic Acquirers: Asymmetric upside sits with cockpit-domain specialists possessing pre-certified cybersecurity platforms and algorithm audit trail capabilities for EU biometric inference mandates. Long-term viability hinges on software revenue share expansion outpacing hardware margin erosion across the next decade. Target acquisition archetype combines AR-HUD waveguide manufacturing expertise with edge-AI processor integration capabilities. Signal to watch is Tier-1 supplier announcements of foundry capacity reservations at automotive-grade nodes.| Strategic Initiative | Industry Significance |
|---|---|
| Domain Controller Platform Standardization | Consolidates infotainment and instrument cluster compute onto Qualcomm Snapdragon substrates, compressing hardware refresh cycles. |
| AR-HUD Windshield Waveguide Integration | Enables Genesis and Ioniq flagship programs to deploy larger field-of-view overlays without dashboard volume expansion. |
| Software-Defined Vehicle Investment | Decouples feature activation from model years, unlocking subscription revenue streams for Continental and Bosch platforms. |
| Geographic Manufacturing Footprint Expansion | Pulls domain controller assembly toward Michigan and Ohio supplier parks under Inflation Reduction Act domestic content incentives. |
| Cybersecurity Certification Pre-Positioning | Creates first-mover advantage for Japan METI SBOM compliance and EU AI Act algorithm audit trail requirements. |
Methodological Framework
Direct dialogue with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations specialists grounded qualitative findings across German, Japanese, Chinese, and United States automotive corridors. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed suppliers, and MIIT cybersecurity disclosure records. Bottom-up and top-down triangulation reconciled component-level bill-of-materials analysis with aggregate OEM procurement budget trajectories.
Bottom-up modeling segmented volume and value across the projection horizon by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. Top-down verification cross-checked against aggregate electronics content forecasts from regulatory filing disclosures. CAGRs derived from weighted average of historical replacement cycle compression, EV platform standardization velocity, and regulatory mandate implementation schedules. Industry-specific inputs incorporated NHTSA distraction-mitigation compliance timelines and EU AI Act conformity assessment pathways.
Caveats apply where foundry capacity reallocation toward data center customers or geopolitical restriction on advanced node exports could materially shift the outlook for head-up display graphics processor availability. Forecasts reflect assumptions regarding EV adoption cadence and regulatory harmonization across jurisdictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market