
 Automotive Optical Fiber Data Cable Systems Market | 2026-2036
Automotive Optical Fiber Data Cable Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Optical Fiber Data Cable Systems Market Insights
Modular fiber harness configurations is decoupling sensor-to-ECU connectivity from legacy copper bundles, letting OEMs scale bandwidth without rewiring entire vehicle platforms. Corning leverages its glass optical fiber leadership to anchor high-temperature engine-bay applications where signal integrity failures carry warranty risk. Prysmian Group competes through backward integration into polymer cladding compounds, sustaining margin control across tight-buffer cable lines. Sumitomo Electric Industries dominates Asian OEM supply chains with manufacturing scale in Japan and Thailand, positioning its multi-mode fiber portfolio for next-generation vehicle communication networks.
Automotive optical fiber data cable systems transmit high-bandwidth digital signals through silica or polymer waveguides rated for temperatures exceeding 125°C and flex-cycle counts above one million, serving primarily to replace copper in electromagnetic-interference-sensitive vehicle zones. Plastic optical fiber leads in cost-constrained infotainment links where bandwidth demands stay below 150 Mbps, while glass optical fiber captures ADAS and autonomous control systems requiring gigabit throughput with near-zero latency. Dense wavelength division multiplexing represents the fastest-growing technology segment as it multiplies effective fiber capacity without adding physical cable weight, a critical parameter for electric vehicles where every gram affects range certification.
FCC electromagnetic emissions rules in the United States, EU F-Gas Regulation material restrictions, and Japan's METI automotive safety standards collectively mandate shielding effectiveness and halogen-free jacketing that only optical architectures natively satisfy. NHTSA crash-test data-integrity requirements are pushing Tier-1 suppliers toward fiber for event-recorder survivability, creating a regulatory pull independent of bandwidth economics. Stakeholders must decide whether to prioritize glass fiber performance for autonomous platforms or plastic fiber cost structures for mass-market electrification, as this technology fork will lock in supplier relationships across two vehicle generations.
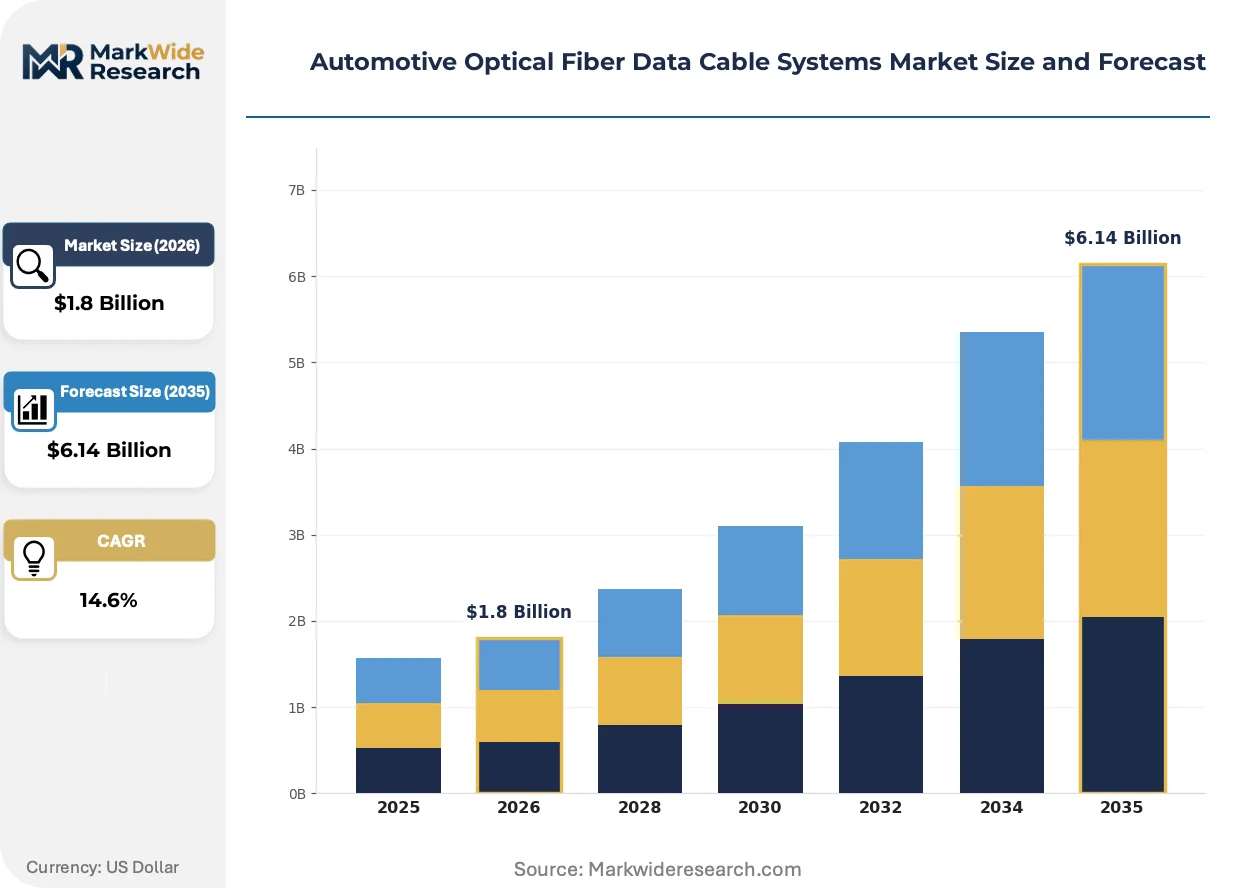
Market Dynamics
ADAS-to-autonomous control migration is forcing fiber-optic architectures into engine-bay and chassis zones previously reserved for copper shielding, with Germany's KBA and Japan's METI tightening electromagnetic compatibility certification timelines that compress supplier qualification windows.
Growth Catalysts
- Dense Wavelength Division Multiplexing:This technology multiplies effective fiber capacity without adding cable weight, directly addressing electric vehicle range-certification constraints where every gram affects battery efficiency ratings.
- NHTSA Crash-Test Data Integrity:Event recorder survivability mandates are pulling Tier-1 suppliers toward optical architectures that withstand impact and thermal stress better than copper alternatives.
- EU F-Gas Regulation:Halogen-free jacketing requirements for automotive electronics create material specifications that optical fiber systems natively satisfy while copper alternatives face reformulation costs.
Market Restraints
- Glass Fiber Cost Structure:Silica waveguide production requires capital-intensive draw towers and hermetic coating lines that concentrate supply among a handful of specialized manufacturers.
- Polymer Cladding Volatility:Fluorinated acrylate and perfluorinated polymer feedstock prices fluctuate with specialty chemical capacity in Japan and Germany, squeezing margin on plastic optical fiber bundles.
- Copper Substitution Defense:Shielded twisted-pair cable improvements and active electromagnetic interference cancellation chips present viable alternatives for sub-gigabit vehicle links.
Strategic Opportunities
- Thailand Manufacturing Expansion:Japanese and German Tier-1 suppliers are relocating fiber harness assembly to capture ASEAN electric vehicle production growth and avoid tariff exposure.
- Vehicle-to-Everything Integration:Fiber's immunity to roadside radar and cellular interference positions it for roadside-unit and infrastructure-to-vehicle communication modules.
- CSRD Supply Chain Disclosure:Corporate sustainability reporting requirements in Europe favor optical fiber's lower lifecycle carbon footprint against copper mining and smelting emissions.
Industry Challenges
- Optical Connector Qualification:Automotive-grade ferrule and alignment sleeve testing protocols demand million-cycle flex and thermal-shock validation that extends development timelines.
- Cross-Functional Talent Scarcity:Engineers combining photonics physics with automotive reliability engineering remain concentrated in Stuttgart, Nagoya, and Detroit metro clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Optical Fiber Data Cable Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Fiber, Multi-Mode Fiber, Armored Cable, Flat Ribbon Cable, Loose Tube Cable, Tight Buffer Cable Technology: Plastic Optical Fiber, Glass Optical Fiber, Fiber Bragg Grating, Dense Wavelength Division Multiplexing, Time Division Multiplexing, Coarse Wavelength Division Multiplexing Application: Advanced Driver Assistance Systems, In-Vehicle Infotainment, Vehicle Communication Networks, Sensor Data Transmission, Telematics, Autonomous Control Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assembly Lines, Fleet Operators, Specialty Vehicle Manufacturers |
| Companies Covered | Corning, Prysmian Group, Sumitomo Electric Industries, OFS Fitel, Furukawa Electric, Nexans, Leoni, LS Cable & System, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Optical Fiber Data Cable Systems Market Trends and Innovations
Silicon photonics and automotive-grade packaging are merging to collapse transceiver size and power draw, while regulatory pressure on electromagnetic emissions accelerates fiber deployment into safety-critical vehicle domains previously dominated by copper.
Multi-mode glass fiber is converging with silicon photonic transceiver chips to enable 100-gigabit links between lidar sensors and central compute nodes. Premium electric vehicle platforms in Germany and California are adopting these chip-scale optical engines for autonomous highway-pilot systems. The technology is converging with automotive thermal management requirements, forcing packaging redesigns that survive 150°C under-hood peaks without active cooling.
Japan's METI automotive safety standards now explicitly recognize optical fiber as a compliant medium for brake-by-wire and steer-by-wire command pathways, creating regulatory precedent that other jurisdictions are studying. This certification pathway compresses supplier qualification timelines for Japanese OEMs while forcing European and North American rivals to accelerate their own fiber validation programs. Tier-1 brake system suppliers in Nagoya and Stuttgart are reconfiguring control module architectures around this mandate.
Fleet operators and mobility-service providers are bundling fiber-health monitoring into predictive maintenance contracts, shifting cable specification decisions from procurement cost-minimization toward total-cost-of-ownership frameworks. This purchasing pattern disrupts traditional wire-harness supplier relationships in commercial vehicle segments. German logistics fleets and North American ride-hail operators are piloting these service-integrated supply agreements first.
Automotive Optical Fiber Data Cable Systems Market Segmentation
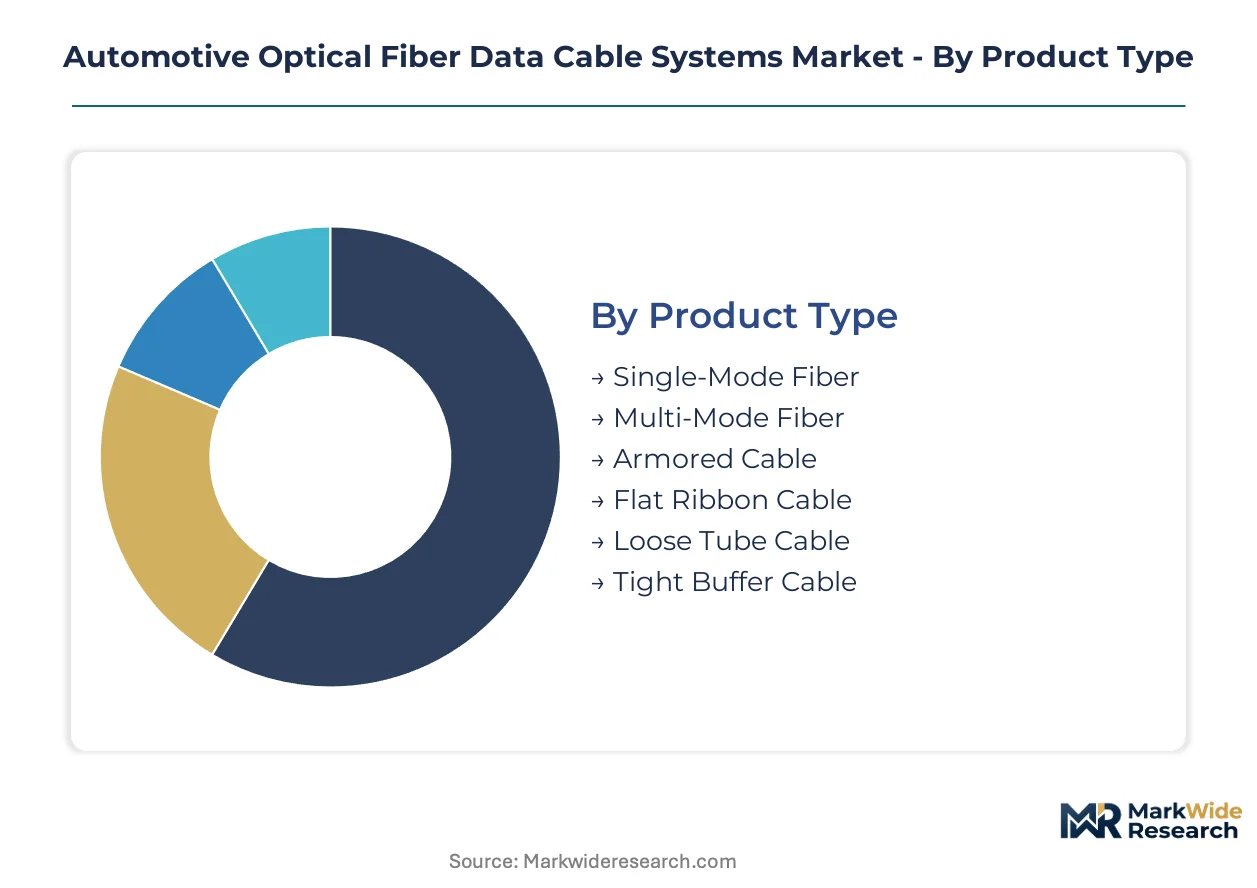
Automotive optical fiber data cable systems fragment across four dimensions that determine supplier qualification requirements and margin structures. Product type and technology choices lock in manufacturing capital intensity, while application and end-user segments dictate certification timelines and contract volumes.
Product Type:
Single-mode fiber demands the steepest upfront investment due to precision draw towers and hermetic coating infrastructure. Multi-mode fiber and cable variants require less specialized equipment but compete on polymer formulation and assembly automation.
- Single-Mode Fiber:Silica waveguides with 8-10 micron core diameters transmit coherent laser signals across kilometer-scale distances with minimal dispersion. German OEMs specify single-mode for lidar-to-compute links in Level 3 autonomous platforms where signal fidelity determines system response latency. Draw tower utilization rates concentrate supply among Corning and Prysmian facilities in North Carolina and Milan.
- Multi-Mode Fiber:Larger 50-62.5 micron cores accommodate lower-cost vertical-cavity surface-emitting lasers for shorter vehicle links. Japanese Tier-1 suppliers in Nagoya and Bangkok assembly plants favor multi-mode for camera-to-ECU connections where bend radius tolerance outweighs distance requirements. Sumitomo Electric's captive fiber production in Osaka and Rayong supports this specification dominance.
- Armored Cable:Steel or aramid reinforcement layers protect against crush and abrasion in chassis routing zones.
- Flat Ribbon Cable:Parallel fiber arrays enable high-density connectorization behind instrument panels where space constraints dominate.
- Loose Tube Cable:Gel-filled buffer tubes accommodate thermal expansion in engine-bay installations.
- Tight Buffer Cable:Direct polymer coating over cladding suits interior cabin links requiring tight bend radii.
Multi-mode fiber absorbs the bulk of installed capacity; single-mode fiber is expanding most quickly.
Technology:
Glass optical fiber commands premium pricing through material purity requirements, while plastic alternatives compete on assembly simplicity. Wavelength multiplexing technologies multiply effective bandwidth without additional physical infrastructure.
- Plastic Optical Fiber:Perfluorinated polymer cores transmit visible and near-infrared light with 2.5 dB/m attenuation, acceptable for sub-10 meter infotainment links. Cost structures align with mass-market electric vehicle platforms in Thailand and Mexico where procurement teams prioritize harness weight reduction over bandwidth headroom. Fluorinated acrylate feedstock volatility from Japanese chemical suppliers compresses margin predictability.
- Dense Wavelength Division Multiplexing:Optical multiplexers stack 40-80 independent channels onto single fiber pairs, collapsing cable mass for electric vehicle range certification. California and Bavaria-based premium OEMs specify DWDM for zonal architecture backbones where centralized compute nodes aggregate sensor floods. The technology climbs the fastest among multiplexing variants as silicon photonic transceiver costs decline.
- Glass Optical Fiber:High-purity silica achieves sub-0.5 dB/km attenuation for ADAS-critical pathways.
- Fiber Bragg Grating:Inscribed refractive index gratings enable strain and temperature sensing within structural cables.
- Time Division Multiplexing:Electronic switching allocates bandwidth sequentially for cost-constrained legacy architectures.
- Coarse Wavelength Division Multiplexing:Wider channel spacing reduces optical component precision requirements for mid-tier platforms.
Glass optical fiber captures the highest value per meter; DWDM is gaining share fastest among multiplexing technologies.
Application:
Autonomous control systems and ADAS generate the most stringent reliability specifications, while infotainment accepts lower-grade fiber to manage bill-of-materials pressure.
- Advanced Driver Assistance Systems:Camera, radar, and lidar fusion demands sub-microsecond latency with 99.999% availability across temperature extremes. German KBA electromagnetic compatibility mandates explicitly reference optical isolation for forward-collision warning pathways, forcing Tier-1 brake suppliers in Stuttgart toward fiber-native architectures. Validation protocols extend 18-24 months for safety-critical link qualification.
- Autonomous Control Systems:Redundant command pathways for steer-by-wire and brake-by-wire require fault-tolerant topologies that copper cannot economically shield. Japan METI regulatory recognition of optical compliance compresses supplier timelines for Nagoya-based OEMs while forcing European rivals to accelerate parallel validation. The segment exhibits the steepest specification escalation as Level 4 prototypes advance.
- In-Vehicle Infotainment:Display and audio distribution tolerates higher latency for cost-sensitive mass-market segments.
- Vehicle Communication Networks:Gateway and domain controller interconnects balance bandwidth against electromagnetic emissions compliance.
- Sensor Data Transmission:Distributed environmental and occupancy sensors prioritize installation flexibility over peak throughput.
- Telematics:Cellular and satellite modem backhauls exploit fiber immunity to antenna crosstalk in roof-mounted modules.
ADAS absorbs the bulk of fiber volume today; autonomous control systems show the steepest expansion trajectory.
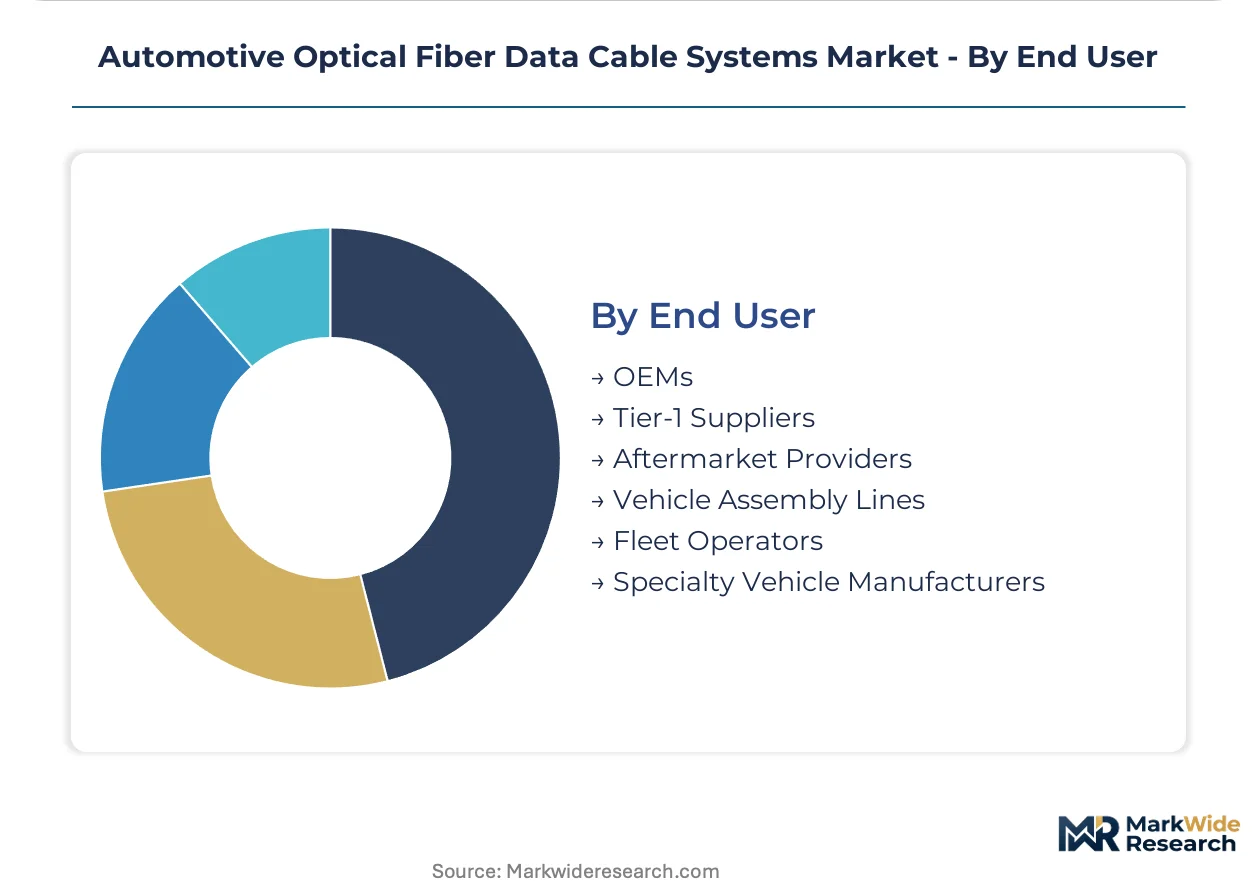
End User:
OEM direct procurement concentrates specification authority, while Tier-1 suppliers compete on harness integration and logistics execution.
- OEMs:Premium German and Japanese manufacturers retain fiber specification authority for autonomous and powertrain domains where warranty exposure concentrates. Direct contracts with Corning and Prysmian lock in multi-year supply agreements with price-volume mechanisms tied to electric vehicle platform launches. Procurement teams in Munich and Toyota City prioritize qualification speed over unit cost for safety-critical links.
- Tier-1 Suppliers:Brake, steering, and infotainment system integrators in Stuttgart and Detroit metro clusters bundle fiber harnesses with control module assemblies. These suppliers absorb optical connector qualification costs to defend position in OEM vendor reduction programs. Margin pressure intensifies as OEMs push volume commitments downstream.
- Aftermarket Providers:Retrofit infotainment and telematics upgrades for commercial fleets.
- Vehicle Assembly Lines:Just-in-sequence harness delivery for final trim installation.
- Fleet Operators:Predictive maintenance contracts bundle fiber health monitoring for logistics vehicles.
- Specialty Vehicle Manufacturers:Military and emergency vehicle specifications demanding extreme environmental survival.
OEMs command the largest contract values; Tier-1 suppliers are expanding their fiber content fastest through subsystem integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes the most automotive optical fiber per vehicle for autonomous platforms, while Thailand and Mexico expand assembly capacity for export-bound harnesses. Japan anchors glass fiber draw tower supply for Asian OEMs. United States demand concentrates in California and Michigan for electric vehicle zonal architectures.
United States
NHTSA crash-test data integrity mandates pull Tier-1 brake suppliers toward optical event recorders. FCC electromagnetic emissions rules tighten shielding requirements that fiber satisfies natively. Detroit metro clusters host validation labs where suppliers compress 18-month qualification timelines for autonomous highway-pilot systems.
Germany
KBA electromagnetic compatibility certification explicitly references optical isolation for forward-collision warning pathways. EU F-Gas Regulation halogen-free jacketing requirements favor fiber over copper reformulation costs. Stuttgart industrial corridors concentrate brake-by-wire and steer-by-wire control module redesigns around METI-compliant fiber architectures.
Japan
METI automotive safety standards now recognize optical fiber as compliant for brake-by-wire command pathways. JIS standards govern connector million-cycle flex validation protocols. Nagoya-based OEMs compress supplier qualification timelines while Osaka and Rayong manufacturing scales multi-mode fiber for camera-to-ECU links.
Thailand
ASEAN electric vehicle production growth drives Japanese and German Tier-1 suppliers to relocate harness assembly. Board of Investment incentives support fiber optic component manufacturing zones. Rayong and Bangkok industrial estates capture zonal architecture backbone contracts for battery electric platforms exported to Europe.
China
MIIT vehicle-to-everything communication standards exploit fiber immunity to roadside radar interference. Dual carbon goals favor optical fiber's lower lifecycle emissions against copper smelting. Yangtze River Delta clusters pilot silicon photonic transceiver packaging for 100-gigabit lidar-to-compute links.
Automotive Optical Fiber Data Cable Systems Market Competitive Landscape
The competitive structure tilts toward materials-scaled specialists with captive fiber draw capacity. Three to five integrated manufacturers control high-purity silica supply while mid-tier assemblers compete on harness integration logistics. Archetypes separate into glass fiber purists, polymer cladding compounders, and connector-integrated harness providers. Capacity expansion and backward integration into specialty chemical feedstocks dominate competitive moves as qualification timelines compress.
Among glass fiber specialists, Corning anchors North American supply for high-temperature engine-bay applications. Prysmian Group exemplifies European backward integration into polymer cladding compounds. Sumitomo Electric Industries occupies a position within Asian OEM supply chains through manufacturing scale in Japan and Thailand. These three represent the materials-scaled tier where draw tower utilization rates and hermetic coating infrastructure create qualification barriers.
| Leading Market Players |
|---|
| Corning |
| Prysmian Group |
| Sumitomo Electric Industries |
| OFS Fitel |
| Furukawa Electric |
| Nexans |
| Leoni |
| LS Cable & System |
| TE Connectivity |
| Others |
Pricing and Supply Chain Analysis
OEM procurement teams in Munich and Toyota City now mandate million-cycle flex validation and halogen-free jacketing as baseline qualifiers, forcing suppliers to absorb optical connector qualification costs that concentrate pricing power among draw tower operators with captive hermetic coating infrastructure.
Pricing Analysis
Margin tightening in plastic optical fiber bundles reflects fluorinated acrylate feedstock volatility from Japanese chemical suppliers. Three-tier pricing structure across premium glass fiber, standard multi-mode, and economy plastic optical fiber tiers separates ADAS-critical pathways from infotainment links. Cost compression accelerates in mass-market electric vehicle platforms as Thai assembly plants prioritize harness weight reduction over bandwidth headroom. Tier-1 brake suppliers exhibit lowest price sensitivity due to warranty exposure; aftermarket retrofit providers face highest procurement pressure.
Supply Chain Analysis
Million-cycle flex and thermal-shock validation protocols gate supply chain entry, concentrating high-purity silica fiber production among Corning's North Carolina draw towers, Prysmian's Milan coating facilities, and Sumitomo's Osaka-Rawong axis. Raw material dependencies center on fluorinated polymer feedstocks from Japanese chemical suppliers, germanium-doped silica preforms, and automotive-grade ferrule ceramics. Single-source vulnerability in specialty polymer cladding compounds threatens margin stability. Distribution runs through just-in-sequence harness delivery to final vehicle trim lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualification timeline compression from Germany's KBA and Japan's METI is forcing sub-scale harness assemblers toward exit or acquisition, consolidating supply relationships among materials-scaled specialists.
For Market Incumbents: Anticipate copper substitution defense from shielded twisted-pair improvements and active EMI cancellation chips by deepening backward integration into polymer cladding compounds and expanding captive draw tower utilization in Thailand to capture ASEAN electric vehicle production growth. For New Entrants and Emerging Players: EU F-Gas Regulation halogen-free jacketing requirements in Germany open a window for specialty cable assemblers without legacy copper reformulation burdens. Target infotainment retrofit contracts for North American ride-hail fleets where predictive maintenance bundling disrupts traditional wire-harness relationships. Lead with fiber-health monitoring service integration as differentiated go-to-market positioning. For Investors and Strategic Acquirers: The window for entry favors mid-tier harness integrators with optical connector qualification capabilities and established OEM vendor codes. Long-term viability hinges on silicon photonic transceiver packaging expertise for 100-gigabit lidar-to-compute links. Watch for METI regulatory recognition spreading to European jurisdictions as inflection signal for accelerated fiber-native architecture adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Cladding | Prysmian's captive compound production sustains margin control against feedstock volatility from Japanese chemical suppliers. |
| Thailand Manufacturing Footprint Expansion | Sumitomo's Rayong assembly captures ASEAN electric vehicle platform contracts while avoiding tariff exposure to European export markets. |
| Silicon Photonic Transceiver Packaging | Corning's chip-scale optical engine development enables 100-gigabit links for California-based autonomous highway-pilot systems. |
| Optical Connector Qualification Investment | Leoni's million-cycle validation capabilities defend position in Stuttgart OEM vendor reduction programs. |
| Predictive Maintenance Service Bundling | German logistics fleets pilot fiber-health monitoring contracts that shift procurement from cost-minimization to total-cost-of-ownership frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, optical connector validation specialists, and aftermarket fleet operations managers. KBA electromagnetic compatibility certifications, METI automotive safety standard submissions, and NHTSA crash-test data integrity mandates provided regulatory trajectory inputs. Bottom-up fiber volume estimates by vehicle platform triangulated against top-down electric vehicle production forecasts.
Data-stream reconciliation across vehicle production databases, IHS Markit registration data, and supplier revenue disclosures shaped the analytical framework. Segmentation dimensions modeled include fiber type, multiplexing technology, application domain, and OEM tier. CAGRs derived from slope analysis of technology adoption curves and content-per-vehicle trajectories. Silicon photonic transceiver cost decline curves and zonal architecture penetration rates served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for copper substitution defense through active EMI cancellation would alter the outlook. Forecasts reflect assumptions about regulatory recognition timelines and electric vehicle platform launch schedules. A model refresh is warranted upon material change in METI or KBA certification protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Automotive Console Box Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Automotive Human Interface System Market