
 Satellite Launch Vehicle (SLV) Market | 2026-2036
Satellite Launch Vehicle (SLV) Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Launch Vehicle (SLV) Market Analysis
Modular payload adapter systems and ride-share bundling is repositioning buyer choice toward flexible manifest configurations rather than dedicated missions. SpaceX leverages its reusable Falcon architecture to sustain price pressure across medium-lift segments. Rocket Lab USA differentiates through vertical integration into satellite manufacturing, anchoring end-to-end customer capture. China Aerospace Science and Technology Corporation dominates domestic launch manifests through state-directed pad access and Long March production scale.
A satellite launch vehicle is a rocket system engineered to deliver payloads into specified orbital trajectories, incorporating staged propulsion architectures with thrust-to-weight ratios exceeding unity and guidance systems achieving orbital insertion precision within kilometers. Its primary purpose serves deployment of commercial, scientific, and defense satellites into low Earth, medium Earth, geostationary, or interplanetary transfer orbits. Reusable launch vehicles command expanding capital allocation as refurbishment cycles compress turnaround timelines. Small satellite launchers represent the fastest-growing payload capacity segment, driven by constellation replenishment schedules and dedicated orbit specificity that ride-share missions cannot satisfy. Expendable launch vehicles retain share in heavy and super heavy satellite categories where single-manifest reliability outweighs unit cost considerations.
FAA launch licensing governs United States commercial spaceflight operations, mandating flight safety analyses and environmental reviews that extend pre-mission timelines. ESA member state regulations under EU Space Surveillance and Tracking framework impose debris mitigation obligations affecting vehicle upper-stage design and post-mission disposal protocols. China's SAMR and military-civil fusion directives shape market access for non-domestic payload providers. Stakeholders must monitor evolving national security payload restrictions and dual-use export control classifications that determine addressable customer pools and technology transfer boundaries.
Market Dynamics
Reusable first-stage recovery systems are compressing turnaround timelines from months to weeks, forcing expendable vehicle operators to defend manifest flexibility through rapid payload integration and dedicated orbit targeting.
Growth Catalysts
- Debris Mitigation Mandates:ESA member state regulations under the EU Space Surveillance and Tracking framework now require post-mission disposal protocols. This regulatory pressure accelerates procurement of vehicles with controlled re-entry upper stages.
- Constellation Replenishment Cycles:Commercial satellite operators in low Earth orbit require launch frequency exceeding ride-share availability. Dedicated small satellite launchers capture this demand through precise orbital insertion.
- Reusable Architecture Maturation:Propulsive landing and rapid refurbishment processes reduce per-launch marginal costs. This technology shift expands addressable payload markets previously priced out of orbital access.
Market Restraints
- Launch Pad Bottlenecks:Fixed orbital launch infrastructure concentrates in coastal United States, Chinese interior sites, and French Guiana. Pad access queues extend manifest confirmation timelines.
- Specialized Engineering Labor Scarcity:Turbomachinery design and flight software verification require decade-long skill cultivation. Talent pipelines constrain production scaling for emerging vehicle developers.
- Propellant Supply Concentration:Hydrazine and nitrogen tetroxide production clusters in Russian and Chinese state-controlled facilities. Export licensing friction disrupts upper-stage propulsion sourcing.
Strategic Opportunities
- Suborbital Tourism Infrastructure:Virgin Galactic and Blue Origin have demonstrated reusable crew vehicle architectures. Derivative cargo configurations could capture microgravity research payloads.
- Indian Spaceport Expansion:Satish Dhawan Space Centre capacity additions and private launch pad licensing under IN-SPACe policy create new Eastern Hemisphere manifest options.
- In-Space Servicing Convergence:Orbital transfer vehicles combining chemical propulsion with electric thrusters enable satellite life extension. This technology pairing opens aftermarket revenue streams.
Industry Challenges
- FAA Licensing Timeline Compression:Commercial spaceflight operators face extended environmental review and flight safety analysis periods. Pre-mission regulatory clearance now exceeds vehicle integration schedules.
- Flight Heritage Requirements:Insurance underwriters and payload customers demand demonstrated success records. New entrants struggle to accumulate launch statistics against established reliability benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Launch Vehicle (SLV) Market |
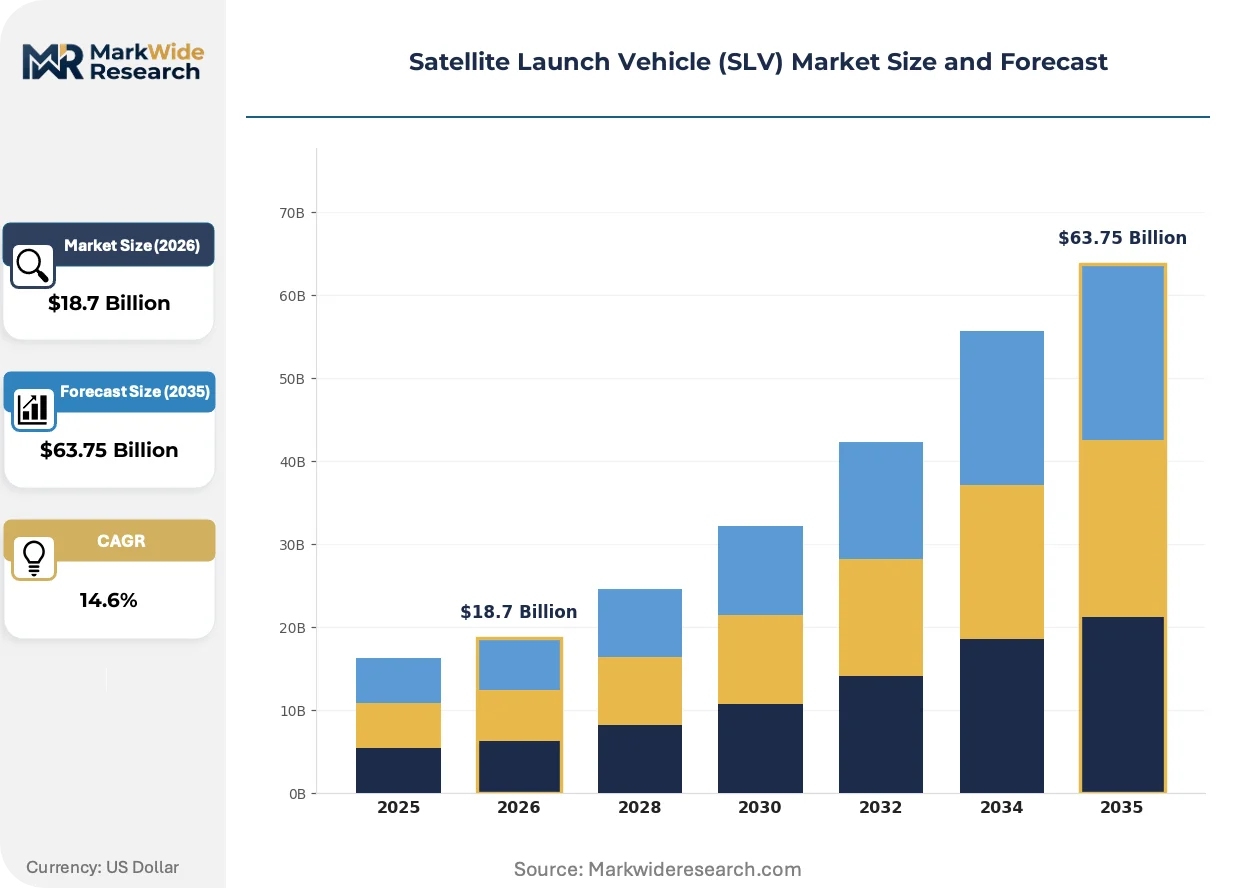
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Expendable Launch Vehicles, Reusable Launch Vehicles, Hybrid Launch Vehicles, Small Satellite Launchers Payload Capacity: Small Satellites, Medium Satellites, Heavy Satellites, Super Heavy Satellites Launch Platform: Ground-Based Launch, Sea-Based Launch, Air-Based Launch, Mobile Launch Platforms Application: Communications, Earth Observation, Scientific Research, Space Exploration |
| Companies Covered | ArianeGroup, China Aerospace Science and Technology Corporation, SpaceX, Relativity Space, Northrop Grumman Corporation, Blue Origin, United Launch Alliance, Firefly Aerospace, Rocket Lab USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Launch Vehicle (SLV) Market Emerging Trajectories
Additive manufacturing of combustion chambers and turbopump housings is compressing engine production lead times while enabling iterative design refinement between flight tests.
Propellant densification through subcooling is expanding into medium-lift vehicle configurations. SpaceX applies this process to Falcon 9 RP-1 and liquid oxygen loading, increasing mass-to-orbit margins without airframe scaling. Competitors must match this performance increment or cede commercial geostationary transfer orbit contracts.
China's SAMR and military-civil fusion directives now require domestic payload preference for Long March vehicles. This policy fragmentation forces non-Chinese satellite operators to dual-source launch procurement, splitting manifests between Chinese and Western providers to ensure schedule redundancy.
Consolidated procurement by mega-constellation operators is displacing fragmented small-satellite customer bases. SpaceX Starlink and Amazon Kuiper negotiate multi-launch blocks directly with vehicle providers, bypassing traditional manifest brokers. This buyer concentration shifts pricing power toward volume-commitment customers in the United States.
Satellite Launch Vehicle (SLV) Market Segmentation
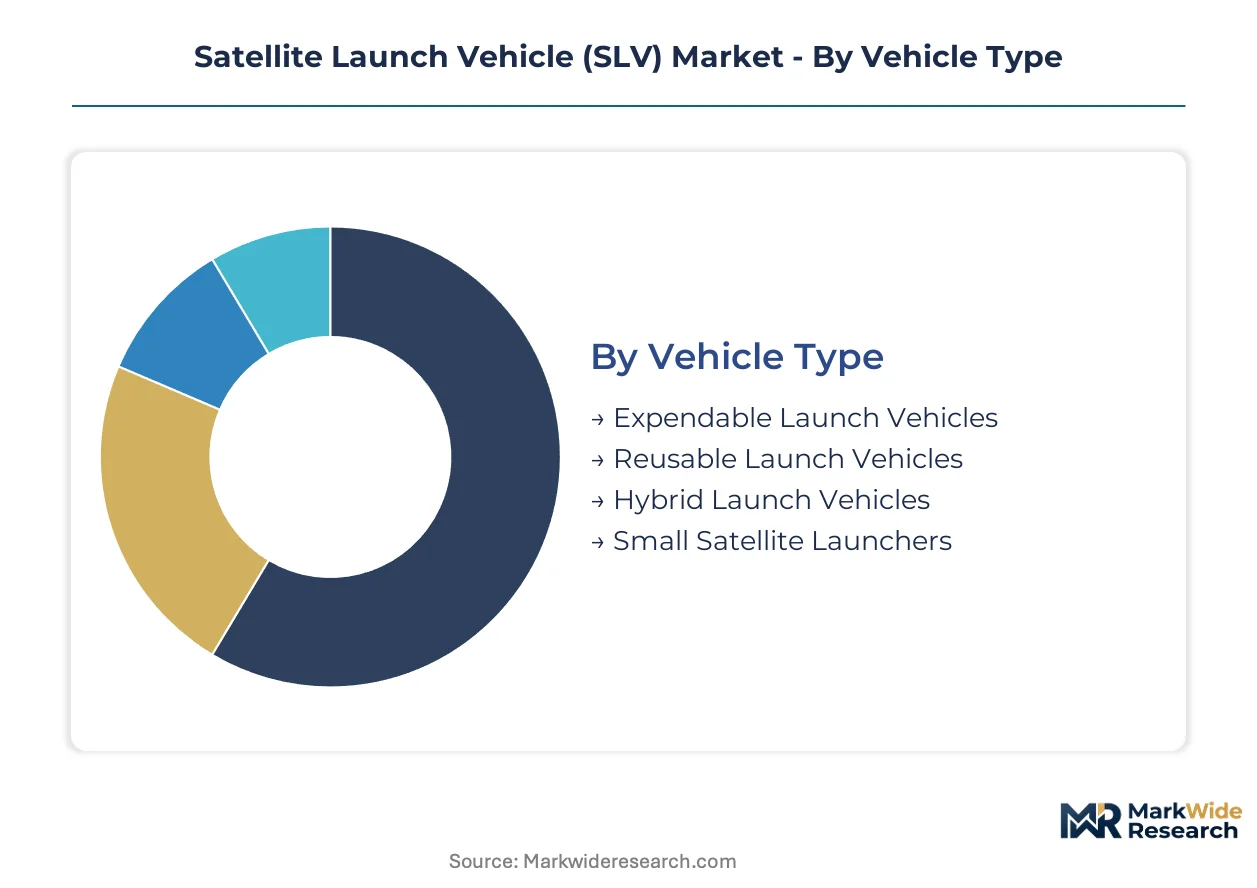
Vehicle architecture choices determine refurbishment economics and manifest flexibility. Payload capacity classifications govern insurance pricing and customer qualification criteria. Platform selection constrains orbital inclination access and range safety overhead.
Vehicle Type:
Upgrade cycles in propulsion recovery systems are compressing amortization schedules and reshaping fleet replacement decisions.
- Expendable Launch Vehicles:Single-use staged architectures with heritage flight software and proven turbomachinery. Heavy-lift demand from geostationary satellite operators in the United States and Europe concentrates here, where reliability certification outweighs unit cost optimization.
- Reusable Launch Vehicles:Propulsive landing systems enable first-stage recovery and rapid refurbishment. SpaceX Falcon and Blue Origin New Glenn architectures dominate commercial manifests as turnaround timelines compress from months to weeks.
- Hybrid Launch Vehicles:Partial recovery configurations combining expendable upper stages with reusable boosters. These systems balance development cost containment with operational cost reduction for medium-lift operators.
- Small Satellite Launchers:Dedicated light-lift vehicles optimized for constellation replenishment schedules. Rocket Lab Electron and Firefly Alpha serve commercial operators requiring precise orbital insertion unavailable through ride-share bundling.
Expendable vehicles sit at the top of the volume ranking, with reusable architectures climbing the fastest.
Payload Capacity:
Cost tier stratification separates premium heavy-lift missions from economy small-satellite access.
- Small Satellites:Under 500 kg mass class encompassing CubeSats and microsatellites. Constellation operators in low Earth orbit drive procurement volume through dedicated launchers bypassing rideshare delays.
- Medium Satellites:500 kg to 2,500 kg range serving commercial remote sensing and regional communications. This segment captures mid-tier operators seeking schedule certainty without heavy-lift premium pricing.
- Heavy Satellites:2,500 kg to 10,000 kg class dominating geostationary communications and meteorological platforms. European and Asian operators anchor demand through established reliability requirements.
- Super Heavy Satellites:Exceeding 10,000 kg for crewed spacecraft and deep-space probes. NASA Artemis and CNSA lunar missions concentrate procurement in this category where single-manifest risk tolerance is highest.
Small satellites command the steepest expansion trajectory, while heavy satellites retain the largest revenue concentration.
Launch Platform:
Geographic distribution of pad infrastructure determines customer access and regulatory jurisdiction.
- Ground-Based Launch:Fixed coastal and inland facilities with established range safety corridors. Cape Canaveral, Vandenberg, Jiuquan, and Kourou anchor global capacity through hardened infrastructure and established logistics.
- Sea-Based Launch:Ocean platforms enabling equatorial access without overflight constraints. China's Long March sea launch program and SpaceX drone ship recoveries expand operational envelopes beyond fixed sites.
- Air-Based Launch:Aircraft-carried systems for responsive insertion and inclination flexibility. Virgin Orbit's LauncherOne demonstrated this architecture before restructuring, with remaining operators pursuing defense contracts.
- Mobile Launch Platforms:Transportable systems for tactical responsiveness and contingency deployment. Military and intelligence customers in the United States prioritize these configurations for rapid reconstitution scenarios.
Ground-based platforms retain dominant share, with sea-based systems gaining fastest on flexibility advantages.
Application:
Customer type differentiation separates commercial revenue streams from government-funded development programs.
- Communications:Geostationary and low Earth orbit broadband constellation deployment. Starlink and OneWeb replenishment schedules drive recurring procurement through multi-launch agreements.
- Earth Observation:Remote sensing satellites for agriculture, defense, and climate monitoring. European Space Agency Copernicus and commercial operators in the United States anchor this demand.
- Scientific Research:Space telescopes, heliophysics probes, and microgravity platforms. NASA and ESA science directorates fund these missions through multi-year development cycles.
- Space Exploration:Crewed spacecraft, lunar landers, and interplanetary missions. Artemis program requirements and CNSA lunar ambitions concentrate super-heavy lift demand in this category.
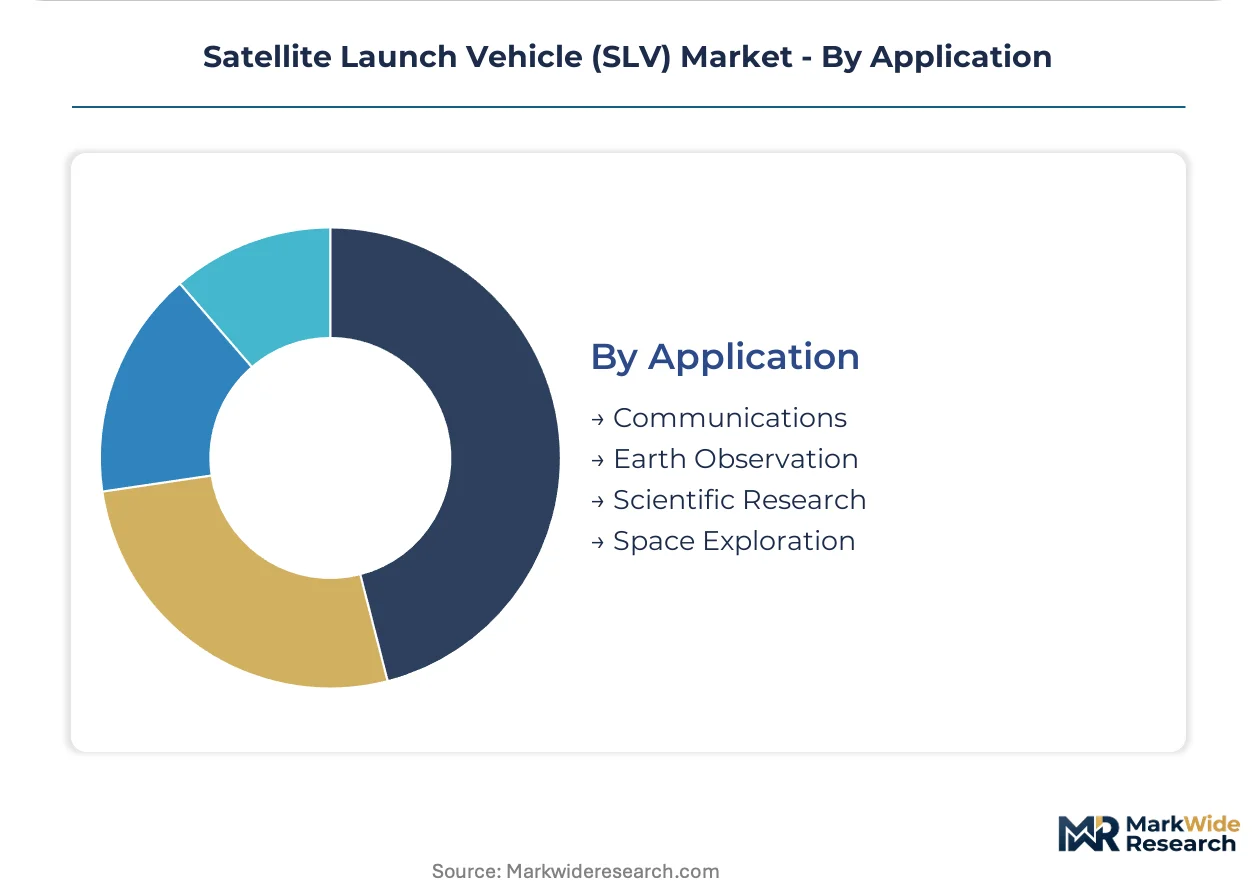
Communications applications lead by launch frequency, with space exploration expanding most quickly on Artemis and lunar program acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Satellite Launch Vehicle industry traces its commercial lineage to United States government-funded programs that transferred launch capabilities to private operators during the 1990s. This heritage established coastal launch infrastructure and regulatory frameworks that now govern orbital access economics.
United States
Cape Canaveral and Vandenberg Space Force Base process the majority of Western commercial launches, with SpaceX and United Launch Alliance anchoring manifest capacity. FAA licensing mandates flight safety analyses and environmental reviews that extend pre-mission timelines. The Texas Gulf Coast cluster near Brownsville hosts emerging private launch facilities competing for polar and equatorial trajectories.
China
Jiuquan, Taiyuan, and Xichang launch centers execute state-directed manifests through Long March vehicle families. SAMR and military-civil fusion directives require domestic payload preference, forcing foreign satellite operators to dual-source procurement. The Hainan coastal complex enables sea launch operations that expand inclination flexibility beyond inland sites.
France
Kourou's Guiana Space Centre leverages equatorial positioning for geostationary transfer orbit efficiency. ESA member state regulations under the EU Space Surveillance and Tracking framework impose debris mitigation obligations affecting vehicle upper-stage design. The Toulouse aerospace cluster concentrates satellite manufacturing integration with launch procurement decisions.
India
Satish Dhawan Space Centre capacity additions support Polar Satellite Launch Vehicle and Geosynchronous Satellite Launch Vehicle operations. IN-SPACe policy licenses private launch pads, creating Eastern Hemisphere manifest alternatives. The Bengaluru aerospace corridor houses satellite operators negotiating dedicated small launcher contracts.
Japan
Japan Aerospace Exploration Agency operates Tanegashima and Uchinoura facilities for H3 and Epsilon vehicle families. METI industrial policy coordinates domestic satellite manufacturing with launch procurement. The Nagoya manufacturing belt produces precision components for solid-fuel booster segments.
Satellite Launch Vehicle (SLV) Market Vendor Landscape
Premium-margin players sit above commodity-margin players across refurbishment cycle efficiency and manifest flexibility dimensions. The vendor base stratifies between reusable architecture operators capturing commercial frequency and expendable vehicle specialists serving heavy-lift reliability requirements. Three archetypes dominate: vertically integrated launch-service providers, state-directed aerospace conglomerates, and dedicated small-satellite launcher developers. Consolidation pressure manifests through multi-launch block negotiations and pad access exclusivity arrangements.
Within the state-directed tier, China Aerospace Science and Technology Corporation exemplifies domestic market control through pad access preference and production scale. Among Western reusable operators, SpaceX anchors commercial manifest pricing through Falcon architecture turnaround compression. Rocket Lab USA occupies a position representing dedicated small launcher specialization through vertical integration into satellite manufacturing.
| Leading Market Players |
|---|
| ArianeGroup |
| China Aerospace Science and Technology Corporation |
| SpaceX |
| Relativity Space |
| Northrop Grumman Corporation |
| Blue Origin |
| United Launch Alliance |
| Firefly Aerospace |
| Rocket Lab USA |
| Others |
Supply Flow & Price Mechanics
Mega-constellation operators negotiating multi-launch blocks command volume-discount leverage that compresses per-kilogram pricing across medium-lift segments. This buyer concentration forces vehicle providers toward performance-tier differentiation rather than commodity rate cards.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates flight-proven heavy-lift missions from rapid-turnaround reusable services and dedicated small-satellite access. Price differentiation hinges on demonstrated flight heritage and payload integration speed, with constellation operators exhibiting highest price sensitivity while government science missions tolerate premium reliability tariffs. Cost compression in small-lift segments is intensifying because Rocket Lab and Firefly Aerospace compete for dedicated manifest slots previously captured by ride-share bundling.
Supply Chain Analysis
First-stage refurbishment flows and upper-stage recovery logistics now dominate operational planning as reusable architectures extend component life cycles. Turbomachinery production concentrates in the United States, France, and China, with propellant sourcing drawing from Russian and Chinese state-controlled hydrazine facilities. Supply chain risk centers on export licensing friction for nitrogen tetroxide oxidizer. Distribution runs through vertically integrated launch service providers controlling pad access and payload integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on reusable architecture maturation collapsing refurbishment costs below expendable vehicle production economics.
For Market Incumbents: To counter emerging small-launcher specialization, SpaceX and United Launch Alliance should deepen captive control over satellite manufacturing through backward integration partnerships, while securing exclusive pad access agreements at Cape Canaveral and Vandenberg to constrain competitor manifest availability. For New Entrants and Emerging Players: Capture underserved demand from defense and intelligence customers requiring mobile launch platforms for rapid reconstitution scenarios, targeting the United States Eastern Seaboard where fixed-pad congestion creates schedule vulnerability for traditional providers. For Investors and Strategic Acquirers: Defense primes with space portfolio gaps are the most active acquirer in this space, seeking flight heritage assets over development-stage vehicles. Long-term viability favors targets with demonstrated reusable recovery and suborbital tourism derivative potential. Monitor FAA licensing timeline compression as inflection indicator for regulatory risk accumulation.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Architecture Scale-Up | SpaceX Falcon turnaround compression forces competitors to match refurbishment economics or cede commercial manifests. |
| Vertical Integration into Satellite Manufacturing | Rocket Lab's in-house spacecraft production locks in end-to-end customer capture and recurring launch demand. |
| Private Launch Pad Licensing | IN-SPACe policy in India creates Eastern Hemisphere capacity alternatives outside Chinese state-directed access. |
| Propellant Supply Agreement | Long-term oxidizer contracts with non-Russian sources mitigate export licensing disruption for upper-stage propulsion. |
| Suborbital Tourism Infrastructure | Blue Origin and Virgin Galactic crew vehicle derivatives capture microgravity research payloads adjacent to orbital markets. |
Methodological Framework
Direct dialogue with launch service executives, satellite constellation procurement leads, FAA licensing officers, and propulsion engineering directors grounds qualitative assessment in operational reality. Secondary validation draws from FAA launch license databases, ESA debris mitigation filings, SEC 10-K disclosures from publicly traded space companies, and customs records for propellant component trade flows. Bottom-up manifest frequency analysis triangulates against top-down payload mass-to-orbit estimates across vehicle classes.
Bottom-up modeling builds from individual launch provider manifest announcements and payload integration timelines, while top-down verification cross-checks against national space agency budget allocations and commercial constellation deployment schedules. Segmentation dimensions include vehicle architecture type, payload capacity tier, launch platform configuration, and application vertical. CAGRs derive from trajectory fitting across disclosed launch cadence targets and pad capacity expansion plans, with propellant cost curves and refurbishment cycle assumptions as key sensitivity inputs.
Underlying measurement precision varies by segment; reusable vehicle economics and small-satellite launcher order backlogs carry tighter precision than emerging sea-launch and mobile platform categories where operational data remains sparse. Forecasts reflect documented assumptions regarding regulatory clearance timelines and propellant supply continuity. Practitioners should monitor FAA environmental review duration, ESA debris rule enforcement intensity, and Chinese SAMR payload preference implementation for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Israel Satellite Imagery Services Market
Satellite
Satellite Sensor Market
Satellite
Cubesat Market
Satellite
Global Small Satellite Service Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Israel Satellite Communications Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
Reconnaissance Satellite Market
Satellite
Advanced Satellite Market
Satellite
Satellite Internet Market
Satellite
ASEAN Satellite-Based Earth Observation Market