
 Israel Satellite Imagery Services Market | 2026-2036
Israel Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Satellite Imagery Services Market Insights
Direct government procurement channels is reconfiguring how satellite imagery flows into Israeli end-user organizations. ImageSat International N.V. anchors domestic supply through its indigenous constellation capabilities. Maxar Technologies competes via high-resolution optical archives and allied government relationships. Planet Labs extends daily coverage cadence for agricultural and environmental monitoring clients.
Satellite imagery services encompass the capture, processing, analysis, and distribution of geospatial data acquired from Earth-observation platforms operating at altitudes typically between 400 and 36,000 kilometers, with spatial resolutions ranging from sub-meter to tens of meters depending on sensor payload and orbital parameters. These services convert raw sensor data into actionable intelligence for mapping, surveillance, resource management, and infrastructure planning across civilian and military domains. Defense applications dominate current revenue pools given classified mission requirements and sovereign data sensitivity, while environmental monitoring represents the fastest-expanding segment as climate adaptation planning intensifies. Data analytics services command premium pricing where machine-learning classification and change-detection algorithms transform raw pixels into decision-ready outputs.
Israel's Ministry of Defense and the Israel Space Agency shape market access through security clearance requirements and foreign ownership restrictions on sensitive geospatial products. The country's national space regulator enforces orbital debris mitigation and frequency coordination standards that constrain operator licensing timelines. Stakeholders must monitor evolving encryption mandates and data residency rules that could bifurcate domestic and foreign supplier participation.
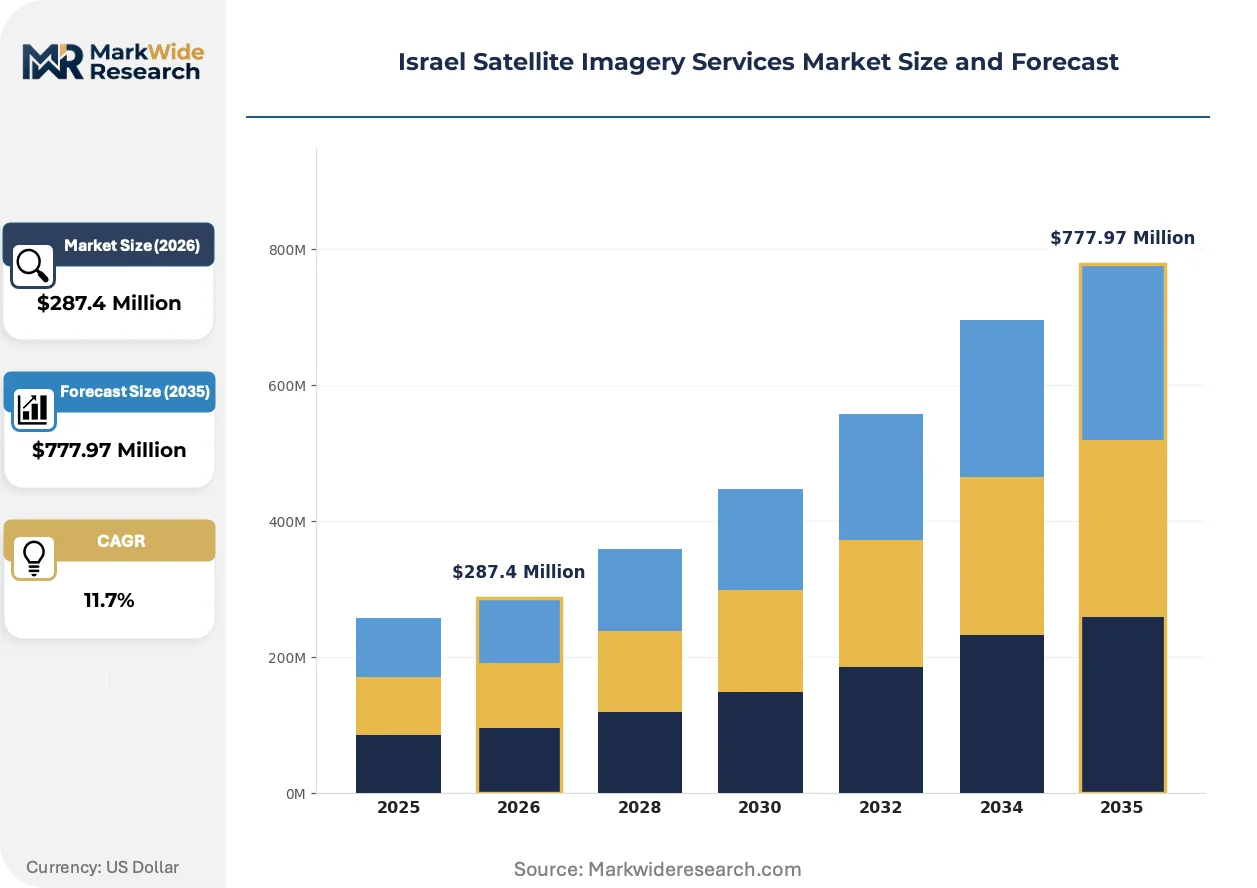
Market Dynamics
Israel's satellite imagery services sector is reconfiguring around sovereign data requirements as the Ministry of Defense tightens security clearance frameworks for foreign-sourced geospatial intelligence. This structural shift is compressing procurement timelines for domestic operators while elevating compliance costs for international suppliers.
Growth Catalysts
- Defense procurement frameworks:The Israel Space Agency and Ministry of Defense are expanding classified mission requirements for indigenous geospatial products. Sovereign data sensitivity is accelerating domestic constellation deployment.
- Tel Aviv metropolitan demand:Central district defense contractors and homeland security agencies are consolidating imagery acquisition through direct government channels. Geographic concentration around intelligence hubs is pulling specialized analytics services.
- Climate adaptation mandates:Agricultural monitoring and environmental planning applications are expanding satellite coverage cadence requirements. Machine-learning classification tools are transforming raw sensor data into decision-ready outputs for water resource management.
Market Restraints
- Foreign ownership restrictions:Security clearance requirements on sensitive geospatial products create structural barriers for non-Israeli operators. The national space regulator enforces data residency rules that bifurcate supplier participation.
- Orbital licensing timelines:Frequency coordination and debris mitigation standards constrain operator authorization cycles. Satellite payload deployment schedules face regulatory friction from the national space regulator.
- Optical sensor limitations:Sub-meter resolution capabilities remain concentrated among select constellation operators. Cloud cover and nighttime acquisition gaps restrict all-weather surveillance applications.
Strategic Opportunities
- Negev Desert agricultural corridors:Southern district irrigation and crop monitoring applications remain underpenetrated for daily coverage services. Precision agriculture operators seek expanded spectral analysis for drought management.
- Dual-use technology convergence:Synthetic aperture radar and hyperspectral imaging integration is opening synthetic aperture radar applications through civilian environmental monitoring channels.
- Encryption mandate tailwinds:Evolving data transmission security requirements are creating procurement preferences for domestic encryption-certified operators. The Ministry of Defense procurement frameworks favor end-to-end sovereign supply chains.
Industry Challenges
- Geospatial intelligence analyst shortage:Specialized skill gaps in machine-learning change-detection algorithm development are compressing talent availability. Defense contractors compete with commercial analytics firms for cleared personnel.
- Legacy system integration friction:Existing ground station infrastructure requires costly upgrades to process next-generation sensor data formats. Military command systems face interoperability barriers with commercial satellite feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Satellite Imagery Services Market |
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $777.97 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Urban Planning, Defense, Environmental Monitoring Service Type: Data Analytics, Image Processing, Consulting, Custom Solutions Technology: Optical Imaging, Synthetic Aperture Radar, Multispectral, Hyperspectral End User: Government, Commercial Enterprises, Research Institutions, NGOs |
| Companies Covered | ImageSat International N.V., Maxar Technologies, Planet Labs, Airbus Group, L3 Harris Corporation, ESRI, Ofek Aerial Photography, Trimble Navigation, Google LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Satellite Imagery Services Market Trends and Innovations
Virtualized ground segment architectures are displacing hardware-dependent processing chains across Israeli satellite imagery workflows. This infrastructure evolution is compressing data latency while enabling scalable analytics deployment.
Cloud-native processing pipelines are virtualizing traditional ground station functions through software-defined radio and containerized data workflows. Israeli defense agencies and agricultural monitoring clients are adopting these architectures at accelerated procurement cycles. The technology is virtualizing capital-intensive infrastructure requirements, enabling smaller operators to compete on analytics sophistication rather than hardware ownership.
The Israel Space Agency is enforcing updated encryption mandates and data residency certifications that reshape supplier qualification pathways. Industrial consequence includes mandatory domestic ground station presence for classified contract eligibility. Defense and homeland security segments are responding through joint ventures with indigenous constellation operators to maintain clearance eligibility.
Subscription-based imagery access is displacing traditional per-scene procurement across Israeli environmental monitoring and agricultural sectors. Research institutions and regional water authorities are consolidating purchasing through platform-as-a-service models rather than direct satellite tasking. This behavioral shift is most visible in central district agricultural cooperatives seeking predictable cost structures for seasonal monitoring campaigns.
Israel Satellite Imagery Services Market Segmentation
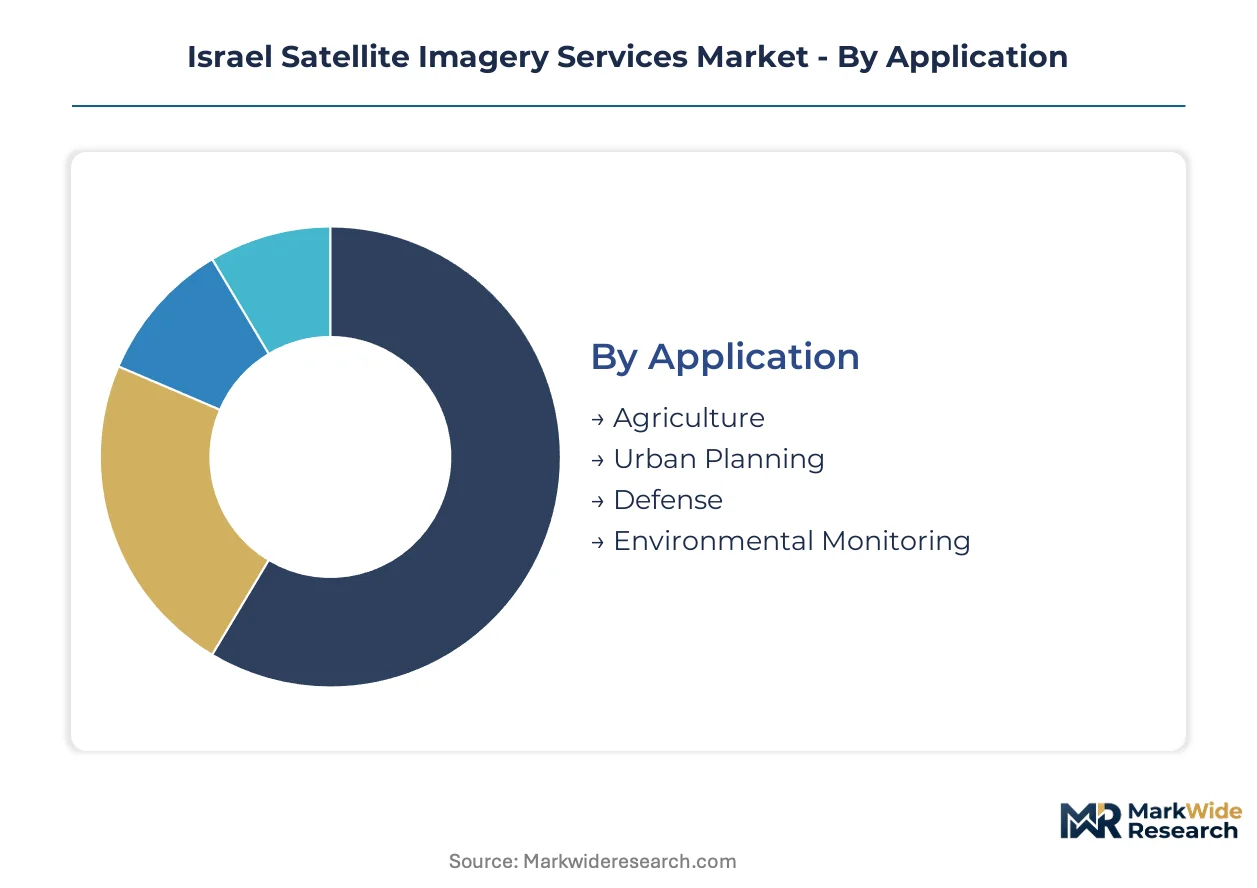
Israel's satellite imagery services market fragments across four intersecting dimensions that determine procurement velocity and contract structure. Application and end-user categories exhibit the widest divergence in sales cycle duration, while technology and service type segments stratify by margin profile and technical complexity.
Application:
Defense contracts turn over on classified procurement timelines measured in quarters, while agricultural monitoring subscriptions renew on annual cycles with minimal friction.
- Defense:Classified mission requirements drive sovereign data sensitivity protocols. The Israel Ministry of Defense and intelligence agencies around Tel Aviv concentrate procurement through direct government channels with stringent security clearance frameworks.
- Environmental Monitoring:Climate adaptation mandates from the Israel Space Agency are accelerating coverage cadence requirements for water resource management. Regional authorities in the central district and Negev Desert are consolidating machine-learning classification tools for drought surveillance.
- Agriculture:Precision irrigation operators seek expanded spectral analysis for crop health monitoring.
- Urban Planning:Municipal infrastructure mapping applications leverage sub-meter resolution archives for development compliance.
Defense anchors the volume base while Environmental Monitoring gains share at the steepest rate.
Service Type:
Cost tiers separate commoditized processing from premium analytics, with consulting engagements commanding the highest per-hour rates but lowest repeat velocity.
- Data Analytics:Machine-learning change-detection algorithms transform raw pixels into decision-ready outputs for defense and agricultural clients. The Israel Space Agency's encryption mandates are creating procurement preferences for domestic-certified analytics operators.
- Custom Solutions:Bespoke integration with legacy military command systems requires specialized engineering talent. Defense contractors in Tel Aviv compete with commercial firms for cleared personnel capable of ground station infrastructure upgrades.
- Image Processing:Cloud-native pipelines virtualize traditional ground station functions through software-defined radio workflows.
- Consulting:Advisory services around regulatory compliance and orbital licensing navigate the national space regulator's debris mitigation standards.
Data Analytics commands the highest margin tier while Custom Solutions expand most quickly through defense procurement frameworks.
Technology:
Volume concentration favors mature optical platforms, though synthetic aperture radar is climbing fastest as all-weather requirements intensify.
- Optical Imaging:Sub-meter resolution capabilities remain concentrated among select constellation operators. Cloud cover and nighttime acquisition gaps restrict surveillance applications for defense agencies requiring persistent coverage.
- Synthetic Aperture Radar:All-weather penetration and nighttime acquisition capability address critical gaps in optical sensor performance. Dual-use convergence through civilian environmental monitoring channels is opening procurement pathways previously restricted to classified budgets.
- Multispectral:Agricultural monitoring applications leverage vegetation index calculations for irrigation optimization.
- Hyperspectral:Mineral detection and pollution tracking applications serve research institutions and environmental agencies.
Optical Imaging anchors the volume base while Synthetic Aperture Radar gains share at the steepest rate.
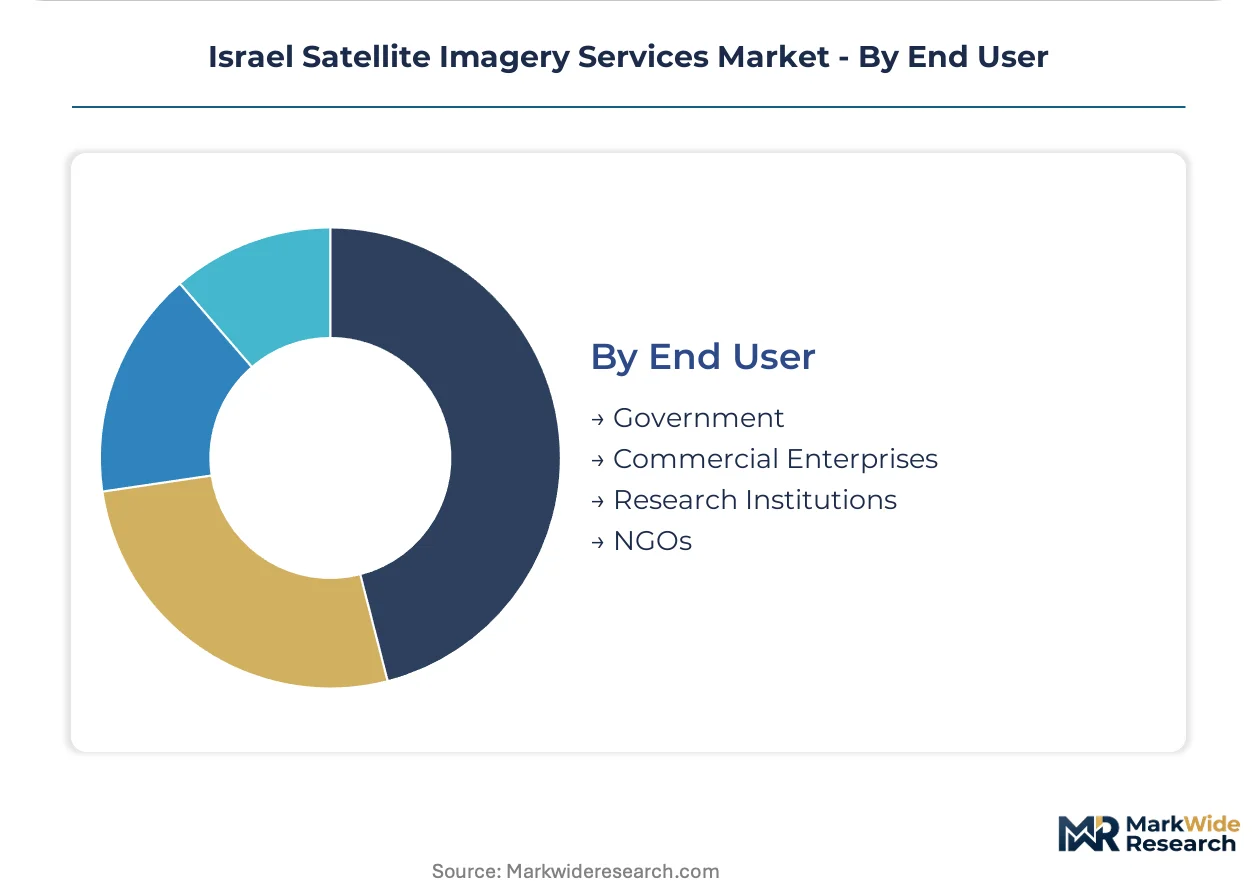
End User:
Customer type determines data residency requirements and encryption certification burdens, with government contracts imposing the most stringent sovereign supply chain mandates.
- Government:The Israel Ministry of Defense and homeland security agencies enforce end-to-end sovereign supply chain requirements. Procurement frameworks favor domestic constellation operators with ground station presence and security clearance eligibility.
- Commercial Enterprises:Agricultural cooperatives and infrastructure developers seek predictable cost structures through subscription-based platform access. Central district enterprises are consolidating purchasing through platform-as-a-service models rather than direct satellite tasking.
- Research Institutions:Academic environmental monitoring programs access archived imagery for climate adaptation studies.
- NGOs:Humanitarian and conservation organizations leverage commercial pricing tiers for regional surveillance campaigns.
Government anchors the volume base while Commercial Enterprises expand most quickly through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Tel Aviv's defense corridor while procurement velocity lags in peripheral districts. The central district commands premium analytics rates through sovereign data mandates. Southern and northern sub-regions face infrastructure gaps that compress service margins.
Tel Aviv Metropolitan Area
Defense contractors and homeland security agencies cluster around intelligence hubs in Tel Aviv and Ramat Gan. The Israel Space Agency enforces security clearance frameworks that favor domestic operators with ground station presence. Procurement frameworks concentrate classified geospatial contracts through direct government channels in this corridor.
Central District
Research institutions and agricultural cooperatives drive environmental monitoring demand across Rehovot and Petah Tikva. The Ministry of Agriculture's climate adaptation mandates accelerate coverage cadence requirements for water resource management. Machine-learning classification tools transform raw sensor data into decision-ready outputs for regional irrigation authorities.
Southern District
Negev Desert agricultural corridors remain underpenetrated for daily coverage services despite precision irrigation expansion. The national space regulator's frequency coordination standards constrain operator licensing timelines for new ground station deployments. Beersheba-area defense research facilities pull specialized synthetic aperture radar applications through dual-use technology channels.
Haifa Bay Area
Port infrastructure and maritime surveillance applications anchor commercial demand in Israel's northern coastal zone. The Ministry of Defense procurement frameworks classify offshore monitoring requirements under sovereign data sensitivity protocols. Industrial concentration around Haifa's technology park supports specialized analytics service providers.
Jerusalem Corridor
Government administration and policy institutions shape regulatory enforcement patterns affecting nationwide market access. The national space regulator's updated encryption mandates and data residency certifications reshape supplier qualification pathways. Eastward infrastructure connections face terrain limitations that elevate transmission costs for real-time imagery services.
Israel Satellite Imagery Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the analytics and processing layers. The vendor base stratifies between indigenous constellation operators with security clearance eligibility and international suppliers competing through high-resolution archives and allied government relationships. Three archetypes dominate: sovereign-data-certified domestic platforms, foreign high-resolution specialists, and cloud-native analytics providers. Competitive moves concentrate on joint ventures for clearance eligibility and subscription model expansion for agricultural segments.
Among domestic constellation operators, ImageSat International N.V. occupies a position exemplifying sovereign supply chain integration. Maxar Technologies and Planet Labs represent international suppliers navigating the Ministry of Defense's tightening security clearance frameworks. These three anchors illustrate the structural tension between indigenous data sovereignty requirements and foreign technical capabilities.
| Leading Market Players |
|---|
| ImageSat International N.V. |
| Maxar Technologies |
| Planet Labs |
| Airbus Group |
| L3 Harris Corporation |
| ESRI |
| Ofek Aerial Photography |
| Trimble Navigation |
| Google LLC |
| Others |
Pricing and Supply Chain Analysis
The Haifa Bay maritime corridor's encryption-certified logistics costs compress margins for foreign-sourced sensor components while amplifying price premiums for domestic ground station operators serving Tel Aviv defense contractors. This freight-cost asymmetry reinforces a bifurcated pricing architecture where sovereign supply chain compliance commands substantial premiums over standard commercial imagery tiers.
Pricing Analysis
The customization-premium spread separates standard subscription access from configured-to-order tasking services across Israeli satellite imagery procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by security clearance certification and ground station proximity, with Ministry of Defense contracts occupying the premium tier. Cost compression in standard agricultural monitoring subscriptions is intensifying because Planet Labs and similar providers are expanding daily coverage cadence without corresponding price increases. Commercial agricultural cooperatives in the central district exhibit highest price sensitivity, while defense agencies demonstrate lowest sensitivity due to sovereign data mandates.
Supply Chain Analysis
Tariff exposure between United States and China dominates component sourcing risk for optical sensor payloads and ground station electronics entering Israeli satellite imagery workflows. Supply concentration rests on United States, France, and Israel for high-resolution optical components, synthetic aperture radar subsystems, and encryption-certified data processors respectively. Single-source vulnerability persists in sub-meter resolution sensor arrays where Maxar Technologies and Airbus Group control limited qualified supplier pools. Distribution runs through direct government procurement channels for defense segments and platform-as-a-service aggregators for agricultural and environmental monitoring clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent scarcity in machine-learning geospatial analytics and security-cleared engineering disciplines constrains expansion velocity for all market participants. The gap between defense contractor compensation and commercial firm salaries compresses available human capital for non-cleared operations.
For Market Incumbents: Entrench sovereign supply chain positioning through joint ventures with ImageSat International N.V. to maintain Ministry of Defense clearance eligibility against emerging foreign competitors. Expand backward integration into domestic ground station infrastructure to satisfy the Israel Space Agency's evolving data residency certifications and encryption mandates. For New Entrants and Emerging Players: Pursue Negev Desert agricultural corridors where daily coverage services remain underpenetrated despite precision irrigation expansion. Target commercial agricultural cooperatives through subscription-based platform access with predictable cost structures, bypassing direct government procurement barriers entirely. For Investors and Strategic Acquirers: The Israel Space Agency's updated encryption mandates reshape the acquisition landscape toward domestic-certified analytics operators with end-to-end sovereign supply chains. Long-term viability centers on platforms capable of serving dual-use defense and environmental monitoring applications through civilian procurement channels. The signal to monitor is Ministry of Defense procurement framework revisions that could accelerate domestic operator consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Ground Station Expansion | Israel Space Agency encryption mandates require physical infrastructure presence for classified contract eligibility. |
| Synthetic Aperture Radar Integration | All-weather capability addresses optical sensor limitations for defense agencies requiring persistent coverage. |
| Machine-Learning Analytics Partnership | Change-detection algorithm development compresses talent scarcity gaps in geospatial intelligence. |
| Subscription Model Migration | Agricultural cooperatives in central district consolidate purchasing through platform-as-a-service structures. |
| Dual-Use Technology Certification | Civilian environmental monitoring channels open procurement pathways for previously classified synthetic aperture radar applications. |
Research Methodology
Cross-validation between regulatory filing analysis and operator licensing records anchors the qualitative findings on market access constraints. Primary interviews with satellite imagery procurement officers at Israeli defense contractors, geospatial intelligence analysts at homeland security agencies, agricultural monitoring specialists at regional water authorities, and ground station infrastructure engineers informed demand-side dynamics. Secondary validation drew from Israel Space Agency licensing databases, Ministry of Defense procurement framework disclosures, national space regulator orbital debris mitigation filings, and customs records for sensor component imports. Bottom-up segmentation modeling and top-down macroeconomic anchoring ensured triangulation consistency.
Calibration against historical contract award patterns and subscription renewal rates refined the analytical framework across the projection horizon. Segmentation dimensions modeled include application category, service type tier, technology platform, and end-user organization type with security clearance status. CAGRs were derived from fitted growth curves applied to disclosed contract values and estimated subscription volumes. Industry-specific forecast inputs incorporated the Israel Space Agency's orbital licensing timeline assumptions and Ministry of Defense procurement cycle patterns for classified geospatial products.
Sensitivities concentrate around regulatory timeline shifts for encryption mandate enforcement and potential revisions to foreign ownership restrictions on sensitive geospatial products. Forecasts reflect documented assumptions on sovereign data sensitivity protocols and domestic operator capacity expansion schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Indonesia Satellite Communications Market
Satellite
Satellite Broadband Market
Satellite
M2M Satellite Communication Market
Satellite
GEO Satellite Market
Satellite
Broadband Satellite System Market
Satellite
Global Remote Sensing Services Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Global Satellite Propulsion System Market
Satellite
Italy Satellite Communication Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Satellite Internet Market
Satellite
ASEAN Satellite Communications Market
Satellite
Global Enterprise VSAT System Market
Satellite
High-Throughput Satellite Market
Satellite
Optical Satellite Communication Market