
 Asia-Pacific Armored Fighting Vehicles Market | 2026-2036
Asia-Pacific Armored Fighting Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Armored Fighting Vehicles Market Outlook
Defense procurement channels across Southeast Asia and Oceania are reconfiguring as governments shift from direct imports to licensed production and technology transfer agreements. Mitsubishi Heavy Industries anchors Japan's indigenous armored vehicle ecosystem through sustained investment in amphibious assault platforms. Hanwha Defense leverages its K21 and AS21 Redback offerings to compete for Australia's Land 400 Phase 3 contract, while Tata Motors specializes in cost-optimized armored solutions for India's paramilitary and army requirements.
Asia-Pacific armored fighting vehicles encompass tracked and wheeled platforms engineered with composite armor arrays, powerpacks exceeding 1,000 horsepower, and digitized battlefield management architectures designed for force protection and maneuver warfare in littoral and high-altitude terrain. Main battle tanks retain the largest installed base across the region, though active protection systems represent the fastest-growing technology segment as legacy platforms face anti-tank guided missile proliferation. Infantry fighting vehicles command premium pricing where C4ISR integration and unmanned turret configurations define competitive bids.
Japan's Ministry of Economy, Trade and Industry coordinates defense production licensing under the Three Principles on Transfer of Defense Equipment, while Australia's Defence Export Controls regulate technology sharing with regional partners. India's Defence Acquisition Procedure mandates progressively higher indigenous content thresholds, reshaping supplier relationships and local joint venture structures. Stakeholders must weigh technology sovereignty commitments against platform interoperability standards as regional security architectures evolve.
Market Dynamics
Active protection systems are compressing upgrade cycles across legacy armored platforms as militaries confront anti-tank guided missile proliferation in contested littoral and high-altitude theaters.
Growth Catalysts
- India's Defence Acquisition Procedure:Indigenous content thresholds now mandate progressive localization, forcing foreign OEMs into joint ventures with domestic partners and expanding local manufacturing capacity for armored hulls and powerpacks.
- Amphibious assault modernization:Japan's Self-Defense Forces prioritize island defense platforms, generating sustained procurement for tracked and wheeled vehicles with swim capability and naval integration.
- Composite armor arrays:Ceramic-metallic laminates and reactive tile systems are displacing homogeneous steel across retrofit programs, extending platform service life by fifteen to twenty years.
Market Restraints
- Powerpack supply concentration:Diesel engine and transmission integration for vehicles exceeding fifty tonnes relies on a narrow supplier base concentrated in Germany and the United States, creating delivery bottlenecks.
- Technical limitation:Active protection system radar signatures remain detectable by electronic warfare suites, forcing trade-offs between hard-kill effectiveness and electromagnetic survivability.
- Regulatory friction:Australia's Defence Export Controls impose technology-sharing restrictions that complicate regional maintenance networks and spare-part logistics for platforms with foreign subsystem content.
Strategic Opportunities
- Underpenetrated geography:Vietnam's mechanized infantry expansion lacks domestic armored vehicle production, creating openings for licensed assembly partnerships with technology transfer provisions.
- Regulatory tailwind:Japan's Three Principles on Transfer of Defense Equipment now permit equipment exports to aligned nations, unlocking Southeast Asian markets previously closed to Japanese platforms.
- Technology convergence:Unmanned turret architectures combined with AI-assisted target recognition are enabling crew size reduction and platform weight optimization for air-transportable configurations.
Industry Challenges
- Skill gap in systems integration:C4ISR architecture implementation for digitized battlefield management requires software engineers and network specialists scarce in traditional defense industrial bases.
- Certification timeline compression:Australia's Land 400 Phase 3 evaluation schedule demands concurrent testing of mobility, protection, and lethality systems, straining validation resources.
- Legacy platform interoperability:Retrofitted active protection systems must interface with analog fire-control computers and mechanical turret drives, complicating software-hardware integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Armored Fighting Vehicles Market |
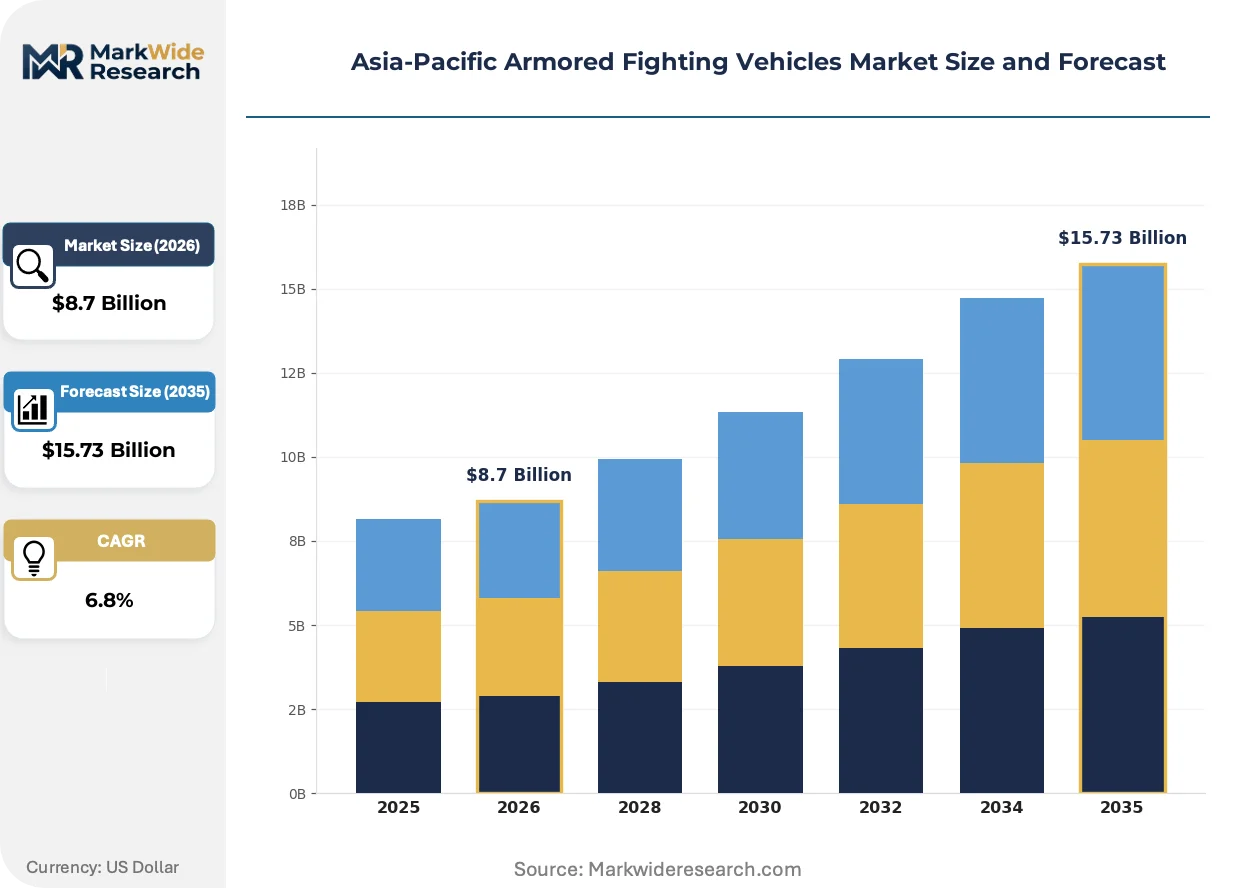
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Armored Vehicles, Main Battle Tanks, Infantry Fighting Vehicles, Armored Personnel Carriers End User: Military Forces, Law Enforcement, Private Security, Government Deployment: Onshore, Offshore, Joint Operations, Peacekeeping Missions Technology: Active Protection Systems, C4ISR, Fire Control Systems, Autonomous Systems |
| Companies Covered | General Dynamics Corporation, Rheinmetall AG, BAE Systems plc, JSC Rosoboronexport (Rostec State Corporation), Mitsubishi Heavy Industries, Ltd., Hanwha Defense, Krauss-Maffei Wegmann GmbH & Co. KG, Tata Motors Limited, FNSS Savunma Sistemleri AŞ, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Armored Fighting Vehicles Market Strategic Shifts
Platform architectures are converging around modular armor kits and open electronic standards that permit rapid reconfiguration between peacekeeping, counter-insurgency, and high-intensity conflict roles.
Integrated battlefield management systems are digitizing crew situational awareness by fusing sensor feeds from unmanned aerial vehicles, adjacent vehicles, and satellite constellations into unified tactical displays. Mechanized infantry units in Australia and India are fielding these systems at brigade scale during live-fire evaluations. This convergence is digitizing command-and-control latency, compressing sensor-to-shooter timelines from minutes to seconds.
Japan's Ministry of Economy, Trade and Industry now interprets defense equipment export licensing under relaxed Three Principles guidelines, enabling technology transfer to Southeast Asian partners previously restricted. Industrial consequence includes Mitsubishi Heavy Industries establishing maintenance partnerships in Indonesia and the Philippines. Amphibious assault vehicle segments are responding fastest, with regional navies prioritizing platforms compatible with Japanese dock landing ships.
Force structure reviews across Southeast Asia are unbundling platform acquisition from through-life support contracts, with militaries negotiating separate maintenance and upgrade agreements. Original equipment manufacturers face margin compression as state-owned depots and third-party maintainers capture sustainment revenue. This pattern is most visible in India's armored modernization programs, where Ordnance Factory Board facilities now compete with foreign OEMs for overhaul contracts.
Asia-Pacific Armored Fighting Vehicles Market Segmentation
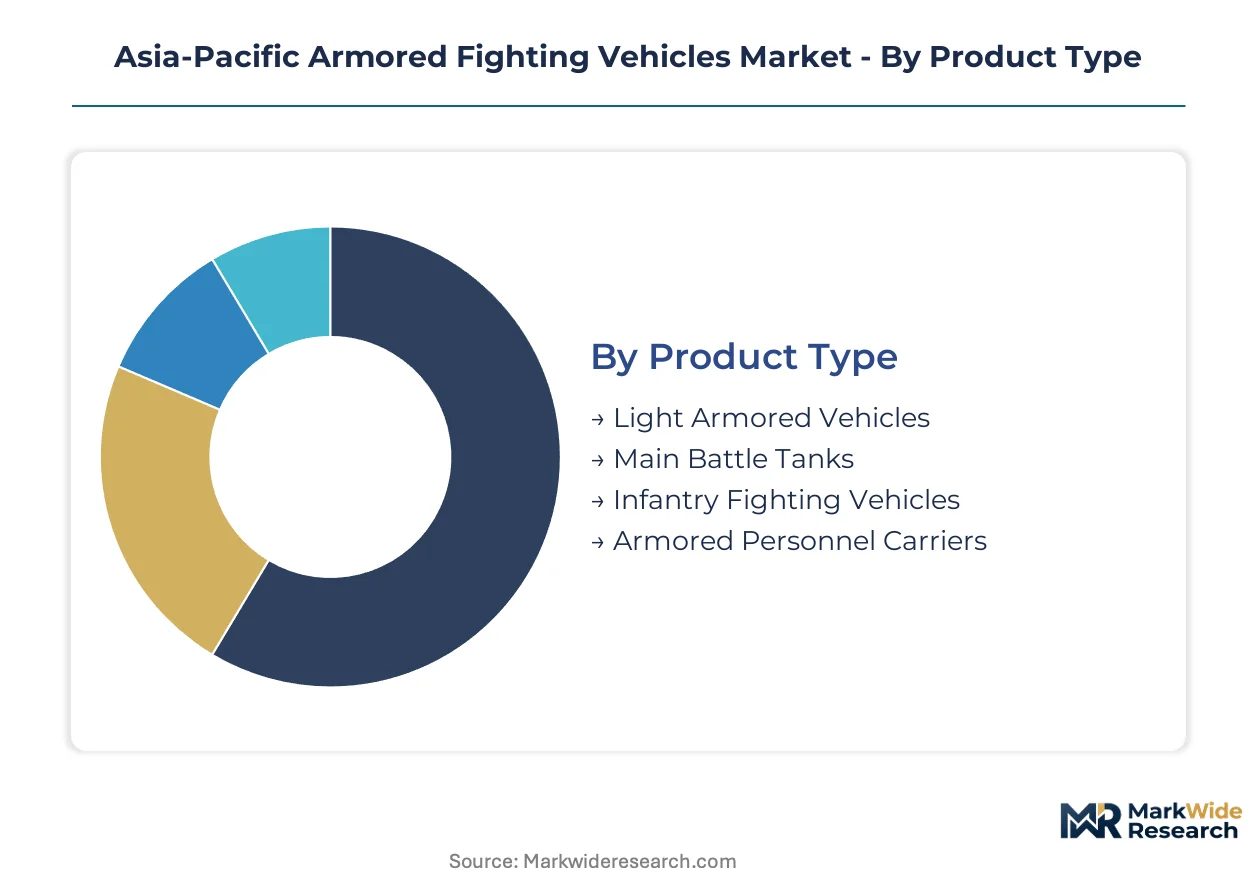
Segmentation reveals how procurement cycles diverge across platform types and operational roles. Military modernization programs favor technology-intensive configurations while paramilitary users prioritize cost-optimized hulls. Understanding these fault lines clarifies where upgrade spending concentrates versus where replacement demand dominates.
Product Type:
Platform life cycles stretch from fifteen years for light reconnaissance vehicles to forty years for heavy tracked systems, creating divergent revenue timing across segments.
- Main Battle Tanks:Tracked platforms exceeding fifty tonnes with composite armor arrays and 120mm smoothbore cannons. India's armored modernization programs drive the largest retrofit contracts as legacy T-72 fleets receive active protection systems and thermal imagers.
- Infantry Fighting Vehicles:Mechanized platforms carrying dismount squads behind autocannon-armed unmanned turrets. Australia's Land 400 Phase 3 acquisition concentrates demand for amphibious-capable wheeled variants with integrated battlefield management systems.
- Armored Personnel Carriers:Protected mobility solutions for troop transport in medium-threat environments. Southeast Asian peacekeeping contingents favor these for United Nations deployment rotations.
- Light Armored Vehicles:Wheeled reconnaissance and patrol platforms under twenty tonnes. Law enforcement agencies across the region procure these for counter-insurgency and border security operations.
Main Battle Tanks anchors the volume base while Infantry Fighting Vehicles gains share at the steepest rate.
End User:
Customer procurement authority shapes contract structures, with military acquisitions favoring multi-year framework agreements and civilian agencies preferring single-lot competitive tenders.
- Military Forces:National army and marine corps units operating tracked and wheeled platforms in combined arms formations. India's Defence Acquisition Procedure mandates indigenous content thresholds that reshape supplier relationships for these buyers.
- Law Enforcement:Paramilitary police and border guard units requiring protected mobility for internal security. These organizations prioritize cost-per-kilometer metrics over armor thickness in platform selection.
- Private Security:Commercial firms protecting critical infrastructure and convoy operations. Demand concentrates in mining and energy corridors across Indonesia and Papua New Guinea.
- Government:Civil defense and disaster response agencies operating specialized variants. Japan's Self-Defense Forces coordinate amphibious assault vehicle procurement through this channel for island defense scenarios.
Military Forces dominates absolute spending while Law Enforcement expands most quickly as internal security budgets outpace conventional defense growth.
Deployment:
Operational environment dictates protection level requirements, with littoral and high-altitude theaters demanding specialized mobility and climate resilience specifications.
- Onshore:Land-based maneuver operations across desert, jungle, and urban terrain. India's mechanized corps conducts the largest concentration of these deployments along contested border regions.
- Offshore:Amphibious assault and ship-to-shore movements requiring swim capability. Japan's island defense priorities generate sustained procurement for tracked vehicles compatible with naval landing craft.
- Joint Operations:Combined arms coordination between armor, infantry, and aviation branches. Australia's brigade modernization emphasizes networked interoperability for these scenarios.
- Peacekeeping Missions:United Nations and regional stabilization deployments with restrictive rules of engagement. Southeast Asian contributors favor wheeled platforms with non-lethal systems for these rotations.
Onshore deployments account for the largest installed base while Offshore applications attract the steepest technology investment.
Technology:
Subsystem integration complexity separates premium platform tiers, with digitized architectures commanding pricing multiples over analog equivalents.
- Active Protection Systems:Radar and electro-optical sensors detecting incoming threats with hard-kill countermeasures. These subsystems compress upgrade cycles as legacy platforms face anti-tank guided missile proliferation.
- C4ISR:Command, control, communications, computers, intelligence, surveillance, and reconnaissance architectures fusing multi-source data. Australia's mechanized brigades field these at scale during live-fire evaluations.
- Fire Control Systems:Ballistic computers and thermal sights enabling first-round hits on moving targets. Retrofit demand concentrates in India's T-90 and Arjun fleet modernization.
- Autonomous Systems:Unmanned ground vehicles and AI-assisted target recognition reducing crew requirements. Development programs in Japan and South Korea prioritize these for future platform generations.
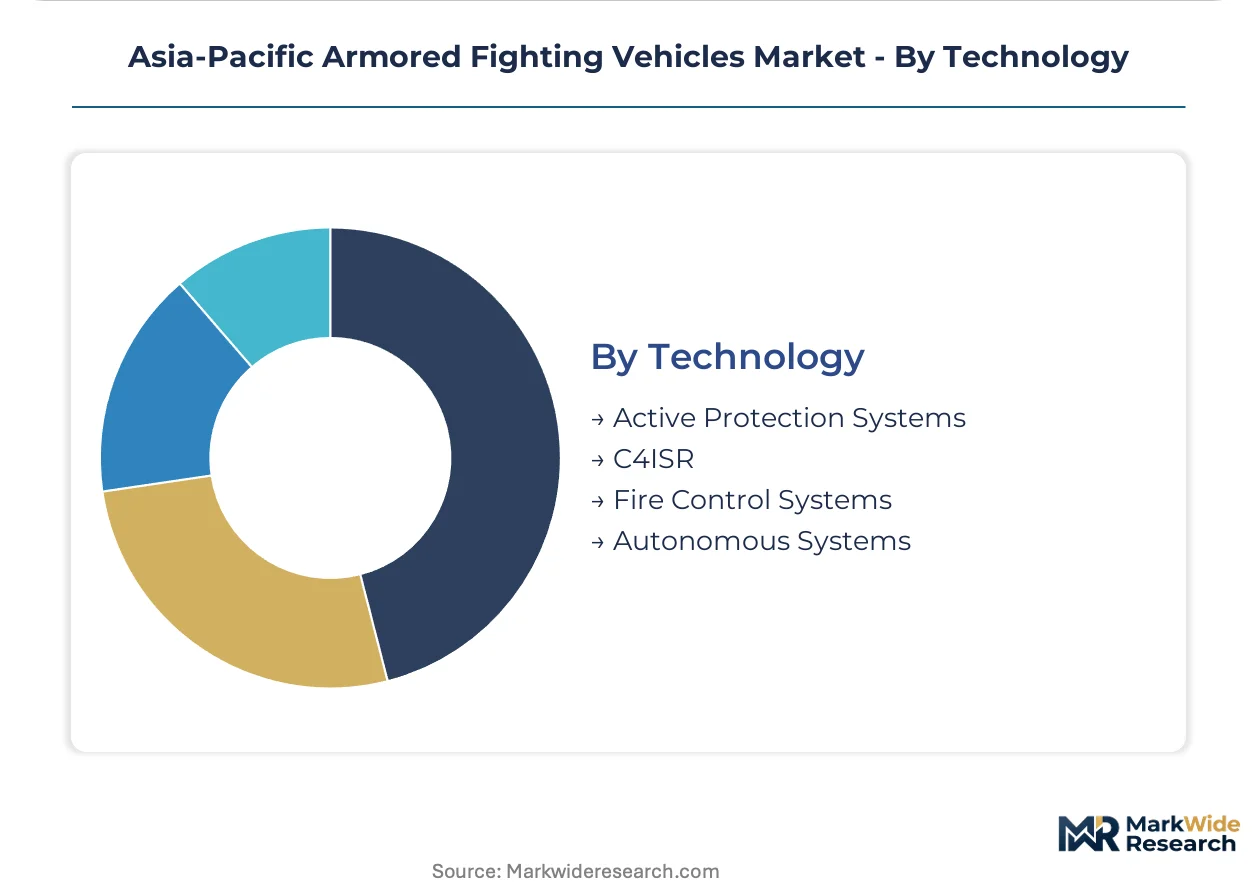
Fire Control Systems represents the most mature retrofit segment while Active Protection Systems climbs the fastest as threat environments intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Defence Acquisition Procedure mandates indigenous content thresholds that reshape procurement patterns across the region. Australia's Land 400 Phase 3 program drives premium platform demand. Japan's relaxed Three Principles on Transfer of Defense Equipment unlock export pathways to Southeast Asian partners.
India
India's armored modernization programs concentrate demand for main battle tank retrofits and active protection systems. The Defence Acquisition Procedure mandates progressive localization, forcing foreign OEMs into joint ventures with domestic partners. Ordnance Factory Board facilities in Avadi and Medak now compete with foreign suppliers for overhaul contracts on legacy T-72 and T-90 fleets.
Australia
Australia's Land 400 Phase 3 acquisition generates premium demand for amphibious-capable wheeled infantry fighting vehicles. The Defence Export Controls regulate technology sharing with regional partners, complicating maintenance networks for platforms with foreign subsystem content. Brisbane-based evaluation facilities conduct concurrent testing of mobility, protection, and lethality systems under compressed certification timelines.
Japan
Japan's Self-Defense Forces prioritize island defense platforms with swim capability and naval integration. The Ministry of Economy, Trade and Industry now interprets defense equipment export licensing under relaxed Three Principles guidelines. Mitsubishi Heavy Industries anchors the indigenous ecosystem through sustained investment in amphibious assault platforms and maintenance partnerships across Southeast Asia.
South Korea
South Korea's mechanized infantry expansion drives procurement for digitized battlefield management architectures. Hanwha Defense leverages K21 and AS21 Redback offerings to compete for regional contracts requiring C4ISR integration. The Seoul Capital Area hosts concentrated defense industrial capacity for powerpack integration and composite armor manufacturing.
Vietnam
Vietnam's mechanized infantry expansion lacks domestic armored vehicle production, creating openings for licensed assembly partnerships. The country's defense procurement channels favor technology transfer provisions over direct imports. Industrial clusters in Hanoi and Ho Chi Minh City concentrate maintenance capacity for legacy Soviet-era platforms awaiting modernization.
Asia-Pacific Armored Fighting Vehicles Market Competitive Environment
On the supply side, the industry is consolidating around defense conglomerates with integrated platform and subsystem capabilities. Tiered competition separates premium integrators from cost-optimized hull fabricators. Strategic archetypes include state-backed champions, diversified industrial conglomerates, and specialized armor subsystem suppliers. Dominant competitive moves encompass joint venture formation with local partners and technology licensing agreements that satisfy indigenous content mandates.
Within the state-backed champion tier, Mitsubishi Heavy Industries, Ltd. and Hanwha Defense exemplify vertically integrated defense conglomerates with indigenous platform ecosystems. Tata Motors Limited occupies a position among cost-optimized fabricators serving paramilitary and army requirements through joint venture structures. General Dynamics Corporation and BAE Systems plc represent Western integrators competing for premium contracts requiring C4ISR integration and active protection systems.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Rheinmetall AG |
| BAE Systems plc |
| JSC Rosoboronexport (Rostec State Corporation) |
| Mitsubishi Heavy Industries, Ltd. |
| Hanwha Defense |
| Krauss-Maffei Wegmann GmbH & Co. KG |
| Tata Motors Limited |
| FNSS Savunma Sistemleri AŞ |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on German and American powerpack suppliers for vehicles exceeding fifty tonnes compresses pricing spreads between premium integrators and cost-optimized fabricators while forcing buyers into long-term offtake commitments that lock in both cost structures and delivery schedules across the region.
Pricing Analysis
Certification level under Australia's Defence Export Controls and India's Defence Acquisition Procedure creates the primary spread between premium C4ISR-integrated platforms and baseline hull configurations. Three-tier pricing structure across active protection system-equipped, fire-control-upgraded, and analog legacy tiers reflects capability differentiation rather than brand positioning alone. Cost compression in the mid-tier retrofit segment is intensifying as Ordnance Factory Board facilities compete with foreign OEMs for overhaul contracts. Military forces demonstrate lowest price sensitivity where indigenous content mandates override unit cost considerations, while law enforcement agencies prioritize cost-per-kilometer metrics in platform selection.
Supply Chain Analysis
High-grade armor steel and ceramic-metallic composite laminates feed from concentrated industrial bases in Germany, South Korea, and Japan. Diesel engine and transmission integration draws from a narrow supplier base concentrated in Germany and the United States, with auxiliary powerpack components sourcing from Japanese and South Korean foundries. Single-source vulnerability in heavy powertrain systems creates delivery bottlenecks that extend lead times for main battle tank programs. Distribution runs through state-owned depots and licensed joint venture facilities rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific armored fighting vehicles market is recovering from procurement delays as regional governments accelerate mechanized infantry modernization to address littoral and high-altitude threat environments.
For Market Incumbents: Entrench platform ecosystem dominance through backward integration into composite armor manufacturing and captive powerpack assembly capacity in India and Australia. Lock in through-life support contracts before state-owned depots capture sustainment revenue, as India's Ordnance Factory Board facilities are already competing for overhaul contracts on legacy T-72 and T-90 fleets. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's licensed assembly partnerships where domestic production capacity is absent and technology transfer provisions are prioritized over direct imports. Target amphibious assault vehicle segments responding to Japan's relaxed Three Principles guidelines, which now permit equipment exports to aligned Southeast Asian nations previously closed to Japanese platforms. For Investors and Strategic Acquirers: Active protection system specialists with hard-kill countermeasure capabilities and software-defined turret architectures represent the most defensible acquisition targets as legacy platform upgrade cycles compress. Long-term viability hinges on positioning for the technology convergence around AI-assisted target recognition and crew size reduction. Watch for inflection signals in Australia's Land 400 Phase 3 down-select timing, which will consolidate regional demand around winning platform architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | India's Defence Acquisition Procedure mandates progressive localization, forcing foreign OEMs into domestic partnerships for armored hull and powerpack manufacturing. |
| Technology Licensing Agreement | Japan's relaxed Three Principles guidelines unlock Southeast Asian markets for Mitsubishi Heavy Industries amphibious platforms through maintenance partnerships. |
| Backward Integration | Ceramic-metallic laminate production in-house reduces exposure to German and Japanese armor steel supply concentration. |
| Platform Standardization | Modular armor kits and open electronic standards permit rapid reconfiguration between peacekeeping and high-intensity conflict roles. |
| Long-term Supply Agreement | Powerpack supply concentration in Germany and the United States necessitates offtake commitments to secure delivery slots for vehicles exceeding fifty tonnes. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with program managers at Australia's Defence Export Controls, procurement leads at India's Ordnance Factory Board, platform engineers at Mitsubishi Heavy Industries and Hanwha Defense, and maintenance directors at regional state-owned depots. Secondary validation drew from India's Defence Acquisition Procedure documentation, Australia's Land 400 Phase 3 evaluation schedules, Japan's Three Principles on Transfer of Defense Equipment guidelines, customs records for armor steel and powerpack imports, and SEC filings from listed defense conglomerates. Bottom-up platform deployment forecasts were triangulated against top-down military budget appropriations across the analysis window.
Calibration against historical procurement cycles and announced modernization timelines informed the analytical framework without reliance on single-source projections. Segmentation dimensions modeled encompass platform type, end user procurement authority, operational deployment environment, and technology integration level. CAGRs were derived from unit delivery schedules and average platform pricing trajectories, with specific weighting applied to active protection system retrofit intensity and amphibious capability premiums.
Sensitivities concentrate around powerpack delivery bottlenecks, regulatory reinterpretations of technology transfer restrictions, and threat environment escalation accelerating upgrade cycle compression. Forecasts reflect documented procurement announcements and defense budget trajectories rather than speculative capability introductions. Cross-checking against verified contract awards and joint venture formation announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
Armored Vehicle Navigation Systems Market