
 Israel Satellite Communications Market | 2026-2036
Israel Satellite Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Satellite Communications Market Insights
The Israel satellite communications sector is rebalancing between premium military-grade terminals and commodity broadband consumer equipment. Gilat Satellite Networks dominates ground infrastructure through its hub systems and VSAT platforms. AMOS Spacecom anchors regional broadcast capacity with its geostationary fleet positioned over Africa and Europe. Orbit Communication Systems Ltd specializes in maritime and airborne antenna systems for defense integrators.
Satellite communications encompasses the transmission, reception, and relay of data via artificial orbital platforms operating in geostationary, medium, or low Earth orbits using radio frequencies in the C, Ku, Ka, and X bands. Low Earth Orbit Satellites are attracting capital due to reduced latency profiles and constellation economics, though Geostationary Satellites retain margin pools in direct-to-home broadcasting and government backhaul. Ground Control Stations command premium pricing when integrated with indigenous cybersecurity protocols demanded by Israeli defense end users.
The Israel Space Agency coordinates orbital slot filings with the International Telecommunication Union, while the Ministry of Defense imposes encryption and frequency-hopping standards on military satellite procurements. The Ministry of Communications governs commercial spectrum licensing and operator certification, creating a dual-track regulatory environment that segments vendor qualification pathways. Stakeholders must monitor evolving ITU coordination procedures and domestic offset requirements that condition access to Israeli defense satellite programs.
Market Dynamics
The Israel satellite communications market is rebalancing around orbital slot scarcity and indigenous cybersecurity mandates that privilege domestic ground segment vendors over foreign terminal suppliers.
Growth Catalysts
- Defense procurement mandates:The Ministry of Defense's encryption and frequency-hopping standards for military satellite procurements create captive demand for Israeli-qualified vendors. Tactical operations units require secure satellite links for battlefield connectivity.
- Orbital coordination:The Israel Space Agency's International Telecommunication Union filings secure geostationary positions over Africa and Europe, enabling regional broadcast capacity expansion. Slot allocation drives fleet renewal timelines.
- Cybersecurity integration:Beersheba's cybersecurity-integrated ground segment cluster attracts defense integrators seeking indigenous protocol compliance. Talent concentration in this corridor accelerates product development cycles.
Market Restraints
- Launch capacity constraints:Domestic payload deployment depends on foreign launch providers, creating schedule risk and cost volatility for constellation deployment. Geopolitical friction complicates access to certain launch sites.
- Spectrum congestion:The Ministry of Communications' commercial licensing framework competes with defense allocations in Ka and X bands, creating coordination delays for new market entrants.
- Terminal cost structures:Military-grade antenna systems require specialized materials and precision manufacturing that resist economies of scale, compressing margins on low-volume defense contracts.
Strategic Opportunities
- Maritime connectivity:Israeli airborne and maritime antenna specialists can expand into Mediterranean shipping lanes where vessel operators seek sovereign-technology suppliers for regulatory compliance.
- Dual-use technology convergence:Integration of commercial broadband platforms with military-grade encryption protocols creates hybrid product categories serving both defense and enterprise verticals.
- Regional broadcast extension:AMOS orbital positions enable African market penetration where terrestrial infrastructure gaps persist, leveraging existing geostationary capacity for video distribution.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave and phased-array design expertise concentrates among legacy defense contractors, constraining startup scaling and product iteration velocity.
- ITU coordination timelines:International frequency filings require multi-year procedural windows that delay service launch, forcing capital commitment before revenue confirmation.
- Legacy system interoperability:Defense integrators demand backward compatibility with existing satellite terminals, adding engineering overhead to new platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Satellite Communications Market |
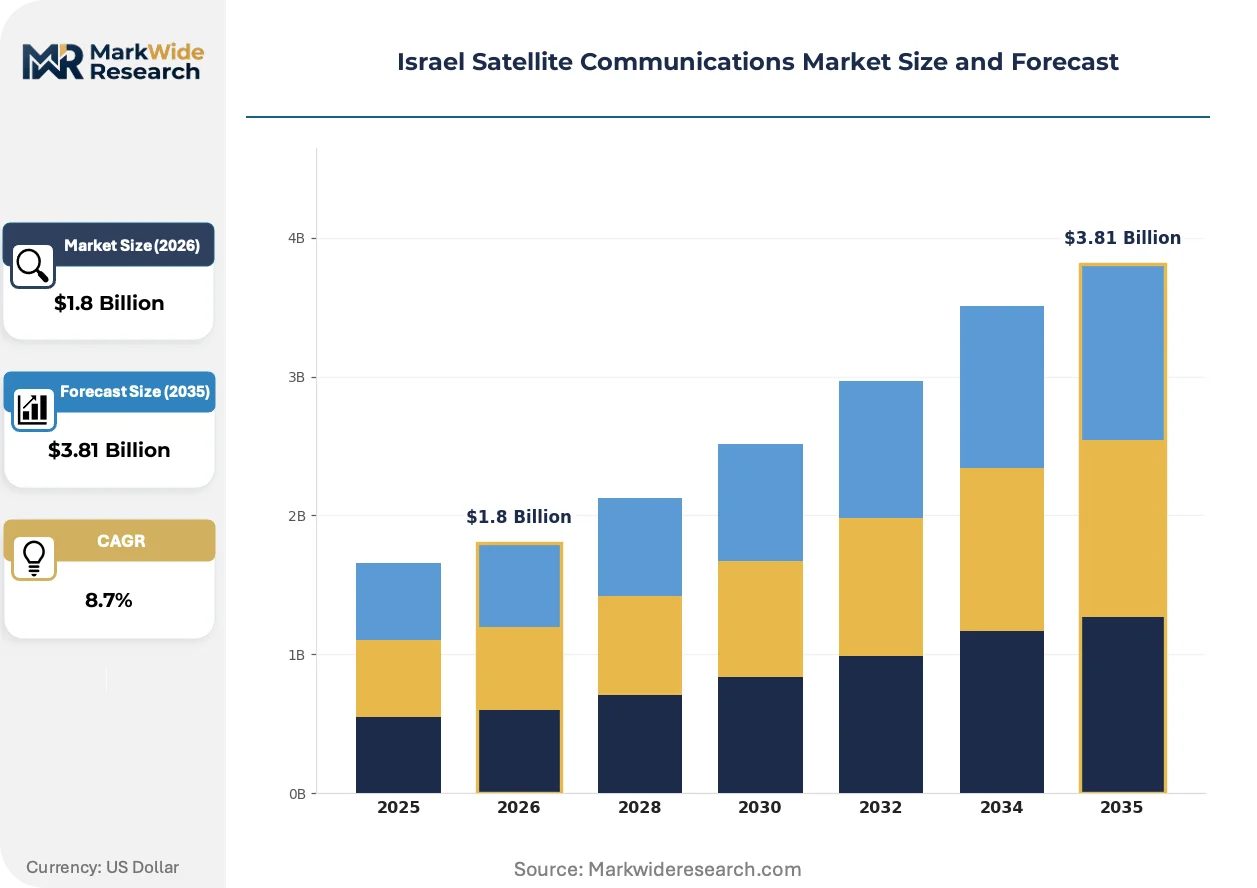
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geostationary Satellites, Low Earth Orbit Satellites, Medium Earth Orbit Satellites, Communication Payloads End User: Government, Military, Broadcast Media, Telecommunication Providers Technology: Antennas, Modems, Signal Processing Units, Ground Control Stations Service Type: Data Transmission, Broadcasting, Internet Services, Remote Sensing |
| Companies Covered | SES S.A, ViaSat Inc., Gilat Satellite Networks, Telesat, Iridium Communications Inc., Inmarsat Global Limited, AMOS Spacecom, Orbit Communication Systems Ltd, SpaceIL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Satellite Communications Market Trends and Innovations
Low Earth orbit constellations are compressing latency benchmarks and forcing geostationary operators to defend their broadcast and backhaul franchises through differentiated service models.
Software-defined radio architectures are decentralizing ground segment functionality by enabling programmable waveform adaptation across multiple orbital regimes. Defense integrators in Tel Aviv's technology corridor are adopting these platforms for multi-band tactical terminals. The shift compresses hardware refresh cycles and reduces dedicated equipment inventory.
The Ministry of Defense's encryption standards are tightening procurement qualification pathways, mandating indigenous development for classified satellite links. Commercial operators face parallel certification requirements from the Ministry of Communications that segment vendor pools. Dual-track compliance costs disproportionately burden smaller terminal manufacturers lacking dedicated regulatory affairs functions.
Defense end users are consolidating satellite service purchasing through prime contractor relationships rather than direct operator contracts. This channel compression shifts pricing power toward systems integrators with existing Ministry of Defense relationships. The pattern is most visible in airborne and maritime segments where platform certification timelines favor incumbent suppliers.
Israel Satellite Communications Market Segmentation
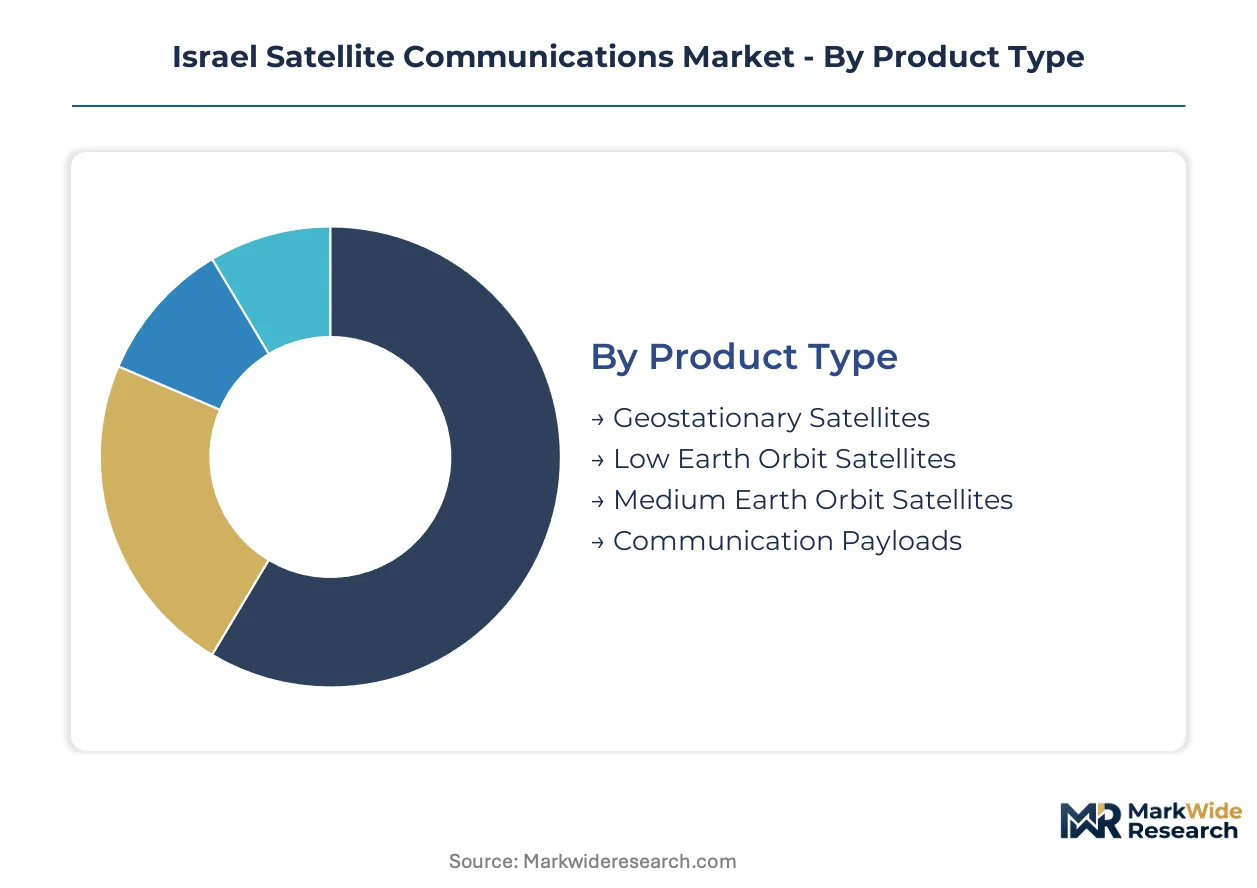
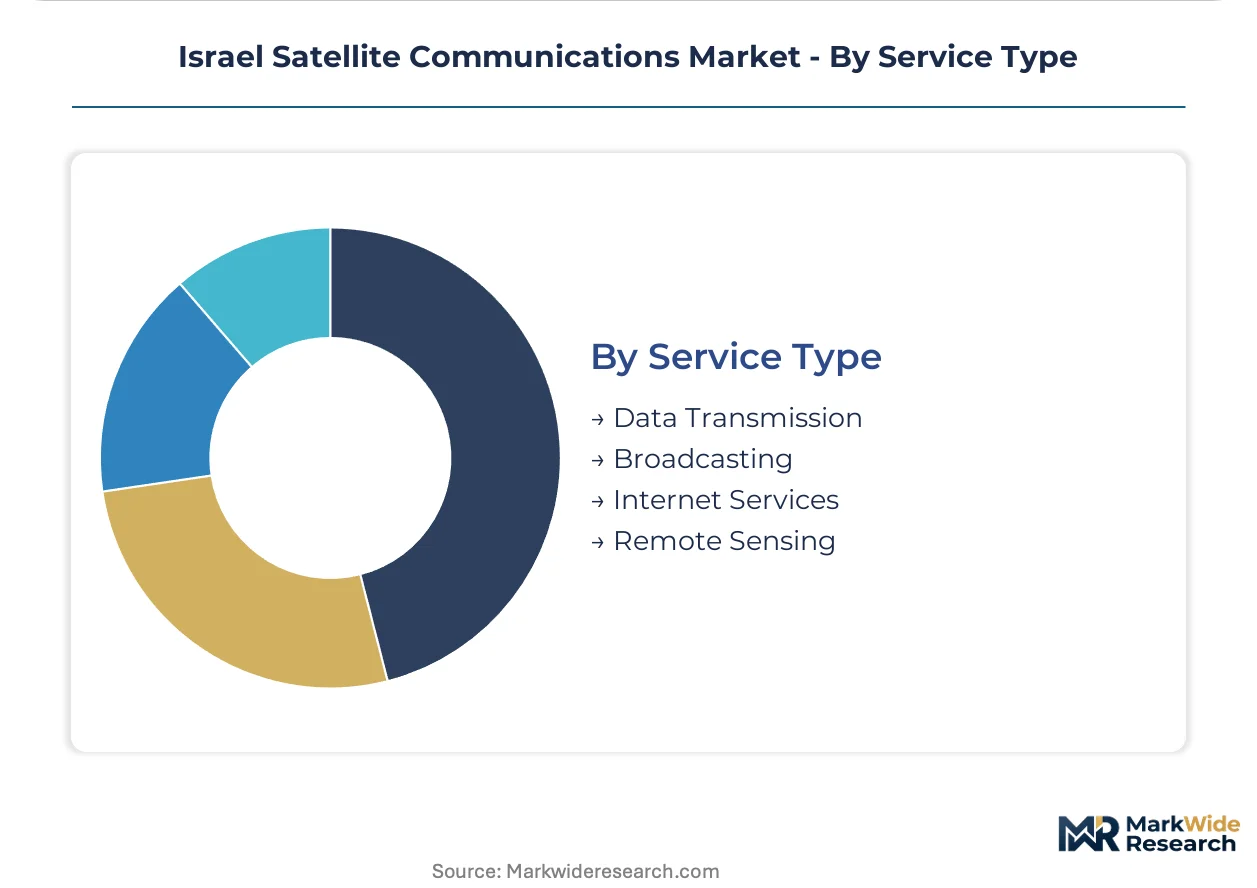
Segmentation in the Israeli satellite communications market reveals how defense procurement mandates and commercial spectrum licensing create divergent qualification pathways for vendors. Understanding these divides helps stakeholders allocate engineering resources across orbital regimes, end-use verticals, and technology layers with diverging margin profiles.
Product Type:
Defense procurement cycles favor orbital platforms with proven encryption compatibility and frequency-hopping resilience, while commercial operators prioritize latency economics and constellation scalability.
- Geostationary Satellites:These platforms occupy fixed orbital positions above the equator, delivering continuous coverage footprints over Africa and Europe from AMOS fleet positions. Israeli broadcast media and government backhaul contracts concentrate demand here, though slot scarcity at the Israel Space Agency limits new entrants.
- Low Earth Orbit Satellites:Operating at altitudes below 2,000 kilometers, these systems achieve sub-50 millisecond latency through dense constellation architectures. Tel Aviv technology corridor startups are attracting capital for these deployments, driven by tactical military requirements for real-time battlefield connectivity.
- Medium Earth Orbit Satellites:Intermediate altitude platforms balance coverage area with latency performance for navigation-integrated communication services.
- Communication Payloads:Transponder and processor modules that host frequency conversion and amplification functions for hosted payload arrangements.
Volume sits with Geostationary Satellites; growth tilts toward Low Earth Orbit Satellites.
End User:
Customer type determines certification burden and contract structure more than any other segmentation dimension in this market.
- Government:National agencies require Ministry of Defense encryption compliance and Israel Space Agency orbital coordination for secure backhaul networks. Procurement runs through systems integrators with existing security clearances rather than direct operator relationships.
- Military:Tactical operations units demand frequency-hopping terminals and indigenous cybersecurity protocols from Beersheba-qualified vendors. These contracts carry the highest technical barriers but also the most durable revenue streams through platform certification lock-in.
- Broadcast Media:Regional television distributors leverage AMOS geostationary capacity for African market penetration where terrestrial infrastructure remains sparse.
- Telecommunication Providers:Commercial carriers seek Ka-band broadband services under Ministry of Communications licensing frameworks with lighter security requirements than defense channels.
Revenue concentrates with Military; expansion is climbing fastest in Broadcast Media.
Technology:
Hardware differentiation increasingly centers on software-defined architectures that reduce dedicated equipment inventory across multiple orbital regimes.
- Antennas:Phased-array and parabolic systems for maritime and airborne platforms require specialized RF engineering talent concentrated among legacy defense contractors. Orbit Communication Systems anchors this segment with military-grade precision manufacturing.
- Modems:Baseband processing units encode and decode satellite signals, with demand shifting toward programmable waveform adaptation. Gilat Satellite Networks dominates hub system integration for both defense and commercial ground segments.
- Signal Processing Units:Onboard and ground-based modules handle interference mitigation and bandwidth optimization for congested spectrum environments.
- Ground Control Stations:Command and telemetry infrastructure commands premium pricing when integrated with indigenous cybersecurity protocols demanded by Israeli defense end users.
Margin pools favor Ground Control Stations; adoption velocity is steepest for Modems.
Service Type:
Application focus determines whether vendors compete on latency benchmarks, coverage reliability, or data throughput specifications.
- Data Transmission:Secure backhaul for government networks and enterprise connectivity drives demand for encrypted links with guaranteed service levels. Military procurement mandates sustain pricing power in this category despite commodity pressure in commercial broadband.
- Broadcasting:Direct-to-home television and radio distribution leverages existing AMOS geostationary capacity for African market extension where terrestrial gaps persist.
- Internet Services:Consumer and enterprise broadband access competes on price per megabit, compressing margins for terminal suppliers lacking defense qualification pathways.
- Remote Sensing:Earth observation data relay services support agricultural and environmental monitoring applications with specialized downlink requirements.
Defense contracts anchor Data Transmission; commercial momentum is gaining fastest in Internet Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tel Aviv's satellite technology corridor anchors national demand, with Beersheba's cybersecurity-integrated ground segment cluster driving defense procurement concentration. The Israel Space Agency coordinates orbital slot filings while the Ministry of Defense imposes encryption standards that privilege domestic vendors.
Central District
Tel Aviv Metro concentrates broadcast media and telecommunication provider headquarters seeking Ka-band commercial services. The Ministry of Communications governs spectrum licensing through regional field offices. Ramat Gan hosts AMOS Spacecom operations managing geostationary fleet coordination over Africa and Europe.
Southern District
Beersheba's cybersecurity corridor attracts defense integrators requiring indigenous protocol compliance for military satellite procurements. The Israel Space Agency maintains ground control infrastructure near the city. Ben-Gurion University feeds RF engineering talent into phased-array antenna development programs.
Haifa District
Haifa's port complex generates maritime connectivity demand from Mediterranean shipping operators. The Ministry of Defense certifies airborne and naval antenna systems through regional procurement offices. The city's industrial zone hosts precision manufacturing for military-grade terminal components.
Jerusalem District
Government agencies in the capital require secure backhaul networks with Ministry of Defense encryption compliance. The Israel Space Agency headquarters coordinates International Telecommunication Union filings from the district. National spectrum allocation policies emanate from ministry complexes in the government quarter.
Israel Satellite Communications Market Competitive Landscape
Premium-margin players sit above commodity-margin players across defense qualification pathways, with indigenous cybersecurity certification creating tiered vendor access. The market structure concentrates around ground segment specialists and orbital fleet operators with established Ministry of Defense relationships. Three archetypes dominate: geostationary fleet operators with regional broadcast capacity, ground infrastructure integrators with hub system expertise, and defense-focused antenna specialists with maritime and airborne platform certification. Competitive moves center on strategic partnerships with systems integrators and portfolio diversification into dual-use commercial-military platforms.
Within the defense-qualified tier, Gilat Satellite Networks and Orbit Communication Systems Ltd exemplify vendors with established Ministry of Defense encryption compliance pathways. AMOS Spacecom anchors the geostationary operator segment with orbital positions over Africa and Europe. These three represent distinct strategic positions: ground infrastructure integration, specialized antenna manufacturing, and regional broadcast capacity management.
| Leading Market Players |
|---|
| SES S.A |
| ViaSat Inc. |
| Gilat Satellite Networks |
| Telesat |
| Iridium Communications Inc. |
| Inmarsat Global Limited |
| AMOS Spacecom |
| Orbit Communication Systems Ltd |
| SpaceIL |
| Others |
Pricing and Supply Chain Analysis
Defense procurement concentration among Ministry of Defense-certified systems integrators anchors value-based pricing for satellite ground infrastructure. These buyers prioritize encryption compliance and frequency-hopping resilience over per-unit cost, enabling premium capture for indigenous vendors.
Pricing Analysis
Value-based pricing tied to guaranteed uptime and encrypted throughput dominates military satellite service contracts. Price differentiation rests on Ministry of Defense certification tier and indigenous cybersecurity protocol integration. Cost compression in commercial broadband terminals intensifies as foreign suppliers compete on volume without defense qualification pathways. Broadcast media customers exhibit highest price sensitivity, while tactical military units accept substantial premiums for certified equipment.
Supply Chain Analysis
Certification gating through Ministry of Defense encryption standards restricts qualified component suppliers to Israeli and select allied-nation vendors. RF engineering talent concentrates in Israel and the United States, with precision manufacturing inputs sourced from Germany and Japan. Single-source vulnerability in phased-array antenna substrates creates schedule risk for defense integrators. Distribution runs through prime contractor relationships rather than direct operator channels, compressing vendor pricing power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as dual-track regulatory compliance costs disproportionately burden smaller terminal manufacturers lacking dedicated regulatory affairs functions.
For Market Incumbents: Lock in defense procurement relationships through deeper integration with Beersheba cybersecurity corridor talent pools. Expand software-defined radio architectures to reduce hardware refresh cycles and defend against emerging LEO constellation entrants. Prioritize backward integration into indigenous encryption module production to maintain certification barriers. For New Entrants and Emerging Players: Software-defined ground segment platforms offer a technology-first wedge into commercial telecommunication provider segments with lighter Ministry of Communications certification burdens. Target maritime connectivity in Mediterranean shipping lanes where sovereign-technology requirements favor new regional suppliers. Pursue partnership pathways with established systems integrators to bypass direct defense procurement qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap antenna specialists with dormant Ministry of Defense certifications in Israel's Southern District. Long-term viability hinges on dual-use technology convergence spanning defense and enterprise verticals. Watch for ITU coordination timeline delays as inflection indicators for fleet operator capital stress.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | Ministry of Defense encryption compliance creates defensible competitive moats for qualified vendors. |
| Dual-Use Platform Development | Commercial broadband integration with military-grade protocols opens hybrid revenue streams. |
| Regional Broadcast Extension | AMOS orbital positions enable African market penetration where terrestrial infrastructure gaps persist. |
| Software-Defined Radio Adoption | Programmable waveform adaptation reduces dedicated equipment inventory across orbital regimes. |
| Maritime Connectivity Expansion | Mediterranean shipping operators seek sovereign-technology suppliers for regulatory compliance. |
Research Methodology
Document review covered regulatory filings from the Israel Space Agency and Ministry of Defense, trade customs data, and orbital coordination records from the International Telecommunication Union, complemented by interviews with ground segment engineering directors, defense procurement officers, satellite operator strategy leads, and RF systems integrators. Secondary sources included ITU satellite network filings, Ministry of Communications spectrum licensing databases, and defense contractor technical specifications. Bottom-up demand estimates from terminal deployment data were triangulated against top-down market sizing from fleet capacity and service revenue analysis.
Segment-level outputs across the projection horizon reflect modeled assumptions for orbital regime adoption, end-user vertical penetration, and technology layer substitution patterns. The analytical framework incorporated geostationary fleet renewal timelines, LEO constellation deployment schedules, and defense procurement cycle phasing as industry-specific forecast inputs. CAGRs were derived from regression analysis of historical capacity pricing and projected terminal cost curves.
Several conditions sit outside the modeled scope, including geopolitical disruptions to launch site access, unilateral spectrum reallocation by national regulators, and breakthroughs in optical inter-satellite link economics. Forecasts reflect assumptions about continued Ministry of Defense encryption standard stability and ITU coordination procedural continuity. A model refresh is warranted upon material change in defense procurement budget allocation or commercial spectrum licensing framework revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Communication System Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
India Satellite Connectivity Market
Satellite
All-Electric Satellites Market
Satellite
UAE Satellite Communication Market
Satellite
Low-Cost Satellite Market
Satellite
ASEAN Satellite-Based Earth Observation Market
Satellite
Global LEO Satellite Market
Satellite
Satellite Antenna Market
Satellite
Satellite Transponder Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Sudan Satellite Transponder Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Nanosatellite Market
Satellite
Healthcare Satellite Connectivity Market