
 ASEAN Satellite-Based Earth Observation Market | 2026-2036
ASEAN Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Satellite-Based Earth Observation Market Insights
Defense and intelligence agencies are unwinding their historical reliance on civilian research institutions as the primary buyers of satellite imagery across Southeast Asia. Maxar Technologies leverages its constellation scale to anchor government contracts in Singapore and Vietnam. Spire Global competes through radio occultation data layers that differentiate its maritime tracking offerings from conventional optical providers. Airbus sustains its position via dual-use platforms serving both ASEAN military customers and European development agencies operating in the region.
Satellite-based earth observation encompasses the acquisition, processing, and distribution of geospatial data captured by orbiting sensors operating at altitudes between 400 and 36,000 kilometers, with spatial resolutions ranging from sub-meter panchromatic to 250-meter multispectral coverage for regional climate monitoring. Synthetic Aperture Radar technology leads in tropical applications where cloud cover persists more than 200 days annually across Indonesia and Malaysia, while optical imaging dominates urban planning contracts requiring true-color validation. Disaster management applications generate the fastest growth trajectory as ASEAN member states operationalize early warning systems for typhoon tracking and flood inundation mapping.
Indonesia's National Institute of Aeronautics and Space partners with the country's national pharmaceutical regulator on health mapping initiatives, while Singapore's Infocomm Media Development Authority sets data localization standards that shape foreign operator market access. Thailand's Geo-Informatics and Space Technology Development Agency coordinates regional calibration protocols under ISO 19115 metadata frameworks. Stakeholders must monitor how national space legislation drafts in the Philippines and Vietnam will reshape foreign ownership rules for ground station infrastructure.
Market Dynamics
Defense procurement patterns across Southeast Asia are compressing contract cycles from multi-year research grants to rapid operational deployments, forcing satellite operators to restructure delivery timelines and technical support models around mission-critical specifications.
Growth Catalysts
- Maritime Domain Awareness Mandates:Naval modernization programs in Vietnam and the Philippines are generating recurring subscriptions for synthetic aperture radar coverage of contested waters. Defense ministries now specify sub-meter resolution as baseline procurement criteria.
- ISO 19115 Metadata Frameworks:Thailand's adoption of standardized geospatial metadata protocols is enabling cross-border data sharing agreements. Regional calibration networks reduce redundant satellite passes and lower analytics processing costs.
- Peatland Fire Monitoring:Indonesia's palm oil certification requirements under national sustainability standards are institutionalizing satellite-based hotspot detection. Plantation conglomerates purchase weekly fire risk assessments to maintain export market access.
Market Restraints
- Ground Station Infrastructure Concentration:Foreign ownership restrictions on terrestrial receiving equipment in the Philippines and Vietnam limit direct-to-customer data delivery. Operators must partner with domestic telecommunications incumbents, adding margin layers.
- Launch Cost Volatility:Dependence on foreign launch providers exposes ASEAN satellite programs to payload integration delays and currency fluctuation risks. Domestic launch capability remains underdeveloped across the region.
- Persistent Cloud Cover:Optical imaging systems face technical limitations in equatorial climates where annual cloud persistence exceeds 200 days. This constrains effective revisit rates for time-critical applications.
Strategic Opportunities
- Myanmar Market Opening:Sanctions relaxation is creating first-mover opportunities for agricultural monitoring contracts. International development agencies require independent crop yield verification for aid distribution programs.
- Health Mapping Convergence:Indonesia's national pharmaceutical regulator is partnering with space agencies to map disease vectors and pharmaceutical supply chains. Epidemiological surveillance represents an emerging application vertical.
- Radio Occultation Integration:Combining atmospheric sounding data with maritime tracking capabilities is enabling weather-routing services for shipping lanes. Technology convergence between meteorological and navigation datasets creates differentiated analytics products.
Industry Challenges
- Geospatial Data Science Talent Scarcity:Remote sensing algorithm development and SAR interpretation require specialized skill sets that universities across Southeast Asia have not scaled to meet. Defense agencies compete with commercial operators for limited personnel.
- Dual-Use Classification Complexity:Satellite systems serving both civilian and military end-uses face export control review processes that extend procurement timelines. Licensing ambiguity creates project planning uncertainty for foreign operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Satellite-Based Earth Observation Market |
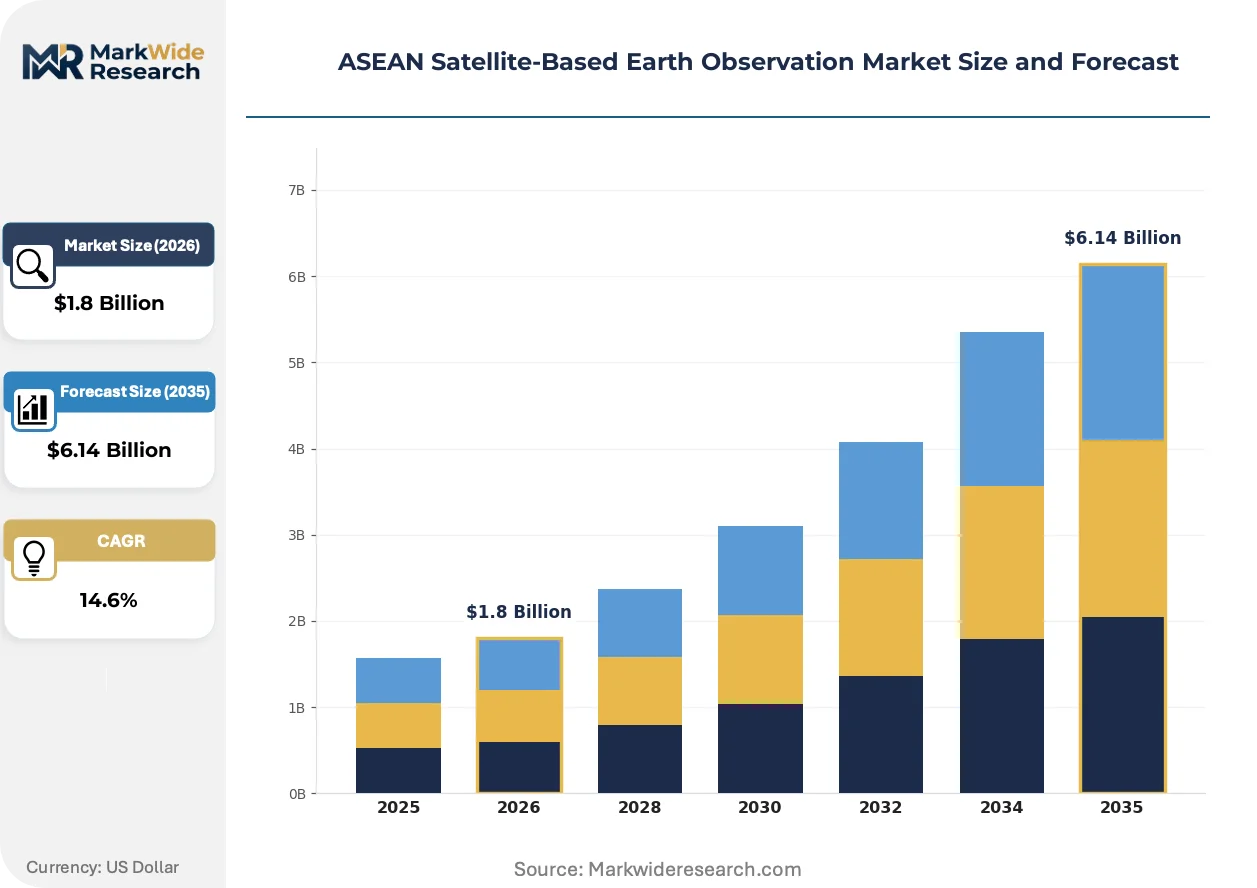
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analytics, Image Processing, Data Management, Remote Sensing End User: Agriculture, Forestry, Environmental Monitoring, Urban Planning Technology: SAR, Multispectral, Hyperspectral, Optical Imaging Application: Disaster Management, Climate Change, Resource Management, Infrastructure Monitoring |
| Companies Covered | Maxar Technologies Inc, Spire Global Inc, Airbus SE, EOMAP Indonesia, NEC Corporation, Philippine Earth Data Resource Observation Center, ST Engineering, Boeing Co, Thales Group, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Satellite-Based Earth Observation Market Trends and Innovations
Sensor platform architectures and data distribution models are undergoing parallel transformation, with hardware miniaturization and regulatory localization operating as interconnected forces reshaping competitive positioning.
Synthetic Aperture Radar payload designs are miniaturizing from bus-scale systems to cubesat-compatible form factors without sacrificing resolution performance. Indonesian university research consortia are deploying these compact SAR units for peatland subsidence monitoring at capital expenditure levels accessible to provincial governments. The technology is miniaturizing market entry barriers, enabling domestic operators to challenge incumbent providers on recurring analytics contracts previously dominated by foreign constellations.
Singapore's Infocomm Media Development Authority has enacted data localization standards requiring terrestrial processing of sensitive geospatial information within national borders. This policy is fragmenting regional cloud infrastructure strategies, compelling foreign satellite operators to establish domestic data centers rather than serving ASEAN markets from centralized Asian hubs. Defense and intelligence contracts now specify sovereign data residency as a non-negotiable technical requirement.
Subscription-based analytics procurement is displacing traditional imagery licensing arrangements across plantation agriculture and disaster response agencies. Indonesian palm oil certification bodies now contract for automated fire alert services rather than purchasing raw satellite scenes. This behavioral shift concentrates purchasing authority with analytics platforms capable of algorithmic feature extraction, compressing margins for pure-play imagery distributors.
ASEAN Satellite-Based Earth Observation Market Segmentation
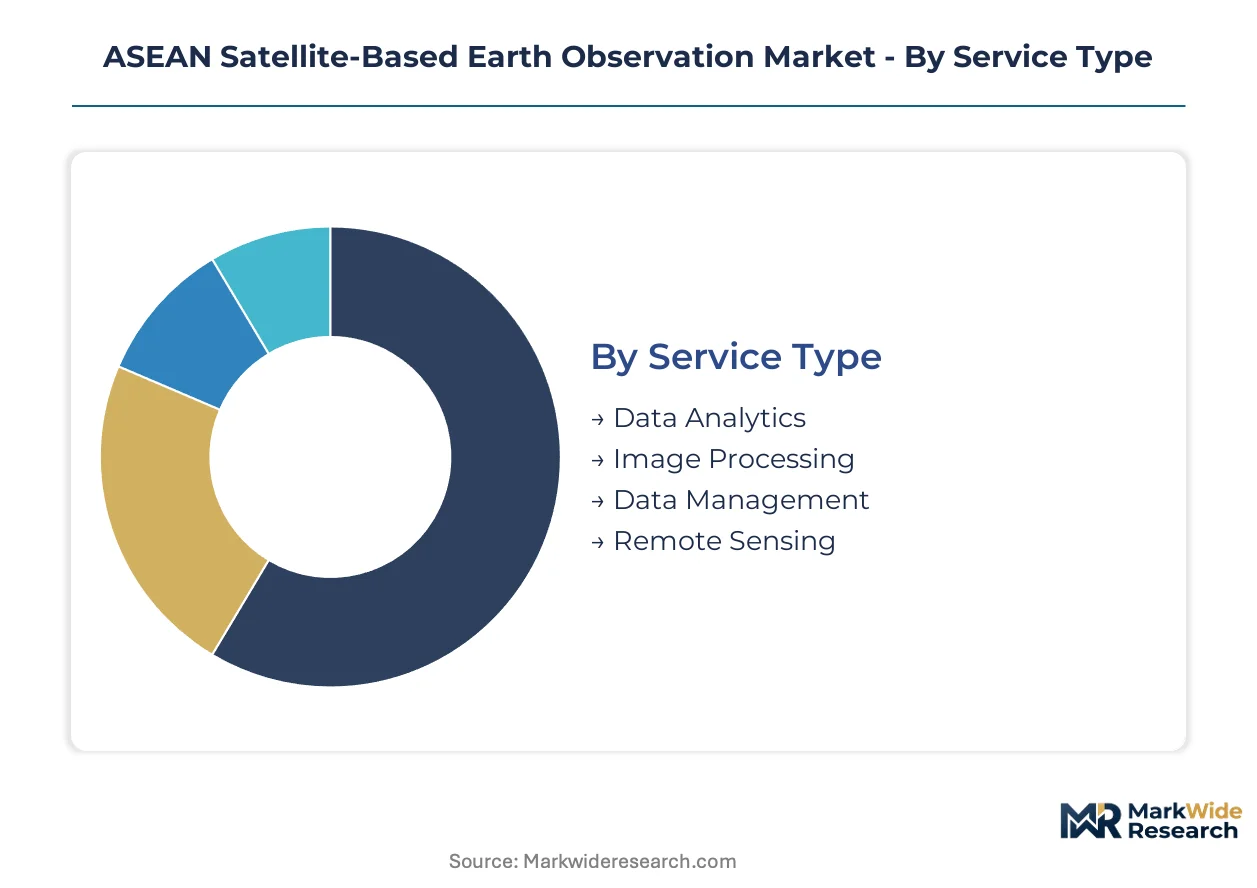
Service delivery models and sensor technologies across Southeast Asia face divergent substitution pressures from drone-based surveys and terrestrial IoT networks. Procurement authority is consolidating around integrated analytics platforms rather than raw data vendors.
Service Type:
Data Analytics faces the strongest substitution threat as plantation conglomerates and defense agencies bypass imagery resellers to contract directly with algorithm developers.
- Data Analytics:Automated feature extraction and predictive modeling services transform raw satellite feeds into actionable intelligence for fire risk assessment and yield forecasting. Indonesian palm oil certification bodies now mandate algorithmic hotspot detection as a condition of export licensing, institutionalizing recurring subscription models over one-time imagery purchases.
- Image Processing:Atmospheric correction, orthorectification, and pan-sharpening workflows convert sensor outputs into analysis-ready datasets. Thailand's Geo-Informatics and Space Technology Development Agency operates regional calibration nodes that standardize preprocessing protocols across Cambodian and Laotian government clients, reducing redundant processing costs.
- Data Management:Cloud-based archiving and retrieval systems with ISO 19115 metadata compliance enable cross-border sharing among ASEAN disaster response agencies.
- Remote Sensing:Direct sensor tasking and acquisition services retain value for time-critical defense applications requiring guaranteed revisit schedules.
Data Analytics anchors the volume base while Image Processing gains share at the steepest rate as standardization reduces customer switching costs.
End User:
Cost tier differentiation separates government-funded environmental monitoring from self-financing plantation agriculture, with urban planning occupying a mid-tier procurement position.
- Agriculture:Plantation operators purchase weekly fire risk assessments and subsidence monitoring to maintain sustainability certifications and insurance coverage. Indonesian and Malaysian palm oil conglomerates represent the largest commercial customer segment, with procurement concentrated among firms controlling more than 50,000 hectares of peatland concessions.
- Forestry:Illegal logging detection and carbon stock verification services attract development agency funding. Vietnam's forest protection departments deploy SAR-based change detection to monitor highland timber concessions where cloud cover limits optical alternatives.
- Environmental Monitoring:Peatland fire detection and haze pollution tracking operate under national regulatory mandates in Indonesia and Singapore.
- Urban Planning:True-color validation for infrastructure development and informal settlement mapping drives demand in Philippine and Vietnamese metropolitan corridors.
Agriculture commands the highest absolute spending while Environmental Monitoring expands most quickly as regulatory compliance deadlines accelerate procurement timelines.
Technology:
Application requirements in equatorial climates favor all-weather capabilities over spectral richness, reshaping sensor procurement priorities.
- SAR:Synthetic Aperture Radar penetrates cloud cover and operates independently of solar illumination, enabling reliable revisit rates exceeding 200 annual observations in Indonesian and Malaysian territories. Naval modernization programs in Vietnam and the Philippines specify SAR-derived maritime domain awareness as baseline technical requirements for contested water surveillance.
- Multispectral:Discrete band imaging supports vegetation health indices and land cover classification at capital expenditure levels accessible to provincial governments. Indonesian university consortia deploy compact multispectral payloads on cubesat platforms for peatland subsidence monitoring.
- Hyperspectral:Continuous spectral sampling enables mineral identification and precision agriculture applications with limited current deployment in Southeast Asia due to data processing complexity.
- Optical Imaging:True-color and panchromatic systems dominate urban planning contracts requiring visual validation, though annual cloud persistence exceeding 200 days constrains effective utilization.
SAR technology anchors the defense and disaster response volume base while Multispectral climbs the fastest as miniaturization enables domestic constellation deployment.
Application:
Customer maturity separates operationalized early warning systems from experimental climate modeling initiatives, with infrastructure monitoring occupying an intermediate adoption position.
- Disaster Management:Operational early warning systems for typhoon tracking, flood inundation mapping, and landslide risk assessment command the fastest procurement cycles across ASEAN member states. Thailand's national disaster prevention center maintains 24-hour satellite tasking authority during monsoon seasons.
- Climate Change:Long-term carbon sequestration monitoring and emissions verification attract multilateral development bank financing. Indonesian peatland restoration projects require decadal subsidence tracking to validate carbon credit claims.
- Resource Management:Fisheries surveillance and maritime boundary enforcement support naval modernization programs in Vietnam and the Philippines.
- Infrastructure Monitoring:Transportation corridor stability and energy grid vulnerability assessment serve both government planning agencies and private concession operators.
Disaster Management anchors the volume base while Resource Management gains share at the steepest rate as maritime sovereignty disputes intensify sensor deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Strait of Malacca shipping corridor underwrites Southeast Asia's strategic position in maritime domain awareness, with coastal ground stations in Singapore and Malaysia anchoring regional data relay networks for satellite operators serving defense and commercial clients.
Indonesia
Peatland fire monitoring and palm oil certification mandates drive recurring analytics subscriptions from plantation conglomerates controlling concessions exceeding 50,000 hectares. The National Institute of Aeronautics and Space partners with the national pharmaceutical regulator on health mapping initiatives. Jakarta and Surabaya host domestic processing centers where university consortia deploy compact SAR cubesats for subsidence tracking.
Singapore
The Infocomm Media Development Authority enforces data localization standards requiring terrestrial processing of sensitive geospatial information within national borders. Defense contracts now specify sovereign data residency as non-negotiable. The city-state's satellite ground segment infrastructure serves as a regional hub for foreign operators establishing ASEAN data centers.
Thailand
The Geo-Informatics and Space Technology Development Agency coordinates regional calibration protocols under ISO 19115 metadata frameworks. Naval modernization programs generate demand for sub-meter resolution imagery. Bangkok anchors cross-border data sharing agreements that standardize preprocessing protocols for Cambodian and Laotian government clients.
Vietnam
Naval modernization programs specify SAR-derived maritime domain awareness for contested water surveillance. Draft national space legislation will reshape foreign ownership rules for ground station infrastructure. Ho Chi Minh City concentrates domestic telecommunications partnerships that foreign operators require for direct-to-customer data delivery.
Philippines
The Philippine Earth Data Resource Observation Center manages domestic satellite receiving infrastructure amid foreign ownership restrictions on terrestrial equipment. Disaster management agencies operationalize early warning systems for typhoon tracking and flood inundation mapping. Manila-based telecommunications incumbents add margin layers as mandatory partners for foreign satellite operators.
ASEAN Satellite-Based Earth Observation Market Competitive Landscape
Concentration sits with constellation-scale operators and specialized analytics platforms serving defense and plantation agriculture verticals. The vendor base spans three tiers: global imagery providers with dedicated ASEAN sales infrastructure, regional analytics specialists with domestic ground station partnerships, and domestic university consortia deploying miniaturized SAR payloads. Competitive moves center on data center localization to satisfy sovereign residency requirements and subscription-based service models displacing traditional imagery licensing.
Among global operators, Maxar Technologies Inc and Airbus SE exemplify the constellation-scale archetype with established government contracting relationships across Singapore and Vietnam. Spire Global Inc occupies a differentiated position through atmospheric data layers integrated with maritime tracking capabilities. Regional specialists including EOMAP Indonesia and ST Engineering anchor domestic processing and analytics services. The Philippine Earth Data Resource Observation Center represents institutional infrastructure operators managing sovereign ground segments.
| Leading Market Players |
|---|
| Maxar Technologies Inc |
| Spire Global Inc |
| Airbus SE |
| EOMAP Indonesia |
| NEC Corporation |
| Philippine Earth Data Resource Observation Center |
| ST Engineering |
| Boeing Co |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Subscription-based analytics procurement replacing raw imagery licensing simultaneously shifts supply geography toward domestic processing centers and compresses pricing power for pure-play data distributors across Indonesia and Singapore.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates ASEAN satellite earth observation, with defense agencies occupying the premium tier for guaranteed revisit schedules and plantation operators clustering in standard tiers for weekly fire risk assessments. Price differentiation hinges on resolution grade and ISO 19115 metadata certification compliance. Cost compression in the economy tier is intensifying because domestic university consortia deploy miniaturized SAR cubesats at capital expenditure levels accessible to provincial governments. Defense and intelligence agencies exhibit the lowest price sensitivity, while provincial disaster management offices in Cambodia and Laos face acute budget constraints.
Supply Chain Analysis
Inventory lead times for SAR payload components extend procurement cycles for domestic satellite programs, with foreign launch provider scheduling creating additional delays. Manufacturing concentration centers on the United States, France, and Japan for high-resolution optical sensors, while SAR subsystem fabrication draws from South Korea and Israel. Supply chain risk manifests in single-source vulnerability for radio frequency components subject to export control review. Distribution runs through domestic telecommunications incumbents in Vietnam and the Philippines, where foreign ownership restrictions on ground station infrastructure mandate local partnership layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
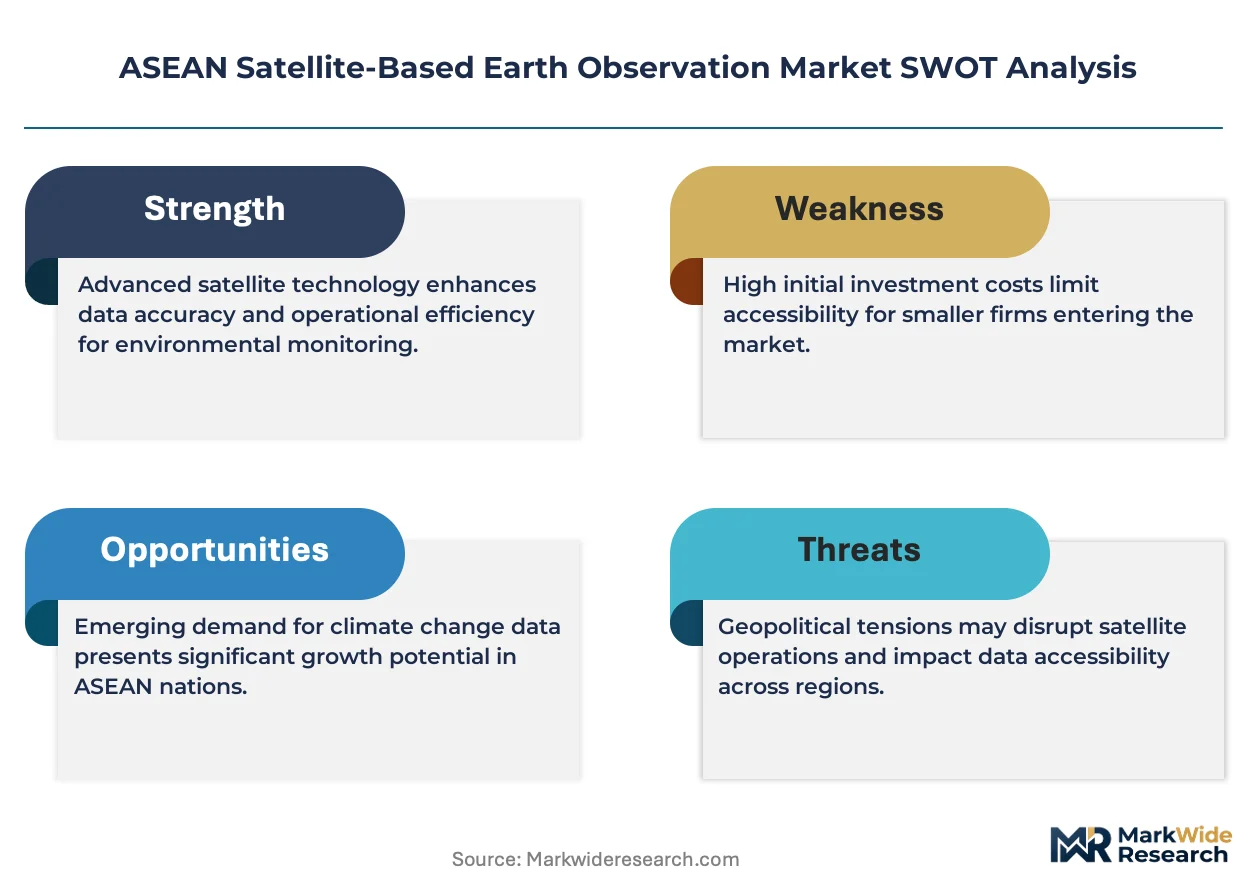
Sovereign data residency mandates across Singapore and Vietnam constitute a regulatory inflection that accelerates market disruption for foreign operators lacking localized infrastructure.
For Market Incumbents: Consolidate analytics platform capabilities through acquisition of algorithm developers serving plantation agriculture verticals, as Indonesian palm oil certification bodies now mandate automated hotspot detection. Anchor defense contracting relationships by establishing domestic data centers that satisfy sovereign residency requirements, converting technical compliance into switching cost barriers against foreign competitors lacking localized infrastructure.
For New Entrants and Emerging Players: Health mapping convergence between space agencies and pharmaceutical regulators in Indonesia represents a service-layer gap where incumbents under-serve epidemiological surveillance applications. Target Myanmar's agricultural monitoring contracts as sanctions relaxation creates first-mover opportunities for crop yield verification services. Deploy radio occultation data layers as a differentiated go-to-market angle that combines atmospheric sounding with maritime tracking capabilities.
For Investors and Strategic Acquirers: The market sits at an infrastructure localization phase that favors analytics platforms with domestic ground station partnerships over pure-play constellation operators. Long-term viability favors acquisition targets possessing algorithmic feature extraction capabilities and recurring subscription revenue from plantation conglomerates. Monitor draft national space legislation in Vietnam and the Philippines as a signal for foreign ownership rule changes that would reshape ground station infrastructure valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Establishment | Singapore's Infocomm Media Development Authority mandates sovereign processing for defense contracts. |
| Algorithm Developer Acquisition | Indonesian palm oil certification bodies require automated fire alert subscriptions over raw imagery. |
| Radio Occultation Capability Integration | Spire Global demonstrates differentiated positioning through atmospheric data layer convergence. |
| University Consortium Partnership | Thailand's Geo-Informatics and Space Technology Development Agency coordinates regional calibration protocols. |
| Myanmar Market Entry | Sanctions relaxation creates first-mover advantage for agricultural yield verification contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of satellite operator filings, ASEAN space agency procurement disclosures, and plantation sustainability certification databases. Primary interviews engaged defense procurement officers, geospatial analytics directors at plantation conglomerates, and satellite ground station engineers across Indonesia, Singapore, Thailand, and Vietnam. Secondary validation drew from customs records of satellite component imports, ISO 19115 metadata framework documentation, and national space legislation drafts. Bottom-up demand modeling triangulated against top-down market sizing from constellation capacity announcements.
Segmentation dimensions modeled include service type, end user vertical, sensor technology, and application category across the analysis window. CAGRs derived from regression analysis of historical procurement volumes and projected satellite launch schedules. Industry-specific forecast inputs incorporated peatland fire monitoring regulatory mandates and naval modernization program timelines for maritime domain awareness.
Underlying assumptions cover sustained enforcement of palm oil certification requirements and continued naval modernization spending, with deviation risk concentrated in foreign launch provider delays and export control licensing ambiguity for dual-use satellite systems. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
UK Satellite-Based Earth Observation Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Satellite Operation Service Market
Satellite
Satellite Amplifier Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Global Remote Sensing Services Market
Satellite
Optical Satellite Communication Market
Satellite
LEO and GEO Satellite Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Commercial LEO Satellite Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
UK Satellite Imagery Services Market