
 VSAT Maritime Satellite Communication Market | 2026-2036
VSAT Maritime Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
VSAT Maritime Satellite Communication Market Analysis
Channel architecture for maritime VSAT is tilting away from traditional resellers toward direct fleet-operator contracts managed by integrated service providers. Inmarsat Global Limited leverages its L-band heritage to anchor long-term contracts with container lines requiring pole-to-pole coverage. Viasat Inc competes through Ka-band capacity density over busy shipping lanes, while Marlink SAS specializes in multi-orchestrator platforms that aggregate Ku-band, Ka-band, and L-band under single service level agreements.
VSAT Maritime Satellite Communication denotes very small aperture terminal systems operating aboard vessels via geostationary, medium-earth, or low-earth orbit satellites, typically employing stabilized antenna platforms under one meter diameter with gyroscopic tracking to maintain link connectivity through sea state motion. The primary commercial purpose centers on delivering broadband internet, voice, and operational data services to vessels beyond terrestrial network reach. Service contracts dominate margin pools as hardware commoditizes, while Ka-band technology leads capacity growth due to spot-beam frequency reuse. Offshore platforms represent the fastest-growing end-user category as drillship operators require real-time telemetry and crew welfare bandwidth.
The FCC governs maritime radio equipment authorization in the United States, while the EU's F-Gas Regulation and CE marking framework shape vessel equipment standards across European waters. These regimes compel terminal manufacturers to certify thermal performance and electromagnetic compatibility for salt-air environments. Stakeholders must monitor spectrum reallocation proceedings at WRC conferences and decide whether to anchor procurement on GEO stability or bet on LEO constellation latency advantages.
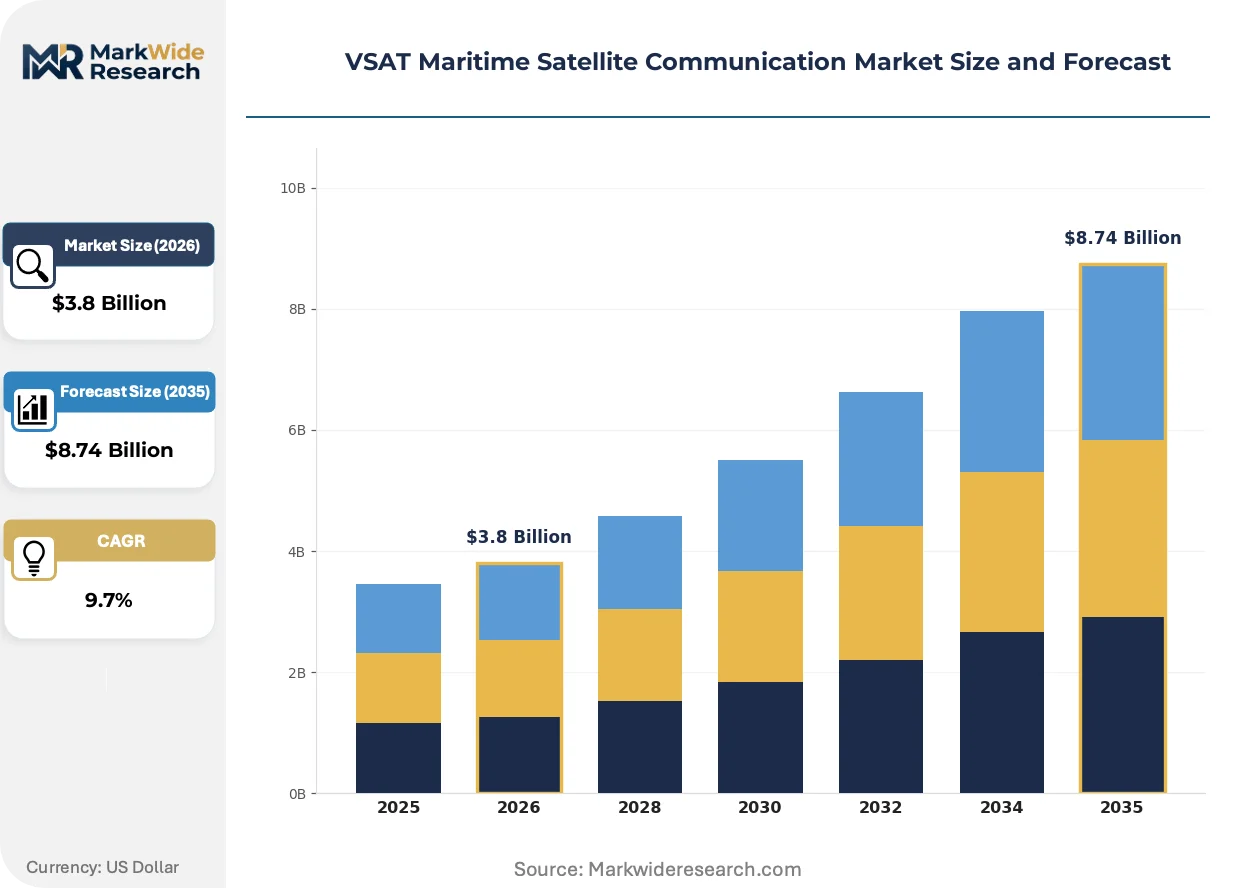
Market Dynamics
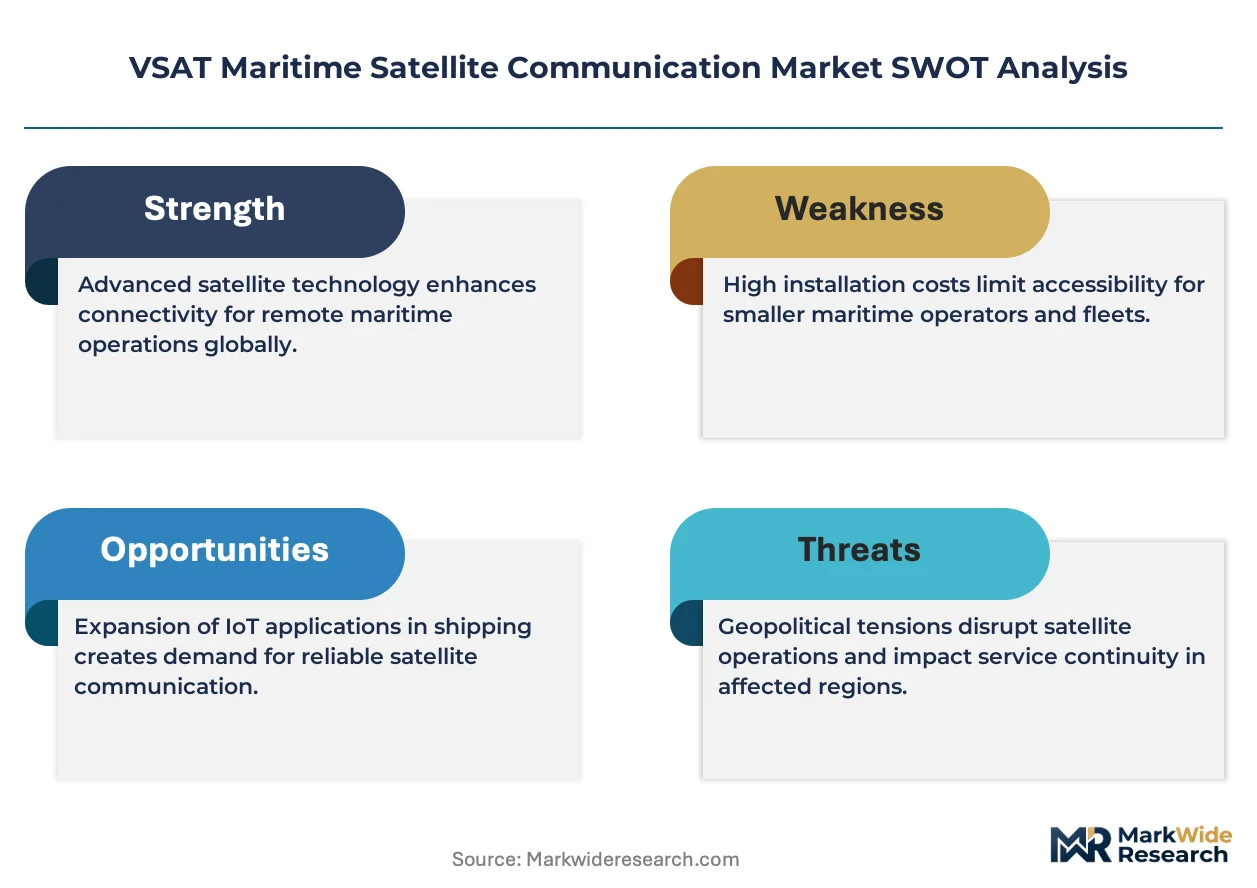
Ka-band spot-beam architectures are collapsing the cost-per-bit economics that once favored Ku-band and L-band legacy contracts, forcing service providers to restructure pricing models and fleet operators to renegotiate multi-year agreements.
Growth Catalysts
- EU F-Gas Regulation:Vessel emission mandates in European waters compel fleet operators to install certified VSAT terminals for real-time emissions monitoring and automated reporting to port authorities.
- Offshore platform digitization:Drillship operators in Norway's North Sea corridor require continuous telemetry bandwidth for remote asset management and crew welfare connectivity beyond legacy L-band limits.
- LEO constellation maturation:Low-earth orbit networks are delivering sub-100ms latency that satisfies autonomous navigation and real-time video requirements previously unattainable through geostationary links.
Market Restraints
- Antenna stabilization costs:Gyroscopic tracking platforms capable of maintaining Ka-band lock through heavy sea states require precision mechanical components subject to supply concentration among Japanese and German component suppliers.
- Spectrum reallocation uncertainty:World Radiocommunication Conference proceedings create procurement hesitation as fleet operators delay terminal investments pending clarity on C-band and Ku-band availability.
- Terrestrial 5G backhaul substitution:Coastal shipping lanes within 50 nautical miles of shore increasingly rely on cellular maritime coverage, compressing addressable market for VSAT providers in regional container trades.
Strategic Opportunities
- Arctic route expansion:Russia's Northern Sea Route and Canada's Northwest Passage lack terrestrial infrastructure, creating first-mover advantage for polar-optimized VSAT terminals with enhanced cold-weather specifications.
- Cybersecurity certification premiums:IEC 62443 industrial cybersecurity standards for maritime systems enable service providers to command pricing premiums through certified secure communication stacks.
- Fishing fleet underpenetration:Industrial trawler and longline vessel segments remain predominantly served by legacy Inmarsat C terminals, presenting upgrade opportunity for broadband-enabled operational efficiency and crew retention.
Industry Challenges
- RF engineer scarcity:Terminal manufacturers face recruitment gaps for specialists capable of designing phased-array antennas that maintain link budgets through vessel pitch and roll motion.
- Multi-orbit integration complexity:Service providers aggregating GEO, MEO, and LEO constellations under single service level agreements encounter handoff latency and billing reconciliation challenges that degrade customer experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VSAT Maritime Satellite Communication Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Service, Maintenance End User: Commercial Shipping, Fishing Vessels, Offshore Platforms, Recreational Boats Technology: Ka-band, Ku-band, C-band, L-band Deployment: On-premises, Cloud-based, Hybrid, Satellite |
| Companies Covered | Inmarsat Global Limited, Viasat Inc, Iridium Communications Inc, KVH Industries Inc, Speedcast International, Marlink SAS, Hughes Network Systems LLC, SES SA, Thuraya Telecommunications Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VSAT Maritime Satellite Communication Market Emerging Trajectories
Flat-panel electronically steered antennas are collapsing the mechanical complexity and maintenance burden that has constrained VSAT adoption on smaller vessel classes and offshore support craft.
Electronically steered arrays eliminate moving parts through solid-state beamforming, enabling antenna profiles below 10 centimeters height that survive helicopter downdraft and green-water impact on fast crew transfer vessels. Offshore wind service operators in the North Sea and Gulf of Mexico are specifying these terminals for turbine technician transfer craft where stabilized parabolic dishes previously failed. The technology is collapsing the vessel-size threshold for broadband VSAT from 500 gross tonnage to sub-50-ton workboats, expanding addressable fleet by an order of magnitude.
REACH chemical restrictions and RoHS substance limitations are compelling terminal manufacturers to reformulate printed circuit board solder compositions and antenna radome materials to eliminate restricted substances from maritime supply chains. The industrial consequence extends certification timelines by 8-14 months as laboratories validate alternative material thermal performance in salt-air environments. European-flagged vessels and those calling EU ports face the strictest enforcement, driving procurement preference toward terminals pre-certified under the CE marking framework.
Direct contracting between fleet operators and integrated service providers is displacing the traditional reseller channel that historically aggregated Ku-band, Ka-band, and L-band capacity from multiple satellite operators. Container lines with 100+ vessel fleets now negotiate enterprise-wide master service agreements with single accountability for global coverage, compressing margin pools for regional distributors. The pattern is most visible among Singapore-flagged and Greek-managed fleets where consolidated procurement functions have centralized technology vendor selection away from ship-manager autonomy.
VSAT Maritime Satellite Communication Market Segmentation
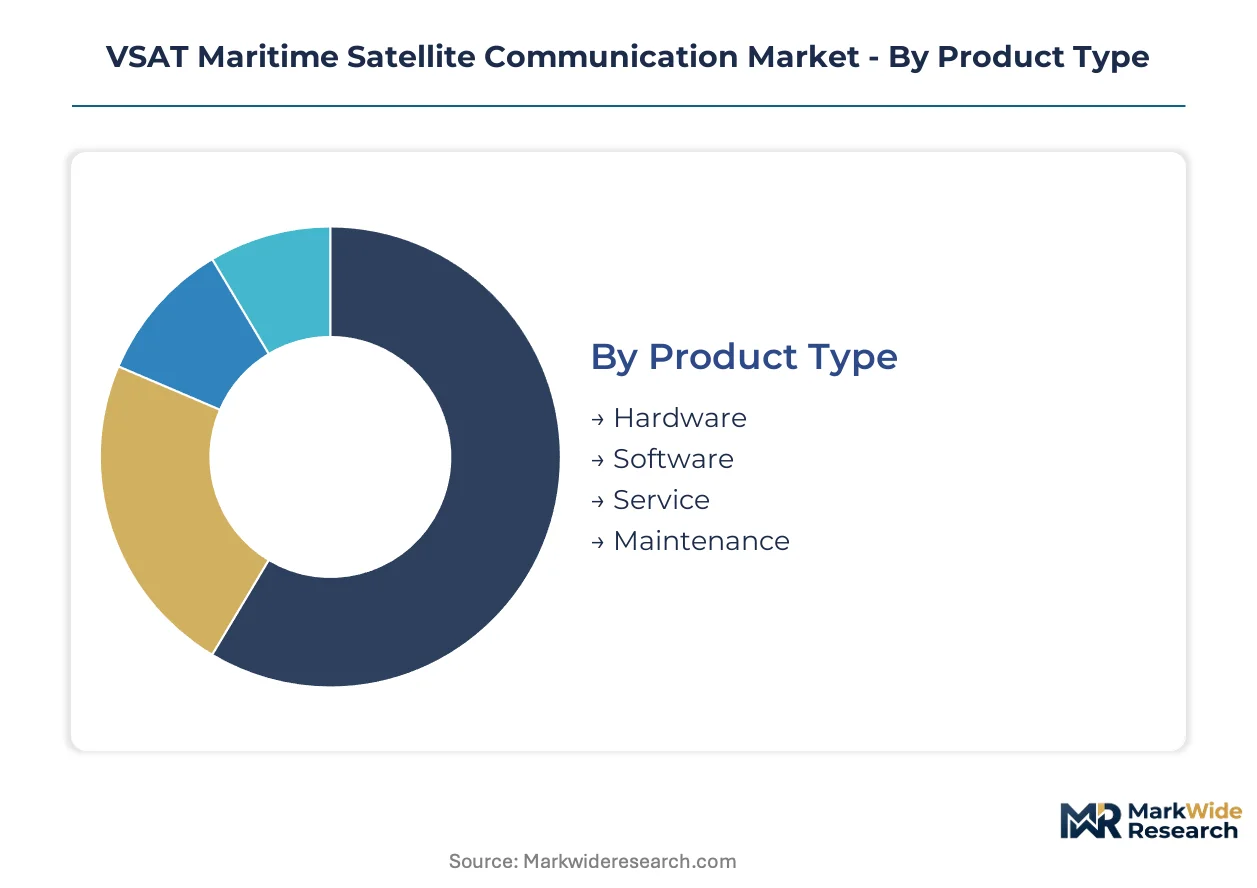
VSAT maritime markets fragment across hardware-software-service value chains, vessel class requirements, frequency bands, and infrastructure models. Procurement patterns diverge sharply between fleet operators seeking bundled service contracts and asset owners prioritizing terminal ownership.
Product Type:
Cost tier stratification separates capital-intensive terminal ownership from recurring service expenditure models favored by mid-size fleet operators.
- Hardware:Stabilized antenna platforms with gyroscopic tracking systems dominate procurement for vessels above 500 gross tonnage. Norwegian North Sea drillship operators specify cold-weather hardened terminals with enhanced salt-air corrosion resistance.
- Service:Bandwidth-as-a-service contracts now anchor margin pools as hardware commoditizes under competitive pressure from Asian manufacturers. Singapore-flagged container lines negotiate enterprise master service agreements with single-accountability coverage.
- Software:Network orchestration platforms enabling multi-orbit constellation switching.
- Maintenance:Predictive service contracts covering gyroscopic component replacement and radome integrity.
Hardware holds installed capacity. Service is rotating up the share rankings.
End User:
Application intensity varies dramatically between mission-critical offshore operations and discretionary recreational connectivity.
- Offshore Platforms:Drillship operators require continuous telemetry bandwidth exceeding 10 Mbps for real-time reservoir monitoring and remote equipment diagnostics. Norway's North Sea corridor drives specification for terminals surviving helicopter downdraft and green-water impact.
- Commercial Shipping:Container lines with 100+ vessel fleets demand pole-to-pole coverage for route optimization and crew welfare bandwidth. Greek-managed fleets centralize procurement away from ship-manager autonomy toward consolidated technology vendor selection.
- Fishing Vessels:Industrial trawler segments remain predominantly served by legacy narrowband terminals, presenting upgrade opportunity for broadband-enabled operational efficiency.
- Recreational Boats:Sub-50-ton workboats and leisure craft represent emerging addressable market as flat-panel antennas collapse size thresholds.
Commercial Shipping anchors contract value. Offshore Platforms is expanding most quickly.
Technology:
Frequency band selection determines link budget, latency tolerance, and weather resilience tradeoffs for specific route profiles.
- Ka-band:Spot-beam architectures deliver highest capacity density over busy shipping lanes through frequency reuse. Viasat and other operators compete on collapsing cost-per-bit economics that force legacy contract renegotiations.
- Ku-band:Established global footprint with proven rain-fade margins maintains preference for routes through tropical precipitation zones.
- L-band:Inmarsat heritage systems anchor long-term contracts requiring pole-to-pole coverage and terminal simplicity, though bandwidth constraints limit application scope.
- C-band:Resilience to heavy rain fade supports tropical route requirements, though spectrum reallocation uncertainty at WRC proceedings creates procurement hesitation.
Ku-band holds installed capacity. Ka-band is rotating up the share rankings.
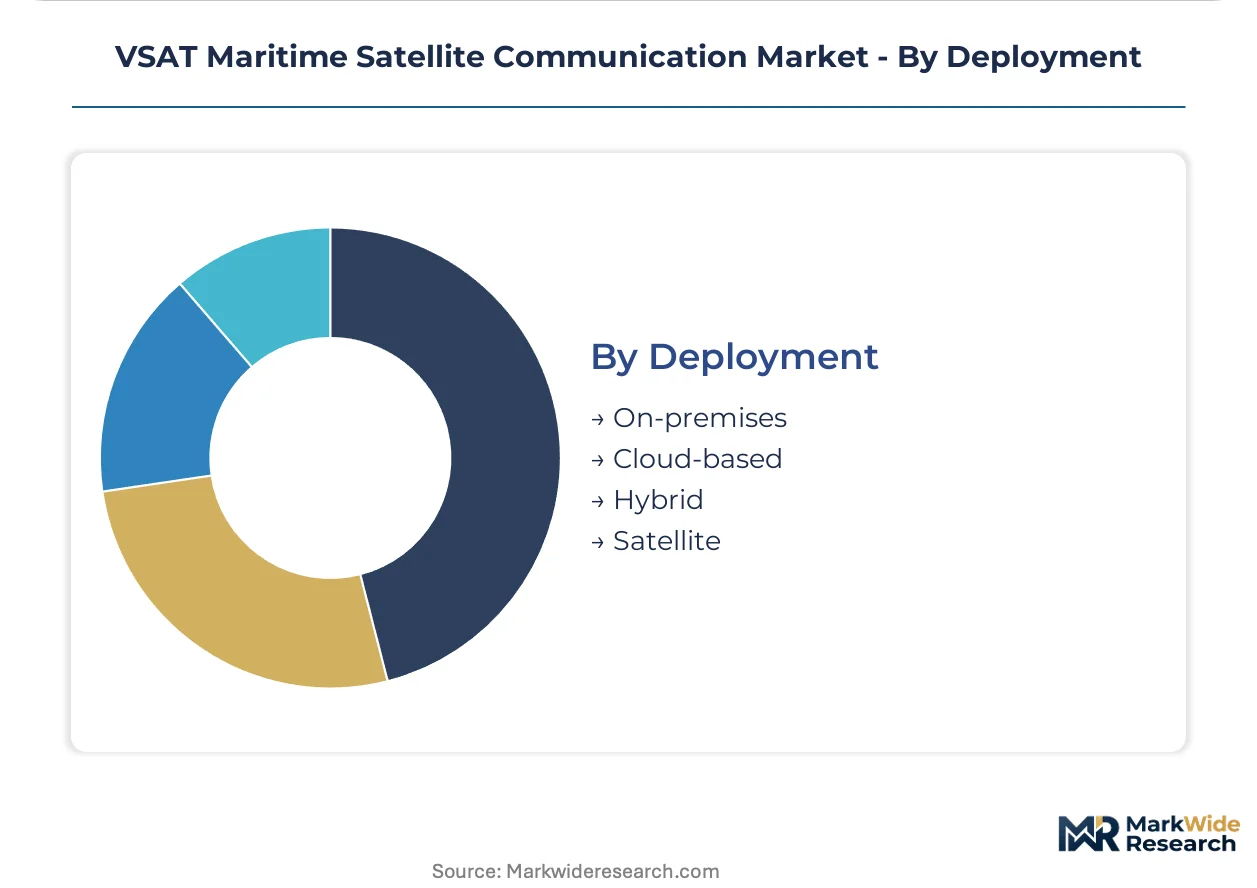
Deployment:
Infrastructure model selection reflects fleet digital maturity and cybersecurity risk tolerance.
- Cloud-based:Centralized network management platforms enable fleet-wide policy enforcement and real-time traffic optimization from shore-based operations centers.
- Hybrid:Edge computing aboard vessels with cloud synchronization accommodates intermittent connectivity and latency-sensitive autonomous navigation systems.
- On-premises:Dedicated terminal ownership with captive maintenance capabilities suits state-affiliated fleets with data sovereignty requirements.
- Satellite:Direct satellite link without terrestrial intermediary remains default for deep-ocean routes beyond coastal cellular coverage.
On-premises holds installed capacity. Cloud-based is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal expansion and Singapore's Tuas Mega Port anchor maritime traffic corridors that drive VSAT terminal demand across three continents.
United States
Gulf of Mexico drillship operators and Houston-based fleet managers require Ka-band capacity for real-time telemetry. The FCC's maritime radio equipment authorization rules mandate thermal performance certification for salt-air environments. Terminal manufacturers concentrate validation laboratories in Houston and New Orleans to serve offshore platform procurement cycles.
Norway
North Sea oil corridor drillships demand continuous connectivity exceeding legacy L-band limits for remote asset management. The EU's F-Gas Regulation compels vessel emission monitoring through certified VSAT terminals. Stavanger and Bergen host engineering clusters where operators specify cold-weather hardened antennas for helicopter downdraft survival.
Singapore
Container lines with 100+ vessel fleets negotiate enterprise master service agreements for pole-to-pole coverage. The Maritime and Port Authority of Singapore enforces cybersecurity standards for vessel communication systems. Tuas Port development concentrates procurement functions for Greek-managed and Singapore-flagged fleets seeking single-accountability global coverage.
Japan
Precision gyroscopic tracking component suppliers face recruitment gaps for RF engineers capable of phased-array antenna design. METI industrial standards shape terminal electromagnetic compatibility requirements. Yokohama and Nagoya manufacturing clusters supply stabilized antenna platforms for vessels above 500 gross tonnage.
Brazil
Pre-salt deepwater drillship operators require broadband connectivity beyond coastal cellular reach. ANVISA and telecommunications regulators coordinate equipment approval frameworks for offshore platform digitization. Rio de Janeiro serves as procurement hub where energy operators specify multi-orbit capable terminals for autonomous navigation support.
VSAT Maritime Satellite Communication Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in antenna stabilization and RF engineering. The vendor base organizes into three tiers: satellite operators with owned capacity, service aggregators managing multi-band contracts, and terminal manufacturers supplying hardware to fleet operators. Strategic archetypes include L-band heritage players anchoring long-term container line contracts, Ka-band capacity densifiers competing on cost-per-bit economics, and multi-orchestrator platforms unifying GEO, MEO, and LEO under single service level agreements. Competitive moves concentrate on direct fleet-operator contract displacement of traditional resellers and flat-panel electronically steered antenna development to collapse vessel-size thresholds.
Within the L-band heritage tier, Inmarsat Global Limited and Iridium Communications Inc represent operators with pole-to-pole coverage capabilities. Ka-band capacity densification is exemplified by Viasat Inc, which competes through spot-beam frequency reuse over busy shipping lanes. Among multi-orchestrator service providers, Marlink SAS occupies a position aggregating Ku-band, Ka-band, and L-band under unified service level agreements for consolidated procurement functions.
| Leading Market Players |
|---|
| Inmarsat Global Limited |
| Viasat Inc |
| Iridium Communications Inc |
| KVH Industries Inc |
| Speedcast International |
| Marlink SAS |
| Hughes Network Systems LLC |
| SES SA |
| Thuraya Telecommunications Company |
| Others |
Supply Flow & Price Mechanics
Ka-band spot-beam overcapacity over North Atlantic shipping lanes is compressing bandwidth pricing while forcing terminal manufacturers to absorb gyroscopic component cost volatility. This utilization imbalance concentrates pricing power with satellite operators holding orbital slots while squeezing hardware margins for antenna platform suppliers.
Pricing Analysis
Volume-discount tiering structures separate enterprise master service agreements for 100+ vessel fleets from per-vessel contracts for mid-size operators. Pricing stratifies across premium certified tiers for EU F-Gas Regulation compliance, standard multi-band bundles, and economy single-frequency options. Cost compression in the economy tier is intensifying because Asian manufacturers are commoditizing stabilized antenna platforms. Mid-size fishing fleet operators exhibit highest price sensitivity, while North Sea drillship contractors prioritize cold-weather certification over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Japanese precision gyroscope specialists and German RF component foundries holding critical stabilization platform capacity. Terminal assembly draws from Thailand, Vietnam, and Mexico for radome fabrication and printed circuit board population. Single-source vulnerability in phased-array antenna RF engineering creates procurement risk for flat-panel terminal launches. Distribution runs through integrated service providers that displace traditional resellers for direct fleet-operator contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bandwidth-as-a-service contracts are expanding faster than terminal hardware sales, creating service-attach opportunities where recurring revenue pools exceed upfront equipment margins. Network orchestration software and predictive maintenance subscriptions represent the fastest-growing revenue layers.
For Market Incumbents: Pre-empt LEO constellation integration by acquiring multi-orbit orchestration software capabilities before flat-panel antenna commoditization erodes hardware differentiation. Secure long-term Ka-band capacity leases over Arctic routes where terrestrial infrastructure gaps protect pricing power. Anchor pole-to-pole coverage contracts with container lines through bundled cybersecurity certification under IEC 62443 standards. For New Entrants and Emerging Players: Industrial trawler and longline fishing fleets in Southeast Asia and West Africa represent the most penetrable entry point, as legacy Inmarsat C terminal saturation leaves broadband upgrade demand unaddressed. Flat-panel electronically steered antennas for sub-50-ton workboats collapse vessel-size thresholds that previously excluded smaller craft. Partner with offshore wind service operators for turbine technician transfer craft specifications that bypass established maritime distribution channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-orchestrator service providers aggregating GEO, MEO, and LEO capacity under unified service level agreements. Long-term viability over a decade horizon rests on cybersecurity certification premiums and polar route first-mover positioning. Monitor WRC spectrum reallocation proceedings as the critical inflection signal for terminal manufacturer valuation multiples. Quarterly review of FCC maritime equipment authorization timelines and EU F-Gas enforcement patterns is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-orbit Platform Integration | Unifying GEO, MEO, and LEO capacity under single SLAs commands pricing premiums from consolidated fleet procurement functions. |
| Flat-panel Antenna Development | Electronically steered arrays eliminate mechanical complexity and expand addressable fleet to sub-50-ton vessel classes. |
| Arctic Route Terminal Certification | Polar-optimized cold-weather specifications capture first-mover advantage on Russia's Northern Sea Route and Canada's Northwest Passage. |
| Cybersecurity Stack Certification | IEC 62443 industrial cybersecurity standards enable service providers to differentiate through certified secure communication offerings. |
| Direct Fleet-operator Contracting | Enterprise master service agreements with Singapore-flagged and Greek-managed fleets displace traditional reseller channel margins. |
Methodological Framework
The analysis maps hardware terminal manufacturing, bandwidth service provisioning, and network orchestration software segments, each validated through fleet procurement directors, satellite operator capacity planners, and terminal engineering leads. Primary interviews with offshore platform operations managers, maritime regulatory compliance officers, and RF antenna design specialists combined with secondary validation against FCC equipment authorization databases, EU F-Gas Regulation implementation reports, and World Radiocommunication Conference proceedings. Bottom-up vessel fleet segmentation triangulated against top-down satellite capacity supply assessments.
Assumptions held fixed include current orbital slot allocations and existing maritime equipment certification frameworks, while variables included LEO constellation deployment schedules and spectrum reallocation outcomes. The projection horizon spans hardware commoditization curves, service contract renewal cycles, and technology band migration patterns across vessel class segments, frequency band adoption, and deployment infrastructure models. CAGRs derived from installed base expansion rates and average revenue per vessel trends, with specific inputs for North Sea drillship bandwidth intensity and container line master service agreement penetration.
Practitioners should monitor WRC spectrum reallocation decisions, LEO constellation launch cadence, and EU F-Gas enforcement intensity for early signals requiring forecast revision. Quarterly review of FCC maritime equipment authorization timelines, Norwegian North Sea drilling permit activity, and Singapore Tuas Port procurement centralization metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
All-Electric Propulsion Satellites Market
Satellite
Spain Satellite Imagery Services Market
Satellite
UAE Satellite Communication Market
Satellite
Global Broadband Satellite Services Market
Satellite
Germany Satellite Communications Market
Satellite
Satellite Communications Service Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Low-Cost Satellite Market
Satellite
Europe Satellite Bus Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
Indonesia Satellite Communications Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Satellite Connectivity Market