
 Salad Dressings Market | 2026-2036
Salad Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Salad Dressings Market Intelligence
Food service procurement channels is reconfiguring how salad dressing manufacturers allocate production capacity and negotiate contract terms. The Kraft Heinz Company leverages its refrigerated distribution network to dominate institutional accounts. Unilever PLC anchors its position through global condiment infrastructure that sustains volume commitments across multiple continents. Kewpie Corporation specializes in emulsion technology for Asian food service formats, differentiating its technical specifications from Western-style formulations.
Salad dressings are stabilized oil-in-water or water-in-oil emulsions containing edible oils, acidulants, emulsifiers, and flavoring systems, manufactured through high-shear homogenization to achieve particle sizes below 5 microns for shelf stability. Their primary commercial purpose is to standardize flavor delivery and moisture retention in prepared salads and protein bowls across retail and food service environments. Vinaigrette formulations lead volume in European retail due to perceived health positioning, while mayonnaise-based dressings occupy the largest margin pool in North American food service procurement. Pouch packaging for single-serve applications represents the fastest-growing structural segment as quick service restaurants reduce waste and labor costs in assembly-line kitchens.
FDA standards of identity for mayonnaise and salad dressing enforce minimum vegetable oil thresholds and restrict filler ingredients, directly constraining reformulation strategies for cost-optimized products. EU Regulation 1169/2011 on food information to consumers mandates detailed allergen labeling and nutritional declarations that manufacturers must integrate into label design and supply chain verification systems. Clean-label certification requirements from USDA Organic and Non-GMO Project verification are forcing ingredient sourcing changes that ripple through oil supplier contracts and emulsifier selection processes. Stakeholders must monitor how dual regulatory pressures from FDA identity standards and EU disclosure rules will reshape competitive advantage between legacy brands and private-label entrants.
Market Dynamics
Clean-label reformulation pressures from FDA and EU regulations are compressing ingredient declarations and forcing manufacturers to reconfigure emulsifier sourcing, sodium reduction pathways, and supply chain verification systems across refrigerated and shelf-stable production lines.
Growth Catalysts
- Quick Service Restaurant Expansion:Fast-casual chains are broadening menu applications for single-serve pouch formats, driving procurement volume commitments for both refrigerated and ambient-stable dressing categories.
- FDA Standards of Identity:Regulatory clarity on mayonnaise and salad dressing definitions creates compliance benchmarks that premium private-label entrants use to position against legacy brands.
- Emulsion Technology Advances:High-shear homogenization achieving sub-5-micron particle sizes is extending shelf stability without synthetic stabilizers, enabling cleaner label claims.
Market Restraints
- Vegetable Oil Input Volatility:Price swings in soybean and canola oil contracts directly compress margin pools for mayonnaise-based formulations dominating North American food service.
- EU Allergen Disclosure Mandates:Regulation 1169/2011 requires granular supply chain verification for emulsifier and flavoring systems, extending compliance timelines and certification costs.
- Vinaigrette Substitution Threat:Simple oil-and-vinegar preparations made in-house by institutional kitchens displace manufactured dressing volumes in European contract catering.
Strategic Opportunities
- Underpenetrated Asian Food Service:Kewpie Corporation's emulsion specialization for regional formats demonstrates technical pathways for Western manufacturers to adapt viscosity and flavor profiles.
- USDA Organic Certification Tailwind:Organic oil sourcing requirements are creating captive supply relationships that lock in premium positioning across retail refrigerated cases.
- Single-Serve Pouch Channel Innovation:Quick service restaurants are adopting portion-controlled packaging to reduce assembly-line waste and labor costs, opening new contract manufacturing demand.
Industry Challenges
- Clean-Label Reformulation Skill Gap:Food scientists capable of replacing modified food starches and synthetic emulsifiers with functional natural alternatives command scarcity premiums in labor markets.
- Dual Jurisdiction Compliance Timelines:Simultaneous FDA identity standard adherence and EU disclosure rule integration extends product development cycles and strains regulatory affairs capacity.
- Legacy Equipment Retrofit Costs:Transitioning high-shear homogenization lines between oil-in-water and water-in-oil emulsion formats requires capital-intensive reconfiguration of cooling and separation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salad Dressings Market |
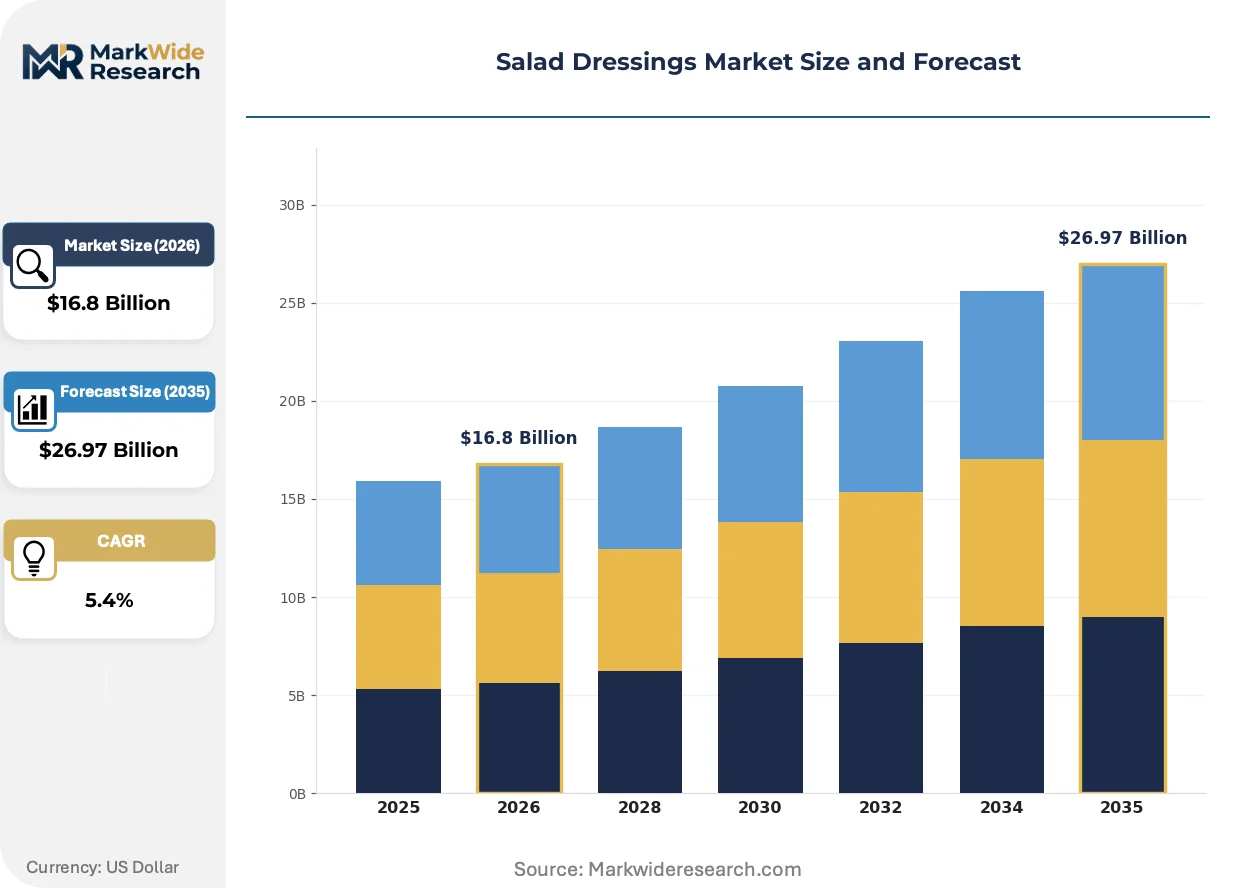
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinaigrette, Mayonnaise-Based, Creamy, Citrus-Based, Oil-Based Packaging Type: Bottle, Sachet, Jar, Pouch, Tub Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores, Food Service Providers Customer Type: Households, Quick Service Restaurants, Catering Companies, Health Food Stores |
| Companies Covered | T. Marzetti Company, Clorox Company, Unilever PLC, Conagra Brands, General Mills, The Kraft Heinz Company, Kewpie Corporation, McCormick & Company, Ken’s Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salad Dressings Market Strategic Shifts & Innovations
Reformulation science and packaging engineering are converging to reshape competitive advantage, with regulatory disclosure requirements and food service operational demands driving simultaneous innovation across ingredient systems and distribution formats.
High-pressure processing technology is collapsing thermal pasteurization requirements for refrigerated dressings. Fast-casual chains with regional distribution networks are adopting cold-chain validated pouch formats at accelerating rates. This technology is collapsing the shelf-life gap between clean-label and conventional formulations, compressing the premium pricing window for legacy stabilized products.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration infrastructure transitions across European food service distribution. Industrial cold-chain operators face retrofit deadlines that favor shelf-stable dressing procurement over refrigerated alternatives. Central and Eastern European contract catering segments are responding by consolidating procurement around ambient-stable mayonnaise and vinaigrette portfolios.
Food service buyers are unbundling flavor customization from base emulsion supply. Institutional accounts now specify proprietary seasoning blends layered over manufacturer-provided neutral bases, displacing finished dressing procurement. This pattern is most visible in United States K-12 and healthcare segments where sodium targets and allergen controls vary by district and facility.
Salad Dressings Market Segmentation
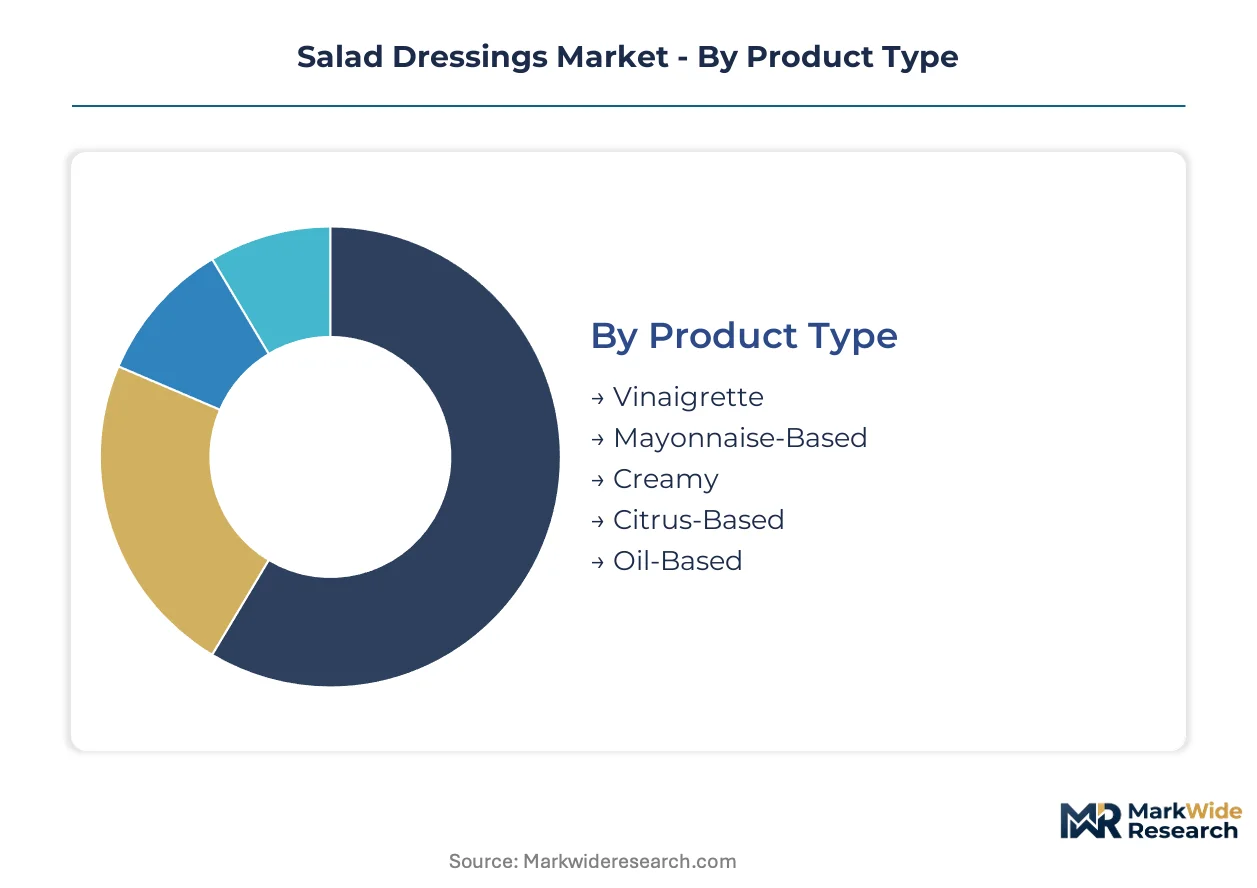
Salad dressing manufacturers configure production lines around emulsion stability requirements and cold-chain constraints. Each segmentation dimension reveals distinct margin structures and procurement patterns across retail and food service channels.
Product Type:
Cost tier stratification separates commodity mayonnaise from premium refrigerated formats.
- Vinaigrette:Oil-in-water emulsions with acidulant ratios between 3:1 and 4:1 oil-to-vinegar. European retail demand concentrates in France and Italy where household preparation traditions sustain manufactured format acceptance.
- Mayonnaise-Based:Egg-yolk stabilized emulsions containing minimum 65% vegetable oil by weight to meet FDA standards of identity. North American food service procurement anchors volume, with quick service restaurants specifying viscosity ranges for automated dispensing equipment.
- Creamy:Dairy or dairy-alternative base emulsions with modified starch or gum stabilizers.
- Citrus-Based:High-acid formulations with pH below 4.6 enabling ambient shelf stability.
- Oil-Based:Minimal water phase dressings requiring no emulsifier systems.
Mayonnaise-Based holds installed capacity. Vinaigrette is rotating up the share rankings.
Packaging Type:
Application context determines structural format selection across portion control and shelf-life requirements.
- Pouch:Multi-layer polymer laminates with oxygen transmission rates below 0.5 cc/m²/day. Quick service restaurant adoption is climbing fastest as assembly-line kitchens eliminate bottle handling and waste streams.
- Bottle:PET or glass containers with 28-38mm neck finishes for retail gravity-fed dispensing. United States supermarkets anchor procurement volume, though shelf space compression is favoring squeeze formats over traditional cylindrical designs.
- Sachet:Single-serve flexible portions for institutional catering.
- Jar:Wide-mouth glass for premium positioning and reuse value.
- Tub:Refrigerated deli-style containers for food service bulk.
Bottle holds installed capacity. Pouch is rotating up the share rankings.
Distribution Channel:
Customer type concentration varies sharply between self-service retail and contract food service procurement.
- Food Service Providers:Broadline distributors and specialty purveyors managing temperature-controlled logistics. United States institutional accounts specify dual-temperature capabilities for refrigerated and shelf-stable portfolios.
- Supermarkets:Center-store and perimeter refrigerated cases with planogram-managed facings. Clean-label certification requirements from USDA Organic are forcing slotting fee renegotiations for reformulated lines.
- Convenience Stores:Grab-and-go refrigerated sets with high-velocity SKU requirements.
- Online Retailers:Direct-to-consumer ambient shipping with ice-pack protocols.
- Specialty Stores:Premium and import-focused independent retailers.
Supermarkets hold installed capacity. Food Service Providers is rotating up the share rankings.
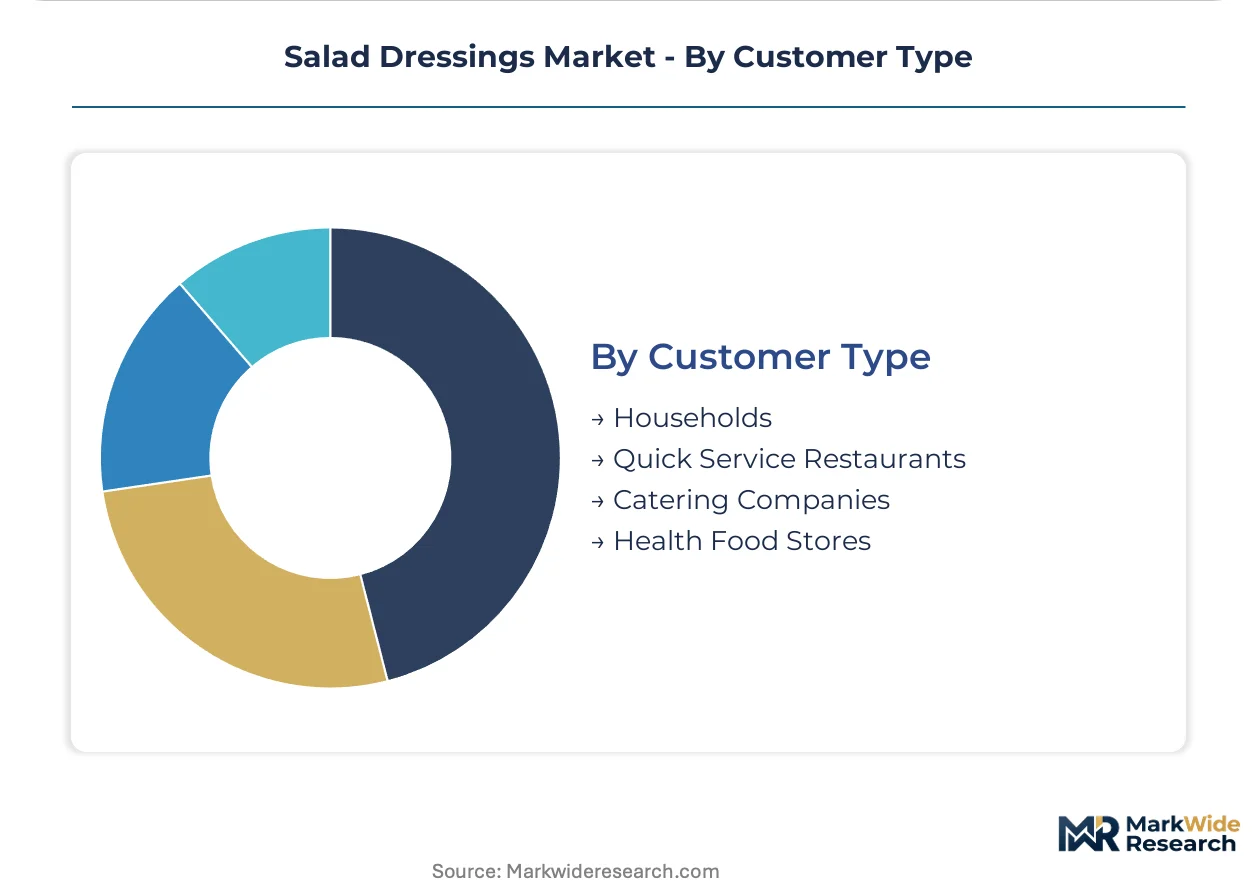
Customer Type:
Volume scale separates household unit purchases from pallet-scale institutional commitments.
- Quick Service Restaurants:Chain-level procurement with standardized specification sheets and approved manufacturer lists. Pouch format adoption is expanding most quickly as operators reduce labor seconds per salad assembly.
- Households:Individual and family-size purchases through retail channels. United States consumers show concentration in premium refrigerated segments with shorter ingredient declarations.
- Catering Companies:Event-scale production with batch customization requirements.
- Health Food Stores:Certified organic and non-GMO positioned assortments.
Households hold installed capacity. Quick Service Restaurants is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA standards of identity for mayonnaise and salad dressing anchor regulatory frameworks in the United States, where food service procurement volumes and premium refrigerated retail segments concentrate category development. Clean-label pressures from EU disclosure rules and Asian emulsion technology advances are reshaping competitive positioning across major demand centers.
United States
Quick service restaurant chains drive single-serve pouch adoption through automated assembly-line specifications. FDA identity standards enforce minimum vegetable oil thresholds that constrain cost-optimized reformulation strategies. Chicago and Dallas-Fort Worth metropolitan areas concentrate broadline distributor headquarters managing temperature-controlled logistics for institutional accounts.
Japan
Specialized emulsion technology for regional food service formats sustains technical differentiation from Western-style formulations. METI industrial standards guide manufacturing equipment specifications for high-shear homogenization systems. Osaka and Nagoya manufacturing clusters produce viscosity-modified dressings for bento and prepared meal applications.
Germany
EU F-Gas Regulation phase-down schedules accelerate refrigeration infrastructure transitions favoring shelf-stable procurement. ECHA chemical safety assessments influence emulsifier selection processes for clean-label certification pathways. Bavaria and North Rhine-Westphalia host reformulation R&D facilities serving Central European contract catering networks.
France
Household preparation traditions sustain manufactured vinaigrette acceptance in retail channels with oil-to-vinegar ratios between 3:1 and 4:1. ANSM food safety oversight extends compliance timelines for allergen disclosure verification systems. The Île-de-France region anchors procurement volumes for institutional catering serving healthcare and education sectors.
China
Western quick service restaurant expansion creates demand for standardized flavor delivery systems in protein bowl applications. SAMR food labeling regulations mandate nutritional declaration formats that manufacturers integrate into export-oriented production lines. Shanghai and Guangzhou cold-chain logistics hubs facilitate refrigerated dressing distribution to fast-casual chain locations.
Salad Dressings Market Key Industry Players
Multinational condiment conglomerates and specialized emulsion technology firms split the market through divergent capability investments. Scale-driven players leverage refrigerated distribution networks to dominate institutional procurement contracts. Technical specialists concentrate on regional flavor profiles and viscosity specifications. Dominant competitive moves include backward integration into oil supply contracts and portfolio diversification across pouch packaging formats.
Within the multinational tier, Unilever PLC and The Kraft Heinz Company exemplify scale-driven positioning through global condiment infrastructure and refrigerated distribution networks. Kewpie Corporation occupies a specialized position representing technical emulsion capabilities for Asian food service formats. These three anchors demonstrate how geographic origin and structural focus determine competitive archetype alignment.
| Leading Market Players |
|---|
| T. Marzetti Company |
| Clorox Company |
| Unilever PLC |
| Conagra Brands |
| General Mills |
| The Kraft Heinz Company |
| Kewpie Corporation |
| McCormick & Company |
| Ken's Foods Inc. |
| Others |
Cost & Logistics Intelligence
Vegetable oil contract volatility between North American crushers and Asian export markets compresses margin pools across mayonnaise-based formulations while simultaneously forcing manufacturers toward captive supply relationships and regional production hedging strategies.
Pricing Analysis
Configured-to-order spreads separate institutional pouch contracts from standard retail bottle pricing by fifteen to thirty percent. Three-tier pricing structure across premium refrigerated, standard shelf-stable, and economy private-label levels anchors the market, with USDA Organic certification commanding slotting fee premiums in United States supermarkets. Cost compression in mayonnaise-based formulations intensifies because soybean oil futures swing with biofuel policy shifts. Quick service restaurant procurement teams exhibit highest price sensitivity, while healthcare institutional accounts prioritize allergen-compliant supply over per-unit cost.
Supply Chain Analysis
Tariff exposure between United States and Canadian canola oil suppliers dominates supply chain risk calculus for North American manufacturers. Production gravity centers on United States Midwest crushing facilities, Argentina soybean processing complexes, and Ukrainian sunflower oil extraction plants. Formulation stability draws from egg yolk powder, modified food starch, and natural gum dependencies. Single-source vulnerability concentrates in high-oleic sunflower oil for clean-label lines. Distribution runs through broadline distributors with dual-temperature capabilities serving quick service restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Salad dressing procurement is consolidating around platform specifications where neutral base emulsions interoperate with proprietary seasoning systems, mirroring software middleware economics.
For Market Incumbents: Entrench refrigerated distribution advantages by locking multi-year pouch supply contracts with top-ten quick service restaurant chains. Deepen backward integration into high-oleic oil crushing capacity to insulate margin pools from commodity volatility. FDA identity standard clarity offers defensive moats against private-label entrants attempting cost-optimized reformulation.
For New Entrants and Emerging Players: Asian quick service restaurant formats in Southeast Asia represent the most penetrable entry point for viscosity-modified emulsion specialists. USDA Organic certification gaps in Central European contract catering create second-tier white-space. Lead with high-pressure processing technology partnerships to collapse shelf-life gaps without synthetic stabilizers.
For Investors and Strategic Acquirers: Regional emulsion technology boutiques with captive Asian food service relationships offer asymmetric consolidation value. Long-term viability hinges on clean-label reformulation capability scarcity extending through the next decade. Watch EU F-Gas Regulation retrofit deadlines as inflection signal for shelf-stable portfolio reweighting.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oil Supply | Captive crushing capacity locks input costs against biofuel-driven vegetable oil volatility. |
| Pouch Packaging Line Expansion | Quick service restaurant automation specifications favor multi-layer laminate portion control. |
| Clean-Label Certification Investment | USDA Organic and Non-GMO Project verification commands slotting fee renegotiation leverage. |
| High-Pressure Processing Adoption | Cold-chain validation without thermal pasteurization collapses legacy shelf-life premiums. |
| Asian Format Viscity Specialization | Bento and prepared meal applications require emulsion stability at ambient distribution temperatures. |
Research Approach
Operator-level perspectives from food service procurement directors, plant operations managers at condiment manufacturers, broadline distributor category buyers, and regulatory affairs specialists anchored the qualitative base. Secondary validation drew from FDA standards of identity filings, USDA Organic certification databases, EU Regulation 1169/2011 implementation guidance, and refrigerated logistics trade association reports. Bottom-up volume modeling triangulated against top-down category spending estimates from food service expenditure surveys.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions spanned emulsion type, packaging format, distribution channel temperature requirements, and customer procurement scale. CAGRs derived from rolling average input cost assumptions and elasticity-adjusted volume responses. Forecast inputs incorporated vegetable oil futures curve shapes and quick service restaurant outlet expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in food service labor cost inflation or biofuel mandate intensity would shift the trajectory. Forecasts reflect documented assumptions on regulatory stability and cold-chain infrastructure investment continuity. Material shifts in FDA identity standard enforcement or EU F-Gas Regulation phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Global Fish Sauce Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
Soups and Sauces Market