
 Cooking Sauces Market | 2026-2036
Cooking Sauces Market Size, Share, and Industry Trends Forecast 2026-2036
Cooking Sauces Market Analysis
EU F-Gas Regulation is shifting refrigeration and processing standards for sauce manufacturers exporting into Europe, raising compliance costs for cold-chain-dependent production. McCormick & Company leverages its spice-sourcing infrastructure to control input costs across multiple sauce categories. Unilever sustains broad retail distribution through its global brand portfolio. Kikkoman Corporation anchors its position in fermented soy sauce through century-old brewing craftsmanship.
Cooking sauces comprise liquid, semi-liquid, or viscous condiment preparations formulated from tomatoes, soybeans, vinegar, oils, spices, and hydrocolloid stabilizers, manufactured through thermal processing, fermentation, or cold blending to deliver flavor, moisture, and visual appeal to prepared foods. Pasta sauce and soy sauce categories command the largest existing volume bases, while marinades represent the fastest-expanding segment as home cooks and food service operators seek pre-flavored protein solutions. Pouch packaging is gaining share against glass jars in convenience-oriented channels, though bottles retain dominance in premium supermarket placements where shelf aesthetics drive selection.
FDA labeling requirements in the United States, EU EFSA additive approvals under REACH-aligned frameworks, and Japan's JIS standards for food manufacturing equipment collectively shape formulation choices, import eligibility, and capital investment decisions for sauce producers. China's SAMR enforces increasingly stringent national food safety standards that foreign entrants must satisfy for market access. Stakeholders must monitor evolving sodium-reduction mandates and single-use packaging restrictions as these dual regulatory vectors will determine which product formats and ingredient systems retain channel access across major economies.
Market Dynamics
Clean-label reformulation pressures across the European Union and North America are forcing sauce manufacturers to eliminate artificial stabilizers and disclose ingredient sourcing, compressing margins while creating tiered product differentiation.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain-dependent sauce producers are retrofitting processing facilities to meet fluorinated gas phase-down schedules, creating upgrade demand for refrigeration equipment and compliant thermal processing lines.
- Food service menu expansion:Ethnic and premium sauce applications are proliferating in United States and China restaurant chains, pulling volume through food service distribution channels.
- Fermentation biotechnology:Controlled microbial cultivation is shortening soy sauce and umami-base production cycles while improving batch consistency for artisanal positioning.
Market Restraints
- Tomato paste input volatility:Concentrated tomato supply from California and Xinjiang provinces creates price squeeze risk for pasta sauce manufacturers during drought cycles.
- Glass jar supply concentration:Premium supermarket channel aesthetics sustain bottle dependency despite pouch packaging gains, locking producers into energy-intensive packaging formats.
- Sodium reduction technical ceiling:FDA and EFSA-aligned sodium targets degrade taste profiles in soy sauce and tomato categories without acceptable clean-label salt replacers.
Strategic Opportunities
- Marinade segment acceleration:Pre-flavored protein solutions for home cooks and food service operators represent the fastest-expanding sauce category by application.
- India FSSAI clean-label pathway:India's food safety regulator is formalizing additive disclosure standards that reward early reformulators with retail shelf preference.
- Pouch-to-bottle hybrid formats:Stand-up spouted pouches with premium finishing are penetrating convenience channels without sacrificing shelf aesthetics.
Industry Challenges
- Flavor chemist talent scarcity:Clean-label reformulation requires rare expertise in natural hydrocolloid stabilization and fermentation-derived umami systems.
- Dual certification timelines:Simultaneous FDA and SAMR approval processes for new sauce entrants create nine-to-fourteen month market access delays.
- Cold-chain reconfiguration:EU F-Gas compliance mandates capital-intensive refrigeration replacement across export-oriented production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooking Sauces Market |
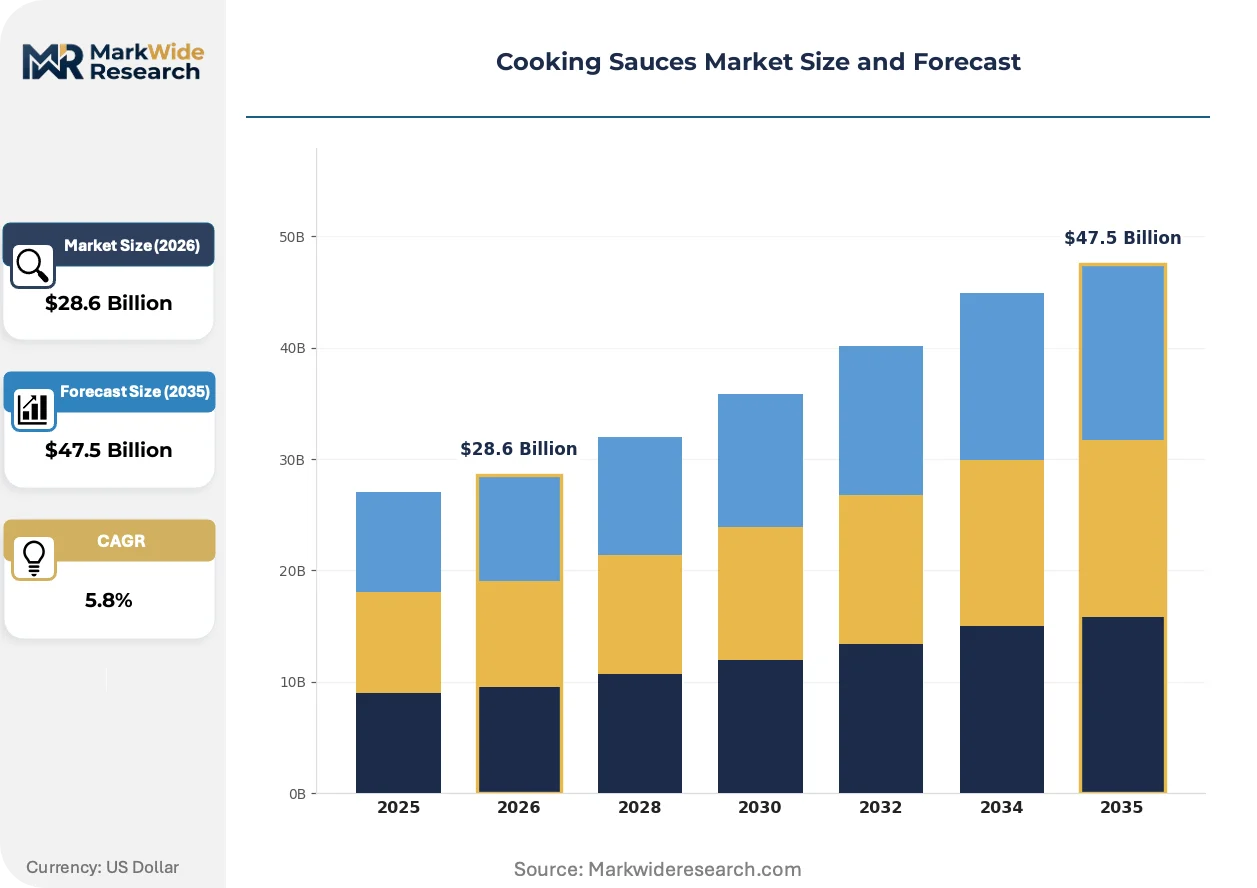
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Barbecue, Soy Sauce, Marinades, Pasta Sauce Flavor Profile: Spicy, Sweet, Savory, Tangy Packaging Type: Bottles, Jars, Pouches, Tubs Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Food Service |
| Companies Covered | McCormick & Company, General Mills, Unilever, Campbell Soup Company, Kikkoman Corporation, Nestle, Conagra Brands, Barilla, Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooking Sauces Market Emerging Trajectories
Fermentation-based processing methods and packaging format innovation are compressing traditional production timelines while reshaping how sauces reach food service and retail buyers.
Precision fermentation for umami base production is expanding into mainstream sauce manufacturing. Mid-tier sauce producers in Germany and Japan are adopting bioreactor-cultured flavor concentrates to reduce reliance on aged soy extraction. This biotechnology is expanding into cost-sensitive segments previously reserved for traditional brewing methods, compressing the premium-commodity price gap.
EU F-Gas Regulation phase-down schedules are accelerating thermal processing equipment replacement across export-oriented facilities. Sauce manufacturers serving European markets must eliminate hydrofluorocarbon-dependent refrigeration from blending and storage operations. Cold-chain-dependent categories including refrigerated salsa and fresh pesto face the steepest compliance cost escalation, with producers in China and the United States front-loading capital expenditure to maintain channel access.
Home cook pre-flavoring behavior is fragmenting procurement patterns across retail and food service channels. Marinade and simmer-sauce kits are displacing scratch cooking in United States and United Kingdom households, pulling volume through club stores and meal-kit aggregators. This channel rotation is most visible in suburban markets where time-compressed consumers trade preparation control for convenience without sacrificing ethnic authenticity claims.
Cooking Sauces Market Segmentation
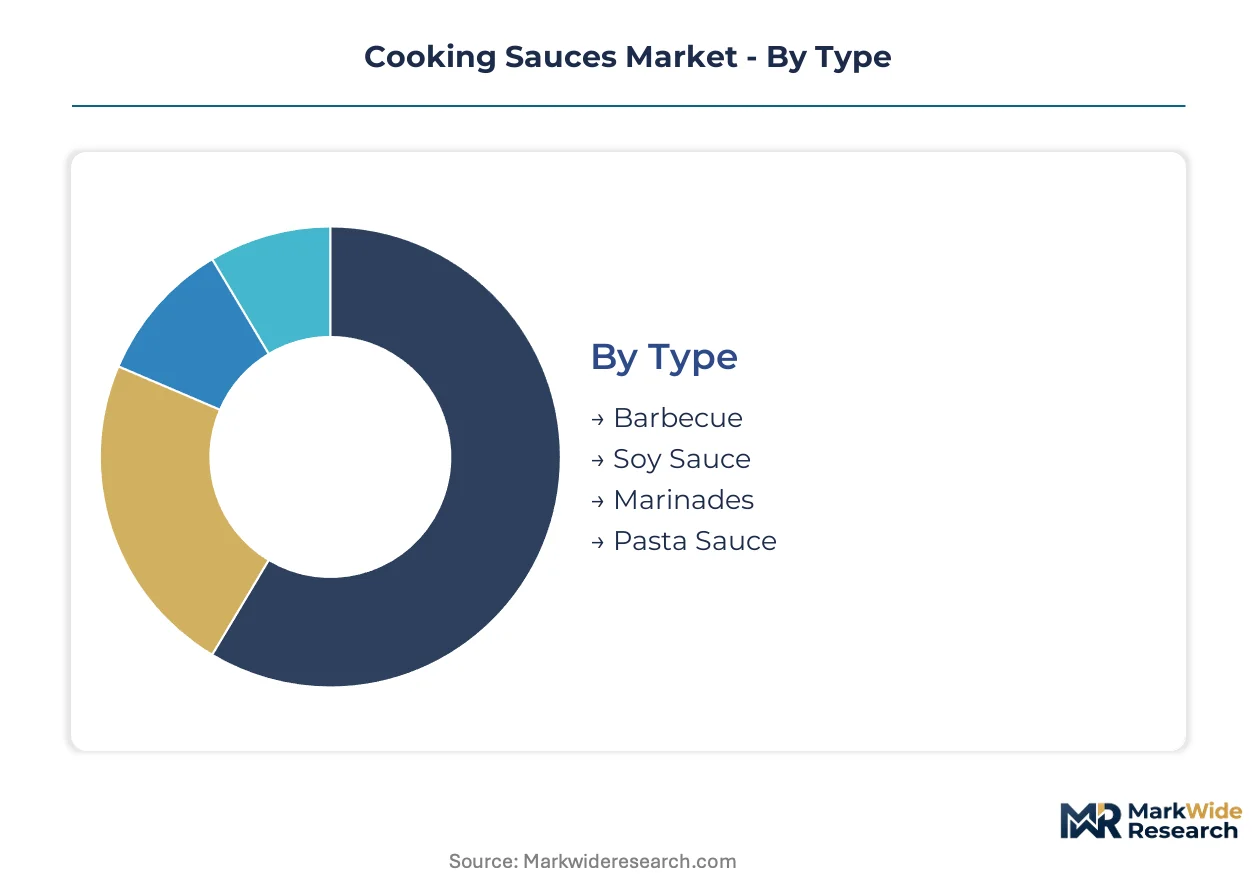
Cooking sauces fragment across multiple axes that determine margin structure and channel access. Type and packaging format choices lock manufacturers into specific capital equipment and cold-chain configurations, while flavor positioning and distribution strategy dictate which regulatory frameworks govern compliance.
Type:
Volume concentration and application method separate these categories, with fermented and thermal-processed variants requiring fundamentally different production footprints.
- Pasta Sauce:Tomato-based formulations with hydrocolloid stabilization for viscosity control. United States retail channels drive the bulk of volume, though California drought cycles periodically squeeze input costs for concentrated paste suppliers.
- Soy Sauce:Fermented soybean and wheat preparations aged through traditional koji cultivation or accelerated bioreactor methods. China's SAMR enforces stringent residue limits that shape import eligibility for foreign brewers.
- Marinades:Acidulated emulsions for protein pre-flavoring, spanning citrus, vinegar, and enzymatic tenderizer variants. Home cooks in suburban United States markets and food service operators in China are pulling volume through club stores and restaurant distributors.
- Barbecue:Smoke-infused tomato or vinegar bases with regional style differentiation. Southern United States flavor profiles dominate formulation R&D spending.
Pasta sauce leads volumes today; marinades are gaining share fastest.
Flavor Profile:
Palate preference maps directly to demographic concentration and ethnic cuisine adoption curves, with heat tolerance thresholds varying sharply by geography.
- Savory:Umami-dense profiles leveraging yeast extracts, fermented bases, and hydrolyzed proteins. Germany and Japan manufacturers prioritize this category for clean-label reformulation without sodium spikes.
- Spicy:Capsicum-derived heat systems ranging from mild paprika to extreme extract concentrations. United States and China consumers are driving Scovell unit escalation in retail and food service applications.
- Sweet:Sugar, molasses, or alternative sweetener bases common in barbecue and teriyaki variants. FDA added sugar disclosure requirements compress formulation flexibility.
- Tangy:Acid-forward profiles from vinegar, citrus, or fermented dairy. Refrigerated formats in this segment face steepest EU F-Gas compliance costs for cold-chain maintenance.
Savory dominates current shelf space; spicy profiles are climbing the fastest as younger demographics expand heat tolerance.
Packaging Type:
Material choice determines shelf aesthetics, shipping economics, and regulatory exposure to single-use packaging restrictions.
- Bottles:Glass or PET containers with controlled neck finishes for pour control. Premium United States supermarket placements sustain demand despite energy-intensive production and higher freight costs versus flexible alternatives.
- Pouches:Multi-layer flexible films with spouted or tear-notch dispensing. Stand-up formats are displacing glass in convenience channels without sacrificing shelf presence.
- Jars:Wide-mouth glass containers for spoonable sauces and thick emulsions. European Union packaging waste directives threaten this format's long-term channel access.
- Tubs:Injection-molded PP or PS containers for refrigerated fresh sauces. Cold-chain dependency limits geographic reach for producers without distributed refrigeration networks.
Bottles retain the largest installed base; pouches are expanding most quickly in club store and online retail channels.
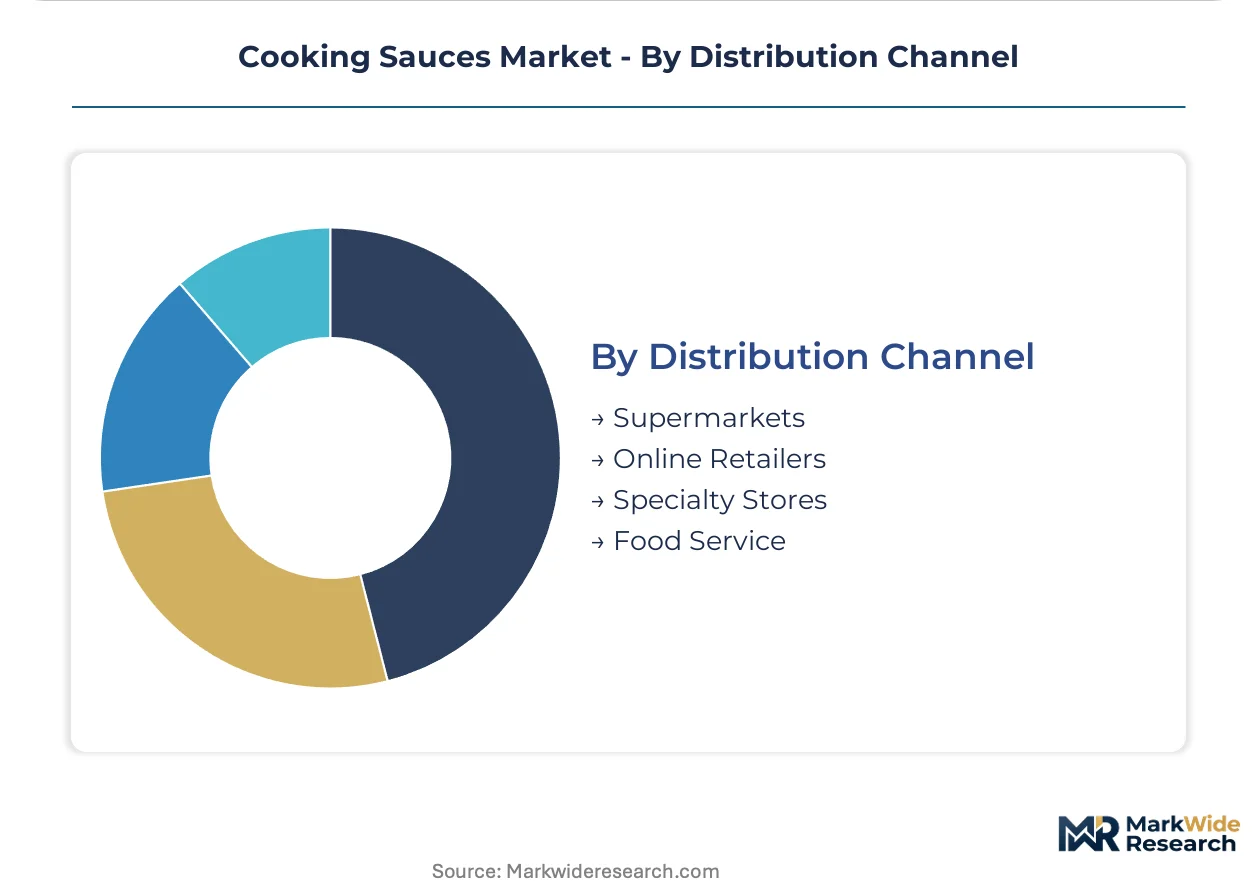
Distribution Channel:
Channel selection determines margin capture, data access, and exposure to food safety inspection regimes.
- Supermarkets:Brick-and-mortar retail with planogram-driven shelf placement and promotional funding requirements. Germany and United States chains are tightening clean-label entry criteria.
- Food Service:Institutional and restaurant supply with bulk format specifications and HACCP compliance documentation. China and United States restaurant chains are expanding ethnic sauce applications fastest.
- Online Retailers:Direct-to-consumer and aggregator platforms with subscription mechanics and review-driven discovery. This channel fragments procurement patterns for marinade and simmer-sauce kits.
- Specialty Stores:Ethnic grocers, gourmet shops, and natural food retailers with curated assortments and local sourcing stories. These outlets reward small-batch fermentation narratives and transparent supply chains.
Supermarkets command the greatest volume throughput; food service is pulling ahead fastest as restaurant chains expand sauce-forward menu engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemist talent pools in Germany, Japan, and the United States anchor formulation innovation for clean-label reformulation. These workforce concentrations determine where fermentation biotechnology and natural hydrocolloid expertise clusters.
United States
Suburban home cooks are pulling volume through club stores for marinade and simmer-sauce kits. FDA sodium-reduction mandates are degrading taste profiles in soy sauce and tomato categories without acceptable clean-label salt replacers. Chicago and New Jersey host concentrated food service distribution networks serving restaurant chains expanding ethnic sauce applications.
China
Food service operators in restaurant chains are accelerating demand for pre-flavored protein solutions. SAMR enforces increasingly stringent national food safety standards that foreign entrants must satisfy for market access. Yangtze River Delta manufacturing clusters are front-loading capital expenditure for EU F-Gas compliant refrigeration to maintain European export channels.
Germany
Mid-tier producers are adopting bioreactor-cultured flavor concentrates to reduce reliance on aged soy extraction. EFSA additive approvals under REACH-aligned frameworks shape formulation choices and import eligibility. Bavaria hosts precision fermentation facilities compressing traditional umami base production timelines.
Japan
Century-old brewing craftsmanship anchors positions in fermented soy sauce through traditional koji cultivation methods. METI standards for food manufacturing equipment influence capital investment decisions for sauce producers. Kansai region brewing clusters maintain artisanal positioning while adopting controlled microbial cultivation for batch consistency.
India
FSSAI clean-label pathway formalization is rewarding early reformulators with retail shelf preference in urban markets. The regulator's additive disclosure standards are accelerating ingredient transparency requirements for domestic and foreign entrants. Maharashtra and Gujarat manufacturing corridors are retrofitting thermal processing lines to meet emerging disclosure mandates.
Cooking Sauces Market Vendor Landscape
The competitive structure tilts toward diversified multinationals with spice-sourcing infrastructure and fermentation expertise. Tiered concentration separates heritage brewers from commodity thermal processors, with mid-tier players caught between clean-label upgrade costs and private-label pricing pressure. Strategic archetypes include fermentation specialists leveraging century-old brewing narratives, diversified condiment conglomerates controlling retail shelf space, and private-label manufacturers serving discounter channels. Dominant competitive moves encompass backward integration into tomato paste and soybean supply chains, plus cross-border M&A to secure regional fermentation assets.
Within the heritage fermentation tier, Kikkoman Corporation exemplifies artisanal positioning through traditional brewing craftsmanship. McCormick & Company and Unilever occupy positions as diversified multinationals with broad retail distribution networks. These three anchors represent distinct strategic archetypes: century-old brewing expertise, spice-sourcing infrastructure, and global brand portfolio scale respectively.
| Leading Market Players |
|---|
| McCormick & Company |
| General Mills |
| Unilever |
| Campbell Soup Company |
| Kikkoman Corporation |
| Nestle |
| Conagra Brands |
| Barilla |
| Kraft Heinz Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in Italy and Japan anchor artisanal soy sauce and pasta sauce production, preserving pricing discipline through controlled batch releases while resisting private-label conversion pressure from supermarket buyers seeking volume commitments.
Pricing Analysis
Ingredient-plus-branding bundles separate premium fermented sauces from unbundled commodity thermal-processed variants. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in mid-tier pasta sauce is intensifying because California tomato paste supply volatility forces margin absorption. Food service operators exhibit least price sensitivity due to menu engineering flexibility, while club store procurement teams drive hardest bargain for marinade kit volume commitments.
Supply Chain Analysis
Direct-to-food-service channels handle hyperscale restaurant chain demand through contracted bulk formats with HACCP documentation. Tomato paste supply draws from California and Xinjiang, while fermented soybean inputs rest on Yangtze River Delta and Kansai region brewing clusters. Single-source vulnerability concentrates in glass jar packaging where European Union waste directives threaten long-term channel access. Distribution runs through refrigerated logistics networks for fresh pesto and salsa categories facing EU F-Gas compliance escalation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where suburban home cooks trade preparation control for ethnic authenticity in marinade and simmer-sauce kits, pulling volume toward premium-positioned convenience formats.
For Market Incumbents: Acquire precision fermentation facilities in Germany and Japan to compress umami base production timelines. Defensive consolidation demands backward integration into Xinjiang and California tomato paste supply chains to hedge drought-cycle price squeezes. Channel control through exclusive food service distribution agreements locks out emerging private-label threats.
For New Entrants and Emerging Players: Bioreactor-cultured flavor concentrates offer technology-first wedge into cost-sensitive sauce segments previously reserved for traditional brewing. White-space targets concentrate in India's FSSAI clean-label pathway where early reformulators capture retail shelf preference. Direct-to-consumer subscription mechanics for ethnic sauce kits bypass supermarket planogram gatekeepers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier thermal processors caught between clean-label upgrade costs and discounter pricing pressure. Long-term viability favors fermentation specialists with captive koji cultivation expertise and heritage brand narratives. Watch sodium-reduction mandate acceleration as inflection indicator for reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioreactor adoption in Germany compresses traditional soy sauce aging timelines while preserving artisanal positioning claims. |
| Clean-Label Reformulation Investment | Natural hydrocolloid stabilization expertise addresses FDA and EFSA sodium-reduction mandates without taste degradation. |
| Cold-Chain Infrastructure Retrofit | EU F-Gas compliant refrigeration replacement maintains European export channel access for refrigerated salsa producers. |
| Food Service Distribution Expansion | United States and China restaurant chain partnerships accelerate marinade volume through institutional procurement. |
| Pouch Packaging Format Migration | Stand-up spouted pouches penetrate club store channels without sacrificing premium supermarket shelf aesthetics. |
Methodological Framework
Bottom-up food service and retail channel modeling reconciled against top-down tomato paste and soybean supply tracking forms the analytical core. Primary interviews with brand managers, category buyers at supermarket chains, fermentation R&D directors, and food service procurement officers combine with secondary validation from FDA labeling guidance, EFSA additive approval databases, SAMR food safety standards, and customs trade records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of pasta sauce, soy sauce, and marinade shipment patterns informs projection frameworks across the analysis window. Segmentation dimensions span sauce type, flavor profile, packaging format, and distribution channel with regional regulatory cluster overlays. CAGRs derive from fitted growth curves adjusted for input cost volatility and clean-label reformulation penetration rates. Forecast inputs incorporate EU F-Gas phase-down schedules and FSSAI disclosure mandate timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to drought-cycle tomato paste pricing and sodium-reduction technical ceiling breakthroughs. Outputs reflect documented assumptions around fermentation biotechnology adoption curves and cold-chain compliance cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Acciughe Pasta Sauce Market