
 US Food Allergen Testing Market | 2026-2036
US Food Allergen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Food Allergen Testing Market Analytics
Modular test-kit configurations are decoupling bundled reagent-and-reader packages into standalone consumables and open-platform instruments, giving mid-sized food plants flexibility to scale testing volume without capital-heavy instrument swaps. Eurofins Scientific leverages its distributed laboratory network to anchor high-throughput ELISA and PCR services for national CPG brands. Neogen Corporation specializes in lateral-flow devices that occupy the rapid-testing niche at plant-floor checkpoints. Thermo Fisher Scientific Inc. extends its mass spectrometry leadership into allergen confirmatory workflows for complex matrices.
Food allergen testing encompasses analytical methods that detect and quantify proteins from peanuts, tree nuts, milk, eggs, wheat, soy, fish, shellfish, and sesame in food matrices, with detection limits typically ranging from 0.1 to 5 parts per million depending on method sensitivity and sample preparation. These tests serve the commercial purpose of verifying label accuracy, preventing cross-contact incidents, and satisfying buyer audit requirements in private-label supply chains. ELISA-based assays dominate routine screening due to established protocols and lower per-test cost, while mass spectrometry captures the fastest-growing structural position as processors seek multi-allergen detection in single runs. PCR methods sustain demand in processed foods where protein denaturation complicates immunoassay reliability, and confirmatory testing commands premium positioning within the testing-method dimension as regulatory scrutiny intensifies.
The FDA enforces FALCPA labeling rules and FSMA preventive controls, while USDA-FSIS oversees allergen controls in meat and poultry processing, and state agriculture departments in California, New York, and Illinois supplement federal standards with their own inspection cadences. This layered regulatory architecture shapes demand by mandating documented testing frequencies, validated methods, and corrective-action records that suppliers must present during audits. Stakeholders should monitor how FDA guidance on sesame as the ninth major allergen evolves method-validation requirements and whether state-level enforcement divergence creates compliance complexity for multi-facility operators.
Market Dynamics
Modular test-kit configurations are decoupling bundled reagent-and-reader packages into standalone consumables and open-platform instruments, giving mid-sized food plants flexibility to scale testing volume without capital-heavy instrument swaps. This structural shift is compressing the traditional equipment upgrade cycle and redistributing purchasing power toward consumables suppliers.
Growth Catalysts
- FALCPA Labeling Mandates:The FDA Food Allergen Labeling and Consumer Protection Act compels processors to validate allergen controls at every production stage, creating recurring demand for documented testing frequencies.
- Bakery and Confectionery Expansion:Food manufacturers in this segment are expanding testing protocols to protect brand integrity, driving adoption of rapid lateral-flow devices at plant-floor checkpoints.
- Midwest Dairy Belt Concentration:Large-scale facilities in Wisconsin, Minnesota, and Iowa face strict state-level enforcement from agriculture departments, anchoring regional demand for high-throughput ELISA services.
Market Restraints
- Mass Spectrometry Capital Intensity:Multi-allergen confirmatory workflows require six-figure instrument investments that freeze out smaller co-packers and regional bakeries.
- Protein Denaturation Limitations:Thermal processing in retort and extrusion applications degrades allergenic proteins, rendering immunoassay methods unreliable and forcing costly PCR alternatives.
- California Enforcement Divergence:State agriculture department inspection cadences exceed federal FSMA baselines, creating compliance complexity for multi-facility operators with plants across state lines.
Strategic Opportunities
- Sesame Validation Services:FDA guidance elevating sesame to the ninth major allergen opens method-validation contracts for laboratories capable of detecting this seed protein in complex spice matrices.
- PCR-ELISA Convergence:Hybrid workflows combining DNA-based screening with protein confirmation are penetrating processed meat and poultry facilities where USDA-FSIS oversight intersects with severe thermal processing.
- Private-Label Supply Chain Audits:Retailer buyer audit requirements are unbundling testing from manufacturing, creating third-party certification channels for independent laboratories in the Southeast and Pacific Northwest.
Industry Challenges
- Multi-Allergen Panel Standardization:Lack of harmonized reference materials for simultaneous peanut, tree nut, and milk detection forces laboratories to maintain parallel validation protocols for each matrix.
- Plant-Floor Technician Training:Rapid lateral-flow deployment requires hourly operators to interpret faint test lines in variable lighting conditions, elevating false-negative risk at critical control points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Food Allergen Testing Market |
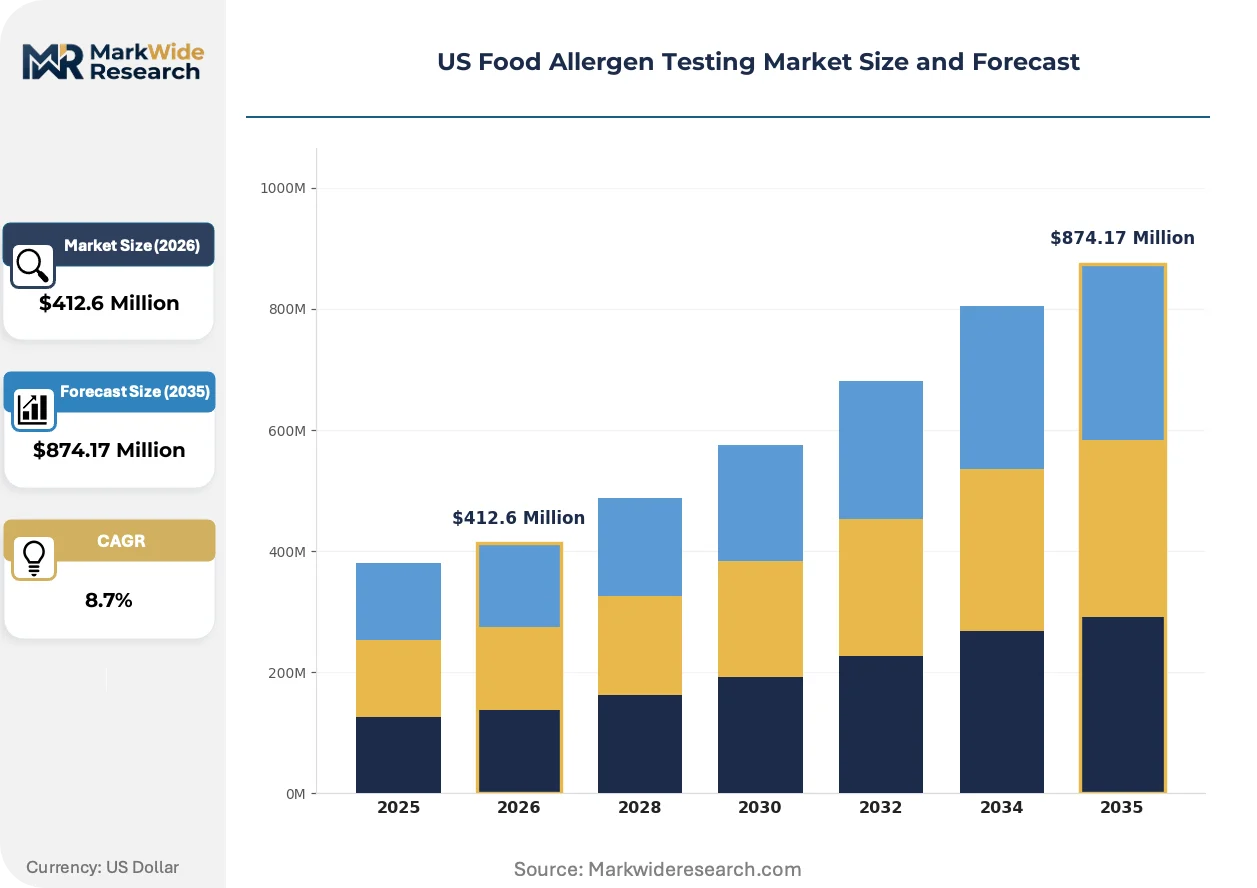
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, PCR, Lateral Flow, Mass Spectrometry End User: Food Manufacturers, Restaurants, Laboratories, Regulatory Agencies Sample Type: Liquid, Solid, Powdered, Raw Materials Testing Method: Qualitative, Quantitative, Rapid Testing, Confirmatory Testing |
| Companies Covered | Eurofins Scientific, Thermo Fisher Scientific Inc., Neogen Corporation, Microbac Laboratories Inc., SGS Société Générale de Surveillance SA., Mérieux NutriSciences Corporation, Romer Labs, Bureau Veritas, IEH Laboratories & Consulting Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Food Allergen Testing Market Evolving Landscape
Mass spectrometry is converging with multiplexed immunoassay platforms to compress confirmatory testing timelines. These technology intersections are reshaping how processors balance speed against analytical rigor in allergen verification workflows.
LC-MS/MS instrumentation is converging with automated sample prep robotics to enable simultaneous detection of peanut, milk, egg, and soy residues in single analytical runs. National CPG brands operating integrated bakery and dairy facilities are adopting these platforms to replace sequential ELISA tests. This convergence is compressing the confirmatory testing bottleneck that previously delayed batch release decisions by 24 to 48 hours.
FDA preventive controls under FSMA now explicitly require environmental monitoring for allergen cross-contact in ready-to-eat facilities. This regulatory expansion is forcing processors to document corrective-action records that suppliers must present during unannounced audits. California and New York state agriculture departments have supplemented these federal standards with accelerated inspection cadences that prioritize facilities with prior labeling violations.
Retailer procurement teams are consolidating testing contracts toward laboratories offering integrated sampling, analysis, and regulatory filing services. This bundling is displacing the historical model where plants managed multiple vendor relationships for kit supply, equipment maintenance, and third-party verification. The shift is most visible among private-label suppliers in the Midwest dairy belt, where buyer concentration at major retail chains has compressed the approved laboratory list to three national providers.
US Food Allergen Testing Market Segmentation
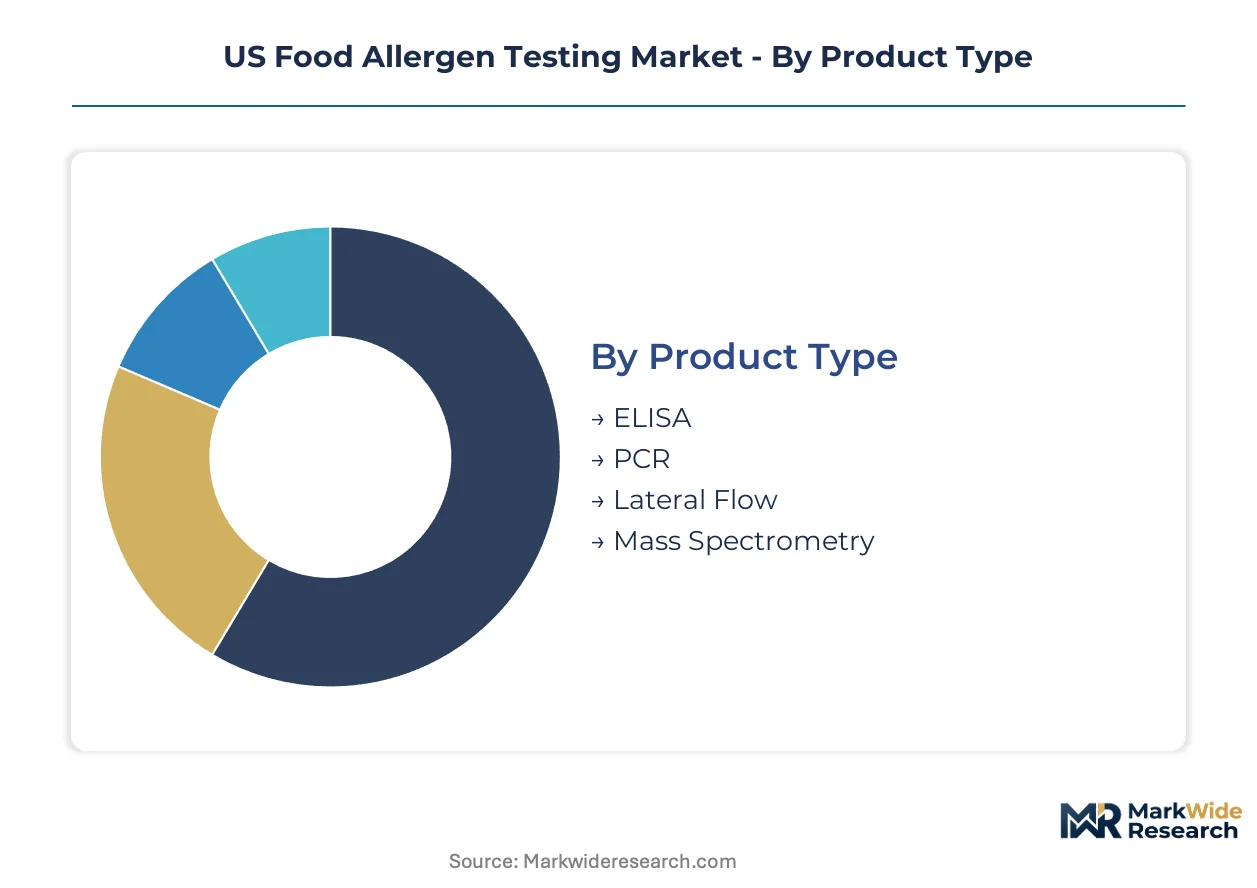
Testing modality selection determines capital allocation, technician training requirements, and regulatory defensibility across the US food production landscape. Segment boundaries reflect competing pressures for speed, sensitivity, and multi-allergen throughput.
Product Type:
Technology performance characteristics anchor purchasing decisions, with detection limits and matrix compatibility driving substitution patterns between incumbent and emerging platforms.
- ELISA:Enzyme-linked immunosorbent assays employ antibody-antigen binding with colorimetric or fluorescent readouts, achieving detection limits near 0.5 ppm for most priority allergens. Mature deployment dominates high-volume dairy processing in Wisconsin and Minnesota, where validated protocols satisfy state agriculture department inspection cadences. The platform's per-test economics and extensive reference material libraries sustain its position in routine screening workflows.
- PCR:Polymerase chain reaction amplifies allergen-specific DNA sequences, penetrating processed meat and poultry facilities where USDA-FSIS oversight intersects with severe thermal processing that denatures proteins. Demand concentrates in retort and extrusion applications where immunoassay reliability degrades, forcing processors toward nucleic acid detection despite higher per-sample costs and specialized technician requirements.
- Lateral Flow:Immunochromatographic strips deliver qualitative results within 10 minutes at plant-floor checkpoints without instrumentation. Bakery and confectionery manufacturers deploy these devices for incoming ingredient verification and line-changeover clearance.
- Mass Spectrometry:LC-MS/MS platforms enable simultaneous detection of multiple allergen proteins in complex matrices with definitive structural confirmation. National CPG brands operating integrated facilities adopt these systems for batch release decisions requiring regulatory-grade documentation.
Mature deployment sits with ELISA. Newer deployment is concentrated in Mass Spectrometry.
End User:
Customer type dictates purchasing scale, service bundling preferences, and the balance between in-house capability and outsourced verification.
- Food Manufacturers:Integrated production facilities from artisan bakeries to multinational dairy processors constitute the core revenue base, with testing volume scaling directly with SKU complexity and allergen-containing product lines. These operators face the most intensive FDA FSMA preventive controls documentation requirements.
- Restaurants:Commercial kitchen and chain dining operations are expanding testing protocols for ingredient verification and supplier qualification, particularly in California where state-level enforcement exceeds federal baselines. Rapid lateral-flow adoption is climbing fastest in this segment as liability exposure drives precautionary screening.
- Laboratories:Third-party analytical service providers anchor high-throughput ELISA and PCR capacity for private-label supply chains, with retailer procurement teams consolidating contracts toward integrated sampling-analysis-filing services. Eurofins Scientific and similar networks capture national CPG brand volume through distributed facility coverage.
- Regulatory Agencies:FDA field laboratories and state agriculture department inspection units maintain reference-method capability for enforcement actions and method-validation oversight, representing a concentrated but price-insensitive demand pocket.
Volume concentrates with Food Manufacturers. Margin expansion is strongest in Laboratories.
Sample Type:
Physical form factors determine extraction protocols, homogenization requirements, and the applicability of specific detection technologies.
- Liquid:Milk, beverages, and liquid ingredients permit direct sampling with minimal preparation, supporting rapid turnaround for dairy processing in the Midwest belt. ELISA protocols for liquid matrices are the most standardized across laboratories.
- Solid:Baked goods, confectionery, and meat products require grinding, solvent extraction, and filtration before analysis, extending preparation time and introducing variability that mass spectrometry addresses through internal standardization.
- Powdered:Flour, spice blends, and dry mixes present homogeneity challenges and dust exposure risks during sampling, with sesame detection in complex spice matrices emerging as a priority application following FDA guidance elevation.
- Raw Materials:Unprocessed agricultural inputs at receiving docks undergo screening before entering production environments, with supplier qualification testing representing a distinct workflow from in-process verification.
Standardization is deepest for Liquid. Technical complexity is highest for Powdered.
Testing Method:
Analytical purpose—screening versus confirmation, speed versus rigor—structures the method-selection hierarchy within quality management systems.
- Qualitative:Presence-absence determination at thresholds typically near 5 ppm serves line-clearance and environmental monitoring applications where rapid binary answers support operational decisions without quantitative precision.
- Quantitative:Concentration reporting with calibration curves enables label-accuracy verification and corrective-action documentation required by FDA preventive controls, with results traceable to reference standards.
- Rapid Testing:Lateral-flow and simplified ELISA formats deliver results within 30 minutes at plant-floor locations, compressing the batch-hold window and supporting just-in-time release decisions in high-velocity bakery operations.
- Confirmatory Testing:Mass spectrometry and reference-method PCR provide defensible analytical data for regulatory submissions, customer dispute resolution, and litigation defense, commanding premium positioning within testing-service pricing structures.
Regulatory defensibility peaks with Confirmatory Testing. Operational velocity peaks with Rapid Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing demand concentrates in production belts where allergen-heavy manufacturing intersects with strict state enforcement. Consumption patterns track population density and retail buyer concentration rather than processing volume alone.
California
The state's agriculture department maintains inspection cadences exceeding federal FSMA baselines, driving bakery and confectionery manufacturers toward rapid lateral-flow deployment at plant-floor checkpoints. Los Angeles and San Francisco Bay Area clusters anchor third-party laboratory demand for private-label supplier audits. Sesame validation services are expanding fastest here following FDA elevation of the seed to major allergen status.
Midwest Dairy Belt
Wisconsin, Minnesota, and Iowa house large-scale dairy processing facilities facing the strictest state-level enforcement from agriculture departments. High-throughput ELISA services dominate in this region where validated protocols satisfy documented testing frequency mandates. Minneapolis-St. Paul and Milwaukee metropolitan areas concentrate laboratory capacity for integrated sampling-analysis-filing contracts.
Northeast Corridor
New York state agriculture departments supplement federal standards with accelerated inspection priorities for facilities with prior labeling violations. New York City and Boston metropolitan areas drive restaurant segment demand for incoming ingredient verification protocols. Retailer procurement consolidation is most advanced here, compressing approved laboratory lists to national providers.
Southeast
Georgia and Florida food manufacturing growth is outpacing local laboratory capacity, creating third-party certification channels for independent providers. Atlanta and Miami clusters see expanding PCR-ELISA hybrid workflows in processed meat facilities where USDA-FSIS oversight intersects with thermal processing challenges. Private-label supply chain audits are unbundling testing from manufacturing fastest in this region.
Pacific Northwest
Seattle and Portland metropolitan areas concentrate specialty food manufacturing with high SKU complexity and allergen-containing product lines. Environmental monitoring for cross-contact is expanding under FSMA preventive controls documentation requirements. State agriculture departments in Washington and Oregon coordinate with FDA field laboratories on method-validation oversight.
US Food Allergen Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across testing modalities and service models. The market structure tilts toward consolidation at the national laboratory network tier while fragmenting among regional kit suppliers and equipment vendors. Three strategic archetypes dominate: distributed laboratory networks, rapid diagnostic device specialists, and analytical instrumentation conglomerates. M&A activity concentrates on geographic coverage expansion and technology portfolio diversification rather than vertical integration.
Within the distributed laboratory network archetype, Eurofins Scientific and SGS Société Générale de Surveillance SA occupy positions anchoring high-throughput service capacity for national CPG brands. Thermo Fisher Scientific Inc. represents the analytical instrumentation conglomerate tier, extending mass spectrometry platforms into confirmatory workflows. These three companies exemplify how scale-driven and technology-driven positioning create defensible market presence without overlapping customer segments.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Thermo Fisher Scientific Inc. |
| Neogen Corporation |
| Microbac Laboratories Inc. |
| SGS Société Générale de Surveillance SA. |
| Mérieux NutriSciences Corporation |
| Romer Labs |
| Bureau Veritas |
| IEH Laboratories & Consulting Group |
| Others |
Value Network & Pricing Analysis
Captive in-house production of ELISA reagents and lateral-flow consumables anchors supply security for national laboratory networks while compressing per-test economics against third-party kit suppliers. This backward integration choice secures volume pricing power for high-throughput service providers facing FALCPA-mandated testing frequency requirements across multi-facility dairy and bakery operations.
Pricing Analysis
Cost-down pressure on confirmatory mass spectrometry services accelerates because national CPG brands consolidate contracts toward integrated sampling-analysis-filing bundles. Three-tier pricing structure across premium confirmatory, standard quantitative ELISA, and economy rapid-screening levels stratifies by certification grade and after-sales regulatory filing support. Pricing pressure stems from retailer procurement teams squeezing approved laboratory lists in the Midwest dairy belt. Smaller regional bakeries exhibit highest price sensitivity, while FDA-facing multinational processors prioritize regulatory defensibility over per-test cost.
Supply Chain Analysis
Regional distribution centers in Wisconsin, Minnesota, and Iowa anchor hub-and-spoke patterns for reagent cold-chain logistics serving dairy processing clusters. Manufacturing concentration for ELISA antibody production rests on facilities in California and Massachusetts, with lateral-flow membrane sourcing tethered to specialized converters in North Carolina and Ohio. Single-source vulnerability sits with reference-standard allergen proteins used for kit calibration. Distribution runs through third-party logistics partners maintaining temperature-controlled warehousing for PCR enzyme stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass spectrometry platforms are displacing sequential ELISA workflows as national CPG brands seek multi-allergen detection in single analytical runs, compressing batch-release timelines and reshaping competitive positioning around confirmatory capability.
For Market Incumbents: Anticipate margin compression in high-throughput ELISA services as modular test-kit configurations enable mid-sized plants to scale without capital-heavy instrument swaps. Defend position by deepening backward integration into antibody production and securing exclusive reference-material partnerships. Prioritize certification investment for sesame validation services ahead of FDA enforcement escalation.
For New Entrants and Emerging Players: Enter via private-label supply chain audits in the Southeast, where Georgia and Florida manufacturing growth outpaces local laboratory capacity. Target restaurant segment rapid-testing in California, where state enforcement exceeds federal baselines and liability exposure drives precautionary screening adoption. Pursue go-to-market partnerships with regional distribution networks for lateral-flow device placement.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified laboratory networks seeking geographic coverage in the Pacific Northwest specialty food cluster. Long-term viability hinges on technology-transition timing as mass spectrometry automation penetrates mid-market facilities. Watch for FDA guidance finalization on sesame method-validation requirements as inflection indicator for validation-service revenue acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| PCR-ELISA Hybrid Workflow Development | Addresses protein denaturation in USDA-FSIS-regulated meat processing facilities. |
| Sesame Validation Service Launch | Captures FDA-mandated testing demand in complex spice matrices. |
| Automated Sample Prep Robotics Integration | Compresses LC-MS/MS turnaround for integrated bakery-dairy facilities. |
| Third-Party Certification Channel Expansion | Penetrates Southeast private-label supply chains unbundling testing from manufacturing. |
| Environmental Monitoring Protocol Rollout | Satisfies FSMA preventive controls documentation for ready-to-eat facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with food safety directors, quality assurance managers, laboratory operations heads, and regulatory affairs specialists at CPG brands and third-party testing providers. FDA warning letters, USDA-FSIS enforcement reports, and state agriculture department inspection records supplemented bottom-up facility capacity estimates against top-down market sizing from reagent import volumes and instrument shipment data.
Segment-level granularity modeled testing modality, end-user archetype, sample matrix type, and analytical purpose dimensions across the projection horizon. CAGRs derived from elasticity-adjusted volume projections tied to FALCPA enforcement intensity indices and SKU proliferation rates in allergen-containing product lines. Forecast inputs incorporated state-level inspection cadence differentials and retailer procurement consolidation timelines.
Revisions become necessary when FDA guidance on sesame validation protocols materializes or when state agriculture departments diverge enforcement standards across multi-facility operators. Forecasts reflect documented assumptions around regulatory stability and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
High-Throughput Food Allergen Screening Test Instruments Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
Adulteration Tester Market