
 Soy-Based Sauce Market | 2026-2036
Soy-Based Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Soy-Based Sauce Market Analytics
Food service buyer concentration is consolidating across Asia-Pacific quick-service chains, shifting procurement power toward centralized purchasing cooperatives. Kikkoman Corporation leverages its integrated brewing infrastructure to secure long-term supply contracts with these consolidating buyers. Lee Kum Kee differentiates through premium positioning in diaspora retail channels across North America and Europe. Foshan Haitian Flavouring & Food Co. Ltd. dominates domestic Chinese distribution through deep penetration of provincial wholesale markets.
Soy-based sauce denotes a fermented liquid condiment produced from soybeans, wheat, salt, and Aspergillus mold cultures, typically aged six months to two years in controlled-temperature brewing vessels, functioning primarily as a umami-intensifying flavor base across commercial and household cooking applications. Light soy sauce leads volume share in food processing applications where color control matters, while tamari commands premium margins in allergen-free retail positioning. Powdered and granular forms represent the fastest-expanding format segment, driven by instant noodle seasoning packet demand and reduced logistics costs.
China's SAMR enforces GB standards for fermented soy products, including amino nitrogen minimums and preservative limits that determine factory-level market access. Japan's Ministry of Health, Labour and Welfare maintains positive-list systems for food additives that constrain formulation flexibility for imported sauces. The EU's EFSA evaluates 3-MCPD ester limits in hydrolyzed vegetable protein additives, affecting tamari and certain fast-fermented variants. Stakeholders must monitor how diverging allergen labeling mandates between Japan's Consumer Affairs Agency and US FDA disclosure rules reshape export formulation strategies and dual-label packaging requirements.
Market Dynamics
Centralized procurement by quick-service restaurant chains across Southeast Asia is consolidating buyer power and forcing fermentation capacity investments near urban consumption clusters.
Growth Catalysts
- Indonesia's QSR Expansion:Local chains scaling centralized kitchen networks are standardizing soy sauce specifications across hundreds of outlets, creating predictable offtake agreements for brewers.
- GB Standards Modernization:China's SAMR tightening of amino nitrogen minimums and additive disclosure rules is accelerating factory consolidation among sub-scale producers unable to meet compliance costs.
- Powdered Format Adoption:Instant noodle seasoning packet demand is driving granular soy sauce investments, reducing logistics costs by two-thirds versus liquid equivalents for cross-border distribution.
Market Restraints
- Wheat Input Volatility:Weather-driven fluctuations in North American and Australian wheat harvests create margin compression for traditional brewing recipes requiring 40-60% wheat content.
- 3-MCPD Ester Scrutiny:EFSA's evaluation of hydrolyzed vegetable protein additives is constraining tamari and fast-fermented variant formulations bound for European retail channels.
- Soybean Supply Concentration:Crushing capacity concentration in Brazil and the US Midwest creates geographic vulnerability for Asian brewers dependent on imported non-GMO beans.
Strategic Opportunities
- Allergen-Free Positioning:Tamari variants without wheat content are capturing premium shelf space in North American and European diaspora retail channels as celiac awareness spreads.
- Dual-Label Packaging:Diverging allergen disclosure mandates between Japan's Consumer Affairs Agency and US FDA rules create arbitrage opportunities for exporters mastering compliant dual-certification.
- Reduced-Sodium Fermentation:Modified koji cultures enabling 30-40% salt reduction without sacrificing umami intensity are opening institutional foodservice contracts in health-conscious urban markets.
Industry Challenges
- Master Brewer Scarcity:Traditional moromi fermentation expertise requires 10-15 year apprenticeships, and aging workforces in Japan's Shoyu-producing prefectures are constraining quality-controlled expansion.
- Temperature-Controlled Aging Capex:Six-month to two-year brewing cycles in climate-controlled vessels require substantial upfront capital that conflicts with private equity holding period expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy-Based Sauce Market |
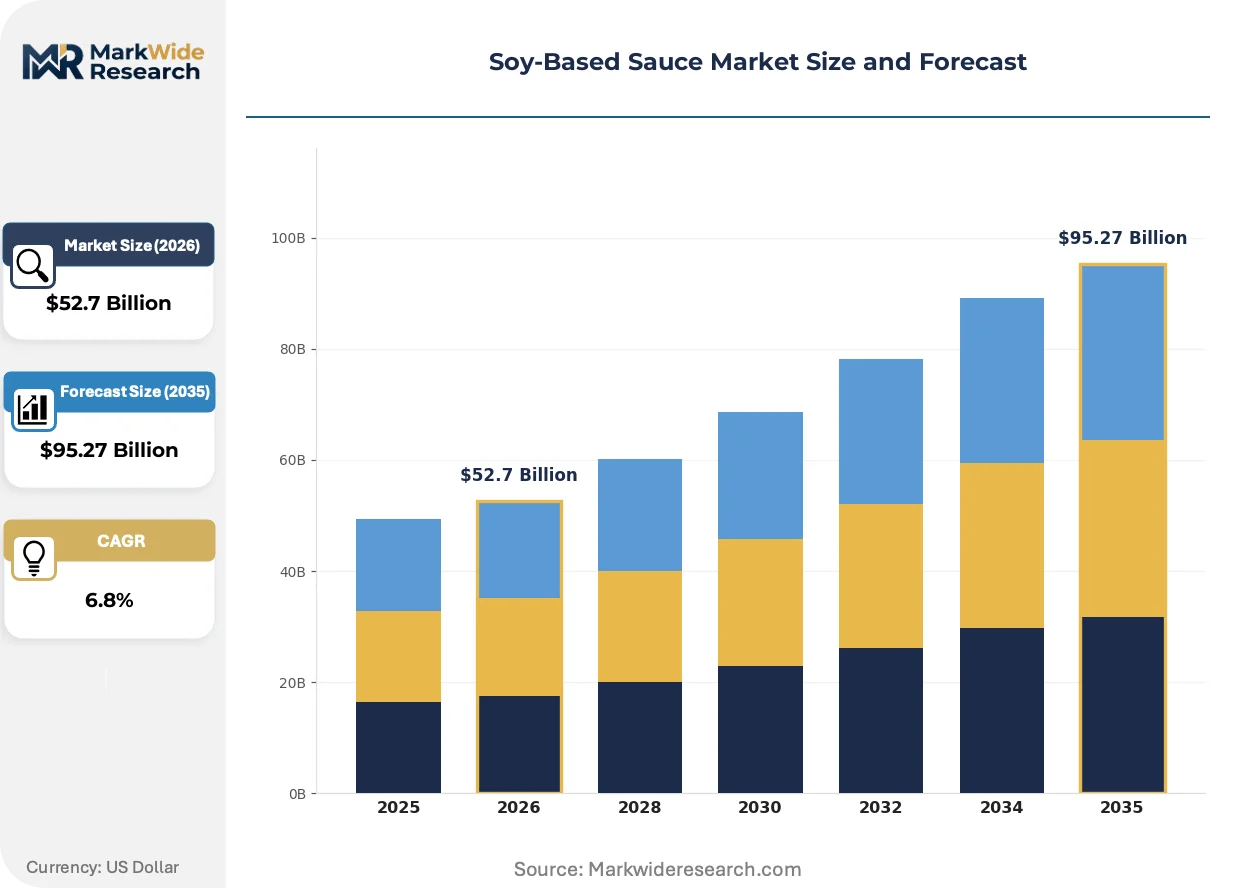
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Soy Sauce, Dark Soy Sauce, Sweet Soy Sauce, Tamari Form: Liquid, Paste, Powdered, Granular End User: Household, Food Service, Food Processing, Retail Packaging Type: Bottle, Pouch, Jar, Bulk |
| Companies Covered | Foshan Haitian Flavouring & Food Co. Ltd., Kikkoman Corporation, Lee Kum Kee, Yamasa Corporation, Masan Group, OTAFUKU SAUCE Co., Ltd., Bourbon Barrel Foods, Sempio Foods Company, Guangdong Meiweixian Flavoring Foods Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy-Based Sauce Market Evolving Landscape
Controlled-environment fermentation technology and regulatory divergence are rewriting production economics and export compliance requirements across traditional brewing strongholds.
Continuous-flow fermentation systems using precision temperature and humidity controls are rewriting the traditional 12-24 month aging timeline. Food processing conglomerates in Thailand and Vietnam are adopting these systems to secure consistent light soy sauce color profiles for standardized product lines. The compression of brewing cycles from years to weeks is enabling just-in-time inventory models previously impossible in artisanal production.
EFSA's evolving 3-MCPD ester limits in hydrolyzed vegetable protein additives are forcing reformulation of tamari and certain fast-fermented variants. European importers are demanding certificate-of-analysis documentation for every batch, raising testing costs and disqualifying smaller exporters lacking in-house laboratory capacity. Japanese and Korean brewers with established EU distribution networks are accelerating naturally brewed certifications to maintain shelf positioning.
Quick-service restaurant procurement committees are consolidating supplier lists from dozens to three-to-five approved partners per condiment category. Indonesia's leading local chains now mandate centralized kitchen pre-approval of all soy sauce specifications, eliminating outlet-level purchasing discretion. This concentration is visible across Jakarta, Surabaya, and Bandung as franchise networks enforce flavor standardization protocols.
Soy-Based Sauce Market Segmentation
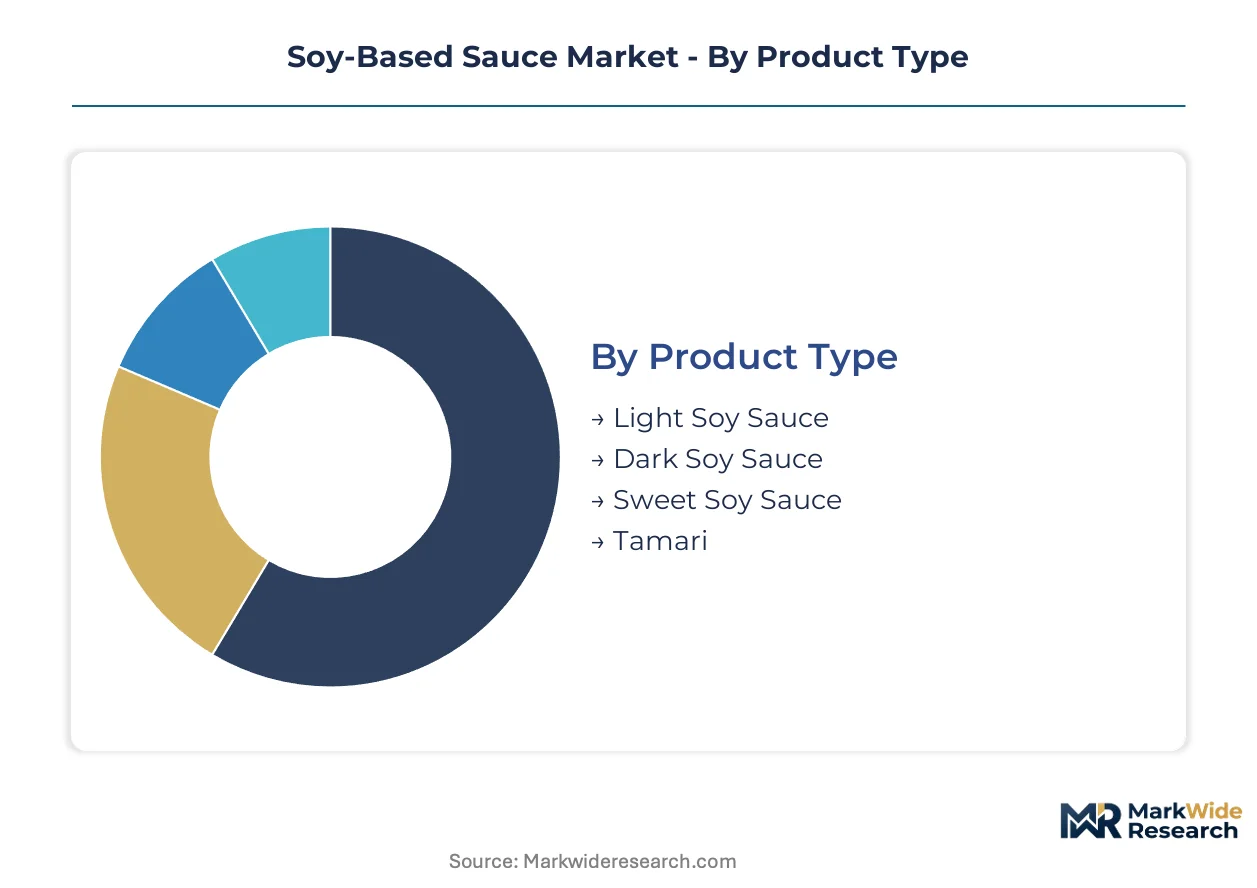
Soy-based sauce segmentation reveals how brewing specifications, format engineering, and procurement scale reshape supplier economics. Understanding these divides exposes where margin pools concentrate and where commoditization pressures mount.
Product Type:
Buyers differentiate by umami intensity, color contribution, and wheat content tolerance, creating distinct specification tiers across commercial and household channels.
- Light Soy Sauce:Lower viscosity and lighter amber coloration suit applications where appearance control matters. Food processing conglomerates in Thailand and Vietnam specify this grade for standardized instant noodle broths where batch-to-batch consistency overrides artisanal variation.
- Dark Soy Sauce:Extended caramelization during brewing produces molasses-like depth and mahogany coloration. Centralized kitchen networks across Indonesia's quick-service chains specify dark variants for braised protein applications requiring visual richness.
- Sweet Soy Sauce:Palm sugar or molasses addition creates viscous glaze properties. Indonesian and Malaysian household buyers dominate procurement for satay and grilled poultry marinades.
- Tamari:Wheat-free brewing with higher soybean content yields denser umami profiles. North American and European diaspora retail channels absorb volumes as celiac awareness reshapes condiment pantry composition.
Light soy sauce leads volumes today; tamari is gaining share fastest.
Form:
Logistics cost structures and manufacturing integration depth separate buyers in this dimension, with powder and granular formats rewarding scale players.
- Liquid:Traditional aqueous format requiring temperature-controlled distribution and glass or PET containment. Food service chains with dedicated cold-chain infrastructure maintain procurement preference for flavor authenticity.
- Paste:Reduced moisture content enables squeeze-tube and portion-pack delivery. Southeast Asian household buyers favor this format for controlled dispensing and extended ambient shelf stability.
- Powdered:Spray-dried extract enables instant noodle seasoning packet integration. Thai and Vietnamese food processing conglomerates drive adoption, cutting cross-border logistics costs by two-thirds versus liquid equivalents.
- Granular:Agglomerated particles dissolve rapidly in hot water applications. Instant noodle manufacturers across Indonesia specify this grade for seasoning sachet compatibility.
Liquid form retains dominant volume position; powdered and granular formats are expanding most quickly.
End User:
Procurement sophistication and specification control intensity vary sharply, from price-sensitive household retail to contract-locked institutional buyers.
- Household:Individual consumers purchasing through retail and e-commerce channels. Diaspora communities in North America and Europe sustain premium positioning for imported Japanese and Korean brewing heritage brands.
- Food Service:Restaurants, cafeterias, and catering operations with volume contracts. Indonesia's quick-service chains now mandate centralized pre-approval of soy sauce specifications, eliminating outlet-level purchasing discretion.
- Food Processing:Industrial manufacturers integrating soy sauce into packaged goods. Instant noodle producers across Thailand and Vietnam constitute the largest contract volume segment.
- Retail:Supermarkets, convenience stores, and specialty grocers stocking packaged SKUs. Provincial wholesale markets in China absorb domestic production through deep distribution penetration.
Food processing leads volumes today; food service is climbing the fastest.
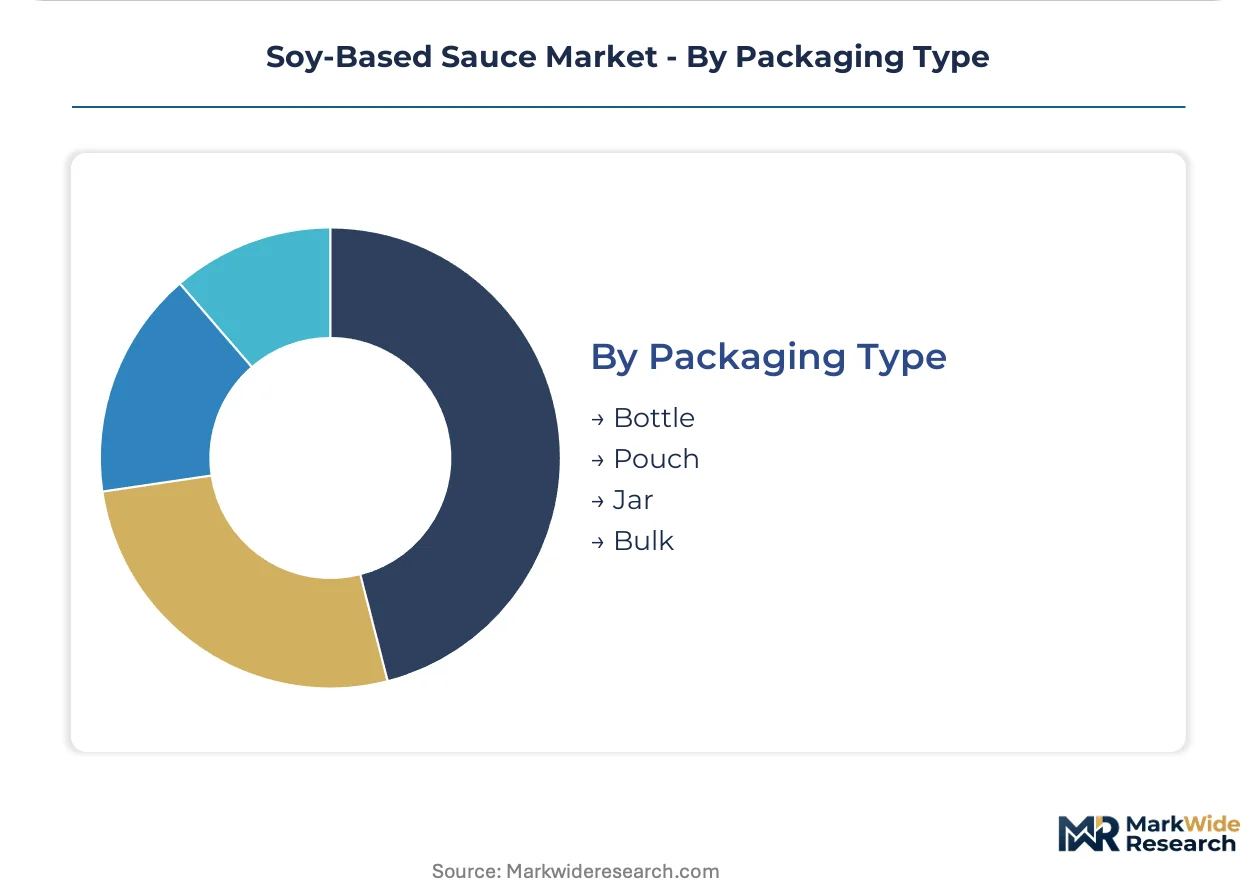
Packaging Type:
Handling efficiency, shelf presence, and waste reduction mandates drive divergent format preferences across channel types.
- Bottle:Glass or PET containment with tamper-evident closures. Household retail channels in Japan and Korea maintain preference for transparent bottle presentation signaling brewing quality.
- Pouch:Flexible laminate construction reducing material weight and shipping cube. Indonesian quick-service chains specify pouch formats for centralized kitchen bulk dispensing systems.
- Jar:Wide-mouth glass or plastic containers enabling spoon access. Traditional retail channels in China's provincial wholesale markets favor this format for consumer familiarity.
- Bulk:Intermediate bulk containers and tanker delivery for industrial users. Food processing conglomerates in Thailand and Vietnam procure through dedicated supply contracts with fermentation facilities.
Bottle packaging leads volumes today; pouch formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands fermentation scale advantages that Indonesia's quick-service chains cannot replicate domestically, while Japan's heritage brewers face capacity constraints against Southeast Asian demand surges.
China
Provincial wholesale markets in Guangdong and Jiangsu absorb the majority of domestic production volume. SAMR's updated GB standards for fermented condiments are tightening amino nitrogen minimums and additive disclosure requirements, accelerating factory consolidation among sub-scale producers. Foshan anchors the largest brewing cluster, where Haitian and Meiweixian maintain deep distribution penetration through tiered wholesale networks.
Japan
Traditional shoyu production concentrates in Chubu prefectures where master brewer expertise sustains premium positioning. The Consumer Affairs Agency maintains strict allergen labeling mandates that diverge from US FDA disclosure rules, forcing exporters toward dual-certification packaging investments. Aging workforces in Aichi and Mie prefectures constrain quality-controlled capacity expansion despite sustained North American and European diaspora demand.
Indonesia
Quick-service restaurant chains in Jakarta, Surabaya, and Bandung are standardizing soy sauce specifications across centralized kitchen networks. Local procurement committees have consolidated approved supplier lists from dozens to three-to-five partners per condiment category. Domestic brewing capacity investments near urban consumption clusters are accelerating to meet predictable offtake agreements from scaling franchise networks.
United States
Diaspora retail channels in California and New York Metro sustain premium positioning for imported Japanese and Korean heritage brands. FDA allergen disclosure rules create compliance friction against Japanese export formulations, favoring domestic bottlers with dual-label capabilities. Bourbon Barrel Foods represents specialty positioning in Kentucky, where barrel-aging differentiation targets craft foodservice accounts.
South Korea
Sempio Foods Company anchors domestic production serving both household retail and industrial food processing contracts. MFDS maintains positive-list systems for food additives that constrain formulation flexibility for imported sauces, protecting local brewer market share. Seoul Capital Area concentration drives packaging innovation toward portion-control formats for foodservice and convenience retail channels.
Soy-Based Sauce Market Competitive Landscape
Japanese producers anchor the premium heritage tier; Chinese manufacturers hold volume-scale dominance through provincial wholesale penetration. The vendor base stratifies across three strategic archetypes: integrated brewing conglomerates with captive fermentation infrastructure, diaspora-focused heritage brands commanding retail premium, and regional specialists serving quick-service procurement committees. Competitive maneuvering concentrates on backward integration into soybean crushing and geographic expansion through centralized kitchen pre-approval protocols.
Within the integrated brewing tier, Kikkoman Corporation and Foshan Haitian Flavouring & Food Co. Ltd. exemplify divergent scale strategies. Kikkoman leverages Japanese fermentation heritage to secure long-term supply contracts with consolidating Asian foodservice buyers, while Haitian dominates domestic Chinese distribution through deep provincial wholesale market penetration. Lee Kum Kee occupies a position between these poles, differentiating through premium positioning in North American and European diaspora retail channels where tamari variants capture shelf space as celiac awareness spreads.
| Leading Market Players |
|---|
| Foshan Haitian Flavouring & Food Co. Ltd. |
| Kikkoman Corporation |
| Lee Kum Kee |
| Yamasa Corporation |
| Masan Group |
| OTAFUKU SAUCE Co., Ltd. |
| Bourbon Barrel Foods |
| Sempio Foods Company |
| Guangdong Meiweixian Flavoring Foods Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned brewing conglomerates across Japan's Chubu prefectures and China's Guangdong province anchor supply discipline through multi-decade fermentation infrastructure ownership, insulating premium tier pricing from commodity volatility while forcing mid-market players toward cost-competitive centralized kitchen contracts.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for light soy sauce grades bound for instant noodle processing contracts. Three-tier pricing structure across heritage-certified, commercial-standard, and private-label economy levels separates Kikkoman's long-term foodservice agreements from Indonesian QSR procurement committees driving 15-20% cost-down targets. Pricing pressure stems from wheat input volatility in North American harvests. Food processing conglomerates in Southeast Asia exhibit highest price sensitivity; diaspora retail channels in North America absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Jakarta, Surabaya, and Bangkok operate hub-and-spoke patterns feeding centralized kitchen networks. Supply concentrates in China, Japan, and Indonesia for fermentation capacity, with soybean crushing tethered to Brazilian and US Midwest agricultural belts. Raw material dependencies span non-GMO soybeans, Australian and North American wheat, and sea salt from coastal evaporation ponds. Single-source vulnerability runs through Brazil's crushing concentration for Asian brewers. Distribution runs through provincial wholesale markets in China and direct tanker delivery to Thai and Vietnamese food processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
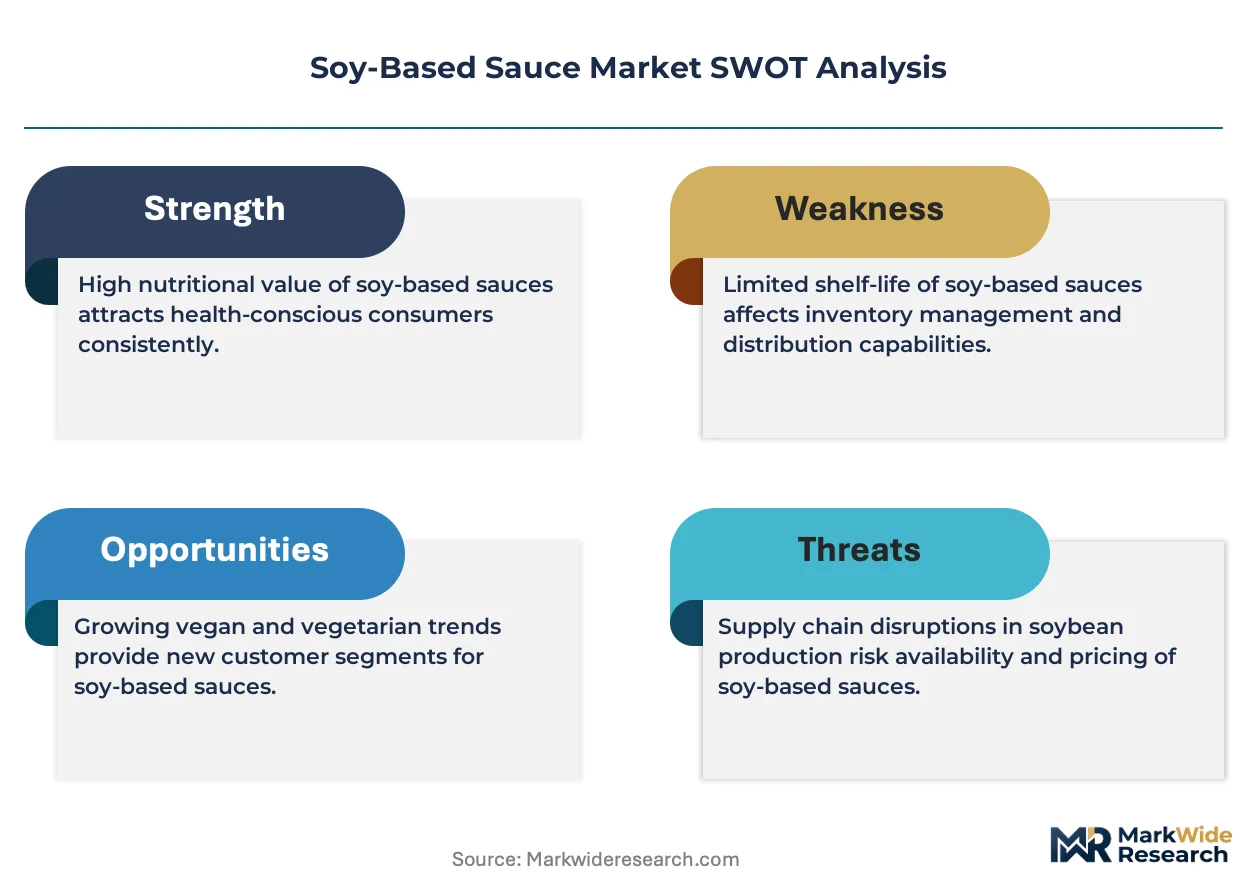
The soy-based sauce market functions as a stable compounder anchored by irreplicable fermentation expertise barriers and recurring institutional procurement contracts across Asia-Pacific foodservice expansion.
For Market Incumbents: Deploy backward integration into captive soybean crushing to secure non-GMO supply chains against Brazilian concentration risk. Accelerate dual-certification packaging investments for Japan's Consumer Affairs Agency and US FDA divergence. Master brewer apprenticeship pipelines must expand to counter aging workforce constraints in Aichi and Mie prefectures. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels in North American and European diaspora markets offer lowest barrier entry for tamari and reduced-sodium variants. Target allergen-free positioning in celiac-aware retail segments where heritage brands command 40-60% shelf price premiums. White-space exists in Indonesian QSR supplier consolidation as committees narrow approved partner lists. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Vietnamese and Thai brewers with continuous-flow fermentation technology but lacking brand equity for export expansion. Five-to-ten year viability hinges on capturing centralized kitchen pre-approval protocols before buyer consolidation hardens. Monitor Indonesia's QSR procurement committee decisions as inflection signal for regional volume allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Fermentation Scale-Up | Vietnamese and Thai brewers compress aging timelines from years to weeks for just-in-time inventory. |
| Dual-Certification Packaging Investment | Exporters bridge Japan's Consumer Affairs Agency and US FDA allergen disclosure divergence. |
| Centralized Kitchen Pre-Approval Capture | Indonesian QSR chains mandate supplier consolidation from dozens to three-to-five partners. |
| Reduced-Sodium Koji Culture Development | Modified fermentation opens institutional foodservice contracts in health-conscious urban markets. |
| Non-GMO Soybean Crushing Integration | Backward integration mitigates Brazilian supply concentration vulnerability for Asian brewers. |
Research Methodology
Multiple input streams — fermentation facility technical audits, procurement committee documentation from Indonesian QSR chains, and customs trade records for soybean and wheat inputs — were reconciled across primary interviews with master brewers, centralized kitchen procurement directors, and food processing R&D leads. Secondary validation drew from SAMR GB standard filings, EFSA additive evaluations, Japan's Consumer Affairs Agency labeling directives, and Nielsen retail audit data for diaspora channels. Bottom-up volume modeling triangulated against top-down category spend estimates.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, format, end user, and packaging configuration alongside regional regulatory cluster divergence. CAGRs were derived from trend extrapolation of procurement contract volumes and capacity expansion announcements. Forecast inputs incorporated master brewer workforce demographics and EFSA 3-MCPD ester limit evolution.
Wheat harvest volatility, EFSA regulatory tightening, and Indonesian QSR procurement committee decisions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions around fermentation cycle durations and buyer concentration trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
UK Prepared Mustard Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Culinary Sauces Market