
 Vacuum Cooling Equipment Market | 2026-2036
Vacuum Cooling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Cooling Equipment Market Analytics
Chinese vacuum pump manufacturers are expanding production capacity for food-grade cooling systems. SHINCCI Energy Equipment Co., Ltd. leverages integrated thermal control systems to anchor its position in energy-efficient designs. ULVAC Inc sustains technology leadership through advanced vacuum insulation engineering. Weber Cooling International BV competes across European fresh produce logistics with specialized batch cooling installations.
Vacuum cooling equipment rapidly reduces product temperature by lowering boiling points under sub-atmospheric pressure, typically achieving core temperatures below 4°C within 20-30 minutes for leafy vegetables. Continuous cooling systems dominate high-volume fresh-cut salad operations where throughput exceeds 5 tonnes per hour, while portable cooling units represent the fastest-growing segment as mobile produce markets and on-farm operations demand flexible deployment. Energy recovery technology captures waste heat for water preheating, creating margin pools for OEMs that integrate thermal control with heat exchange architectures.
FDA food safety regulations mandate rapid temperature reduction for ready-to-eat products, directly shaping vacuum cooling specifications in US processing plants. The EU Green Deal and F-Gas Regulation restrict refrigerant choices and energy intensity, forcing redesigns of vacuum pump systems across European installations. China's MEE enforces dual carbon compliance for industrial equipment, tightening access for non-conforming imports. Stakeholders must monitor evolving efficiency benchmarks and refrigerant phase-down schedules to align R&D pipelines with compliance timelines.
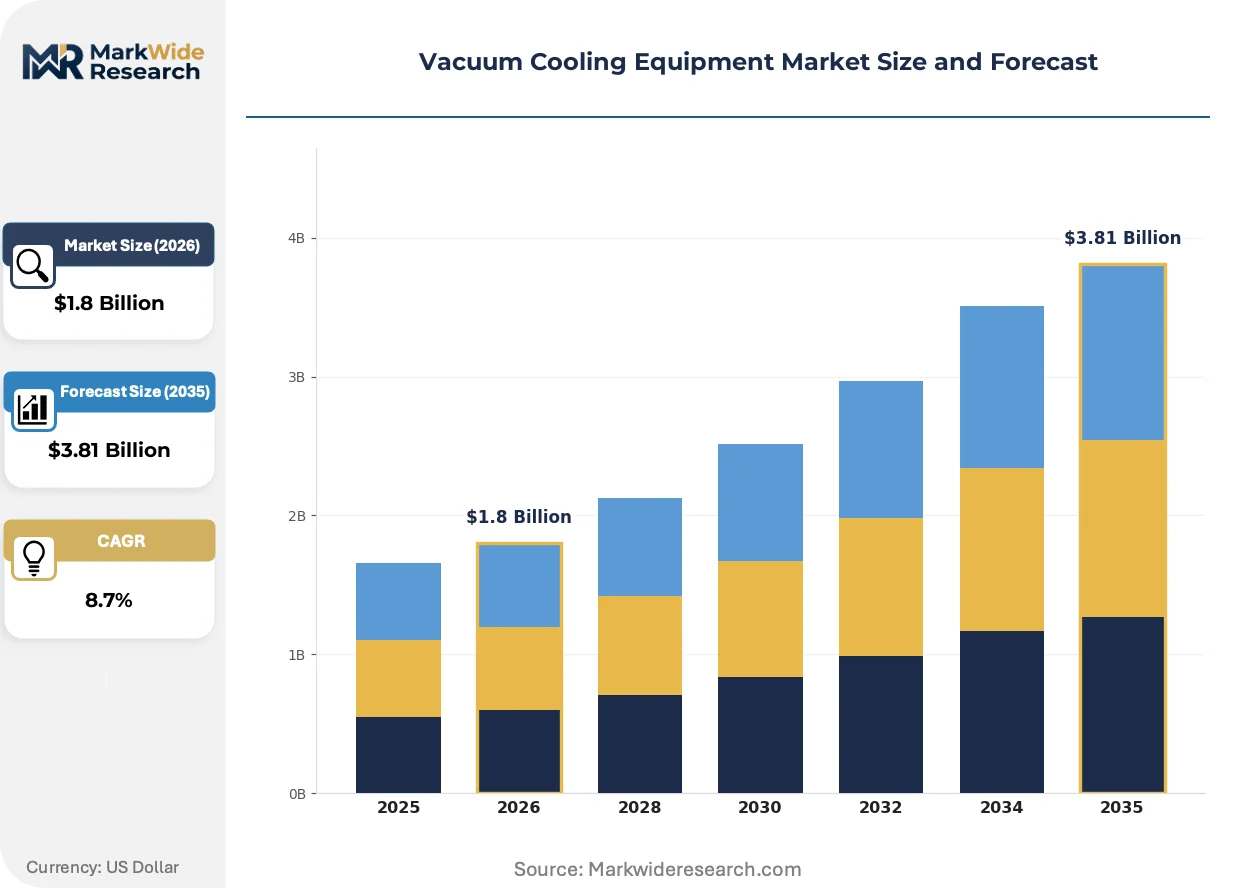
Market Dynamics
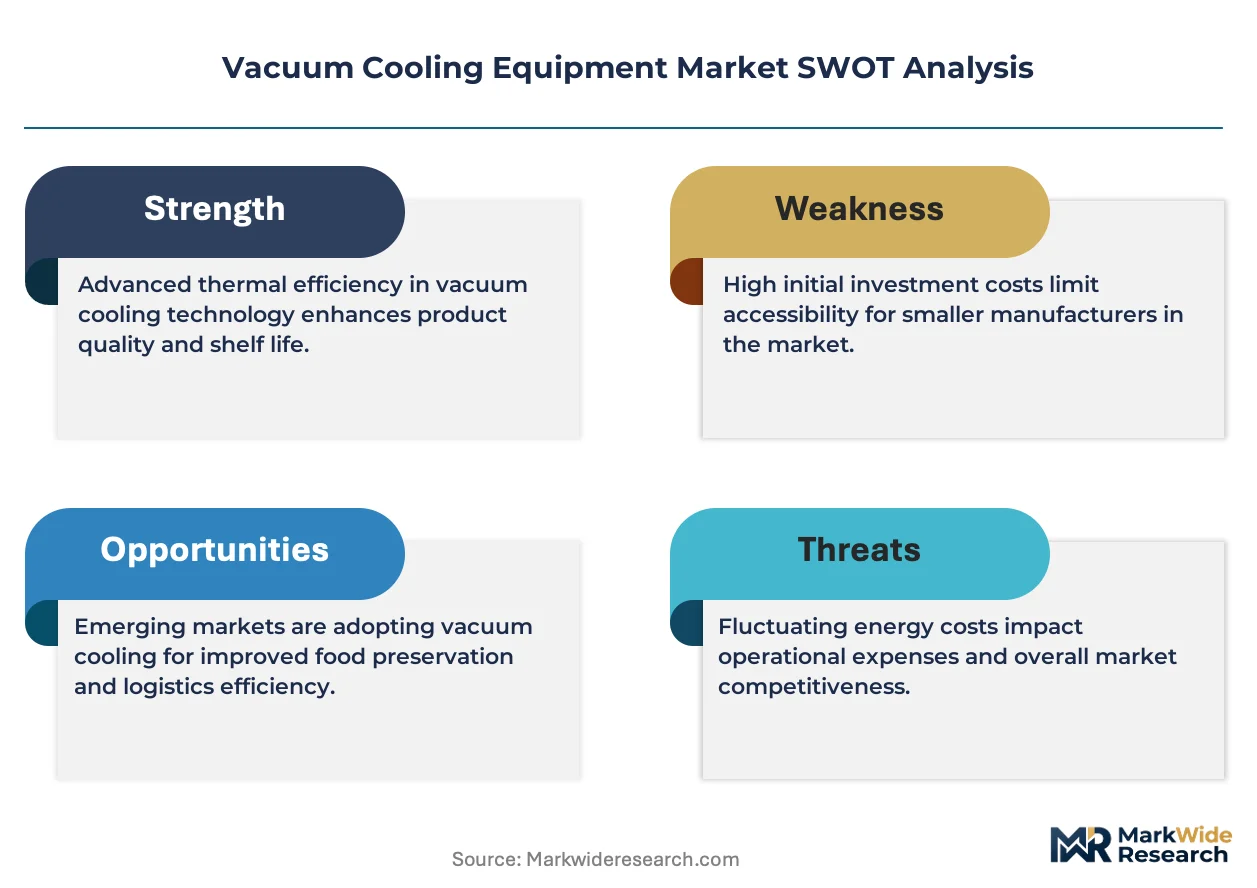
Energy-efficiency mandates from the EU F-Gas Regulation and China's MEE are forcing OEMs to redesign vacuum pump architectures around heat recovery integration, compressing margins for non-compliant equipment while creating premium positioning for thermal control innovators.
Growth Catalysts
- EU F-Gas Regulation phase-down schedules:The refrigerant restrictions accelerate replacement cycles across European fresh produce logistics, pulling demand toward compliant vacuum cooling installations in Germany and the Netherlands.
- Leafy vegetable processors:High-throughput salad operations require sub-4°C core temperatures within 30 minutes, mandating continuous cooling systems that exceed 5 tonnes per hour throughput.
- Mobile produce markets:On-farm and pop-up retail formats drive portable cooling unit demand, extending vacuum cooling beyond fixed processing facilities into flexible deployment models.
Market Restraints
- Stainless steel and vacuum-grade aluminum input costs:Raw material price volatility compresses fabrication margins for batch cooling chambers and vacuum vessel construction.
- German component supplier concentration:Precision vacuum pump manufacturing clusters around Bavarian and Baden-Württemberg industrial corridors, creating single-source exposure for non-European OEMs.
- Mechanical vapor compression substitutes:Blast chilling and hydrocooler alternatives retain cost advantages for non-leafy produce categories, limiting vacuum cooling penetration in root vegetable and stone fruit segments.
Strategic Opportunities
- India's cold chain infrastructure gaps:Post-harvest loss reduction mandates from the country's food safety regulator create first-mover positioning for portable vacuum cooling units in horticultural clusters around Nashik and Bengaluru.
- Bakery and prepared-meal segments:Rapid chilling requirements for cooked rice, pasta, and sauce-based products extend vacuum cooling applicability beyond raw produce into ready-to-eat manufacturing.
- Heat pump convergence with vacuum systems:Integrated thermal architectures capture waste heat for facility water preheating, unlocking energy service company partnerships and recurring revenue streams.
Industry Challenges
- Vacuum system commissioning expertise:Specialized technician shortages delay installation timelines and inflate field service costs for OEMs expanding into emerging markets.
- FDA hazard analysis validation:Ready-to-eat processors face extended certification cycles when integrating vacuum cooling into HACCP-compliant production lines, slowing equipment procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Cooling Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Cooling, Continuous Cooling, Portable Cooling, Industrial Cooling Application: Food Preservation, Agricultural Products, Beverage Cooling, Electronics Cooling End User: Food Industry, Agriculture Sector, Electronics Manufacturers, Pharmaceutical Companies Technology: Vacuum Insulation, Thermal Control, Energy Recovery, Heat Exchange |
| Companies Covered | Verbruggen Vacuum Cooling, TOMCO Systems, SHINCCI Energy Equipment Co., Ltd., Dekker Vacuum Technologies Inc, Dongguan COLDMAX Ltd, Southern Vacuum Cooling Inc, Weber Cooling International BV, ULVAC Inc, Bakery Services BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Cooling Equipment Market Evolving Landscape
Equipment architecture is fragmenting into configurable subsystems that permit field-upgradable thermal control, vacuum pump, and heat exchange modules. This decomposition enables buyers to phase capital deployment while preserving compliance pathway flexibility.
Modular vacuum chamber design is modularizing around standardized flange interfaces and swappable cooling coils. Fresh-cut salad processors in California and the Netherlands adopt these configurations to match seasonal throughput variation without full system replacement. The approach compresses equipment lifecycle costs while extending vendor attachment through upgradeable subsystem contracts.
China's MEE enforcement of dual carbon compliance for industrial cooling equipment tightens import access for non-conforming vacuum pumps. Domestic manufacturers accelerate in-house heat recovery integration to meet efficiency benchmarks. European OEMs face redesign pressure to maintain market position against locally certified competitors.
Buyer preference is consolidating around performance-guaranteed service contracts that unbundle equipment capital from operational responsibility. Food processing corridors in Germany increasingly specify outcome-based chilling commitments rather than hardware procurement. This shift compresses OEM margins on initial sales while extending recurring revenue duration through multi-year thermal service agreements.
Vacuum Cooling Equipment Market Segmentation
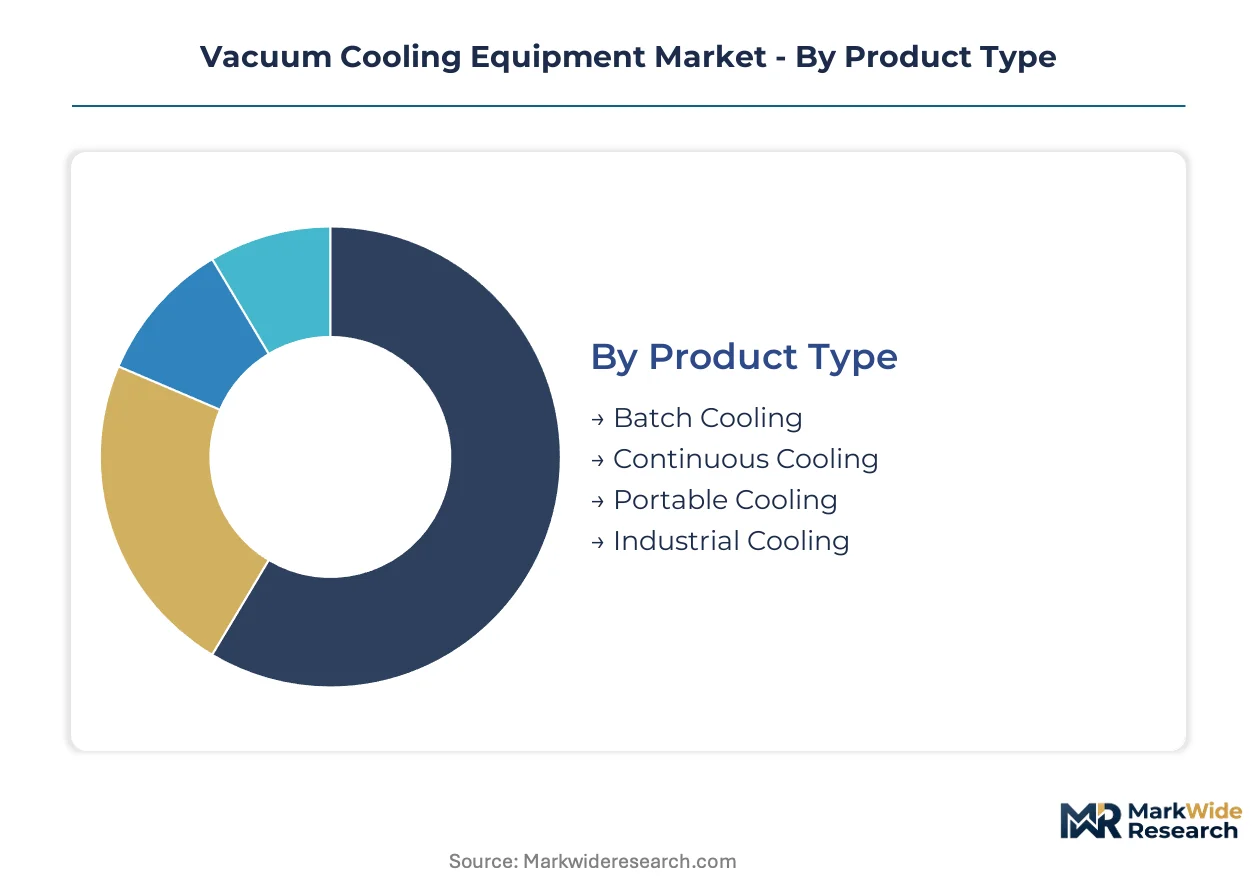
Vacuum cooling equipment segments diverge sharply by capital intensity and deployment flexibility. Batch systems serve seasonal processors while continuous lines anchor permanent installations. Technology choices determine compliance pathways under tightening energy regulations.
Product Type:
Buyer differentiation centers on throughput requirements versus mobility needs across fresh produce logistics.
- Continuous Cooling:High-throughput installations process over 5 tonnes per hour through integrated vacuum chambers and conveyor systems. Fresh-cut salad operations in California and the Netherlands mandate these configurations to meet FDA and EU F-Gas Regulation timelines for rapid temperature reduction.
- Portable Cooling:Self-contained trailer-mounted units deploy to on-farm locations and mobile produce markets. India's horticultural clusters around Nashik and Bengaluru drive demand as FSSAI post-harvest loss mandates extend cold chain reach beyond fixed infrastructure.
- Batch Cooling:Chamber-based systems handle discrete product loads for seasonal processors with variable throughput.
- Industrial Cooling:Heavy-duty configurations serve large-scale food manufacturing corridors with dedicated utility connections.
Continuous cooling leads volumes today; portable cooling is gaining share fastest.
Application:
End-use economics separate commodity produce handlers from premium product processors.
- Food Preservation:Ready-to-eat processors deploy vacuum cooling to achieve sub-4°C core temperatures within 30 minutes for cooked rice, pasta, and sauce-based products. Germany's prepared-meal manufacturing corridor specifies these systems to satisfy EFSA food safety protocols.
- Agricultural Products:Leafy vegetable handlers dominate installed base with rapid post-harvest chilling to extend shelf life. California's Central Valley logistics operators expand capacity as labor costs and spoilage penalties intensify.
- Beverage Cooling:Specialized configurations handle temperature-sensitive liquid processing for craft and industrial producers.
- Electronics Cooling:Precision thermal control serves semiconductor fabrication and battery manufacturing cleanrooms.
Food preservation commands premium pricing; agricultural products maintains the largest installed base.
End User:
Procurement sophistication ranges from outcome-based service contracts to capital equipment ownership.
- Food Industry:Bakery and prepared-meal producers in Germany's processing corridor increasingly specify performance-guaranteed chilling commitments rather than hardware procurement. This shift extends vendor relationships through multi-year thermal service agreements.
- Agriculture Sector:Fresh produce cooperatives and logistics operators prioritize equipment mobility to match seasonal harvest windows across dispersed growing regions.
- Electronics Manufacturers:Cleanroom-grade vacuum cooling supports precision thermal management for sensitive component fabrication.
- Pharmaceutical Companies:Validated cooling systems meet stringent temperature documentation requirements for active ingredient processing.
Food industry drives technology upgrade cycles; agriculture sector shows steepest expansion trajectory.
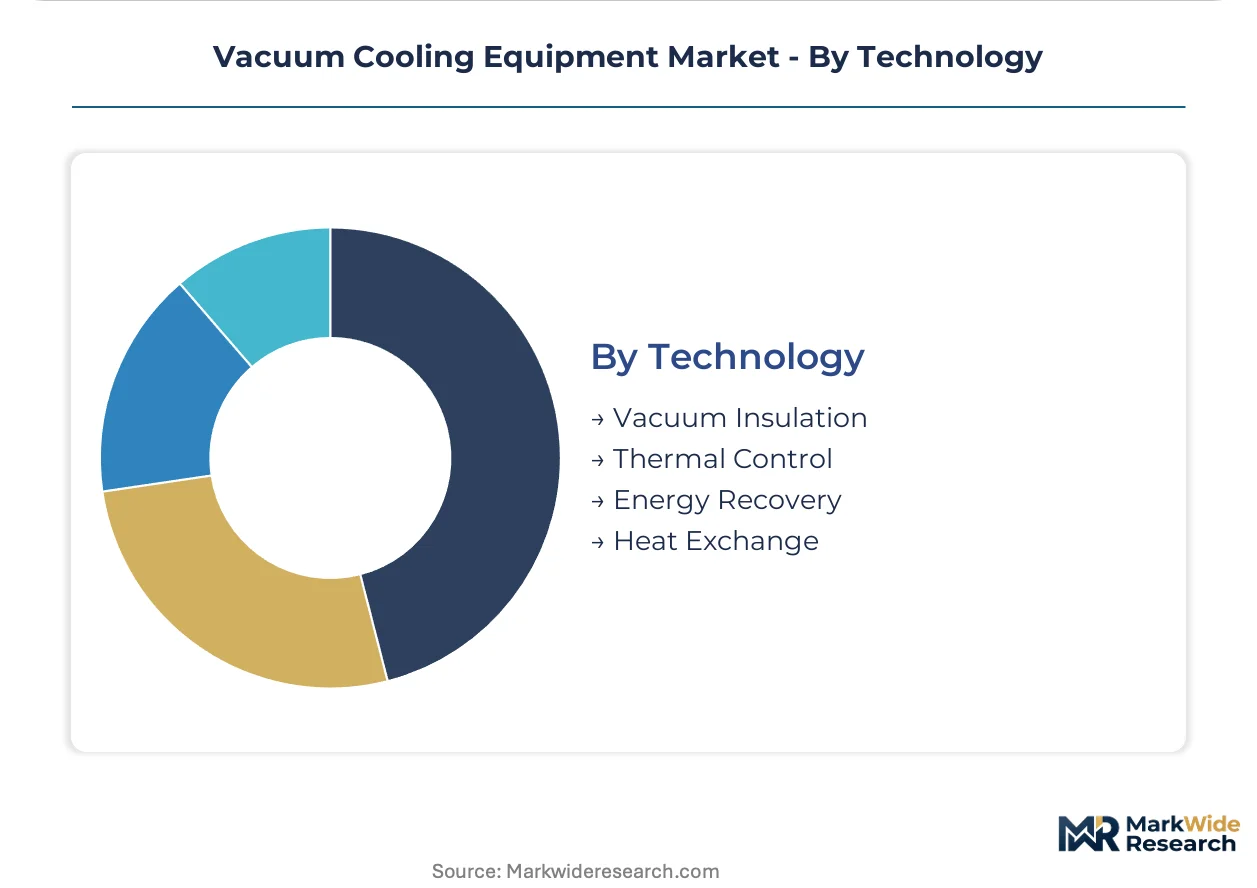
Technology:
Regulatory compliance separates integrated thermal architectures from basic vacuum systems.
- Energy Recovery:Heat capture systems preheat facility water using waste thermal energy from vacuum pump exhaust. China's MEE dual carbon enforcement accelerates domestic manufacturer investment in these configurations to maintain import competitiveness.
- Thermal Control:Integrated sensor networks and automated pressure modulation enable precise temperature trajectory management. EU F-Gas Regulation phase-down schedules force redesigns around these systems to meet efficiency benchmarks.
- Vacuum Insulation:Advanced panel and multi-layer barrier technologies minimize thermal bridging in chamber construction.
- Heat Exchange:Modular swappable coil configurations enable field-upgradable capacity adjustments without full system replacement.
Thermal control dominates current installations; energy recovery shows strongest specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's food processing corridor deploys vacuum cooling at scale for prepared-meal compliance, while India's horticultural clusters still rely on conventional chilling for post-harvest handling. This divergence shapes equipment specification patterns across both mature and emerging installation bases.
Germany
Bakery and ready-to-eat manufacturers in Baden-Württemberg and Bavaria mandate rapid chilling to satisfy EFSA protocols. The EU F-Gas Regulation phase-down forces vacuum pump redesigns around heat recovery integration. Stuttgart's precision engineering cluster supplies critical vacuum components to domestic OEMs.
United States
Fresh-cut salad processors in California's Central Valley exceed 5 tonnes per hour throughput requirements. FDA hazard analysis validation extends certification cycles for HACCP-compliant production lines. Salinas Valley logistics operators expand vacuum cooling capacity as labor costs and spoilage penalties intensify.
China
Domestic manufacturers accelerate in-house heat recovery development to meet MEE dual carbon enforcement. The country's tightening efficiency benchmarks restrict import access for non-conforming vacuum pumps. Yangtze River Delta equipment fabricators anchor production for food-grade cooling systems.
India
FSSAI post-harvest loss reduction mandates create positioning for portable vacuum cooling units. Nashik and Bengaluru horticultural clusters demand mobile deployment as fixed cold chain infrastructure remains underdeveloped. The country's national food safety regulator extends compliance timelines to regional produce markets.
Netherlands
Fresh produce logistics operators adopt modular vacuum chamber configurations for seasonal throughput flexibility. EU Green Deal efficiency requirements accelerate replacement cycles across Rotterdam-Antwerp distribution corridors. Wageningen-region technology providers integrate thermal control with automated pressure modulation systems.
Vacuum Cooling Equipment Market Competitive Landscape
German component suppliers anchor one tier of precision vacuum pump manufacturing; Chinese fabricators hold cost-optimized positions for standardized equipment. The vendor base splits between integrated thermal architecture specialists and batch chamber constructors. Two strategic archetypes dominate: energy-recovery technology integrators and modular subsystem providers. Capacity expansion and geographic licensing partnerships represent the primary competitive vectors.
Within the thermal control tier, SHINCCI Energy Equipment Co., Ltd. and ULVAC Inc exemplify divergent regional approaches to efficiency compliance. Weber Cooling International BV occupies a position among European fresh produce logistics specialists. These three entities represent the geographic and technological segmentation visible across installation bases.
| Leading Market Players |
|---|
| Verbruggen Vacuum Cooling |
| TOMCO Systems |
| SHINCCI Energy Equipment Co., Ltd. |
| Dekker Vacuum Technologies Inc |
| Dongguan COLDMAX Ltd |
| Southern Vacuum Cooling Inc |
| Weber Cooling International BV |
| ULVAC Inc |
| Bakery Services BV |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down schedules gate qualified supply for premium-tier vacuum cooling equipment, compressing margins for non-compliant fabricators while rewarding thermal control innovators with pricing power. Stainless steel and vacuum-grade aluminum input costs tether batch chamber construction to commodity volatility, forcing OEMs to index long-term service contracts against raw material benchmarks.
Pricing Analysis
Capacity additions in China are reshaping price floors for standardized vacuum pump systems, displacing European mid-tier offerings in emerging markets. Three-tier pricing structure across premium, standard, and economy levels separates energy-recovery-integrated thermal architectures from basic batch configurations. Cost compression in economy tiers intensifies because Yangtze River Delta fabricators scale food-grade cooling production. Fresh produce cooperatives in India's agriculture sector exhibit highest price sensitivity; Germany's prepared-meal manufacturers show lowest, prioritizing EFSA-compliant performance guarantees over capital expenditure minimization.
Supply Chain Analysis
Freight cost escalation from Bavarian and Baden-Württemberg precision component clusters to non-European assembly sites is amplifying landed cost differentials for vacuum pump subsystems. Manufacturing concentrates in Germany, China, and the Netherlands, with Stuttgart's engineering corridor supplying critical vacuum insulation components. Supply chains draw from stainless steel mills, vacuum-grade aluminum foundries, and precision-machined flange interfaces. Single-source vulnerability concentrates around German component suppliers for high-precision vacuum pumps. Distribution runs through OEM-direct channels for large installations and regional equipment distributors for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum cooling equipment functions as a stable compounder, with regulatory-driven replacement cycles providing predictable demand visibility across food safety mandates.
For Market Incumbents: Deepen backward integration into precision vacuum pump manufacturing to reduce exposure to Bavarian supplier concentration. Anchor capacity expansion in China's Yangtze River Delta to capture MEE dual carbon compliance premiums. Mechanical vapor compression substitutes threaten margin compression in root vegetable segments; counter with thermal service contract bundling that locks in multi-year recurring revenue. For New Entrants and Emerging Players: Begin with portable cooling unit deployment in India's Nashik and Bengaluru horticultural clusters, where FSSAI post-harvest loss mandates outpace fixed cold chain infrastructure development. Mobile produce markets represent the most penetrable application layer. Pursue outcome-based chilling commitments rather than equipment sales to bypass capital-constrained buyer resistance. For Investors and Strategic Acquirers: Roll-up economics work for regional thermal service providers because outcome-based contracts generate sticky recurring revenue with embedded upgrade pathways. Five-to-ten-year viability hinges on regulatory compliance deepening rather than technological disruption. Target acquisition archetype: modular subsystem specialists with field-upgradable thermal control architectures. Signal to watch: EU F-Gas Regulation enforcement intensity accelerating replacement pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery Integration | Captures waste thermal energy for facility water preheating, satisfying China's MEE dual carbon benchmarks. |
| Modular Subsystem Architecture | Enables field-upgradable vacuum chambers without full system replacement, extending vendor attachment duration. |
| Portable Unit Geographic Expansion | Extends vacuum cooling reach into India's underdeveloped cold chain infrastructure per FSSAI mandates. |
| Performance-Guaranteed Service Contracts | Unbundles equipment capital from operational responsibility, aligning vendor incentives with EFSA compliance outcomes. |
| Precision Component Backward Integration | Reduces single-source exposure to German vacuum pump suppliers while capturing margin pools in thermal control. |
Research Methodology
Coverage spans Germany, the United States, China, India, and the Netherlands, with primary inputs from each market informing demand calibration. The research combines structured interviews with food processing plant engineers, cold chain logistics operators, OEM procurement teams, and aftermarket service heads with secondary validation from EU F-Gas Regulation filings, China's MEE enforcement notices, FDA hazard analysis guidelines, and FSSAI post-harvest loss mandates. Bottom-up equipment shipment tracking triangulates against top-down food industry capital expenditure analysis.
Segmentation dimensions were modeled at product type, application, end user, and technology levels across the projection horizon. Continuous versus portable versus batch cooling configurations received distinct throughput and mobility assumptions. Thermal control, energy recovery, vacuum insulation, and heat exchange technologies were separately parameterized for compliance pathway analysis. CAGRs were derived from replacement cycle timing under regulatory phase-down schedules and penetration elasticity in emerging horticultural clusters. Industry-specific inputs included salad processor throughput requirements, bakery chilling protocols, and mobile produce market deployment patterns.
Several conditions sit outside the modeled scope, including abrupt refrigerant technology shifts, trade policy disruptions affecting German component flows, and subsidy program cancellations in India's agriculture sector. Forecasts reflect assumptions about regulatory enforcement continuity and capital availability for cold chain infrastructure. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Seafood Processing Equipment Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Mushroom Fermenter Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market