
 GCC Condiment Sauces (for Hospitality Sector) Market | 2026-2036
GCC Condiment Sauces (for Hospitality Sector) Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Condiment Sauces (for Hospitality Sector) Market Foresight
Consolidation among fast-food chains and international hotel operators is repositioning procurement power toward centralized purchasing consortia in the GCC. Unilever leverages its manufacturing footprint across the Gulf to supply standardized formulations to multi-property hospitality groups. Nestlé sustains competitive pressure through specialized foodservice channels tailored to regional palate preferences. Golden State Foods anchors North American-format quick-service restaurant supply with localized production adaptations.
GCC condiment sauces for hospitality comprise commercially formulated tomato-based, emulsified, vinegar-based, and pepper-derived preparations manufactured to pH, viscosity, and preservative specifications ensuring shelf stability under ambient Gulf temperatures. Their primary purpose is flavor standardization across high-volume kitchen operations subject to batch consistency requirements. Mayonnaise and ketchup occupy the largest volume positions due to universal menu integration across casual dining and fast food chains, while hot sauce and barbecue sauce segments capture expanding interest from fine dining establishments seeking differentiated flavor profiles. Sachet packaging dominates airline and institutional kitchen applications where portion control and waste reduction determine procurement logic.
Saudi Food and Drug Authority standards, UAE Ministry of Climate Change and Environment halal certification protocols, and GCC Standardization Organization technical regulations collectively govern ingredient sourcing, additive permissions, and import documentation for condiment sauces. Compliance with these frameworks determines market access eligibility and shapes reformulation investments by international suppliers. Stakeholders must monitor evolving Gulf-wide harmonization of food additive standards and the trajectory of local sourcing mandates affecting import-dependent supply structures.
Market Dynamics
Centralized procurement consortia across Saudi Arabia and the UAE are consolidating purchasing power, forcing suppliers to restructure pricing and service models around multi-property contracts rather than individual hotel negotiations.
Growth Catalysts
- SFDA Labeling Mandates:Tightened ingredient disclosure requirements for imported sauces are accelerating domestic formulation partnerships, creating localized production incentives.
- Dubai Hospitality Corridor:International hotel brands anchoring bulk agreements in this cluster are standardizing condiment specifications across their Gulf portfolios.
- Hot Sauce Segment Expansion:Fine dining establishments seeking differentiated flavor profiles are diversifying beyond mayonnaise and ketchup volumes.
Market Restraints
- Import Dependency:Heavy reliance on foreign-sourced raw materials exposes margins to shipping cost volatility and currency fluctuation.
- Halal Certification Complexity:UAE Ministry of Climate Change and Environment protocols require multi-stage verification, extending supplier onboarding timelines.
- Temperature-Stability Requirements:Ambient Gulf heat necessitates preservative-heavy formulations that constrain clean-label positioning.
Strategic Opportunities
- Qatar Hospitality Buildout:FIFA legacy infrastructure and new luxury hotel supply create underpenetrated demand for premium condiment portfolios.
- Sachet-to-Pouch Format Shift:Airline catering and institutional kitchens are transitioning from rigid portion packs to flexible retort pouches for waste reduction.
- Kuwait Food Manufacturing Zones:Government incentives for local production are attracting backward integration investments from regional suppliers.
Industry Challenges
- Reformulation Talent Scarcity:Food chemists capable of balancing pH stability, halal compliance, and clean-label demands command premium compensation in the Gulf.
- Batch Consistency at Scale:High-volume kitchen operations require viscosity specifications tighter than standard manufacturing tolerances permit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Condiment Sauces (for Hospitality Sector) Market |
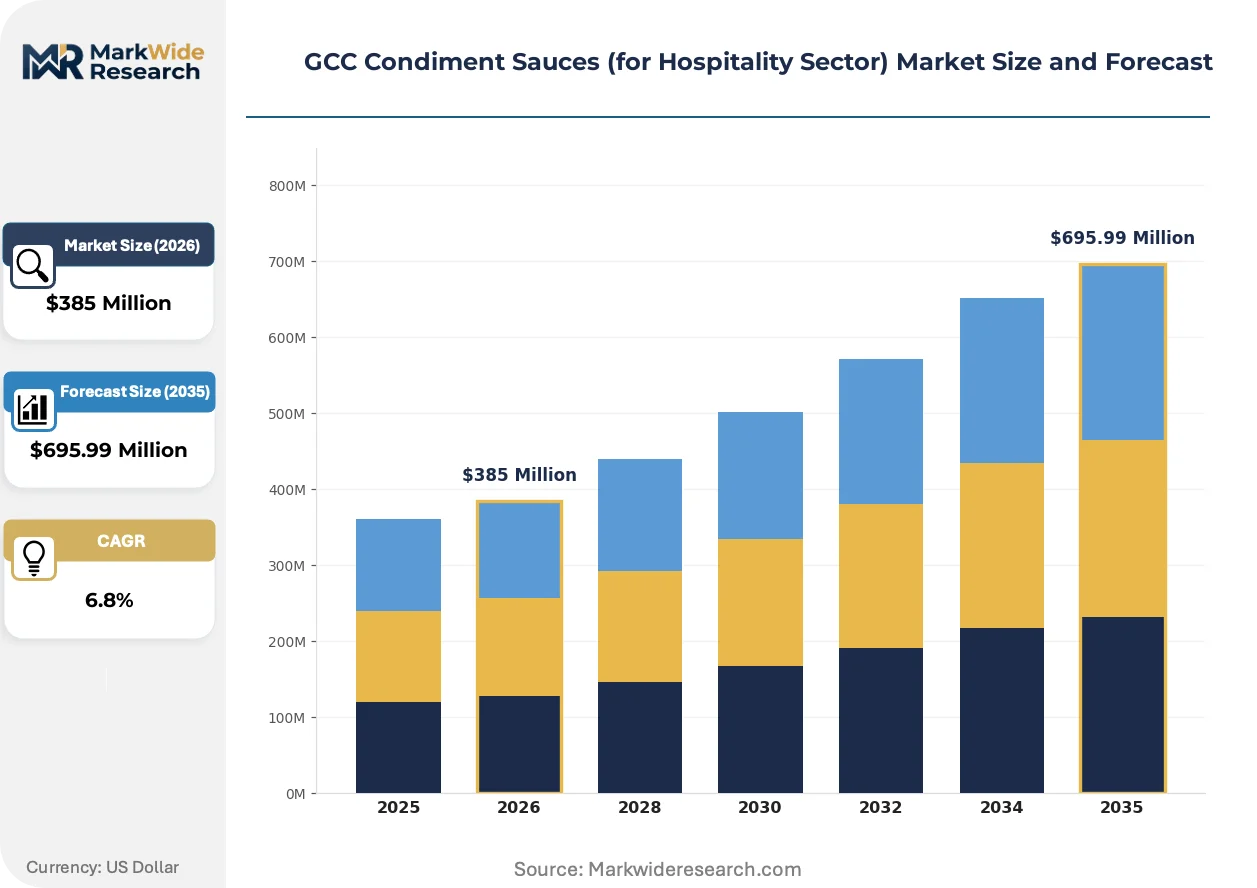
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $695.99 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketchup, Mayonnaise, Mustard, Barbecue Sauce, Hot Sauce, Salad Dressing Application: Fine Dining Restaurants, Casual Dining, Fast Food Chains, Catering Services, Cafes, Food Trucks Packaging Type: Bottles, Sachets, Jars, Tubes, Bulk Containers, Dispensers End User: Hotels, Resorts, Event Management Companies, Airlines, Cruise Lines, Institutional Kitchens |
| Companies Covered | Unilever, Ajinomoto, Golden State Foods, Remia International, Pinehill Arabia Food Ltd., Saudia Dairy & Foodstuff Co. Ltd. (SADAFCO), Nestlé, Heinz, Gyma Food Industries LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Condiment Sauces (for Hospitality Sector) Market Shifts & Advancements
Active reformulation investments are reshaping competitive positioning around preservative reduction, localized production, and packaging format innovation tailored to Gulf climate and regulatory conditions.
Clean-label enzyme technologies are decentralizing preservative-dependent supply chains by enabling ambient-stable formulations without synthetic additives. Full-service hotel chains in Riyadh and Jeddah are piloting these enzyme-stabilized batches for premium menu lines. The shift is decentralizing quality control from centralized manufacturing plants toward on-site kitchen validation protocols.
GCC Standardization Organization technical regulations are harmonizing additive permissions across member states, reducing the compliance fragmentation that previously required country-specific formulations. Industrial consequence includes accelerated cross-border distribution for standardized product lines. Saudi Arabia and Bahrain are responding fastest, with suppliers consolidating previously separate national SKUs into unified Gulf-wide specifications.
Consortium-based purchasing is compressing supplier negotiation cycles from annual to quarterly reviews, with procurement teams demanding real-time inventory visibility. Traditional distributor networks serving independent restaurants are losing share to direct-manufacturer relationships with hospitality groups. This pattern is most visible in Dubai, where international hotel operators have established dedicated foodservice supply divisions.
GCC Condiment Sauces (for Hospitality Sector) Market Segmentation
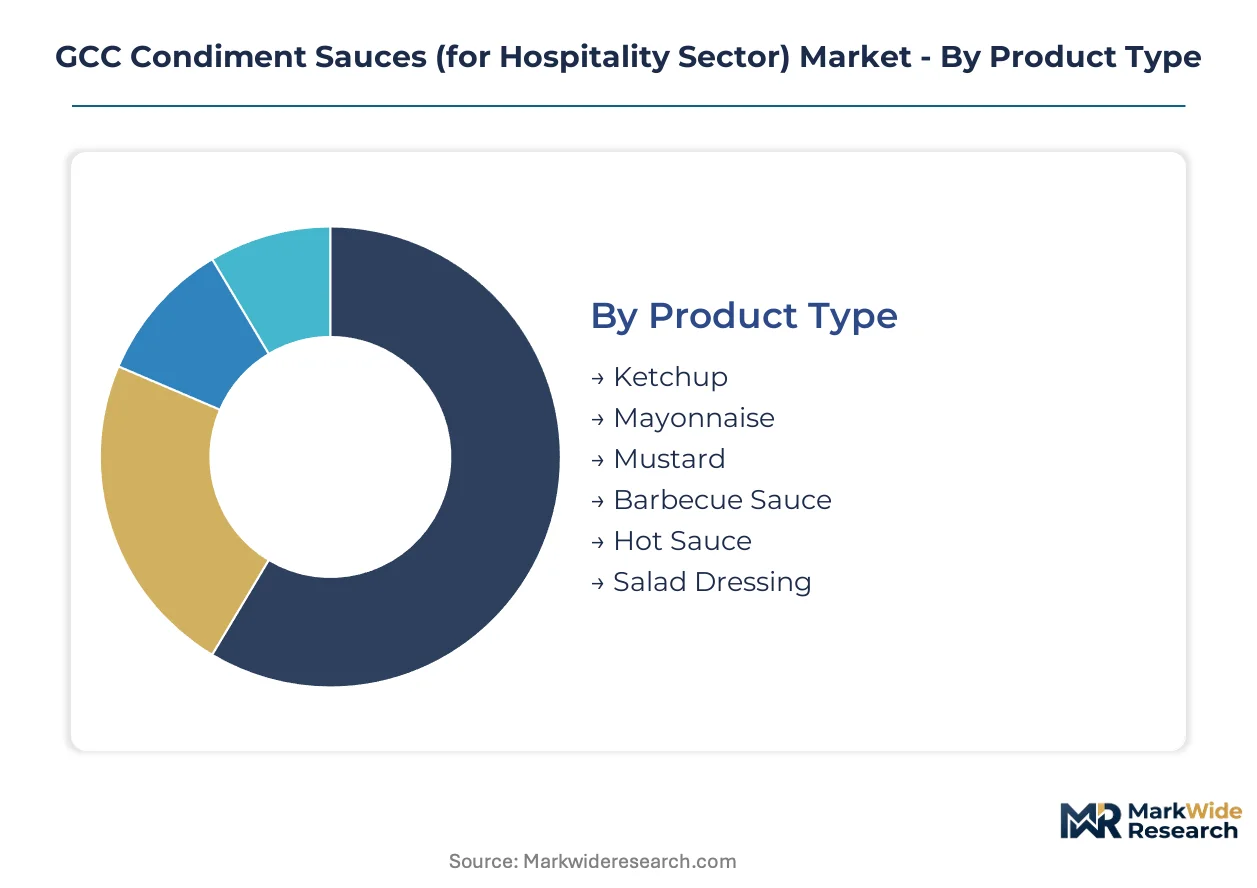
Condiment sauce procurement in the GCC hospitality sector fragments across product chemistry, service format, and operational scale. Each segmentation dimension carries distinct specification requirements that reshape supplier capability investments and contract structuring.
Product Type:
Upgrade cycles in Gulf hotel kitchens accelerate as international brands enforce formulation standardization across property portfolios.
- Ketchup:Tomato-based formulations with pH stabilization between 3.5-4.0 ensure ambient shelf stability in Gulf climates. Procurement concentrates in Dubai's fast-food corridor where centralized commissary agreements lock in multi-year volume commitments.
- Mayonnaise:Emulsified oil-in-water preparations require pasteurization and acidification for ambient distribution without refrigeration. Demand clusters in Riyadh's full-service hotel sector where breakfast buffet operations drive institutional-scale purchasing.
- Mustard:Vinegar-based seed emulsions serve niche sandwich and deli applications in premium casual dining.
- Barbecue Sauce:Molasses-tomato blends with smoke flavoring capture fine dining menu diversification in Jeddah's waterfront restaurant cluster.
- Hot Sauce:Capsicum-derived heat profiles with vinegar or fermented bases attract chef-driven experimentation in Abu Dhabi's luxury hotel kitchens.
- Salad Dressing:Emulsified and vinaigrette formats support airline catering and institutional healthcare feeding operations.
Volume placements concentrate in Ketchup and Mayonnaise; the faster expansion belongs to Hot Sauce.
Application:
Cost tier stratification separates premium formulation specifications from economy-grade procurement in high-volume channels.
- Fine Dining Restaurants:Small-batch artisanal sauces with clean-label positioning command chef-driven specification authority. Procurement in Doha's West Bay district favors regional flavor adaptations over standardized imports.
- Fast Food Chains:Centralized commissary supply demands viscosity tolerances within 2% batch-to-batch variation. Saudi Arabia's QSR expansion drives the largest contract volumes in the GCC.
- Casual Dining:Mid-tier pricing accommodates both proprietary house formulations and modified stock sauces.
- Catering Services:Event-scale production requires sachet and pouch formats for portion control and waste minimization.
- Cafes:Limited menu scope favors multi-purpose sauces reducing SKU complexity.
- Food Trucks:Mobile operations prioritize shelf-stable squeeze formats and ambient storage compatibility.
Contract value concentrates in Fast Food Chains; menu differentiation gains share fastest in Fine Dining Restaurants.
Packaging Type:
Format selection traces directly to waste reduction mandates and labor cost pressures across kitchen operation types.
- Sachets:Single-serve foil-laminate portions dominate airline and institutional feeding where portion control compliance is mandatory. Emirates Flight Catering in Dubai anchors the GCC's largest sachet procurement contract.
- Bulk Containers:10-20 liter bag-in-box and pail formats serve high-throughput commissary kitchens with dedicated sauce dispensing systems. Saudi fast-food commissaries drive regional volume leadership.
- Bottles:Table-service glass and PET formats persist in full-service restaurants with front-of-house presentation requirements.
- Jars:Wide-mouth glass packaging retains niche position in specialty and import-positioned sauces.
- Tubes:Collapsible aluminum and laminate formats serve mobile catering and limited-space kitchen configurations.
- Dispensers:Pump and gravity-fed systems integrate with fast-casual counter service workflows.
Volume concentrates in Sachets and Bulk Containers; sustainability-driven format shift is climbing fastest in Dispensers.
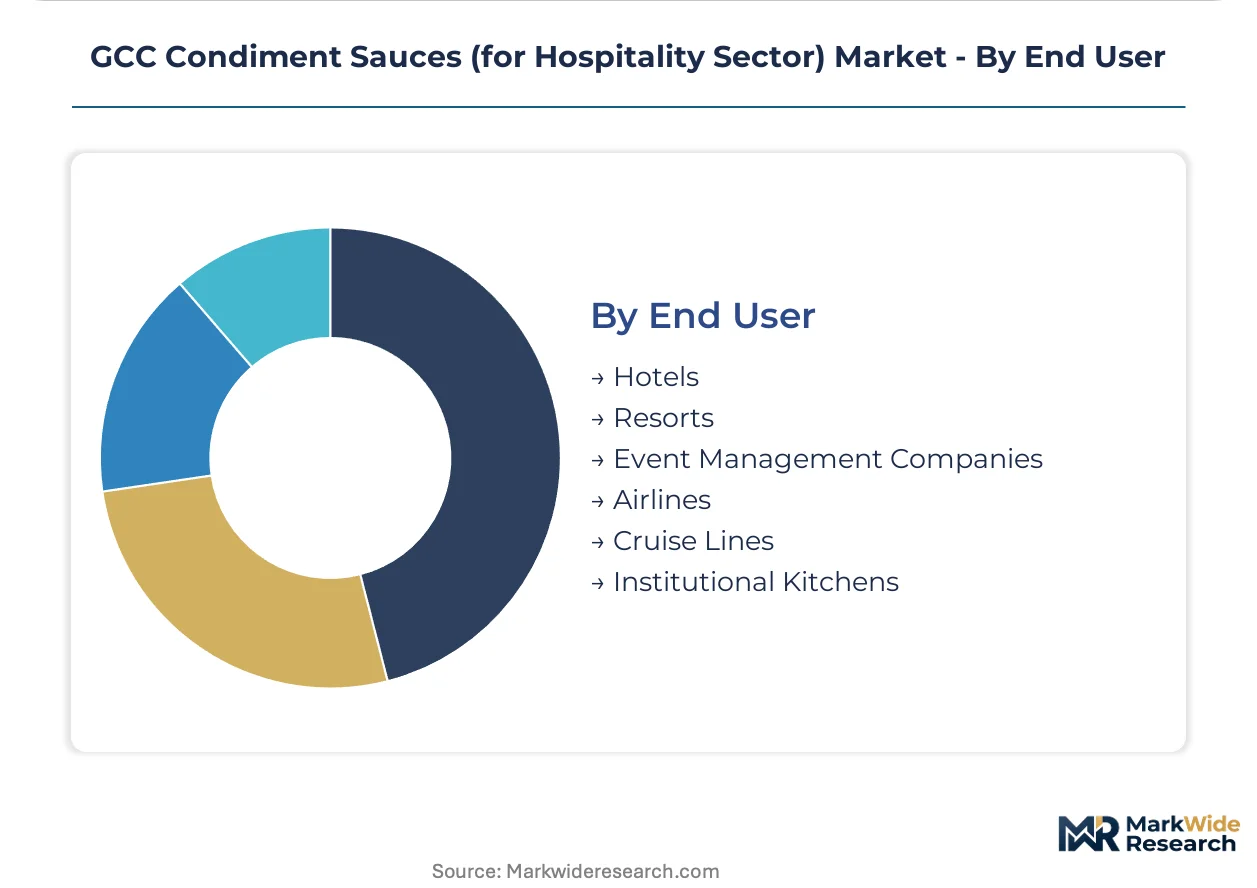
End User:
Customer-type segmentation reveals divergent specification authority between procurement consortia and individual property operators.
- Hotels:International brand standards enforce cross-property formulation consistency, consolidating supplier relationships through regional procurement hubs in Dubai and Riyadh. Marriott and Hilton's Gulf foodservice divisions negotiate master agreements covering 50+ properties.
- Airlines:Halal certification at production source and in-flight weight minimization drive sachet-format dominance. Etihad Airways and Qatar Airways maintain dedicated sauce specification teams.
- Resorts:Destination properties with multiple outlet types require portfolio breadth from single-supplier relationships.
- Event Management Companies:Temporary infrastructure demands ambient-stable formats with minimal equipment dependency.
- Cruise Lines:Maritime supply logistics favor extended-shelf-life formulations and consolidated provisioning.
- Institutional Kitchens:Healthcare and education feeding operations prioritize cost containment over flavor differentiation.
Contract value concentrates in Hotels; specification sophistication is expanding most quickly in Airlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement power concentrates in Saudi Arabia and the UAE, where international hotel chains and fast-food consortia anchor bulk purchasing agreements. Qatar and Kuwait represent emerging demand pockets driven by hospitality infrastructure expansion. Bahrain and Oman serve secondary markets with specialized catering requirements.
Saudi Arabia
Riyadh's full-service hotel sector and Jeddah's waterfront restaurant cluster drive institutional-scale condiment procurement. The Saudi Food and Drug Authority tightened labeling mandates for imported sauces, accelerating domestic formulation partnerships. Eastern Province fast-food commissaries now lock in multi-year volume commitments for standardized ketchup and mayonnaise specifications.
United Arab Emirates
Dubai's hospitality corridor anchors the GCC's largest centralized purchasing agreements for premium condiment portfolios. The UAE Ministry of Climate Change and Environment enforces multi-stage halal certification protocols that extend supplier onboarding timelines. Emirates Flight Catering in Dubai maintains the region's dominant sachet procurement contract for airline catering applications.
Qatar
FIFA legacy infrastructure and new luxury hotel supply create underpenetrated demand for differentiated sauce formulations. The country's national food regulator maintains strict import documentation requirements for additive permissions. Doha's West Bay district favors chef-driven regional flavor adaptations over standardized imports for fine dining procurement.
Kuwait
Government incentives for local production attract backward integration investments from regional suppliers seeking to reduce import dependency. Food manufacturing zones offer tax advantages for domestic formulation facilities. Kuwait City's hospitality sector shows accelerating interest in clean-label enzyme technologies for premium menu lines.
Bahrain
Cross-border distribution advantages position the kingdom as a consolidation hub for Gulf-wide SKU standardization. GCC Standardization Organization harmonization efforts enable unified product specifications across member states. Manama's catering services sector prioritizes ambient-stable formats for event-scale production with minimal equipment dependency.
GCC Condiment Sauces (for Hospitality Sector) Market Competitive Landscape
European and North American producers anchor one tier; Gulf-based specialists hold localized formulation advantages. The supplier base organizes around three strategic archetypes: multinational FMCG conglomerates with standardized Gulf-wide portfolios, regional dairy and food processors with halal-certified captive production, and hospitality-focused foodservice distributors with specialized logistics networks. Competitive moves concentrate on multi-property contract consolidation and backward integration into domestic manufacturing capacity.
Within the multinational tier, Unilever and Nestlé represent archetypal positions. Unilever leverages its manufacturing footprint across the Gulf to supply standardized formulations to multi-property hospitality groups. Nestlé sustains competitive pressure through specialized foodservice channels. Among regional processors, Saudia Dairy & Foodstuff Co. Ltd. (SADAFCO) exemplifies the halal-certified domestic producer archetype with localized production adaptations for Saudi procurement consortia.
| Leading Market Players |
|---|
| Unilever |
| Ajinomoto |
| Golden State Foods |
| Remia International |
| Pinehill Arabia Food Ltd. |
| Saudia Dairy & Foodstuff Co. Ltd. (SADAFCO) |
| Nestlé |
| Heinz |
| Gyma Food Industries LLC |
| Others |
Supply & Pricing Matrix
Tomato paste commodity indices from Italy and China cascade through GCC condiment manufacturing into three distinct pricing tiers, with bulk procurement consortia in Dubai and Riyadh extracting volume discounts that compress margins for import-dependent suppliers while enzyme-stabilized premium formulations command chef-driven specification premiums.
Pricing Analysis
High-volume ketchup and mayonnaise placements sacrifice margin for contract security while hot sauce and clean-label specialty lines retain pricing power. Three-tier pricing structure across premium enzyme-stabilized, standard preservative-based, and economy-grade bulk formats separates chef-specified boutique production from commissary-scale supply. Pricing pressure stems from centralized purchasing consortia consolidating multi-property negotiations into quarterly rather than annual cycles. Fast-food chains exhibit highest price sensitivity due to standardized menu requirements; fine dining establishments show lowest sensitivity where flavor differentiation justifies premium positioning.
Supply Chain Analysis
Direct-manufacturer relationships with hospitality groups now bypass traditional distributor networks for properties above 50-unit portfolios. Raw material sourcing concentrates in Italy and China for tomato paste, Malaysia and Indonesia for palm oil derivatives, and India for spice inputs. Single-source vulnerability runs through Red Sea shipping corridors where container rate volatility feeds directly into landed cost structures. Distribution runs through Dubai and Jeddah consolidation hubs serving Gulf-wide property networks with ambient-stable inventory pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over halal-certified formulation capacity determines contract viability against import-dependent competitors facing SFDA compliance cost escalation.
For Market Incumbents: Extend captive production footprints into Kuwait's food manufacturing zones to capture government incentive structures and reduce import dependency exposure. Consolidate previously separate national SKUs into unified Gulf-wide specifications as GCC Standardization Organization harmonization accelerates cross-border distribution. Counter reformulation talent scarcity through dedicated food chemistry training partnerships with Saudi technical universities. For New Entrants and Emerging Players: The gap between premium enzyme-stabilized and economy bulk pricing creates entry space for mid-tier clean-label specialists. Qatar's underpenetrated luxury hotel supply offers the most penetrable geography following FIFA legacy infrastructure completion. Target airline catering divisions with sachet-to-pouch format innovation emphasizing weight reduction and waste minimization compliance. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional dairy processors with existing halal certification infrastructure in Saudi Arabia and the UAE. Long-term viability across the analysis window hinges on domestic formulation capability rather than import-reliant trading positions. Monitor SFDA local sourcing mandate trajectory as the critical inflection signal for import-dependent supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Formulation | SFDA labeling mandates accelerate localized production partnerships reducing import compliance costs. |
| Enzyme-Stabilized Product Line Launch | Clean-label positioning captures chef-driven specification authority in Riyadh and Jeddah premium kitchens. |
| Flexible Retort Pouch Format Expansion | Airline catering transition from sachets creates procurement opening with Emirates Flight Catering scale. |
| Multi-Property Master Agreement Consolidation | Marriott and Hilton Gulf divisions centralize purchasing power through regional foodservice hubs. |
| Halal Certification Infrastructure Investment | UAE Ministry of Climate Change and Environment protocols extend supplier onboarding timelines for unprepared entrants. |
Research Methodology
Document review covered customs and trade databases, GCC Standardization Organization technical regulations, and hospitality procurement contract disclosures, complemented by interviews with foodservice procurement directors at international hotel chains, regulatory affairs specialists at Saudi and UAE food authorities, and supply chain managers at regional dairy processors. Secondary validation drew from SFDA additive permission filings, airline catering specification documents, and food manufacturing zone incentive announcements. Bottom-up volume estimates from individual property procurement scales were triangulated against top-down market value assessments.
Cross-referencing historical procurement contract structures against panel input from procurement consortium executives established the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry type, service format tier, packaging configuration, and operational scale category. CAGRs were derived from trend extrapolation of procurement volume commitments and price trajectory assumptions. Forecast inputs incorporated halal certification pipeline timelines and enzyme technology adoption curves in premium kitchen segments.
Inputs from regulatory filing databases and hospitality group annual disclosures were available through the study window; gaps in private-label contract pricing introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding GCC harmonization pace and local sourcing mandate implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sauce Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Condiments Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Mayonnaise Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Prepared Mustard Market