
 Compound Condiments Market | 2026-2036
Compound Condiments Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Condiments Market Insights
Flavor chemist and fermentation specialist availability is bifurcating the competitive landscape between heritage producers and industrial scale operators. Lee Kum Kee leverages century-old brewing mastery to sustain premium positioning in soy-based compound sauces. Kraft Heinz anchors North American retail shelf space through manufacturing scale and cold-fill processing infrastructure. Haitian Group dominates China's mass-market segment with vertically controlled fermentation capacity spanning Guangdong and Jiangsu provinces.
Compound condiments represent blended or multi-step processed flavoring preparations combining base ingredients such as fermented soybean paste, vinegar, sweeteners, and stabilizers into ready-to-use formulations with standardized viscosity, pH, and shelf-life parameters. These products serve commercial kitchens and retail consumers by delivering consistent flavor intensity without requiring ingredient assembly from scratch. The savory flavor profile segment leads absolute volume given its ubiquity in Asian and Western cooking applications, while spicy variants generate disproportionate margin expansion through premium positioning in North American and European specialty channels. Pouch packaging is accelerating fastest among format options, driven by foodservice portion-control requirements and reduced logistics cost per unit compared to glass alternatives.
FDA nutrition labeling mandates and EU REACH chemical safety standards shape permissible additive portfolios and disclosure thresholds for cross-border condiment trade. China's SAMR enforces GB standard compliance for domestic fermentation-derived products, creating divergent compliance burdens for multinational portfolios. Stakeholders must monitor regulatory divergence between jurisdictions while building formulation flexibility into R&D pipelines.
Market Dynamics
Fermentation capacity concentration in China's coastal provinces is compressing cost structures while EFSA clean-label mandates force R&D pipeline redesigns across European portfolios.
Growth Catalysts
- Foodservice menu expansion:Asia-Pacific commercial kitchens are deploying compound condiments across fusion applications as flavor differentiation intensifies competitive positioning.
- REACH chemical disclosure thresholds:EU importers are reformulating additive portfolios to meet ECHA registration requirements, accelerating clean-label innovation cycles.
- Pouch packaging infrastructure:Cold-fill processing lines are capturing foodservice portion-control demand while reducing per-unit logistics expenditure versus glass alternatives.
Market Restraints
- Soybean input volatility:Fermentation feedstock costs fluctuate with Brazilian and Argentine harvest cycles, compressing margin predictability for soy-based sauce producers.
- Guangdong-Jiangsu supply concentration:Vertically controlled fermentation capacity creates geographic risk exposure for mass-market supply security.
- GB standard divergence:China's SAMR enforces domestic fermentation product compliance that fragments multinational formulation strategies.
Strategic Opportunities
- Southeast Asian underpenetration:Vietnam and Indonesia foodservice channels lack standardized compound condiment adoption, presenting first-mover positioning for fermentation-scale operators.
- Plant-based protein convergence:Fermentation expertise is transferring into alt-protein flavor masking applications, opening adjacent revenue streams for heritage brewers.
- EU Green Deal procurement incentives:Public sector foodservice tenders are prioritizing carbon-labeled condiment suppliers, rewarding early certification investment.
Industry Challenges
- Fermentation microbiologist scarcity:Heritage-scale brewing expertise concentrates among aging specialists, constraining talent pipelines for quality-consistency maintenance.
- Dual-compliance capex burden:Simultaneous FDA nutrition label redesign and EFSA additive approval timelines demand parallel laboratory infrastructure investment.
- Legacy cold-fill retooling:Glass-to-pouch format migration requires sterilization system replacement, straining mid-scale operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Condiments Market |
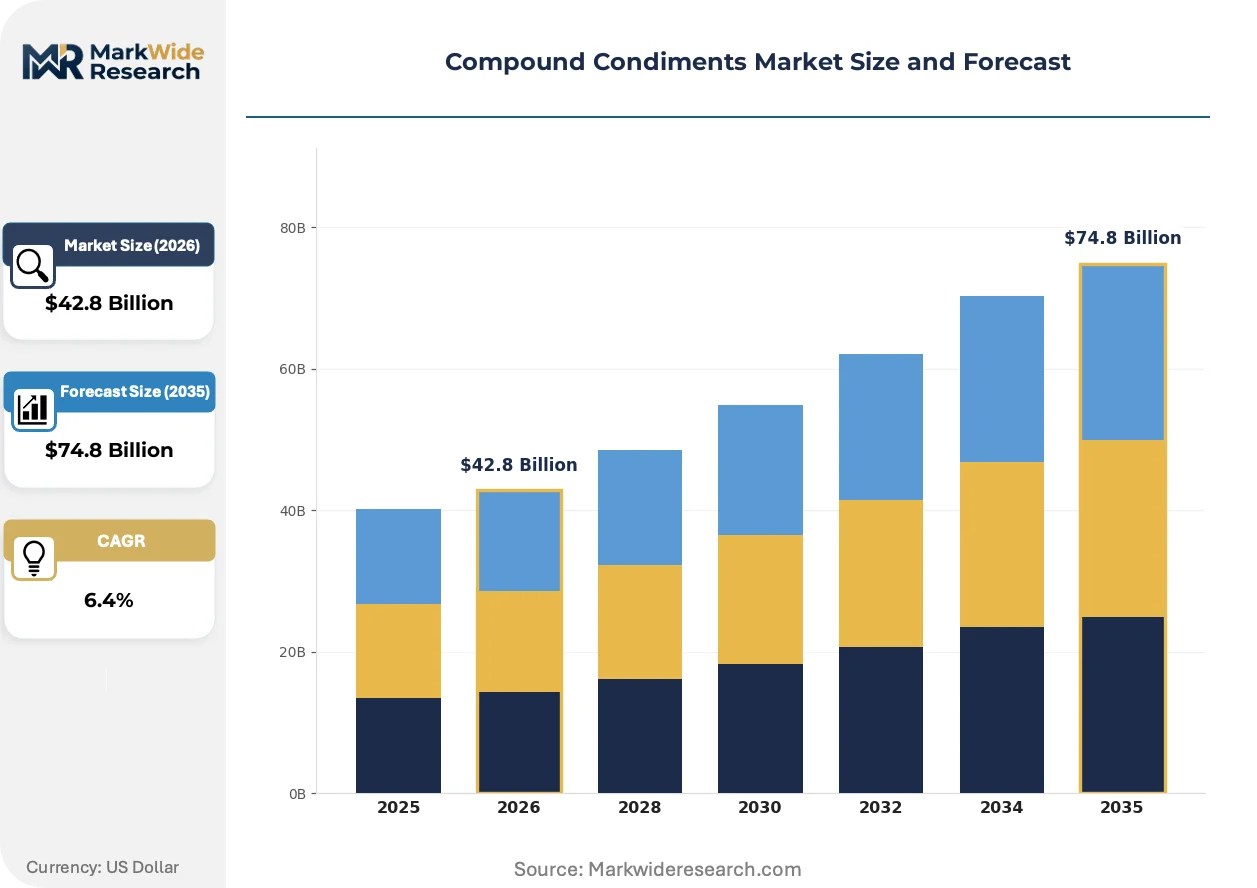
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketchup, Mustard, Mayonnaise, Barbecue Sauce Flavor Profile: Sweet, Savory, Spicy, Tangy Packaging Type: Glass Jar, Plastic Bottle, Pouch, Tube Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice |
| Companies Covered | Lee Kum Kee, Kikkoman Corporation, Kraft Heinz, Yihai International, McCormick & Company, Unilever, Nestlé, Haitian Group, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Condiments Market Trends and Innovations
Precision fermentation controls and bioactive stabilization technologies are compressing product development cycles while regulatory disclosure mandates reshape permissible ingredient palettes.
Controlled-environment fermentation systems is supplanting open-vat traditional brewing in premium sauce production. North American specialty retailers are adopting these systems to achieve batch-to-batch pH consistency within 0.1 variance. The technology is supplanting heritage-scale quality arbitrage by enabling industrial operators to replicate artisan flavor profiles at volume.
EFSA's evolving clean-label framework is tightening permissible stabilizer and preservative categories for cross-border condiment trade. Manufacturers are reformulating around natural acidification and high-pressure processing to maintain shelf-life parameters. European retail private-label suppliers are accelerating ingredient simplification to preempt disclosure threshold reductions.
Direct-procurement platforms are fragmenting traditional distributor relationships in North American foodservice channels. Restaurant groups are sourcing compound condiments through vertical supply agreements that bypass broadline distributors. This pattern is most visible in fast-casual chains with centralized menu development functions.
Compound Condiments Market Segmentation
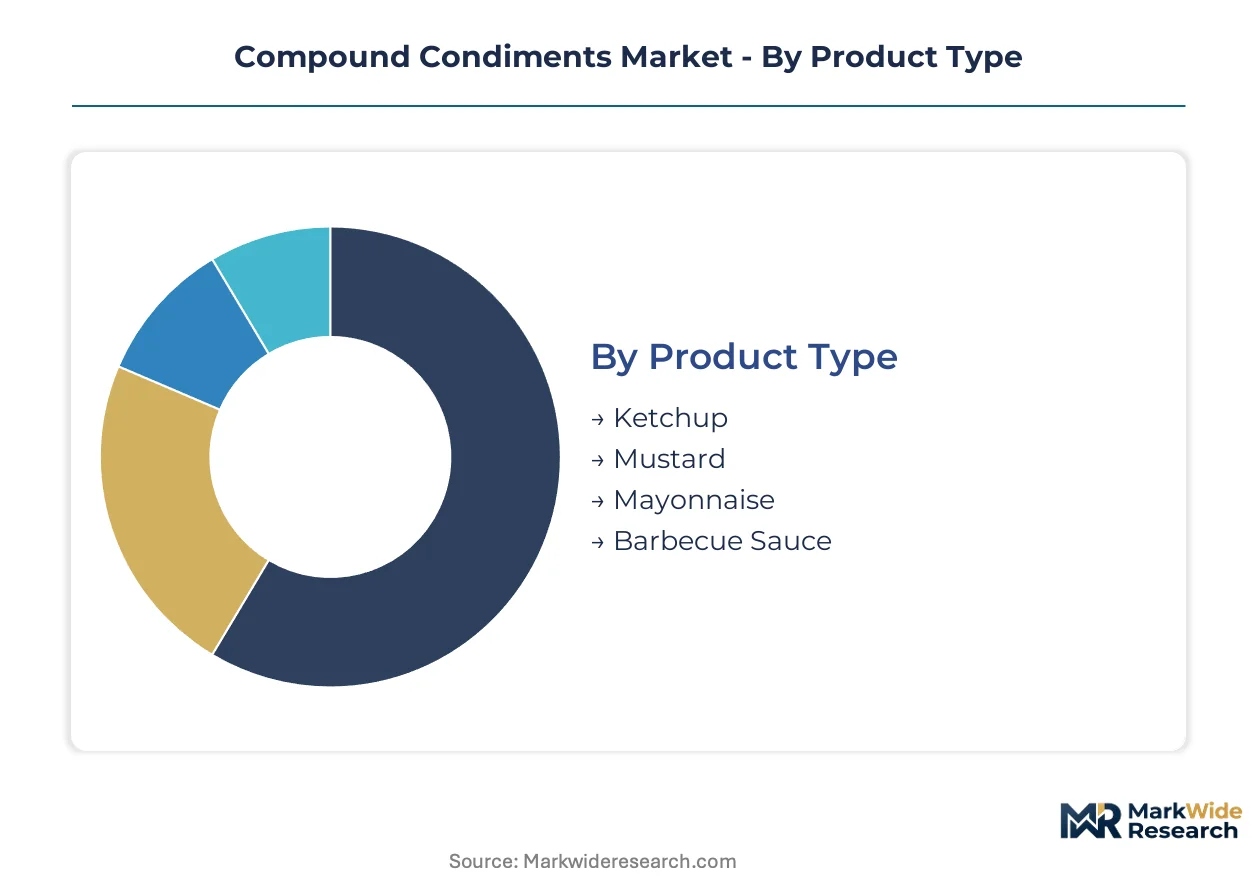
Compound condiments require granular segmentation to capture divergent demand patterns across fermentation-derived heritage products and industrial formulations. Each dimension reveals distinct margin structures, regulatory exposure, and channel dependencies that reshape competitive positioning.
Product Type:
Domestic consumption anchors ketchup and mayonnaise volumes in North American and European households, while barbecue sauce and mustard variants drive disproportionate export-led growth into Asian foodservice channels.
- Ketchup:Tomato-based formulations with standardized Brix measurements and pH stabilization dominate retail shelf space. Demand concentrates in US family households and quick-service restaurant chains, constrained by high-fructose corn syrup reformulation costs under FDA added-sugar disclosure mandates.
- Barbecue Sauce:Molasses-vinegar-tomato blends with regional smoke profiles vary by specification. Export demand from South Korean and Australian foodservice operators is accelerating as American-style grilling concepts expand, though EFSA caramel coloring restrictions fragment European formulation strategies.
- Mustard:Seed-based emulsions ranging from yellow ballpark styles to Dijon wine-infused variants serve niche applications.
- Mayonnaise:Egg-yolk stabilized oil-in-water emulsions with defined viscosity parameters anchor sandwich preparation across commercial kitchens.
Ketchup commands the established base. The steepest expansion runs through barbecue sauce.
Flavor Profile:
Cost tier stratification separates commodity formulations from premium positioning, with savory and spicy variants capturing margin premiums through ingredient intensity and fermentation complexity.
- Savory:Umami-forward formulations leveraging fermented soybean, fish sauce, or hydrolyzed yeast extracts deliver consistent flavor depth. Foodservice operators in Japan and Vietnam are standardizing these profiles across ramen and pho applications, though EFSA clean-label mandates are forcing preservative system redesigns.
- Spicy:Capsaicin-derived heat levels measured in Scoville-equivalent units enable precise menu calibration. North American fast-casual chains are deploying these variants for differentiation, with ghost pepper and gochujang-inspired formulations gaining share fastest in urban coastal markets.
- Sweet:Sugar or alternative sweetener bases with balanced acid profiles serve children's palates and baking applications.
- Tangy:Vinegar-dominant formulations with pronounced acidity support salad dressing and marinade applications.
Savory profiles command the established base. The steepest expansion runs through spicy variants.
Packaging Type:
Volume throughput and logistics economics favor plastic bottles for retail scale, while pouch and tube formats capture foodservice portion-control and travel-retail convenience segments.
- Pouch:Multi-layer laminate structures with oxygen barrier properties enable cold-fill processing at reduced per-unit shipping weight. Asia-Pacific foodservice distributors are adopting these formats for single-serve condiment dispensing, though retooling costs strain mid-scale operator capital allocation.
- Glass Jar:Inert barrier properties and premium shelf presence sustain heritage brand positioning. European retail channels maintain glass preference for organic and craft-positioned lines, constrained by weight-based logistics penalties and breakage rates.
- Plastic Bottle:PET and HDPE formats with squeeze-dispense closures dominate mass-market retail throughput.
- Tube:Aluminum-laminate collapsible formats serve travel retail and outdoor recreation channels with portion precision.
Glass jar commands the established base. The steepest expansion runs through pouch.
Distribution Channel:
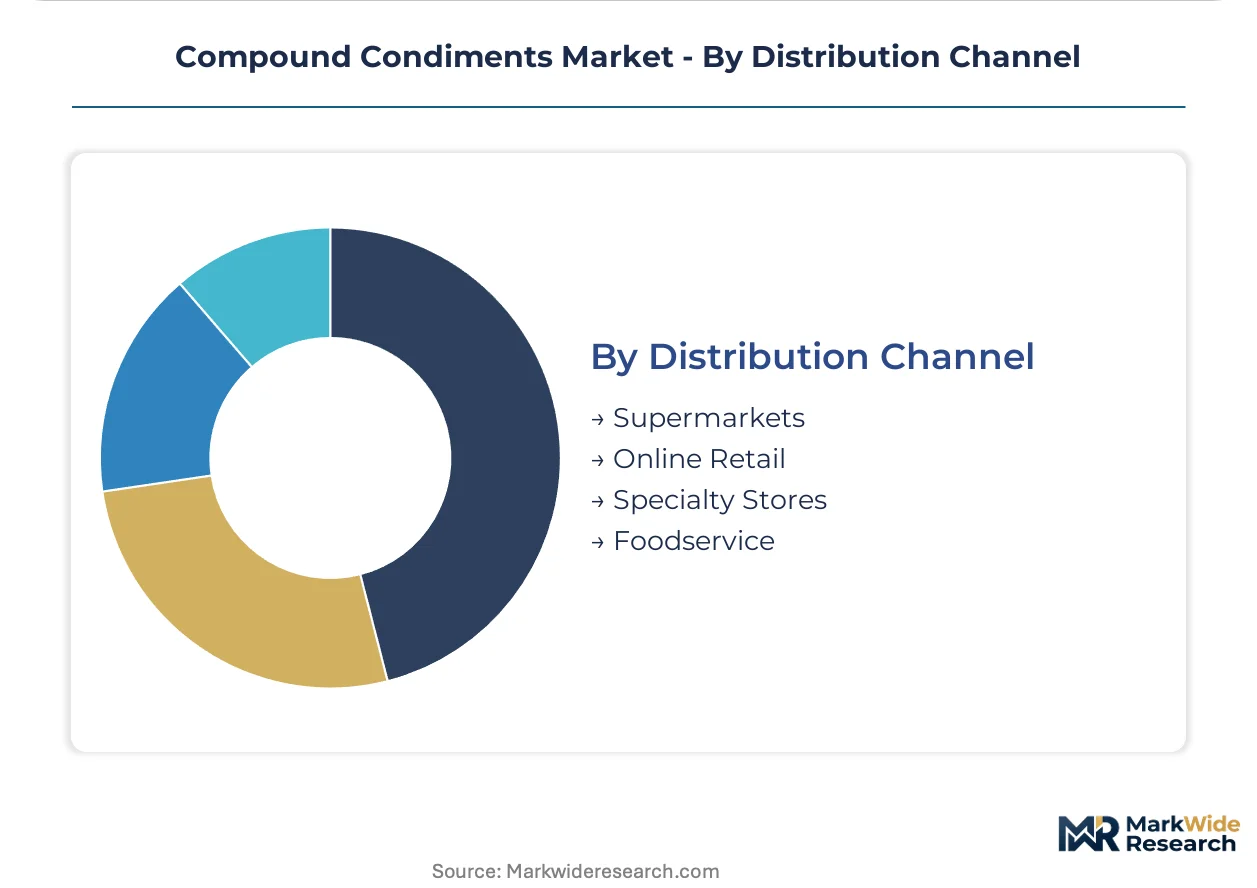
Customer type fragmentation separates centralized procurement by chain operators from fragmented household purchasing, with channel mix determining formulation specifications and margin capture.
- Foodservice:Gallon-format institutional packaging with pump-dispense compatibility and HACCP-aligned lot traceability serves commercial kitchen operations. Contract manufacturing relationships with US-based broadline distributors are consolidating supplier bases, though direct-procurement platforms are fragmenting traditional distributor lock-in.
- Online Retail:Direct-to-consumer subscription models and marketplace fulfillment enable niche flavor discovery. South Korean and Chinese e-commerce platforms are accelerating cross-border specialty sauce access, constrained by customs clearance complexity for fermentation-derived products.
- Supermarkets:Slotting fee structures and planogram positioning determine mass-market brand visibility.
- Specialty Stores:Curated assortments with origin storytelling and small-batch credentials serve enthusiast segments.
Supermarkets command the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes compound condiments as everyday cooking staples through retail channels, while the United States deploys them primarily as foodservice flavor accelerators for fast-casual menu differentiation. This consumption-mix differential shapes divergent product specifications and margin structures across geographies.
China
Guangdong and Jiangsu provinces anchor domestic fermentation capacity, supplying standardized soy-based sauces to mass-market retail. SAMR enforces GB standards for domestic fermentation products, creating compliance complexity for multinational portfolios. Foshan and Nantong manufacturing clusters concentrate vertically controlled brewing infrastructure.
United States
Fast-casual chains drive pouch-format adoption for portion-controlled condiment dispensing in commercial kitchens. FDA nutrition labeling mandates force reformulation around added-sugar disclosure thresholds. Chicago and California foodservice distributors are consolidating supplier bases through direct-procurement platforms.
Japan
Ramen and pho applications standardize savory umami profiles across foodservice channels. METI guidelines influence fermentation process documentation for export certification. Kanto and Kansai industrial corridors maintain heritage-scale brewing expertise alongside precision fermentation adoption.
Germany
European retail channels sustain glass-jar preference for organic-positioned condiment lines. EFSA clean-label mandates restrict stabilizer categories, accelerating natural acidification R&D. Bavaria and North Rhine-Westphalia host reformulation laboratories serving cross-border private-label suppliers.
South Korea
Gochujang-inspired formulations gain share in urban coastal markets as American-style grilling concepts expand. MFDS enforces additive disclosure thresholds for imported fermentation-derived products. Seoul Capital Area foodservice operators are deploying compound condiments across fusion menu applications.
Compound Condiments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation-scale operators commanding cost advantages and heritage brewers retaining premium positioning. The vendor base separates into three strategic archetypes: vertically integrated mass-market suppliers, century-old fermentation masters, and North American retail-scale processors. Capacity expansion and clean-label reformulation constitute the dominant competitive moves reshaping portfolio composition.
Within the heritage fermentation tier, Lee Kum Kee and Kikkoman Corporation exemplify century-old brewing mastery sustaining premium positioning. Kraft Heinz occupies a position representing North American retail-scale manufacturing and cold-fill processing infrastructure. Haitian Group anchors the vertically integrated mass-market archetype with controlled fermentation capacity spanning coastal Chinese provinces.
| Leading Market Players |
|---|
| Lee Kum Kee |
| Kikkoman Corporation |
| Kraft Heinz |
| Yihai International |
| McCormick & Company |
| Unilever |
| Nestlé |
| Haitian Group |
| Conagra Brands |
| Others |
Pricing and Supply Chain Analysis
Fermentation capacity utilization rates above 85% in Guangdong and Jiangsu provinces compress unit economics for mass-market soy-based sauces while simultaneously elevating price floors for heritage-positioned variants. Scale operators leverage backward integration into soybean crushing and brewing infrastructure to defend margin structures against Brazilian harvest volatility.
Pricing Analysis
Long-term offtake contracts between broadline foodservice distributors and compound condiment manufacturers dominate procurement patterns, locking in volume commitments across 12-24 month horizons. Three-tier pricing structure across premium, standard, and economy levels separates heritage-fermented positioning from industrial formulations and private-label alternatives. Cost compression in the standard tier intensifies due to pouch-format retooling capex requirements and EFSA clean-label reformulation expenses. Quick-service restaurant chains exhibit highest price sensitivity through centralized procurement functions, while specialty retailers in Germany and Japan absorb premium markups for glass-jar heritage lines.
Supply Chain Analysis
Port congestion at Shanghai-Ningbo and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European importers of fermentation-derived products. Manufacturing gravity centers on China, South Korea, and Japan, with China commanding upstream fermentation infrastructure and South Korea specializing in gochujang-inspired flavor innovation. Raw material dependencies rest on Brazilian and Argentine soybean harvests, Chinese wheat bran for koji cultivation, and Vietnamese chili for heat-profile standardization. Single-source vulnerability concentrates in Guangdong-Jiangsu fermentation clusters. Distribution runs through broadline foodservice distributors in North America, direct-procurement platforms fragmenting traditional relationships, and e-commerce marketplaces in South Korea and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-procurement platform economics are displacing traditional distributor gatekeepers, creating interoperability requirements between manufacturer ERP systems and restaurant group procurement portals.
For Market Incumbents: Shield fermentation expertise advantages through captive microbiologist training pipelines and precision fermentation technology adoption. Consolidate supplier relationships with Brazilian soybean crushers to offset harvest-cycle price volatility. Defend against pouch-format specialists by accelerating cold-fill infrastructure deployment in North American foodservice corridors. For New Entrants and Emerging Players: Southeast Asian foodservice standardization gaps present white-space opportunities in Vietnam and Indonesia where compound condiment adoption remains fragmented. Target Indonesian quick-service chains with halal-certified savory formulations as the most penetrable entry vector. Deploy direct-procurement platform integration as the primary go-to-market mechanism, bypassing entrenched broadline distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation equipment suppliers and clean-label formulation laboratories over legacy open-vat operators. Long-term viability concentrates in assets capable of dual FDA-EFSA compliance without parallel laboratory infrastructure duplication. Acquisition target archetype: regional fermentation-scale operators with underutilized capacity and existing GB standard certification. Monitor EFSA disclosure threshold reduction announcements as the critical inflection signal for reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | EFSA additive restrictions force preservative system redesigns across European export portfolios. |
| Pouch Packaging Infrastructure Expansion | Cold-fill sterilization lines capture foodservice portion-control demand while reducing logistics expenditure. |
| Fermentation Microbiologist Talent Pipeline | Heritage-scale brewing expertise concentrates among aging specialists, constraining quality-consistency maintenance. |
| Direct-Procurement Platform Integration | Restaurant group ERP interoperability requirements fragment traditional broadline distributor lock-in. |
| Southeast Asian Market Development | Vietnam and Indonesia foodservice channels lack standardized compound condiment adoption. |
Research Methodology
Cross-validation between fermentation technology suppliers and foodservice procurement executives anchors the qualitative findings on equipment adoption timelines and menu application expansion. Primary interviews with flavor chemists, fermentation specialists, broadline distributor category managers, and quick-service restaurant supply chain directors combined with secondary validation from FDA labeling guidance documents, EFSA scientific opinions, SAMR GB standard publications, and customs trade flow databases. Bottom-up volume modeling triangulates against top-down category expenditure estimates.
Sensitivity analysis around soybean price volatility and regulatory disclosure threshold timing shapes the forecast confidence intervals across the projection horizon. Segmentation dimensions modeled include product type, flavor profile, packaging format, distribution channel, and fermentation methodology heritage versus precision. CAGRs derive from historical trajectory analysis adjusted for structural shifts in foodservice procurement patterns and clean-label mandate implementation pacing. Forecast inputs incorporate fermentation capacity expansion announcements and pouch-format adoption curves in Asia-Pacific commercial kitchens.
Material uncertainties — Brazilian harvest failure scenarios, EFSA additive category reclassifications, and China-Taiwan logistics disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and foodservice recovery trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Hoisin Sauce Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market