
 Hot Sauce Powder Market | 2026-2036
Hot Sauce Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Sauce Powder Market Foresight
Capsaicin extraction expertise is reorganizing competitive dynamics as specialty chemical knowledge migrates from pharmaceutical into food-grade applications. McCormick & Company leverages century-old spice procurement networks to secure heirloom pepper cultivars. Kerry Group anchors its position through backward integration into spray-drying facilities across multiple climate zones. Symrise competes by dominating encapsulation technology that preserves volatile heat compounds during thermal processing.
Hot sauce powder consists of dehydrated chili pepper mash or extract reduced to free-flowing particulate through spray-drying or drum-drying, typically standardized to Scoville heat units between 500 and 500,000 SHU for industrial consistency. The product delivers concentrated pungency, extended shelf stability, and precise dosing control for processed food applications where liquid sauces introduce moisture conflicts. Habanero powder commands premium positioning among food manufacturers seeking extreme-heat claims with minimal inclusion rates. Sachet packaging for single-serve restaurant and foodservice channels represents the fastest-growing configuration, driven by portion-control economics and reduced waste metrics. Bulk bags for industrial food manufacturers remain the mature volume base, though margin pools have compressed amid commodity chili powder competition.
FDA food additive regulations and USDA organic certification requirements shape formulation choices and label claims for products distributed in the United States. EFSA novel food assessments and EU pesticide residue limits govern import eligibility for non-European chili sources entering European food manufacturing supply chains. Stakeholders must monitor evolving capsicum extract purity standards and dual-use pharmaceutical classifications that could restrict concentrated oleoresin trade flows.
Market Dynamics
Capsaicin standardization requirements are fragmenting procurement relationships as food manufacturers demand batch-certified heat units that commodity chili suppliers cannot reliably deliver.
Growth Catalysts
- Clean-label mandates:FDA and USDA organic disclosure rules compel reformulation of powdered condiments toward single-ingredient chili sources without anti-caking agents or synthetic carriers.
- Spray-drying infrastructure:Multi-zone climate facilities enable year-round production independent of harvest seasonality, stabilizing supply contracts for processed food manufacturers.
- Mexico:Jalisco and Oaxaca processing clusters leverage heirloom cultivar knowledge to secure premium sourcing agreements with North American snack food producers.
Market Restraints
- Input cost volatility:Fresh habanero and chipotle pepper prices swing with drought cycles in Veracruz and Chihuahua, compressing margin predictability for powder processors.
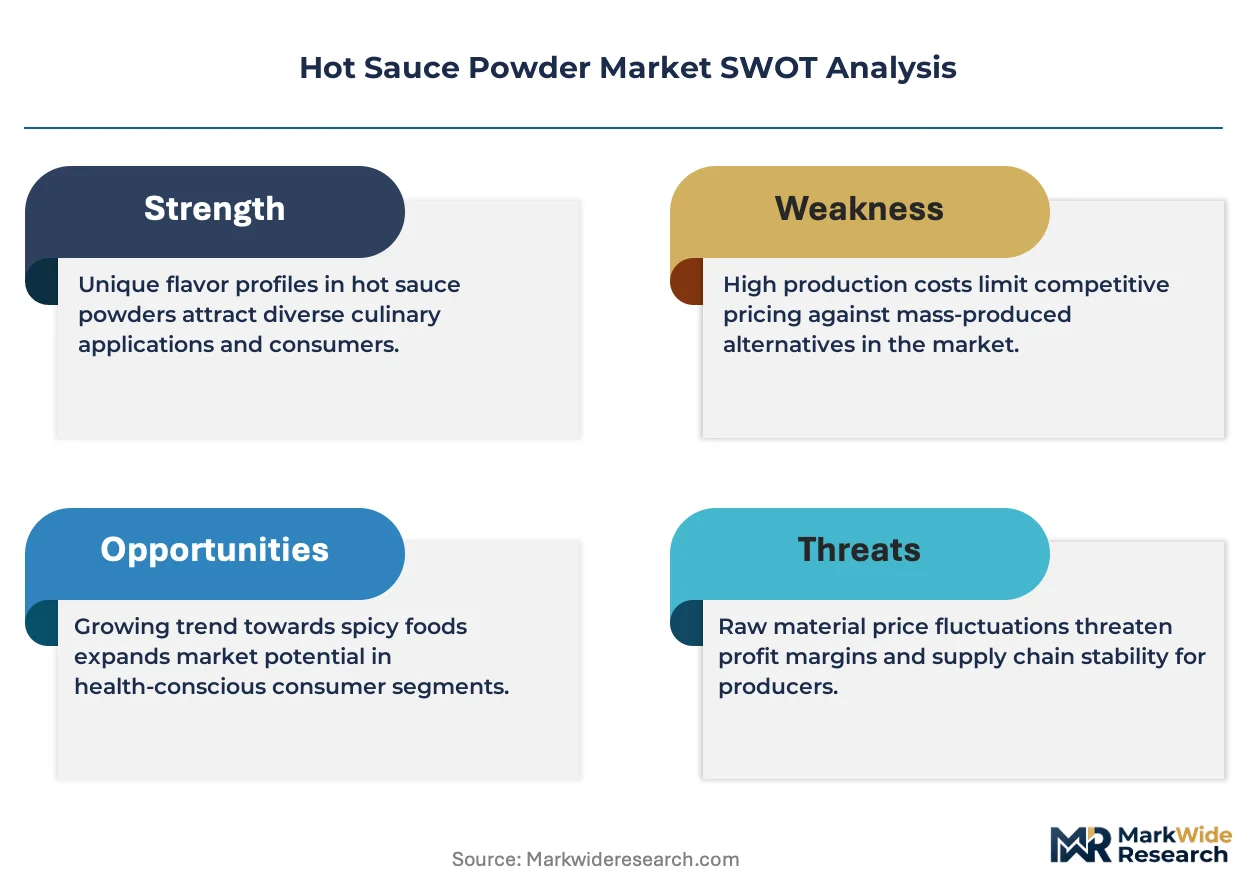
- Supply concentration risk:Over half of food-grade oleoresin extraction capacity sits with three specialty chemical groups, creating single-source vulnerability for extreme-heat formulations.
- Substitution threat:Liquid hot sauce concentrates with modified starch carriers capture cost-sensitive applications where moisture tolerance permits.
Strategic Opportunities
- Southeast Asia:Thailand and Vietnam street-food manufacturing presents underpenetrated demand for sachet-format heat powders in instant noodle and snack seasoning.
- Encapsulation-convergence:Pharmaceutical-grade liposome technology migrating into food applications enables heat-stable microencapsulation for bakery and confectionery.
- EU Green Deal:Farm-to-Fork pesticide reduction targets favor residue-tested Mexican and Southwest US chili sources over conventional Asian supply.
Industry Challenges
- Scoville calibration expertise:Analytical chemists capable of HPLC-based capsaicinoid quantification command premium wages, constraining quality control scaling.
- Organic certification timelines:USDA and EU organic transitions require 36-month field histories, delaying premium positioning for newly converted pepper acreage.
- Legacy equipment incompatibility:Drum-dried powder specifications conflict with modern pneumatic conveying systems, forcing capital reinvestment or contract manufacturing reliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Sauce Powder Market |
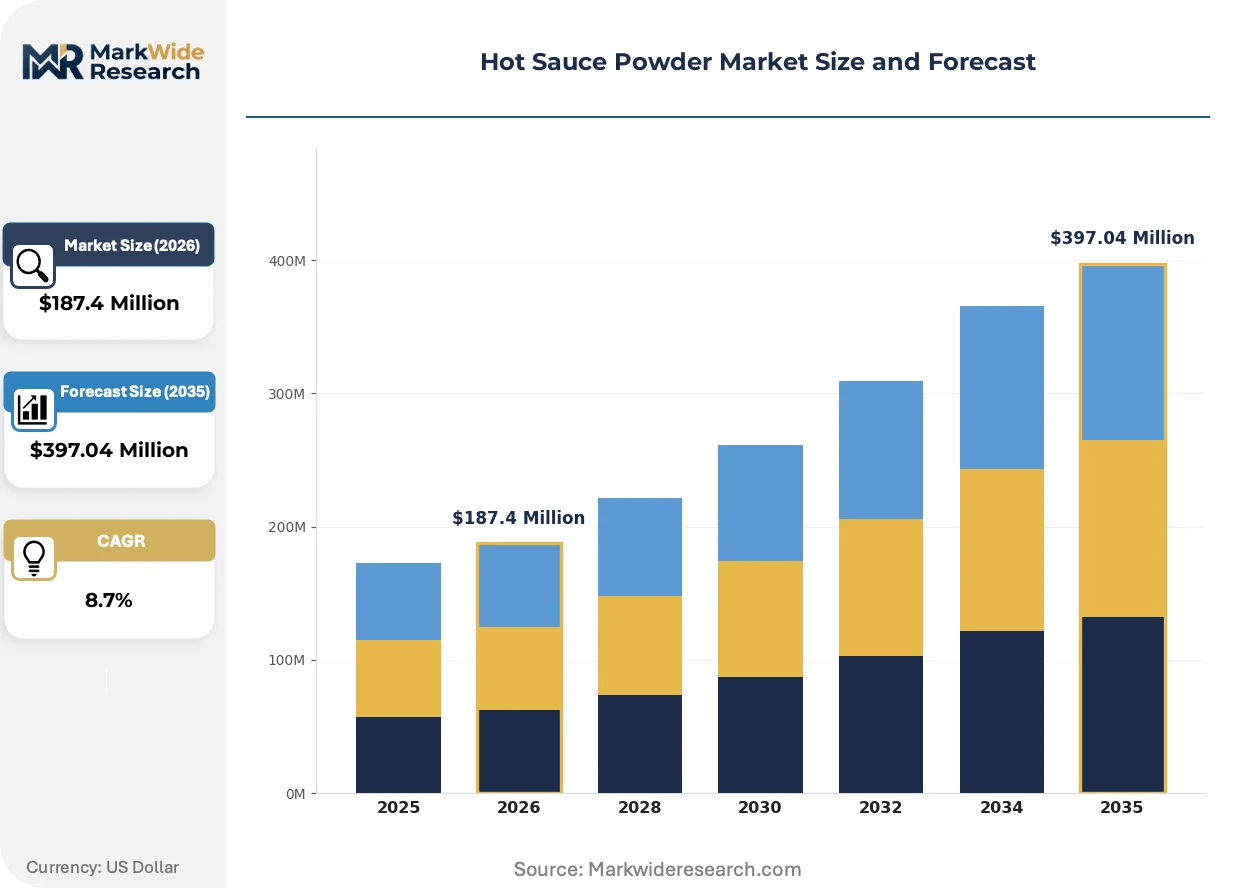
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chili Powder, Habanero Powder, Chipotle Powder, Cayenne Powder End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Packaging Type: Bulk Bags, Sachets, Jars, Pouches Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Cargill, Archer Daniels Midland, Ingredion, Tate & Lyle, Roquette Frères, McCormick & Company, Symrise, Givaudan, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Sauce Powder Market Shifts & Advancements
Precision heat delivery systems are redefining formulation economics as manufacturers seek dosage accuracy without liquid sauce moisture penalties.
Microencapsulation via fluidized-bed coating is decomposing the traditional trade-off between heat intensity and thermal stability. Bakery and extruded snack producers in Germany and the Netherlands adopt coated capsaicin granules at accelerating rates. This technology is decomposing commodity powder margins by enabling proprietary heat-delivery platforms that command formulation exclusivity.
EFSA novel food assessments now require full toxicological dossiers for concentrated oleoresin imports exceeding 8% capsaicin content. European compounders face 18-24 month approval windows for new non-EU chili sources. High-heat sauce powder categories targeting 100,000+ Scoville units see delayed market entry and inventory pre-positioning in bonded warehouses.
Single-serve sachet specifications are displacing bulk bag procurement in foodservice channels. Quick-service restaurant chains in Texas, Arizona, and California specify portion-control packets to reduce waste metrics and standardize customer experience. This pattern concentrates demand with contract packagers capable of high-speed form-fill-seal operations.
Hot Sauce Powder Market Segmentation
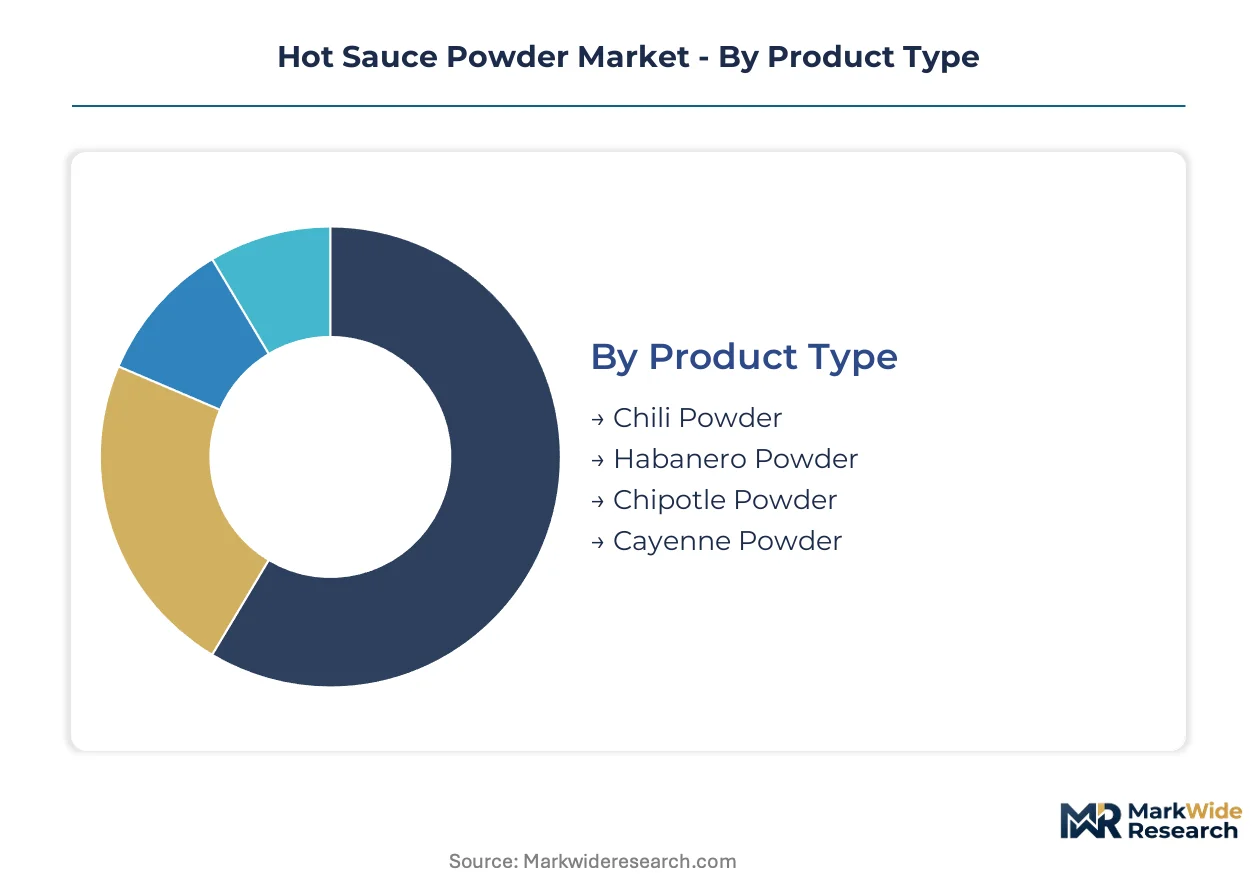
Segmentation in hot sauce powder markets reveals how substitution pressures and regulatory compliance reshape procurement priorities across product grades and packaging configurations. Powder processors must align production specifications with end-use moisture constraints, distribution economics, and clean-label mandates that vary sharply by customer type.
Product Type:
Substitution pressure from liquid sauce concentrates and oleoresin extracts intensifies competition for mid-heat commodity powders while ultra-hot specialty grades defend margin pools through technical differentiation.
- Habanero Powder:Standardized to 100,000–350,000 Scoville heat units through spray-dried oleoresin infusion. Snack food manufacturers in Mexico and the southwestern United States specify habanero for extreme-heat claims at inclusion rates below 0.5%, minimizing raw material costs per unit while maximizing label impact.
- Chipotle Powder:Smoke-dried jalapeño reduced to 2,500–8,000 SHU with characteristic mesquite flavor compounds preserved through controlled drum-drying. Barbecue sauce compounders and meat processors in Texas and Chihuahua procurement zones favor chipotle for flavor-forward applications where liquid smoke alternatives fail clean-label scrutiny.
- Chili Powder:Blended cayenne and paprika base delivering 500–5,000 SHU for cost-sensitive seasoning applications.
- Cayenne Powder:Single-origin red pepper standardized at 30,000–50,000 SHU for pharmaceutical and food-grade capsaicin extraction feedstock.
Habanero powder retains volume leadership among premium-positioned segments; chipotle powder holds the steepest expansion curve as smoke-flavored clean-label demand accelerates.
End User:
Cost tier stratification separates specification-intensive industrial buyers from price-sensitive household segments, with foodservice operators occupying an intermediate zone defined by portion-control economics.
- Food Manufacturers:Industrial compounders of extruded snacks, seasoning blends, and processed proteins requiring batch-certified Scoville consistency and year-round supply contracts. Spray-drying infrastructure investments by Kerry Group and captive oleoresin extraction capacity anchor procurement relationships with these buyers.
- Restaurants:Quick-service chains and independent operators specifying sachet-format single-serve packets to standardize heat delivery and reduce waste metrics. Texas, Arizona, and California chains drive specification tightening for portion-control economics.
- Retailers:Supermarket and specialty store buyers merchandising jarred and pouched formats to home cooks seeking recipe versatility.
- Home Cooks:Direct consumers purchasing through online retail and specialty channels, price-sensitive and brand-loyal within ethnic cooking segments.
Food manufacturers retain volume leadership; restaurants hold the steepest expansion curve as foodservice sachet adoption accelerates.
Packaging Type:
Supply concentration in high-speed form-fill-seal contract packaging creates bottlenecks for sachet and pouch formats while bulk bag capacity remains commoditized.
- Sachets:Single-serve aluminum-laminate or metallized film packets of 0.5–5 gram capacity, specified by quick-service restaurant chains for portion control and reduced waste. High-speed packaging line investments by contract packagers in Jalisco and Texas concentrate supply capability.
- Bulk Bags:10–25 kilogram multi-wall paper or woven polypropylene containers for industrial food manufacturing, the mature volume base facing margin compression from commodity chili powder competition.
- Jars:Glass or PET containers of 50–500 gram capacity for retail shelf presence and home cook recipe use.
- Pouches:Stand-up or flat flexible packaging for retail and foodservice intermediate volumes, gaining share in specialty and ethnic market channels.
Bulk bags retain volume leadership; sachets hold the steepest expansion curve as foodservice standardization demands intensify.
Distribution Channel:
Geography-driven channel preferences separate consolidated wholesale procurement in industrial zones from fragmented retail and online paths serving household and small commercial buyers.
- Wholesale:Direct and distributor-mediated bulk sales to food manufacturers and restaurant chains, concentrated in Mexico City, Houston, and Los Angeles supply hubs where procurement teams negotiate annual contracts with Scoville certification requirements.
- Online Retail:E-commerce platforms serving home cooks and small restaurants with specialty and ethnic varieties unavailable through conventional retail, expanding most quickly in Southeast Asian markets where street-food manufacturing digitizes procurement.
- Supermarkets:Mass-market retail chains merchandising jarred and pouched formats to household consumers in North American and European urban centers.
- Specialty Stores:Ethnic grocery and gourmet food retailers curating heirloom cultivar powders and extreme-heat specialty grades for enthusiast segments.
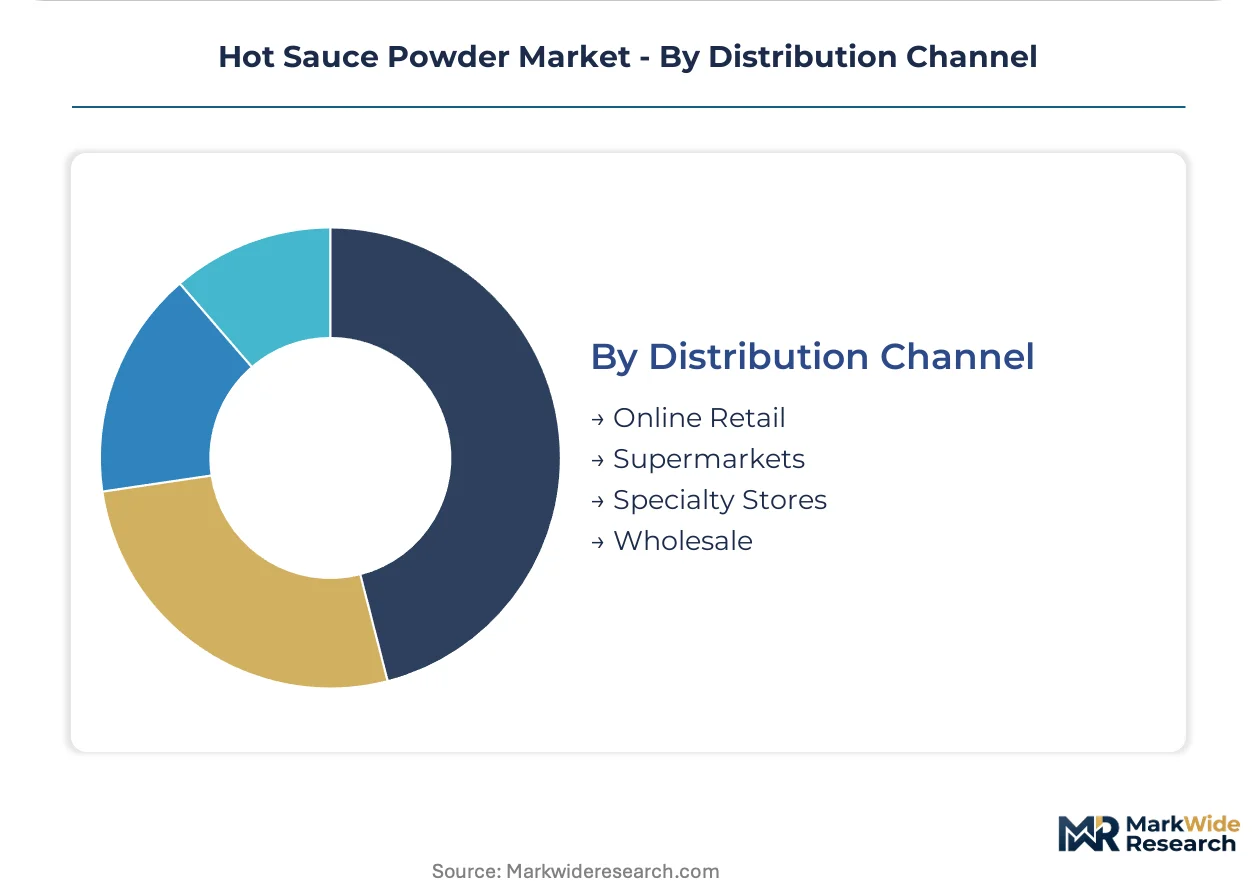
Wholesale retains volume leadership; online retail holds the steepest expansion curve as procurement digitization penetrates foodservice and small manufacturing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Food manufacturers in Mexico and the southwestern United States prioritize extreme-heat habanero powders for snack seasoning. European buyers emphasize residue-tested organic chipotle varieties for clean-label meat processing. Southeast Asian street-food producers favor low-cost cayenne bases for instant noodle applications.
United States
Snack food manufacturers in Texas and California drive procurement of spray-dried habanero powders standardized above 100,000 Scoville units. FDA food additive regulations and USDA organic certification requirements govern label claims for distributed products. Jalisco-Texas supply corridors concentrate sachet packaging capacity for quick-service restaurant chains seeking portion-control economics.
Mexico
Jalisco and Oaxaca processing clusters leverage heirloom cultivar knowledge to secure premium sourcing agreements with North American producers. Domestic regulations under COFEPRIS align with FDA disclosure standards for cross-border trade. Veracruz and Chihuahua pepper-growing regions face drought-driven price volatility that compresses margin predictability for powder processors.
Germany
Bakery and extruded snack producers in Bavaria and North Rhine-Westphalia adopt microencapsulated capsaicin granules for heat-stable formulations. EFSA novel food assessments and EU pesticide residue limits govern import eligibility for non-European chili sources. Cologne and Hamburg serve as compounding hubs where 18-24 month approval windows delay market entry for high-heat oleoresin categories.
Thailand
Street-food manufacturing and instant noodle seasoning operations present underpenetrated demand for sachet-format heat powders. National food safety standards under the Thai FDA regulate additive disclosure for processed food applications. Bangkok and surrounding industrial zones concentrate contract packaging capacity for ASEAN distribution networks.
Netherlands
Food manufacturers in Rotterdam and Eindhoven procurement zones specify residue-tested Mexican chili sources to meet EU Green Deal Farm-to-Fork pesticide reduction targets. EFSA governance applies equally here as in Germany, creating regulatory consistency across Benelux operations. Amsterdam distribution hubs manage bonded warehouse pre-positioning for high-heat categories awaiting novel food clearance.
Hot Sauce Powder Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding backward integration into spray-drying and oleoresin extraction. The middle layer fragments across regional pepper processors and private-label compounders lacking captive supply chains. Three archetypes dominate: diversified ingredient conglomerates with multi-zone climate facilities, flavor houses leveraging pharmaceutical-grade encapsulation migration, and heritage spice traders with century-old procurement networks. Competitive moves concentrate on geographic expansion into Southeast Asian sachet markets and technology licensing for microencapsulation platforms.
Within the diversified ingredient tier, Cargill and Archer Daniels Midland occupy positions anchored by global agricultural sourcing infrastructure. McCormick & Company exemplifies the heritage spice archetype through procurement network depth. Kerry Group represents integrated processing capability with multi-zone spray-drying assets. Symrise and Givaudan sit within the flavor-house segment where encapsulation technology specialization defines competitive differentiation.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Ingredion |
| Tate & Lyle |
| Roquette Frères |
| McCormick & Company |
| Symrise |
| Givaudan |
| Kerry Group |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Jalisco processing clusters and Texas snack food manufacturers lock in habanero powder supply access while stabilizing unit costs against Veracruz drought cycles. These contracts embed Scoville certification requirements and volume minimums that protect processors from spot market volatility while giving buyers price visibility across harvest seasons.
Pricing Analysis
Contract-based long-term offtake dominates procurement relationships for industrial food manufacturers seeking batch-certified heat units, with spot market activity confined to commodity chili powder grades. Price differentiation rests on Scoville certification tier and organic USDA accreditation, with premium habanero oleoresin powders commanding substantial spreads over standard cayenne bases. Cost compression in mid-heat commodity tiers is intensifying because drum-dried powder specifications face substitution from liquid concentrate alternatives. Retail home cooks exhibit highest price sensitivity, while quick-service restaurant chains prioritize portion-control standardization over per-unit cost.
Supply Chain Analysis
Port congestion at Veracruz and container availability constraints on the Asia-Pacific trade lane elevate inbound logistics costs for Southeast Asian cayenne sources competing in European markets. Geographic supply concentrates in Mexico, the southwestern United States, and Vietnam, with heirloom cultivar knowledge in Jalisco and Oaxaca anchoring premium positioning. Raw material dependencies center on fresh habanero and chipotle pepper harvests, food-grade oleoresin extraction capacity, and spray-drying infrastructure. Single-source vulnerability pervades extreme-heat formulations where three specialty chemical groups control over half of food-grade extraction capacity. Distribution runs through wholesale procurement hubs in Mexico City, Houston, and Los Angeles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA and EFSA certification requirements creates substantial switching costs for established supplier relationships.
For Market Incumbents: Shield margin pools by deepening backward integration into captive oleoresin extraction capacity and securing multi-zone spray-drying assets across climate-diverse geographies. Liquid hot sauce concentrate substitutes with modified starch carriers threaten cost-sensitive applications; incumbents should accelerate encapsulation technology licensing to defend formulation exclusivity in bakery and confectionery segments. For New Entrants and Emerging Players: USDA organic certification fast-track programs offer entry pathways into premium positioning despite 36-month field history requirements. Southeast Asian sachet markets for instant noodle and street-food manufacturing present the most penetrable white-space opportunity. New entrants should pursue contract packaging partnerships with Jalisco and Texas form-fill-seal operators rather than greenfield capacity investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated processors with captive supply chains and established regulatory dossiers. Long-term viability across a 5-10 year window rests on acquiring heritage procurement networks and multi-zone climate facilities rather than commodity chili powder assets. Investors should monitor EFSA novel food approval timelines for high-heat oleoresin categories as the critical inflection signal for premium segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleoresin Extraction | Captive supply of food-grade capsaicin isolates processors from specialty chemical group concentration risk. |
| Multi-Zone Spray-Drying Capacity Expansion | Year-round production independent of harvest seasonality stabilizes supply contracts with industrial food manufacturers. |
| Microencapsulation Technology Licensing | Pharmaceutical-grade liposome migration enables heat-stable formulations for German and Dutch bakery producers. |
| Sachet Format Manufacturing Scale-Up | High-speed form-fill-seal operations capture quick-service restaurant chain specification tightening in Texas and California. |
| USDA Organic Certification Investment | Clean-label positioning aligns with FDA disclosure rule tightening and EU Green Deal pesticide reduction targets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with spray-drying facility operators, procurement leads at snack food manufacturers, regulatory affairs specialists, and contract packaging executives; and secondary validation through FDA food additive filings, USDA organic certification databases, EFSA novel food assessment records, and customs trade data for chili powder imports. Bottom-up triangulation across processor capacity disclosures and top-down reconciliation against food manufacturer demand surveys anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product heat intensity tier, end-user procurement specification level, packaging format configuration, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical procurement patterns and substitution elasticity estimates between powder and liquid concentrate formats. Forecast inputs incorporated spray-drying capacity utilization rates and EFSA approval pipeline status for concentrated oleoresin categories.
Decision-makers should treat outputs as directional under assumptions of stable FDA disclosure requirements and continued EU pesticide residue limit stringency; material deviation in regulatory timelines or drought severity in Veracruz and Chihuahua would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
Curry Cube Market