
 Safety Helmets Market | 2026-2036
Safety Helmets Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Helmets Market Intelligence
A shift from single-source supplier contracts toward multi-sourcing strategies is rebalancing procurement for large industrial buyers. This trend allows enterprises greater flexibility and supply chain resilience. MSA Safety Inc. leverages its strong brand recognition in fire service and industrial sectors. Meanwhile, Honeywell International Inc. competes with a broad portfolio of personal protective equipment, while 3M Company differentiates through material science innovation.
Safety helmets are a form of personal protective equipment designed to shield the wearer's head from impact, falling objects, and electrical hazards. These devices are typically constructed with a hard outer shell, often made from high-density polyethylene, and an internal suspension system that absorbs shock. Helmets made from materials like polycarbonate and carbon fiber command premium pricing due to superior impact resistance. The construction application continues to represent the largest volume segment, driven by non-discretionary safety mandates.
Compliance with standards such as ANSI/ISEA Z89.1 in the United States, EN 397 under Europe's CE marking framework, and China's GB 2811 standards is non-negotiable for market access. These regulations dictate minimum performance criteria, directly influencing product design and material selection. The key decision for manufacturers now centers on integrating smart technologies, like impact sensors, without compromising core safety certifications or affordability.
Market Dynamics
The safety helmets market is defined by the non-negotiable demand from regulated industries, balanced against the technical and cost challenges of material innovation. This dynamic forces manufacturers to innovate within strict performance and cost envelopes dictated by standards like ANSI/ISEA Z89.1 and EN 397.
Growth Catalysts
- Regulatory Mandates:Stricter enforcement of occupational safety rules, including those from the US Occupational Safety and Health Administration (OSHA), compels employers in construction and manufacturing to ensure worker compliance, sustaining baseline demand.
- Infrastructure Expansion:Large-scale public works and infrastructure projects in developing economies, particularly in India's transport and energy sectors, create concentrated pockets of new demand for industrial-grade head protection.
- Advanced Materials:The adoption of premium materials like carbon fiber and polycarbonate, while increasing cost, allows for superior impact resistance and lighter weight, creating a distinct high-performance tier for specialized applications.
Market Restraints
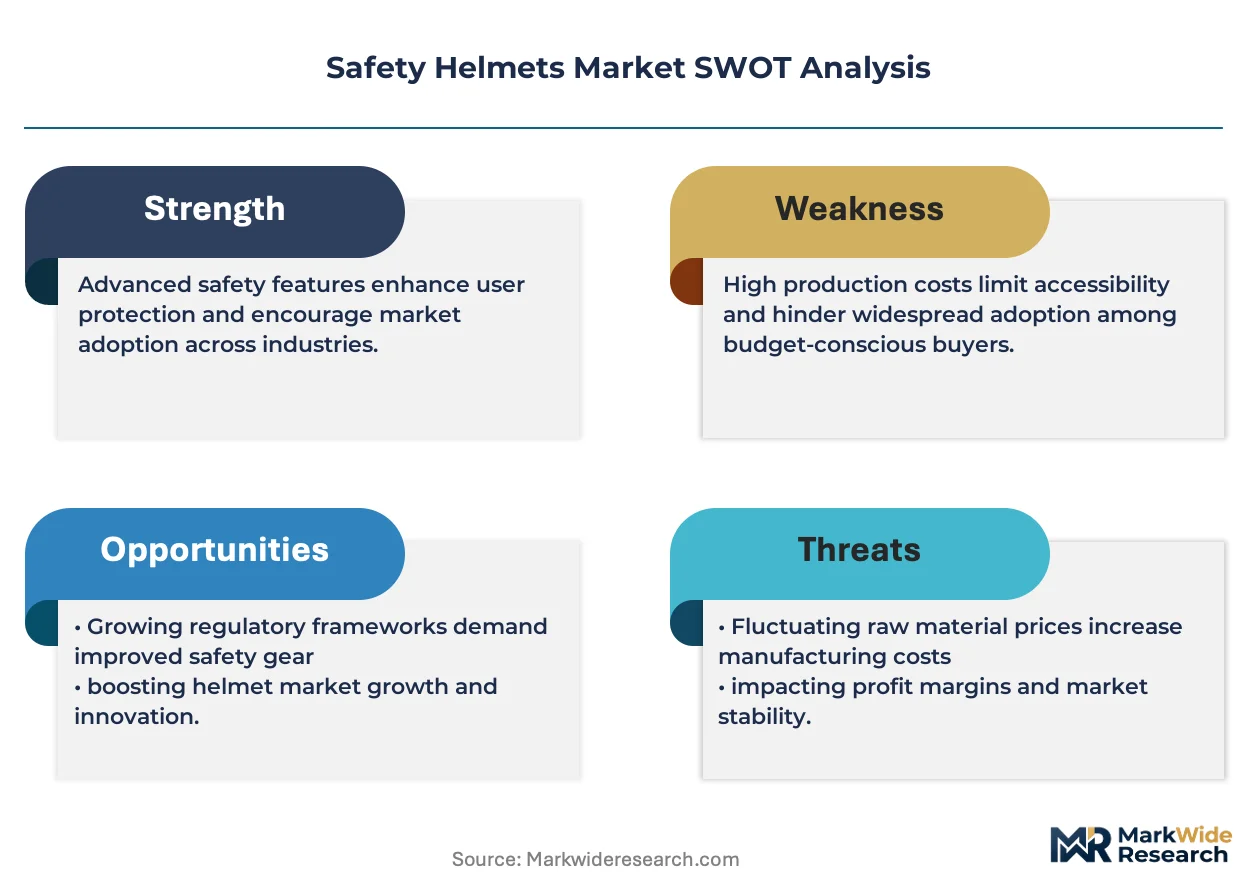
- Input Cost Volatility:Fluctuations in the price of raw materials, especially petroleum-derived polymers like high-density polyethylene (HDPE), create margin pressure for manufacturers of standard, high-volume helmets.
- Counterfeit Products:The proliferation of low-cost, non-compliant, and counterfeit helmets in less-regulated markets poses a significant threat, undermining legitimate sales and posing serious safety risks to end-users.
- Design Trade-offs:Integrating smart technologies such as sensors or communication hardware often involves a trade-off against weight, comfort, and battery life, complicating design without compromising core safety certifications.
Strategic Opportunities
- Underpenetrated Geographies:The ongoing industrialization and formalization of labor laws in Latin American countries, such as Brazil's manufacturing sector, present significant expansion opportunities for certified safety equipment.
- Specialized Applications:Development of helmets for niche, high-risk environments, like those offering enhanced electrical insulation for workers in electric vehicle battery plants, opens new value-added segments.
- IoT Integration:Incorporating IoT-enabled sensors for real-time impact detection, location tracking, and environmental monitoring allows helmet manufacturers to transition from selling products to providing comprehensive safety solutions.
Industry Challenges
- Complex Compliance Landscape:Manufacturers face significant administrative and testing burdens to secure and maintain certifications across multiple international standards, such as ANSI, EN, and GB standards, slowing market entry.
- Supply Chain Management:Executing a multi-sourcing strategy to enhance resilience introduces complexity in quality control, logistics coordination, and supplier qualification, challenging procurement teams.
- Product Lifecycle Management:The limited and often ambiguous guidelines on helmet service life and replacement schedules create uncertainty for both employers and workers, leading to inconsistent replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Helmets Market |
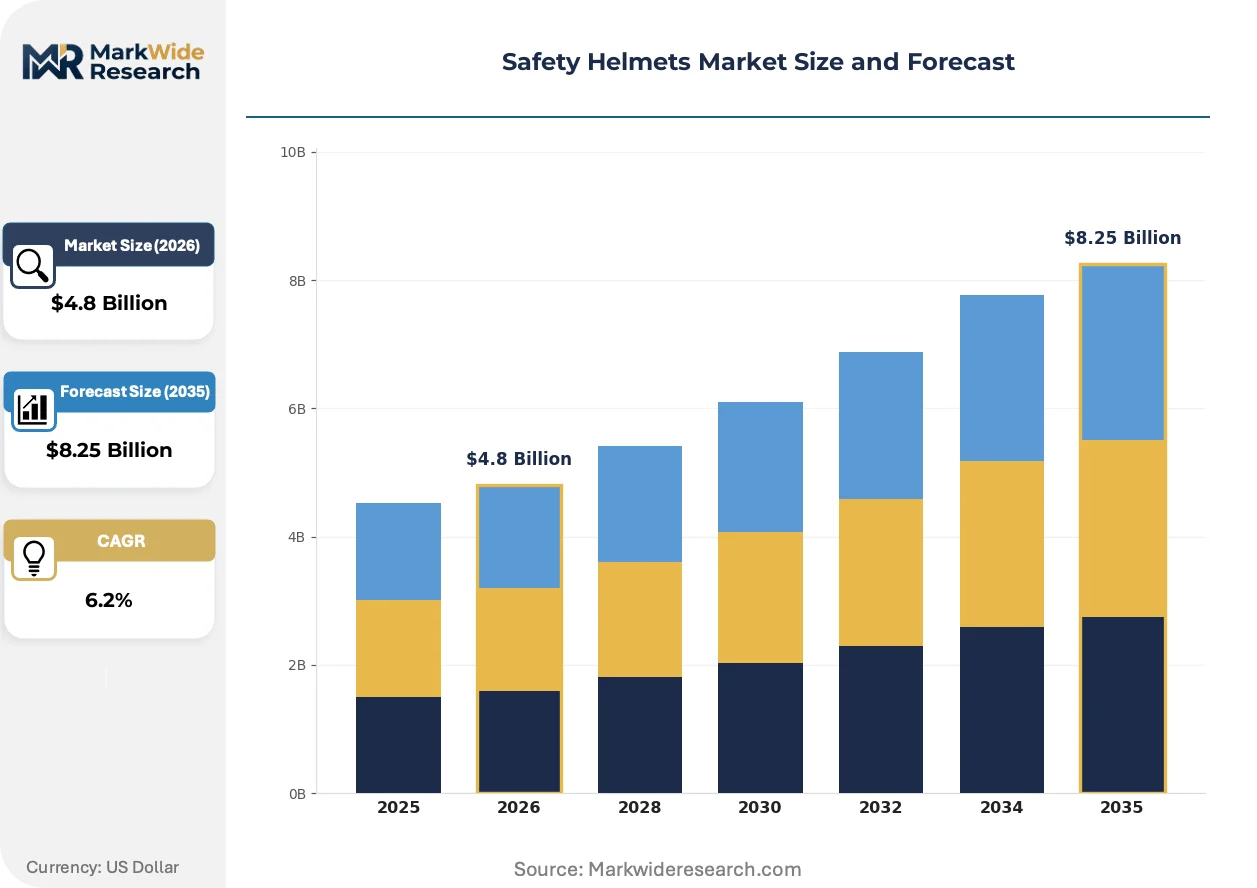
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Face Helmets, Half Shells, Lightweight Helmets, Bump Caps Material: Polycarbonate, Fiberglass, High-Density Polyethylene, Carbon Fiber Application: Construction, Manufacturing, Mining, Sports End User: Industrial Workers, Construction Contractors, Emergency Personnel, Recreational Users |
| Companies Covered | Delta Plus Group SA, Bullard, 3M Company, KASK Spa, Dragerwerk AG and Co. KGaA, Honeywell International Inc., UVEX Group, Centurion Safety Products Ltd., MSA Safety Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Helmets Market Strategic Shifts & Innovations
The evolution of safety helmets is accelerating, driven by the convergence of material science and digital technology. This shift is transforming the helmet from a passive piece of protective gear into an active component of a connected worksite safety ecosystem.
Integrated sensor technology, which detects impacts, falls, and proximity to hazards, is a primary area of innovation. High-risk industries such as mining, oil and gas, and utilities are the earliest adopters of these smart helmets. This technology is unifying passive head protection with active worksite monitoring systems, feeding critical data to safety managers and enabling immediate incident response.
European regulations, particularly the EN 397 standard under the CE marking framework, continue to set a high bar for industrial safety helmet performance. This standard's stringent requirements for shock absorption and penetration resistance directly influence material selection and shell design. Construction and heavy industry sectors across Europe are most affected, as they must procure helmets that meet these evolving criteria for lateral crush protection.
A notable shift in buying behavior involves large industrial enterprises moving away from exclusive supplier contracts for personal protective equipment. This trend disrupts the traditional distribution model, where a single vendor would supply a company's entire PPE needs. This pattern is most visible in the global manufacturing and logistics sectors, where procurement departments now prioritize supply chain diversification and resilience.
Safety Helmets Market Segmentation
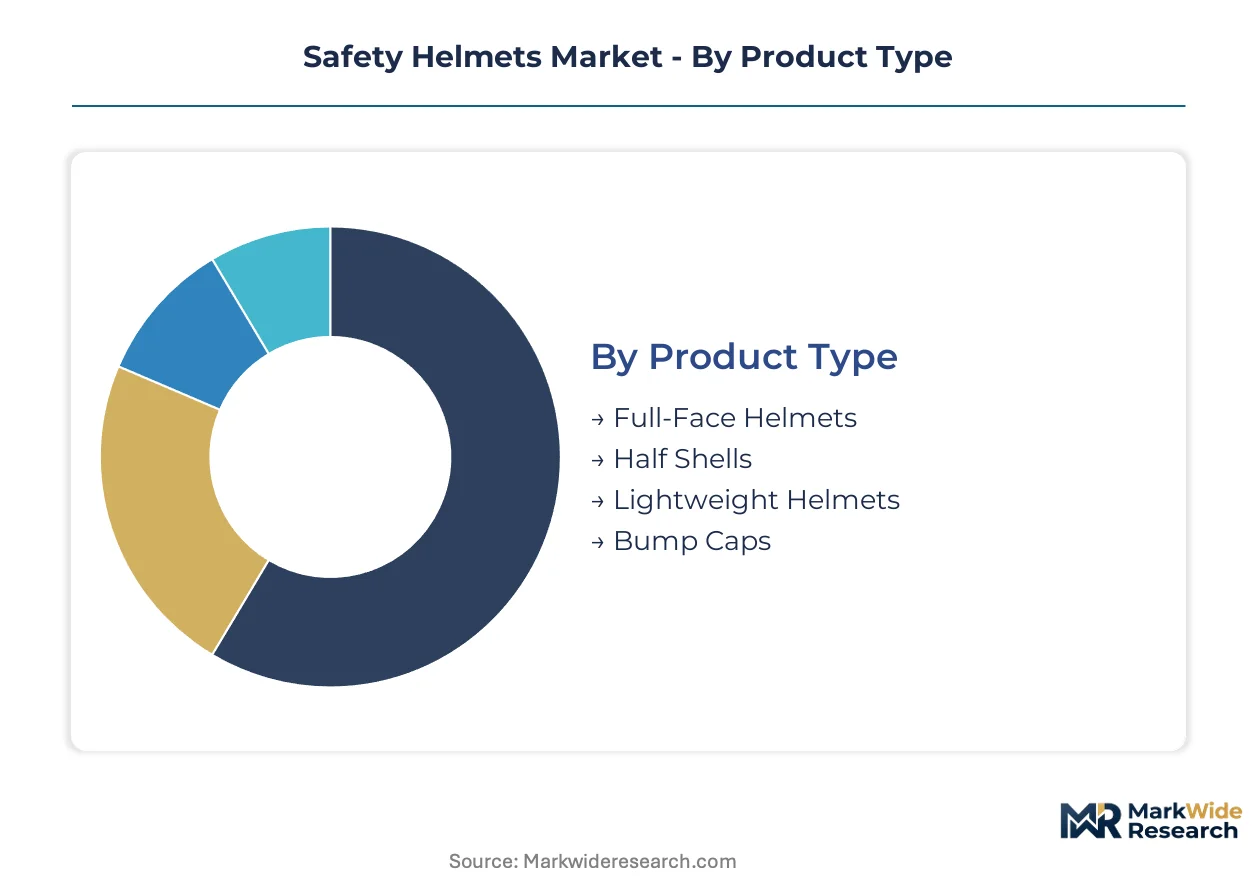
The safety helmets market segments reflect diverse protective requirements, material innovations, and end-user applications across industries. Understanding these distinctions allows manufacturers to tailor product development and procurement specialists to optimize their supply chain for specific operational needs. Compliance with international safety standards remains a fundamental differentiator across all segments.
Product Type:
Buyers prioritize specific helmet product types based on the level of head protection required for their operational environments and the nature of potential hazards.
- Full-Face Helmets:These helmets offer comprehensive head and face protection, often integrating visors or face shields for industrial settings where flying debris or chemical splashes are risks. Demand concentrates in welding, grinding, and forestry applications, where full facial coverage is non-negotiable.
- Half Shells:Providing primary top-of-head protection, half shell helmets are common in general construction and manufacturing, designed to guard against impacts from falling objects. Their lighter weight and open design contribute to user comfort during extended wear.
- Lightweight Helmets:Engineered with advanced materials or optimized designs, these helmets minimize wearer fatigue while maintaining essential protective qualities. The construction sector and utility workers increasingly seek lightweight options to enhance all-day comfort without compromising safety certifications.
- Bump Caps:Designed for environments with minor head bumps or scrapes, these offer less impact resistance than hard hats. Warehousing and light assembly operations frequently utilize bump caps for basic head protection.
Full-Face Helmets lead on scale; Lightweight Helmets lead on momentum.
Material:
Material selection for safety helmets directly influences both the protective capabilities and the final cost, creating distinct pricing tiers for industrial buyers.
- Polycarbonate:This material offers good impact resistance and optical clarity when used for visors, also forming durable helmet shells for various industrial applications. Helmets made from polycarbonate provide a balance of protection and cost-effectiveness for general use.
- Fiberglass:Fiberglass composite helmets deliver high strength-to-weight ratios and excellent rigidity, making them suitable for environments requiring robust protection. Specialized industrial workers in heavy manufacturing often use fiberglass helmets.
- High-Density Polyethylene:HDPE is a widely used, cost-effective material for standard industrial safety helmets, offering good impact absorption and chemical resistance. Demand from large-scale construction projects in India and Brazil drives significant volume for HDPE helmets.
- Carbon Fiber:Premium carbon fiber helmets provide superior impact resistance and exceptional lightness, often targeting specialized high-risk applications where weight reduction is critical. Mining and aerospace maintenance sectors increasingly adopt carbon fiber for enhanced worker mobility.
High-Density Polyethylene secures the largest volume, with carbon fiber expanding most quickly.
Application:
The volume of safety helmet procurement is heavily dictated by the specific industry application and its inherent safety risks and regulatory compliance mandates.
- Construction:This application represents the largest volume segment, driven by mandatory head protection regulations on building sites globally. Infrastructure development projects in countries like India and Brazil create substantial demand for construction-specific helmets.
- Manufacturing:Manufacturing facilities across various sectors, from automotive to electronics, mandate safety helmets to protect workers from machinery hazards and falling objects. OSHA regulations in the United States compel widespread adoption within manufacturing plants.
- Mining:Miners require robust head protection against falling rocks, impacts in confined spaces, and electrical hazards in underground and surface operations. Helmets for mining often integrate features like lamp brackets and communication systems.
- Sports:This segment includes helmets for recreational and professional sports, prioritizing specific impact zones and aerodynamic designs. Cycling and climbing activities drive demand for sports-specific headgear.
Construction applications account for the majority of helmet demand, with mining showing significant new purchases.
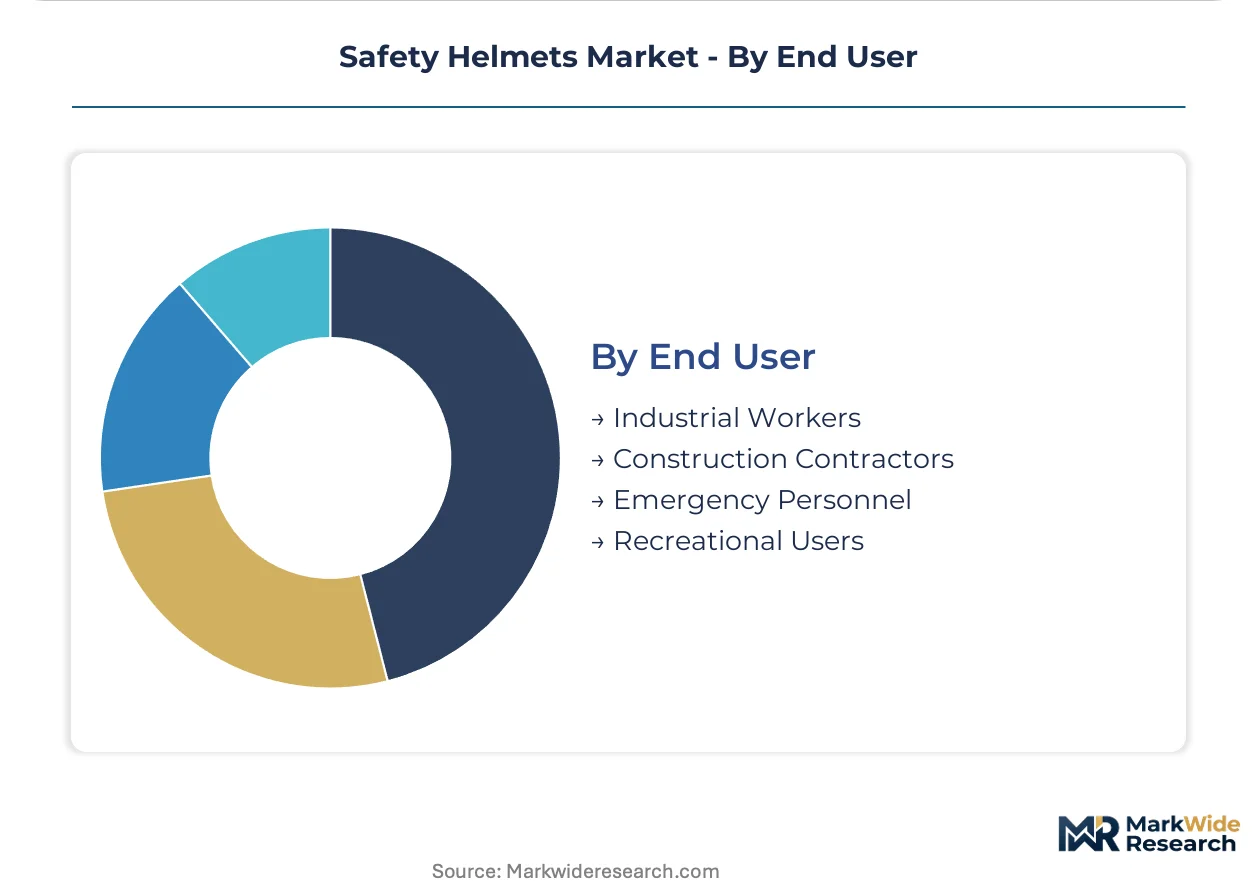
End User:
Specific end-user groups drive helmet design and feature requirements, reflecting diverse hazard exposures and regulatory compliance needs across various work environments.
- Industrial Workers:This broad category includes individuals working in factories, warehouses, and other industrial settings where head protection is mandated against impacts and falling objects. Compliance with EN 397 standards is critical for industrial workers across Europe.
- Construction Contractors:Contractors procure safety helmets for their workforce on construction sites, ensuring adherence to local safety regulations like ANSI/ISEA Z89.1 in the United States. Bulk purchasing by large contracting firms defines this segment.
- Emergency Personnel:Firefighters, paramedics, and rescue workers require specialized helmets offering protection against extreme heat, impacts, and often integrating communication systems. These helmets must meet stringent performance criteria for high-stress environments.
- Recreational Users:Individuals participating in activities such as climbing, kayaking, and skateboarding constitute this segment. Recreational helmets prioritize comfort, ventilation, and specific impact protection tailored to the sport.
Industrial Workers form the largest user base, while Emergency Personnel demonstrate unique specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The safety helmets market exhibits distinct regional dynamics, often influenced by the stringency of occupational safety regulations and the pace of industrialization. A regulatory-arbitrage angle sometimes influences production decisions, as manufacturers balance compliance costs in highly regulated markets against lower overheads in regions with less stringent oversight. This balance impacts both supply chain configuration and final product availability across different price points.
United States
United States demand for safety helmets stems from its large construction sector and robust manufacturing base. The US Occupational Safety and Health Administration (OSHA) mandates head protection across numerous industries, driving consistent procurement. Compliance with ANSI/ISEA Z89.1 standards is essential for market access, particularly in major infrastructure projects in states like California and Texas.
Germany
Germany's market for safety helmets is propelled by its advanced manufacturing industries and stringent European Union safety directives. The CE marking framework, including the EN 397 standard, ensures high performance and quality for industrial workers. Major automotive and machinery manufacturing hubs in Bavaria and Baden-Württemberg consistently require certified head protection.
India
India presents significant demand for safety helmets, fueled by its rapid infrastructure expansion and burgeoning industrial sector. Government-backed projects in transport and energy sectors create concentrated demand for industrial-grade head protection. The Bureau of Indian Standards (BIS) regulations guide product specifications, particularly in manufacturing zones like Maharashtra and Gujarat.
China
China's vast construction and manufacturing industries drive substantial volume in the safety helmets market. The country's GB 2811 standards dictate performance requirements for industrial safety helmets, influencing local production and imports. Major industrial clusters in the Yangtze River Delta and Pearl River Delta regions represent significant procurement centers.
Brazil
Brazil's market is experiencing growth due to ongoing infrastructure development and the formalization of labor laws in its manufacturing sector. Demand for certified safety equipment is rising as industrialization progresses across key states. Construction projects in São Paulo and mining operations in Minas Gerais anchor significant regional purchasing volumes.
Safety Helmets Market Key Industry Players
Established producers occupy the standard tier, providing high-volume, compliant products, while emerging entrants pursue adjacent spaces like smart helmet integration. The market structure exhibits a tiered approach, with players differentiating on material science, brand recognition, and technological sophistication. Strategic archetypes include diversified PPE providers, material science innovators, and specialized safety solution developers. Portfolio diversification and technology integration are dominant competitive moves among market participants.
Among the diversified suppliers, Honeywell International Inc. offers a broad portfolio of personal protective equipment, exemplifying a comprehensive market approach. MSA Safety Inc. leverages strong brand recognition within fire service and industrial sectors, anchoring its position in specialized segments. 3M Company, with its focus on material science innovation, represents the segment pushing advanced protective capabilities and comfort features.
| Leading Market Players |
|---|
| Delta Plus Group SA |
| Bullard |
| 3M Company |
| KASK Spa |
| Dragerwerk AG and Co. KGaA |
| Honeywell International Inc. |
| UVEX Group |
| Centurion Safety Products Ltd. |
| MSA Safety Inc. |
| Others |
Cost & Logistics Intelligence
Large industrial buyers' shift toward multi-sourcing strategies is rebalancing procurement, forcing safety helmet manufacturers to adapt both pricing models and supply chain configurations. This trend influences material selection and production location, driving a nuanced approach to market entry and expansion.
Pricing Analysis
Volatility in petroleum-derived polymers, such as high-density polyethylene, directly impacts the pricing of standard, high-volume safety helmets. The market operates primarily on a per-unit transactional pricing model, with project-based contracts for large infrastructure developments. Pricing stratifies across premium, standard, and economy tiers, driven by material science (e.g., carbon fiber versus HDPE), certification levels (ANSI/ISEA Z89.1, EN 397), and brand recognition. Pricing pressure stems from the proliferation of counterfeit products and raw material cost fluctuations. Construction contractors exhibit high price sensitivity for standard helmets, while specialized industries like mining accept premium pricing for advanced protective gear.
Supply Chain Analysis
Single-source vulnerability sits with specialized component suppliers, particularly for advanced sensors or specific composite materials. Supply chain concentration for high-volume, standard helmets is centered in China and India, leveraging lower manufacturing costs for HDPE products. Critical raw material dependencies include high-density polyethylene, polycarbonate, and carbon fiber composites. A structural risk involves commodity price volatility for petroleum-derived inputs, creating margin pressure for manufacturers. Distribution runs through a hybrid model, combining direct sales to large industrial enterprises implementing multi-sourcing strategies with traditional distributors serving smaller businesses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The safety helmets market offers geographic arbitrage opportunities, leveraging lower manufacturing costs in Asia against stringent regulatory requirements and premium pricing in Europe or North America.
For Market Incumbents: Cement brand loyalty through continuous innovation in smart technologies like integrated impact sensors and advanced materials. Diversify supply chains to mitigate raw material volatility and counter the threat of non-compliant counterfeit products. Invest in R&D for lighter, more comfortable designs that maintain core safety certifications, addressing wearer fatigue. Expand into underpenetrated geographies like Latin America, leveraging existing certification expertise for industrial workers.
For New Entrants and Emerging Players: Begin with specialized applications in high-risk environments, such as enhanced electrical insulation for electric vehicle battery plants, where premium pricing is accepted. Target niche segments like IoT-enabled smart helmets for mining or oil and gas, offering comprehensive safety solutions beyond basic head protection. Focus on rapid certification for specific regional standards, such as BIS in India, to gain market access quickly. Leverage agile manufacturing to offer customized solutions for smaller, high-value industrial clients.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology providers integrating IoT sensors into head protection. The long-term viability favors companies able to transition from product sales to comprehensive safety solution providers. Acquire firms with strong material science intellectual property in lightweight composites or established distribution networks in emerging markets. A signal to watch is the widespread adoption of smart helmet mandates by major industrial enterprises.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Integration Partnership | Unifies passive protection with active monitoring, feeding critical data to safety managers. |
| Advanced Materials R&D Investment | Develops lighter, stronger helmets using carbon fiber or polycarbonate for specialized applications. |
| Geographic Expansion into Latin America | Captures new demand from industrialization and formalization of labor laws in Brazil. |
| Multi-Sourcing Supply Chain Development | Enhances resilience and flexibility, mitigating input cost volatility for manufacturers. |
| Specialized Application Product Launch | Addresses niche, high-risk environments like EV battery plants with enhanced electrical insulation. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from industrial safety managers, procurement specialists, and R&D leads. This involves combining in-depth interviews with secondary validation from regulatory bodies like OSHA and CE marking. Data sources include national safety statistics, construction project databases, and material science journals. Bottom-up and top-down triangulation ensures robust market sizing.
Rate-of-change decomposition analyzes growth drivers and restraints across the analysis window, including regulatory mandates and infrastructure expansion. Segmentation dimensions modeled include product type, material, application, and end-user. Compound annual growth rates are derived from historical trends and projected economic indicators. Forecast inputs include industrial output projections and raw material price forecasts.
Caveats apply where unforeseen geopolitical events or rapid material science breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and economic development. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Machine Safety Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Safety Vest Market