
 Global Industrial Safety Footwear Market | 2026-2036
Global Industrial Safety Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Safety Footwear Market Foresight
Asset-light leasing models for industrial PPE procurement is reconfiguring competitive dynamics by lowering capital barriers for mid-sized contractors. Honeywell International Inc. leverages its integrated safety equipment portfolio to bundle footwear with respiratory and eye protection systems. Wolverine World Wide Inc. sustains manufacturing scale advantages through captive production facilities in North America and Asia. Bata Corporation anchors emerging market penetration through established retail infrastructure across multiple continents.
Industrial safety footwear comprises protective boots and shoes engineered with reinforced toe caps, puncture-resistant midsoles, and slip-resistant outsoles to shield workers from impact, compression, and electrical hazards in hazardous workplaces. Composite toe variants incorporate non-metallic materials such as Kevlar or carbon fiber to achieve ASTM F2413 impact ratings while eliminating cold-transfer and spark risks associated with steel. The product type dimension shows composite toe and carbon fiber toe categories gaining share as lightweight alternatives displace traditional steel in electrical and cold-environment applications. Within materials, polyurethane dominates mid-sole construction for energy return and durability, while rubber outsoles command premium positioning in oil, gas, and chemical plant settings where chemical resistance is non-negotiable.
OSHA workplace safety mandates in the United States, EU Machinery Directive compliance requirements, and ISO 20345 international standards collectively establish minimum protective specifications that manufacturers must satisfy for market access. Health Canada and Germany's KBA extend this regulatory architecture through national certification schemes that add testing layers beyond baseline international norms. Stakeholders must monitor evolving composite material certifications and regional enforcement intensity to align R&D investment with where compliance thresholds are tightening fastest.
Market Dynamics
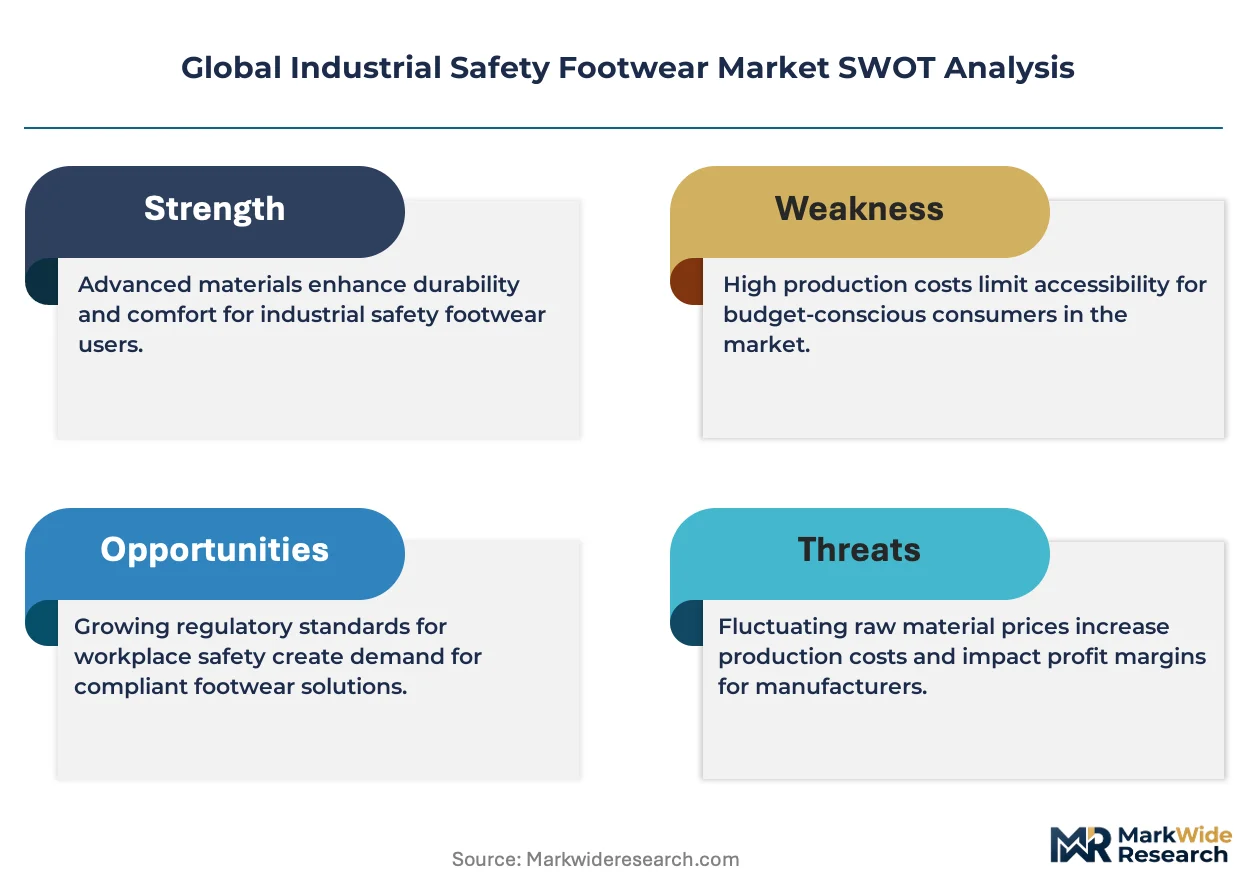
Composite toe technology is hybridizing with traditional steel constructions as manufacturers balance weight reduction against cost sensitivity in price-elastic emerging markets. Oil and gas field operators are driving specifications toward chemical-resistant outsoles while EU regulatory pressure accelerates certification complexity.
Growth Catalysts
- EU Machinery Directive enforcement:Germany's KBA and France's labor inspectorate are mandating ISO 20345-compliant footwear in heavy manufacturing, forcing fleet-wide replacements at automotive plants and metal fabrication facilities.
- Polyurethane midsole advances:Energy-return formulations from chemical suppliers are extending boot lifespan in warehouse and logistics environments where concrete flooring accelerates wear.
- Brazil:ANVISA alignment with international PPE standards is opening import pathways for certified manufacturers while Petrobras procurement expands chemical-resistant specifications for offshore platforms.
Market Restraints
- Petrochemical input volatility:Polyurethane and synthetic rubber prices fluctuate with crude oil indices, compressing margins for mid-tier manufacturers without long-term supply contracts.
- China supply concentration:Carbon fiber toe cap production clusters in Zhejiang and Guangdong provinces create geographic risk exposure for brands dependent on single-source composite suppliers.
- Steel toe thermal conductivity:Cold-transfer limitations in sub-zero environments restrict steel's utility in Nordic and Canadian oil extraction, fragmenting material preferences by climate zone.
Strategic Opportunities
- India:BIS certification harmonization with ISO 20345 is reducing technical barriers for international entrants as construction and mining safety enforcement intensifies in Maharashtra and Karnataka.
- Leasing and rental models:Industrial laundries and PPE service providers are embedding footwear into managed rental programs, shifting capital expenditure to operating expense for construction contractors.
- Sensor integration:Pressure-mapping and fatigue-monitoring insoles are converging with traditional safety boot architecture, opening premium positioning for connected worker platforms in warehousing and distribution.
Industry Challenges
- Composite certification timelines:ASTM F2413 and ISO 20345 testing protocols for non-metallic toe caps require extended validation cycles, delaying product launches by six to twelve months.
- Multi-standard compliance:Manufacturers serving both North American and European markets must maintain parallel testing documentation for OSHA, CSA, and CE marking schemes, inflating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Safety Footwear Market |
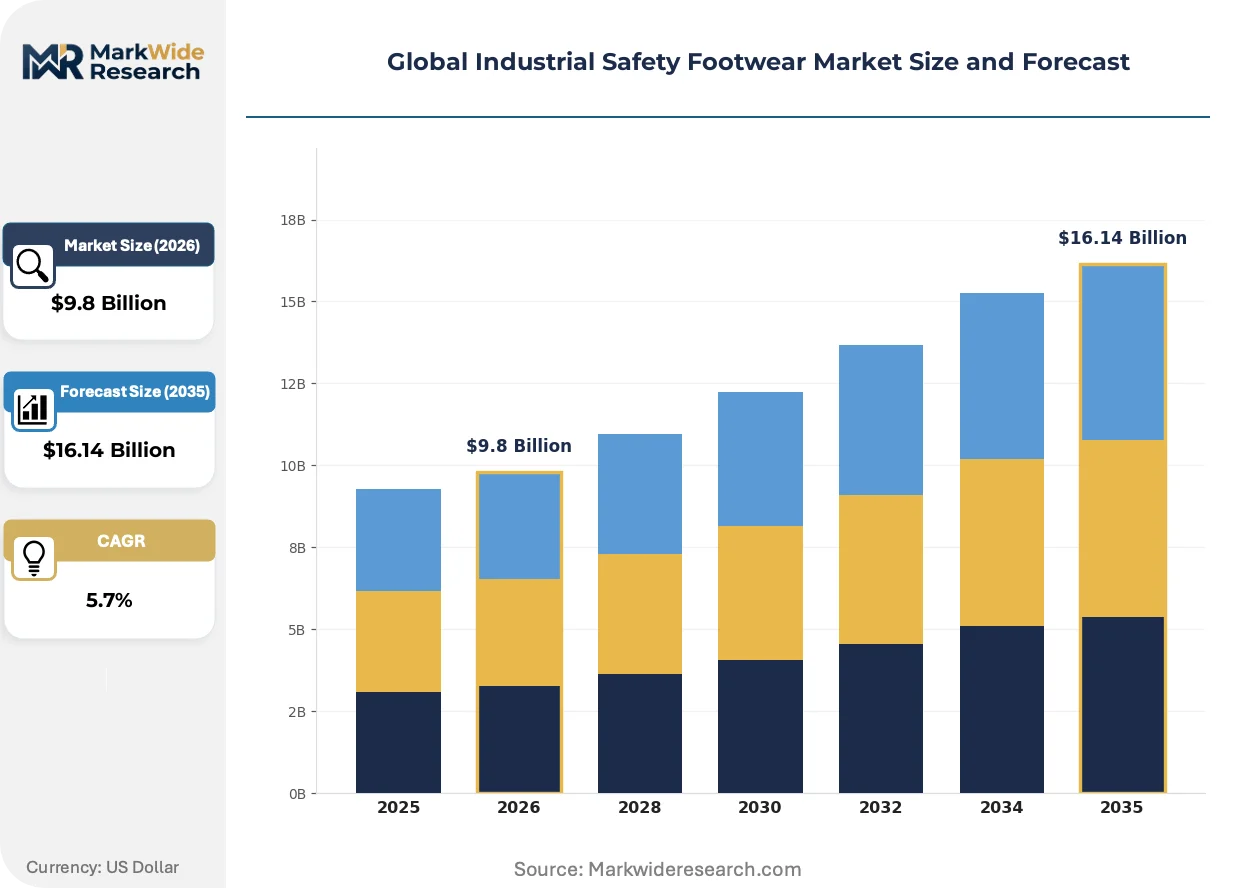
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Toe, Composite Toe, Alloy Toe, Aluminum Toe, Carbon Fiber Toe Material: Leather, Rubber, Polyurethane, PVC, Neoprene Application: Construction, Manufacturing, Mining, Oil & Gas, Warehousing End User Industry: Logistics, Agriculture, Food Processing, Chemical Plants, Utilities |
| Companies Covered | Honeywell International Inc., Wolverine World Wide Inc., VF Corporation, Bata Corporation, Dunlop Protective Footwear, uvex group, Elten GmbH, JAL Group, COFRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Safety Footwear Market Shifts & Advancements
Material science breakthroughs are compressing the weight-performance tradeoff that has historically segmented premium from standard safety footwear tiers. Digital integration and circular economy mandates are simultaneously reshaping product architecture and end-of-life obligations.
Carbon fiber reinforced polymer toe caps are hybridizing with thermoplastic polyurethane shells to achieve ASTM F2413 impact ratings at 40% weight reduction versus steel equivalents. Petrochemical operators in the US Gulf Coast and North Sea installations are specifying these hybrids for twelve-hour shift comfort without sacrificing drop-test performance. The technology is compressing price premiums for lightweight protection, forcing steel-toe incumbents to defend positioning through durability claims rather than cost advantage.
REACH chemical restrictions and the EU Green Deal's extended producer responsibility frameworks are mandating recyclability disclosures for footwear sold in Germany, France, and Italy. Manufacturers must now document sole-to-upper material separation capabilities and establish take-back partnerships with industrial waste processors. The German market is responding fastest, with KBA-aligned procurement specifications beginning to preference mono-material constructions that simplify end-of-life sorting.
Mid-sized construction contractors are consolidating vendor relationships through integrated safety equipment programs that bundle footwear with respiratory and fall protection. Distributors serving the US Midwest and Texas oil patch are displacing standalone footwear specialists by offering consolidated billing and site-level inventory management. Brazil's industrial corridor from São Paulo to Rio de Janeiro exhibits the most pronounced consolidation, as ANVISA-registered distributors capture procurement rationalization mandates from multinational engineering firms.
Global Industrial Safety Footwear Market Segmentation
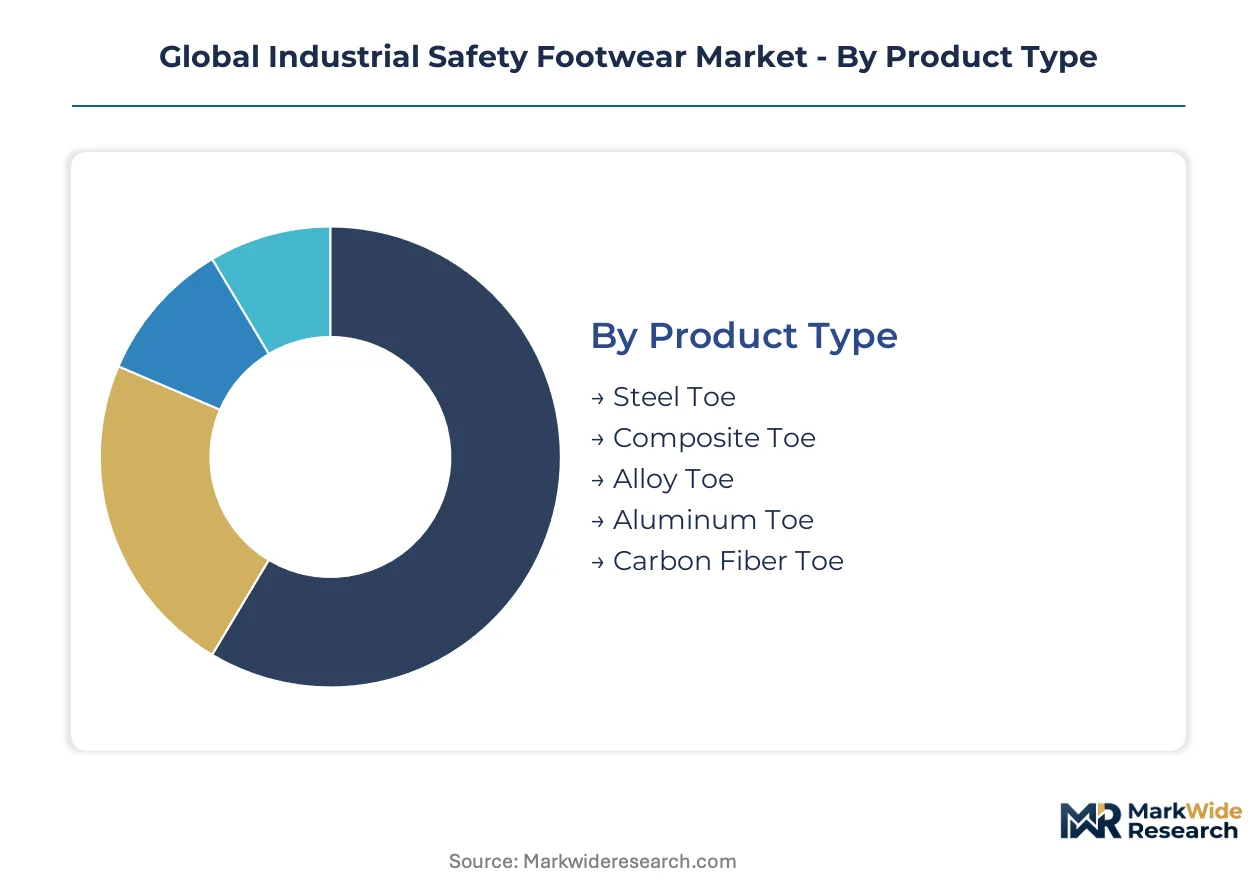
Industrial safety footwear segmentation reveals divergent replacement cycles across protective technologies and material platforms. Procurement managers align inventory turnover with hazard exposure intensity and regulatory refresh mandates.
Product Type:
Steel toe variants turn over slowest due to established supply chains and price-driven bulk purchasing, while composite and carbon fiber technologies refresh fastest as lightweight specifications displace legacy metal constructions.
- Steel Toe:Traditional steel-reinforced caps deliver ASTM F2413 impact resistance at the lowest unit cost. German automotive assembly plants and Texas oilfield contractors maintain fleet-wide steel specifications where thermal conductivity limitations are non-critical.
- Composite Toe:Non-metallic Kevlar and fiberglass constructions eliminate cold-transfer and spark hazards for electrical trades. Norwegian offshore platforms and Canadian oil sands operators specify composite for sub-zero shift comfort without sacrificing drop-test performance.
- Alloy Toe:Titanium-aluminum blends reduce weight versus steel while retaining metal-detector compatibility. Airport logistics and food processing facilities in France favor alloy for security checkpoint passage.
- Aluminum Toe:Pure aluminum caps offer intermediate weight reduction at moderate cost premiums. Brazilian construction contractors deploy aluminum toe for tropical climate comfort.
- Carbon Fiber Toe:Advanced polymer-matrix composites achieve maximum strength-to-weight ratios. Petrochemical operators in the US Gulf Coast specify carbon fiber for twelve-hour shift endurance.
Steel toe anchors the volume base while carbon fiber toe gains share at the steepest rate.
Material:
Cost tier stratification separates premium chemical-resistant formulations from commodity constructions, with polyurethane commanding mid-market positioning through energy-return performance.
- Leather:Full-grain and split-leather uppers dominate durability specifications for welding and foundry applications. Italian tanneries supply premium hides for German KBA-certified boots.
- Rubber:Natural and synthetic rubber outsoles deliver non-negotiable chemical resistance for oil and gas field operations. North Sea installations mandate rubber for hydrocarbon exposure protection.
- Polyurethane:Injection-molded PU midsoles provide superior energy return and abrasion resistance. Warehouse operators in Maharashtra, India specify PU for concrete flooring endurance.
- PVC:Polyvinyl chloride constructions offer cost-efficient waterproofing for agricultural and food processing wet environments. Brazilian poultry processors favor PVC for washdown compliance.
- Neoprene:Synthetic rubber compounds excel in chemical and thermal insulation. Chemical plant operators in Louisiana specify neoprene for acid resistance.
Polyurethane captures the broadest application footprint while rubber commands the steepest price premiums.
Application:
Customer type differentiation separates project-based construction procurement from continuous manufacturing fleet replacement, with mining and oil and gas exhibiting the longest replacement intervals due to specialized hazard ratings.
- Construction:General contractor procurement spans residential, commercial, and infrastructure projects. India's National Highways Authority mandates ISO 20345 compliance for roadwork crews.
- Manufacturing:Automotive and metal fabrication plants enforce uniform fleet standards. Germany's KBA inspections drive replacement cycles at Bavarian automotive facilities.
- Mining:Underground and surface extraction operations require puncture-resistant midsoles and metatarsal guards. South African platinum mines specify reinforced metatarsal protection.
- Oil & Gas:Onshore drilling and offshore platform operations demand chemical-resistant outsoles and static-dissipative properties. Petrobras procurement in Brazil drives specifications for Atlantic basin operations.
- Warehousing:E-commerce fulfillment and distribution centers prioritize lightweight comfort for walking-intensive shifts. Amazon fulfillment centers in Poland specify composite toe for ten-hour shift ergonomics.
Construction generates the highest unit volume while oil and gas commands the most stringent specification premiums.
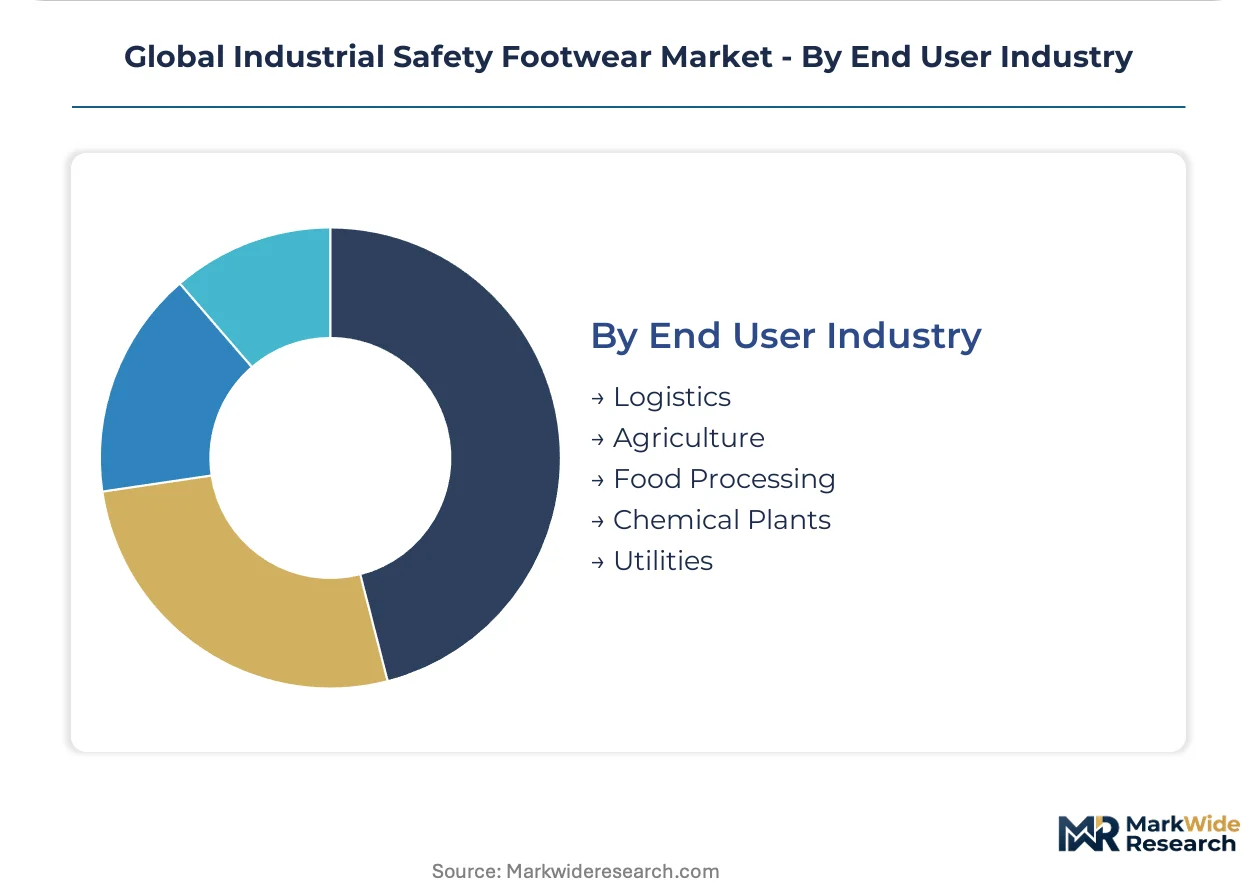
End User Industry:
Geography clusters reveal regulatory enforcement intensity as the primary segmentation driver, with EU member states and select US states advancing certification requirements fastest.
- Logistics:Third-party warehousing and last-mile delivery operations balance comfort against minimum compliance. DHL supply chain facilities in Germany specify lightweight composite for driver mobility.
- Agriculture:Crop and livestock operations face seasonal demand spikes and wet-environment exposure. California Central Valley contractors favor waterproof PVC constructions.
- Food Processing:Meatpacking and dairy operations require washdown-compatible materials and slip resistance. JBS facilities in Brazil mandate ANVISA-registered footwear for contamination control.
- Chemical Plants:Petrochemical and specialty chemical operations specify the highest chemical resistance ratings. BASF Ludwigshafen procurement drives German chemical industry standards.
- Utilities:Electric power generation and transmission trades require electrical hazard protection. Florida Power & Light specifies ASTM F2413 EH-rated boots for lineworkers.
Logistics represents the largest addressable base while chemical plants drive the most demanding performance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA enforcement intensification and EU Machinery Directive compliance deadlines are synchronizing procurement cycles across industrial corridors. Brazil's ANVISA alignment with international PPE standards is unlocking import pathways for certified manufacturers. India's BIS harmonization with ISO 20345 is accelerating safety footwear adoption in construction and mining clusters.
United States
Petrochemical operators along the US Gulf Coast are driving specifications toward carbon fiber toe caps for twelve-hour shift endurance. OSHA workplace safety mandates enforce ASTM F2413 compliance across automotive assembly plants in Michigan and Ohio. Warehouse operators in Amazon fulfillment centers across Pennsylvania and Illinois specify composite toe variants for ten-hour walking-intensive shifts.
Germany
Automotive and metal fabrication facilities enforce uniform fleet standards under KBA inspection protocols. The EU Machinery Directive and REACH chemical restrictions mandate recyclability disclosures and mono-material constructions. Bavarian automotive plants and North Rhine-Westphalia chemical facilities drive replacement cycles through regulatory refresh mandates.
Brazil
Petrobras procurement for offshore Atlantic basin platforms expands chemical-resistant safety boot specifications. ANVISA alignment with international PPE standards reduces technical barriers for certified international entrants. The industrial corridor from São Paulo to Rio de Janeiro exhibits pronounced distributor consolidation as multinational engineering firms rationalize procurement.
India
Construction and mining safety enforcement intensifies in Maharashtra and Karnataka as BIS certification harmonizes with ISO 20345. The National Highways Authority mandates ISO 20345 compliance for roadwork crews. Warehouse operators in Maharashtra specify polyurethane midsole constructions for concrete flooring endurance in logistics facilities.
China
Carbon fiber toe cap production clusters in Zhejiang and Guangdong provinces create geographic concentration for composite suppliers. Manufacturing scale advantages sustain export competitiveness for mid-tier safety footwear producers. Industrial safety procurement in Shanghai and Shenzhen manufacturing zones emphasizes cost-efficient bulk purchasing for construction contractor fleets.
Global Industrial Safety Footwear Market Competitive Landscape
On the supply side, the industry is consolidating around integrated safety equipment portfolios and captive manufacturing scale. Tiered competitive positioning separates premium technology specialists from volume-driven manufacturers serving price-sensitive emerging markets. Three strategic archetypes dominate: diversified industrial conglomerates bundling footwear with respiratory and fall protection systems; vertically integrated manufacturers controlling North American and Asian production facilities; and established retail infrastructure operators penetrating multiple continents through distribution networks. Dominant competitive moves include portfolio diversification into connected worker platforms with sensor-integrated insoles and geographic expansion through ANVISA and BIS certification pathways.
Among diversified industrial conglomerates, Honeywell International Inc. exemplifies the integrated safety equipment archetype through bundled procurement programs. Wolverine World Wide Inc. represents vertically integrated manufacturing scale with captive production facilities spanning multiple continents. Bata Corporation anchors the established retail infrastructure archetype through distribution networks penetrating emerging markets across multiple continents.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Wolverine World Wide Inc. |
| VF Corporation |
| Bata Corporation |
| Dunlop Protective Footwear |
| uvex group |
| Elten GmbH |
| JAL Group |
| COFRA |
| Others |
Supply & Pricing Matrix
Carbon fiber toe cap production clusters in Zhejiang and Guangdong provinces concentrate upstream supply leverage, concentrating margin capture with composite material specialists while downstream brands compete on certification tier and shift-comfort positioning.
Pricing Analysis
Certification level creates the primary spread across ASTM F2413, ISO 20345, and CE-marked tiers, with German KBA and Brazil ANVISA registrations commanding 15-25% premiums over baseline compliance. Three-tier pricing structure across premium carbon fiber, standard composite, and economy steel toe segments reflects energy-return midsole technology and chemical-resistant rubber outsole specifications. Cost compression in polyurethane midsole formulations intensifies as petrochemical input volatility squeezes mid-tier manufacturers lacking long-term supply contracts. Construction contractors in price-sensitive emerging markets exhibit highest price sensitivity, while oil and gas operators in the US Gulf Coast and North Sea prioritize performance specifications over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Wolverine World Wide's captive facilities in North America and Asia, alongside Bata Corporation's vertically integrated production across multiple continents. Raw material dependencies center on carbon fiber from Chinese Zhejiang clusters, polyurethane formulations from German chemical suppliers, and natural rubber from Southeast Asian plantations. Single-source vulnerability in carbon fiber toe cap supply creates geographic risk exposure for brands dependent on Zhejiang and Guangdong province production. Distribution runs through industrial safety distributors bundling footwear with respiratory and fall protection systems, with consolidated procurement programs displacing standalone footwear specialists in the US Midwest and Texas oil patch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial safety footwear is entering a cyclical recovery phase as post-pandemic capital expenditure normalization in manufacturing and construction drives fleet replacement demand.
For Market Incumbents: Pre-empt composite toe certification bottlenecks by accelerating ASTM F2413 and ISO 20345 validation cycles for hybrid carbon fiber-thermoplastic polyurethane constructions before regulatory refresh mandates in Germany and France accelerate. Secure captive supply of carbon fiber toe caps through backward integration into Zhejiang province production partnerships, mitigating single-source concentration risk that threatens margin stability. For New Entrants and Emerging Players: Pursue ANVISA certification pathways for Brazil's industrial corridor from São Paulo to Rio de Janeiro, where Petrobras procurement expansion and distributor consolidation create white-space for certified international entrants. Target India's Maharashtra and Karnataka construction clusters as BIS harmonization with ISO 20345 reduces technical barriers, leveraging polyurethane midsole specifications for concrete flooring endurance in warehouse and logistics applications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial PPE service providers embedding footwear into managed rental programs, shifting capital expenditure to operating expense for mid-sized construction contractors. Long-term viability over a five-to-ten year window favors acquisition targets with sensor-integrated insole capabilities converging with connected worker platforms. Monitor quarterly certification timeline extensions for composite toe variants as inflection indicator for R&D investment efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Certification Acceleration | ASTM F2413 validation cycles for carbon fiber toe caps compress six-to-twelve month delays before German KBA mandates tighten. |
| Managed Rental Program Expansion | Industrial laundries embedding footwear into PPE service contracts shift contractor procurement from capital to operating expense. |
| Sensor-Integrated Insole Development | Pressure-mapping technology converges with safety boot architecture for Amazon fulfillment center ten-hour shift ergonomics. |
| ANVISA Certification Pathway Investment | Brazil's alignment with international PPE standards unlocks import pathways for Petrobras offshore platform specifications. |
| Backward Integration into Carbon Fiber Supply | Captive production partnerships in Zhejiang province mitigate geographic concentration risk for composite toe cap sourcing. |
Research Methodology
Operator-level perspectives from plant safety managers, procurement leads at oil and gas operators, industrial laundry service providers, and distributor channel partners anchored the qualitative base. Primary interviews combined with secondary validation from OSHA enforcement records, EU Machinery Directive compliance databases, ANVISA registration filings, and BIS certification harmonization documentation. Customs and trade data from India, Brazil, and Germany supplemented SEC 10-K disclosures from listed safety equipment manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic industrial production indices.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling protective technology type, material platform, application intensity, and regional regulatory enforcement cluster as primary segmentation dimensions. CAGRs derived from regression analysis of historical replacement cycle data against industrial production forecasts and regulatory mandate implementation timelines. Oil and gas capital expenditure trajectories and warehouse construction permit volumes served as industry-specific demand inputs.
Sensitivities concentrate around petrochemical input volatility, composite certification timeline extensions, and regional enforcement intensity variations. Forecasts reflect documented assumptions regarding regulatory harmonization pace and replacement cycle normalization. Quarterly review of ASTM F2413 validation queue lengths, ANVISA registration approval rates, and German KBA inspection frequency is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Industrial Safety Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Machine Safety Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Safety Vest Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Canada Safety Services Market