
 Industrial Safety Mats Market | 2026-2036
Industrial Safety Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Safety Mats Market Foresight
A shift from single-source procurement to multi-source qualification is pivoting how industrial buyers manage safety mat supply chains. 3M Company leverages its materials science portfolio to dominate high-performance electrical insulation segments. Wearwell LLC anchors its position through specialized anti-fatigue solutions for standing workstations. COBA Europe Ltd competes across rubber and PVC formulations with broad European manufacturing coverage.
Industrial safety mats are engineered floor coverings constructed from rubber, foam, PVC, or carpet substrates, typically featuring slip-resistant surfaces, electrical insulation properties, or ergonomic cushioning with thicknesses ranging from 12mm to 25mm depending on hazard classification. These products serve to reduce slip incidents, mitigate static discharge, alleviate musculoskeletal strain, and comply with workplace hazard controls. Anti-fatigue mats command the strongest margin pools due to specialized foam formulations and occupational health claims, while electrical insulation mats face the most stringent certification barriers. Rubber mats sustain volume leadership across manufacturing facilities and warehouses where chemical resistance and durability requirements dominate purchasing criteria.
OSHA General Industry Standards, ISO 20347 occupational footwear and matting benchmarks, and REACH chemical compliance frameworks collectively shape product specifications, testing protocols, and market access conditions for industrial safety mat suppliers. The EU Machinery Directive and CE marking requirements further constrain entry for non-compliant manufacturers serving European industrial end users. Stakeholders must monitor evolving ergonomic regulations and material disclosure rules to anticipate specification changes before they disrupt sourcing decisions.
Market Dynamics
OSHA workplace safety mandates and ISO ergonomic standards are tightening compliance requirements, forcing manufacturing facilities to expand mat deployment on assembly lines and driving specification upgrades across procurement cycles.
Growth Catalysts
- OSHA General Industry Standards:Manufacturing facilities in the United States face escalating inspection frequency and penalty structures, compelling systematic replacement of legacy floor coverings with certified anti-fatigue and electrical insulation matting.
- Industrial automation density:Germany's automotive and precision engineering clusters drive premium mat adoption as robotic workstations require specialized static-dissipative and ergonomic cushioning solutions.
- REACH chemical compliance frameworks:European industrial buyers are disqualifying PVC formulations containing restricted plasticizers, redirecting volume toward rubber and thermoplastic elastomer alternatives with full material disclosure documentation.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and climate-induced yield fluctuations compress margin pools for manufacturers dependent on latex-based formulations.
- Electrical insulation certification barriers:IEC 61111 dielectric testing protocols and third-party validation timelines extend product launch cycles by 8-14 months for new market entrants.
- Modular flooring systems:Interlocking polymer tiles and poured epoxy surfaces capture warehouse and light manufacturing applications previously served by roll matting.
Strategic Opportunities
- India's PLI scheme for manufacturing:Greenfield electronics and automotive assembly plants create first-mover positioning for suppliers establishing local testing and distribution infrastructure.
- EU Green Deal procurement criteria:Public sector tender specifications now weight recycled content and carbon footprint metrics, advantaging mat producers with circular material flows and EPD documentation.
- Sensor-embedded smart matting:Convergence of pressure-sensing films with industrial IoT platforms enables predictive maintenance and workforce analytics, opening subscription-based revenue models.
Industry Challenges
- Polymer formulation chemistry expertise:Shortage of compounders capable of balancing flame retardancy, electrical insulation, and ergonomic density within single substrates constrains product development pipelines.
- Multi-jurisdiction certification management:Simultaneous pursuit of OSHA, CE marking, and BIS approvals fragments engineering resources and delays geographic expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Safety Mats Market |
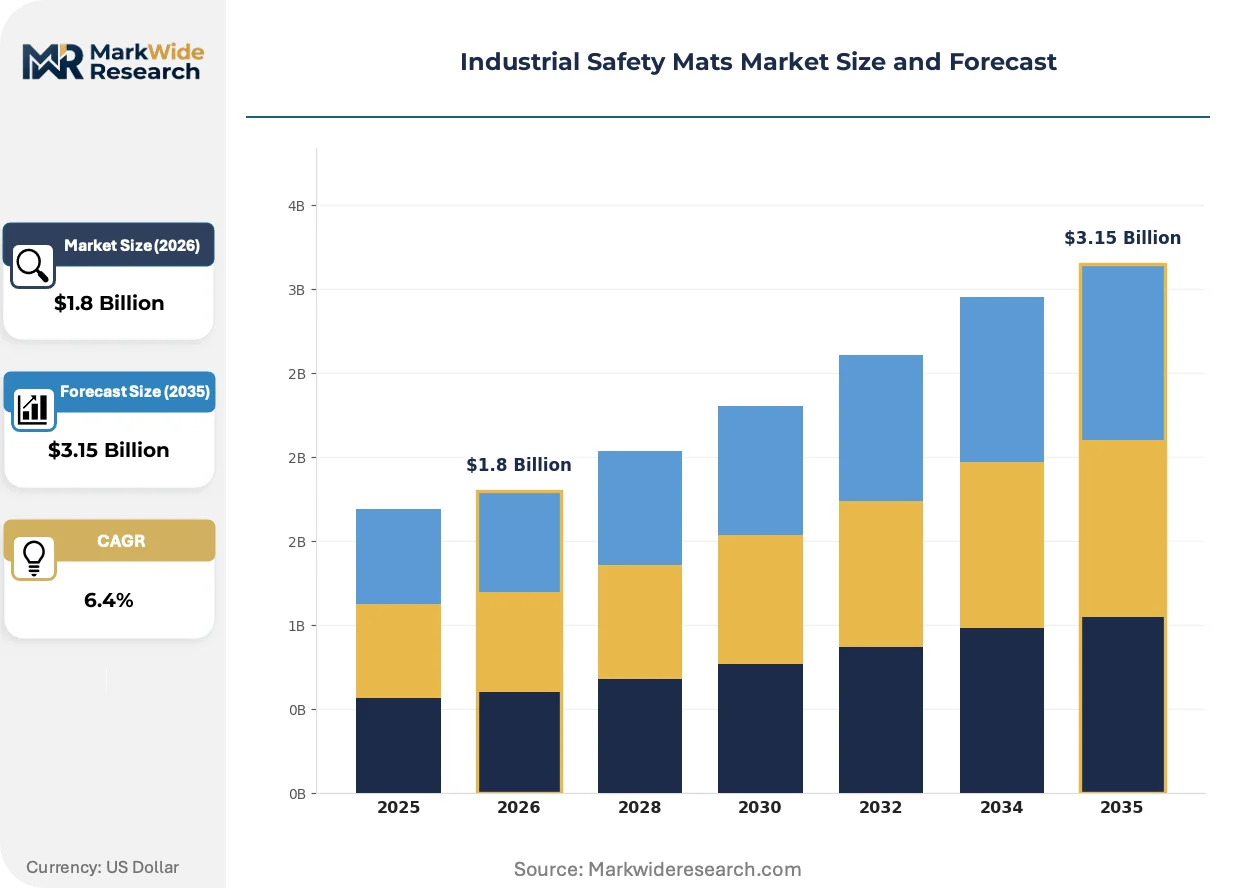
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Mats, Anti-Fatigue Mats, Chemical-Resistant Mats, Electrical Insulation Mats End User: Manufacturing Facilities, Warehouses, Laboratories, Construction Sites Application: Floor Safety, Workstation Comfort, Hazard Protection, Ergonomic Solutions Material: Rubber, Foam, PVC, Carpet |
| Companies Covered | 3M Company, Wearwell LLC, Notrax, Cintas Corporation, Crown Matting Technologies, COBA Europe Ltd, Apache Mills, M+A Matting, Bergo Flooring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Safety Mats Market Shifts & Advancements
Active materials science development and procurement digitization are compressing product lifecycles while elevating performance benchmarks across electrical insulation, ergonomic, and chemical-resistant segments.
Conductive carbon nanotube dispersions are integrating into rubber substrates to deliver consistent static-dissipative properties across humidity extremes. Semiconductor fabrication facilities and aerospace component manufacturers are specifying these formulations for cleanroom and explosive atmosphere applications. The technology is integrating quality assurance protocols previously reserved for pharmaceutical manufacturing into industrial matting supply chains.
EU Machinery Directive updates are mandating documented slip resistance coefficients for all powered equipment operating zones. Industrial buyers must now specify mats with EN 13845-tested surface profiles and maintain replacement schedules tied to wear-indicator thresholds. German automotive OEMs are pushing this requirement upstream through supplier quality agreements.
Consolidated procurement platforms are displacing distributor-centric purchasing for multi-site manufacturing organizations. Facility managers at US and European industrial conglomerates now issue blanket purchase orders with centralized specification control, compressing vendor lists and demanding digital inventory integration. Food processing and pharmaceutical verticals show the fastest migration toward direct manufacturer relationships with vendor-managed replenishment.
Industrial Safety Mats Market Segmentation
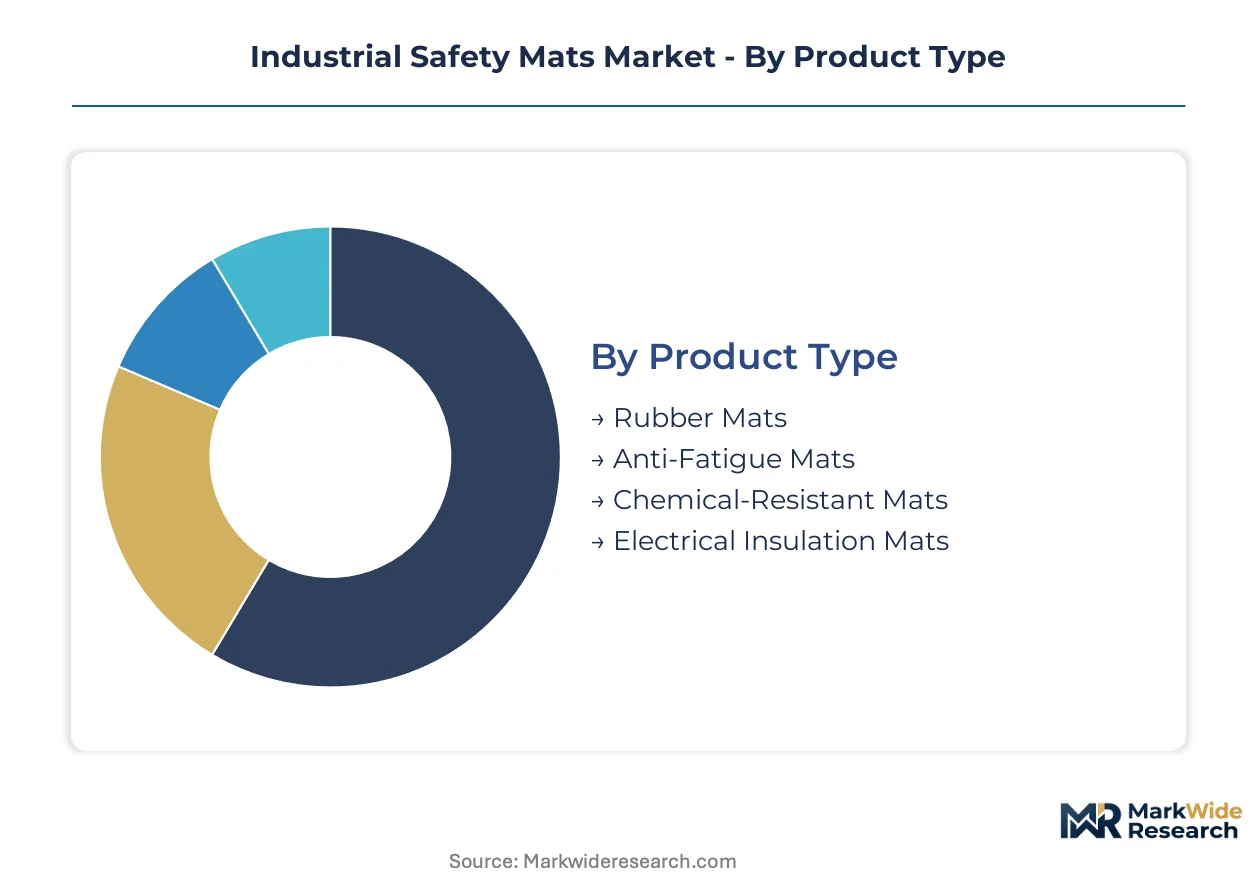
Industrial safety mat procurement hinges on matching substrate properties to precise hazard classifications. Specification divergence across end-use environments fragments supplier portfolios and forces compounders to maintain parallel formulation capabilities.
Product Type:
Supply concentration clusters around rubber-based formulations due to established Southeast Asian latex processing infrastructure and mature vulcanization expertise.
- Rubber Mats:Natural and synthetic rubber compounds deliver chemical resistance and durability for heavy-traffic manufacturing floors. Automotive assembly plants in Germany and chemical processing facilities in the United States specify these formulations for their recovery properties under continuous load.
- Anti-Fatigue Mats:Multi-density foam substrates with graduated compression zones reduce musculoskeletal strain during prolonged standing. Distribution centers and precision assembly operations specify these for workstation compliance with OSHA ergonomic guidelines.
- Chemical-Resistant Mats:Nitrile and neoprene formulations withstand petroleum-based solvents and caustic washdowns in food processing and pharmaceutical cleanrooms.
- Electrical Insulation Mats:Dielectric rubber compounds meeting IEC 61111 standards protect maintenance personnel from energized equipment up to specified voltage classes.
Rubber mats absorb the bulk of installed capacity; anti-fatigue mats are expanding most quickly.
End User:
Cost tier differentiation separates specification-grade procurement from commodity replacement cycles across facility types.
- Manufacturing Facilities:High-volume deployment of anti-fatigue and static-dissipative matting at assembly workstations. German automotive OEMs mandate EN 13845-tested surface profiles through supplier quality agreements.
- Warehouses:Interlocking rubber tiles and heavy-duty roll matting dominate loading docks and picking zones. E-commerce fulfillment networks drive specification upgrades for slip resistance certification.
- Laboratories:Cleanroom-compatible formulations with low particulate shedding for semiconductor fabrication and pharmaceutical quality control environments.
- Construction Sites:Temporary portable matting for weather protection and ground stabilization during infrastructure projects.
Manufacturing facilities absorb the bulk of installed capacity; warehouses are expanding most quickly.
Application:
Volume concentration tracks regulatory inspection frequency and penalty structures rather than discretionary safety investment.
- Floor Safety:Slip-resistant surface profiles with documented coefficient of friction values. EU Machinery Directive updates now mandate replacement schedules tied to wear-indicator thresholds.
- Workstation Comfort:Ergonomic cushioning solutions for standing tasks exceeding two hours duration. OSHA General Industry Standards enforcement drives systematic retrofit programs.
- Hazard Protection:Chemical containment and electrical isolation for maintenance and repair operations.
- Ergonomic Solutions:Integrated anti-fatigue and conductive properties for combined musculoskeletal and static discharge control.
Floor safety absorbs the bulk of installed capacity; ergonomic solutions are expanding most quickly.
Material:
Margin tier stratification reflects formulation complexity and certification burden rather than raw material cost alone.
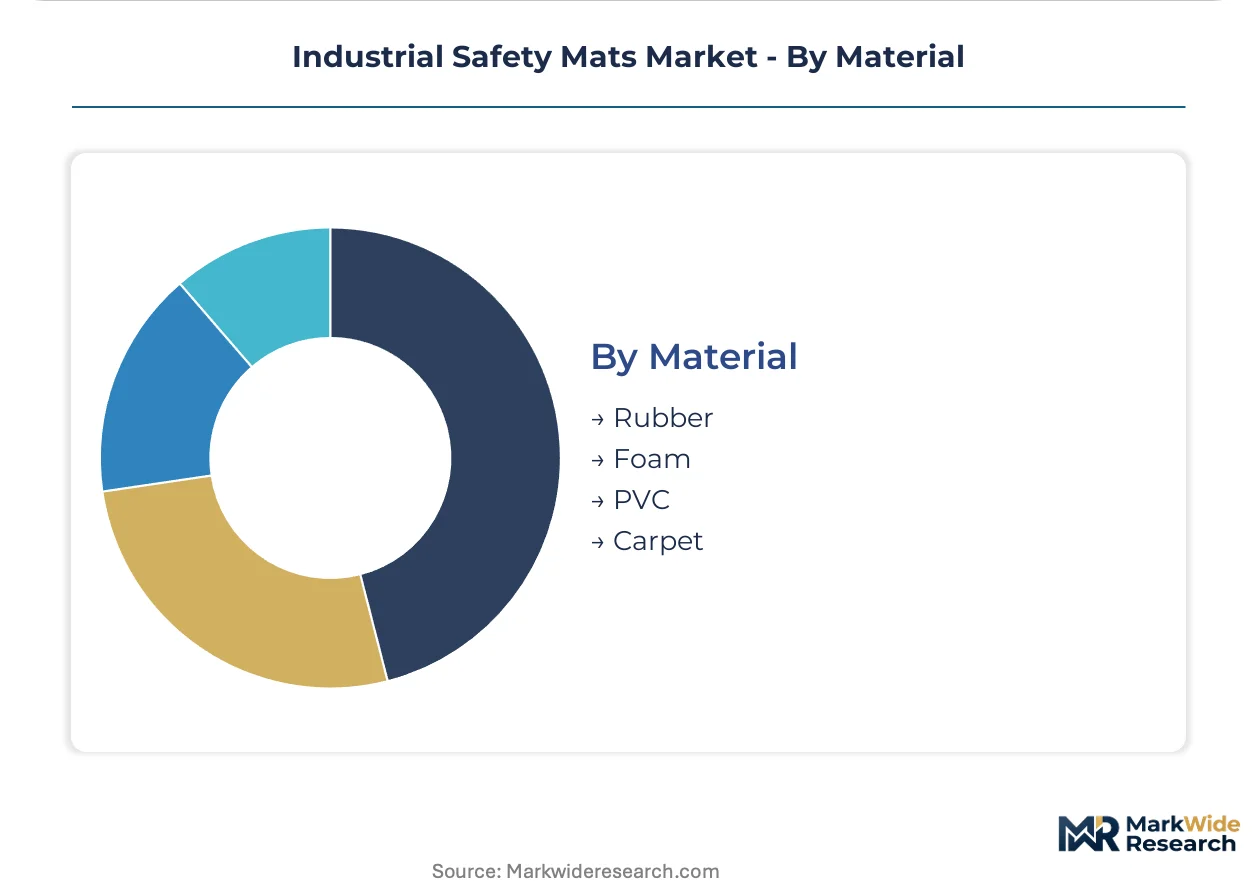
- Rubber:Natural and synthetic elastomers dominate heavy industrial applications. REACH chemical compliance frameworks disqualify formulations containing restricted plasticizers, redirecting volume toward disclosed alternatives.
- Foam:Polyurethane and closed-cell formulations for ergonomic density tuning. Anti-fatigue product lines command premium positioning through occupational health claims.
- PVC:Cost-effective extrusion for light-duty commercial environments. European buyers are shifting toward thermoplastic elastomer alternatives with full material documentation.
- Carpet:Needle-pile and berber constructions for office-industrial hybrid spaces with aesthetic requirements.
Rubber absorbs the bulk of installed capacity; foam is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian latex processing infrastructure anchors raw material supply for rubber-based formulations, while finished mat demand concentrates in industrialized manufacturing clusters across Germany, the United States, China, and India.
United States
Automotive assembly plants and e-commerce fulfillment networks drive specification upgrades for anti-fatigue and slip-resistant matting. OSHA General Industry Standards enforcement escalates inspection frequency and penalty structures, compelling systematic replacement of legacy floor coverings. Detroit-area automotive OEMs mandate EN 13845-tested surface profiles through supplier quality agreements.
Germany
Industrial automation density in automotive and precision engineering clusters creates demand for specialized static-dissipative and ergonomic cushioning solutions. EU Machinery Directive updates mandate documented slip resistance coefficients for all powered equipment operating zones. Bavarian automotive suppliers push these requirements upstream through quality agreements with tier-one matting vendors.
China
Semiconductor fabrication facilities and electronics assembly plants specify conductive carbon nanotube formulations for cleanroom applications. GB standards and MIIT industrial safety protocols tighten certification requirements for electrical insulation matting. Yangtze River Delta manufacturing hubs drive volume procurement of chemical-resistant and anti-fatigue substrates.
India
Greenfield electronics and automotive assembly plants under the PLI scheme create first-mover positioning opportunities for suppliers establishing local infrastructure. BIS approval requirements and CEA electrical safety mandates constrain market access for non-compliant imports. Gujarat and Maharashtra industrial corridors concentrate demand for workstation comfort and hazard protection matting.
Japan
Precision engineering and aerospace component manufacturers specify advanced static-dissipative formulations for explosive atmosphere applications. METI industrial safety guidelines and JIS standards enforce rigorous material disclosure and performance documentation. Nagoya-area automotive clusters drive premium adoption of sensor-embedded smart matting prototypes.
Industrial Safety Mats Market Competitive Landscape
Portfolio diversification dominates the current landscape as established players extend from core substrates into adjacent ergonomic and electrical insulation segments. The vendor base separates into three tiers: diversified materials conglomerates with broad industrial portfolios, specialized matting manufacturers with regional fabrication depth, and emerging smart-surface technology developers. Strategic partnerships between compounders and industrial IoT platforms are accelerating, while backward integration into captive rubber processing capabilities is reshaping cost structures for volume leaders.
Among diversified materials specialists, 3M Company exemplifies the conglomerate archetype leveraging cross-divisional materials science capabilities. Wearwell LLC and COBA Europe Ltd occupy positions within the specialized manufacturer tier, with geographic naming conventions suggesting US and European operational bases respectively. These three anchors illustrate the competitive spectrum from integrated materials portfolios to focused regional fabrication expertise.
| Leading Market Players |
|---|
| 3M Company |
| Wearwell LLC |
| Notrax |
| Cintas Corporation |
| Crown Matting Technologies |
| COBA Europe Ltd |
| Apache Mills |
| M+A Matting |
| Bergo Flooring |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between IEC 61111-validated electrical insulation mats and uncertified commodity rubber matting manifests in parallel supply chain configurations: premium tiers require captive compounder relationships and third-party testing infrastructure, while commodity flows route through distributor networks with minimal technical documentation.
Pricing Analysis
Warranty and replacement-schedule bundling separates premium anti-fatigue and electrical insulation offerings from unbundled commodity roll matting. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, foam density specifications, and static-dissipative additive loadings. Cost compression in natural rubber formulations is intensifying because Southeast Asian latex supply disruptions feed through to compounder margins. E-commerce fulfillment networks and automotive OEMs show lowest price sensitivity due to compliance mandates, while construction site procurement exhibits highest sensitivity with purely transactional purchasing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive clusters and US e-commerce fulfillment networks, while distributor-centric models serve fragmented construction and light manufacturing segments. Raw material supply concentrates in Thailand, Indonesia, and Malaysia for natural latex processing, with synthetic rubber feedstocks anchored in South Korea and Japan. Finished mat fabrication depends on vulcanization equipment and dielectric testing capabilities concentrated in Germany, China, and the United States. Single-source vulnerability in carbon black and conductive additive supply creates exposure to petrochemical price cycles. Distribution runs through specialized industrial safety distributors in Europe and North America, with direct manufacturer relationships displacing intermediaries in food processing and pharmaceutical verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compounders with captive testing infrastructure and multi-jurisdiction certification portfolios, as REACH disclosure requirements and IEC 61111 validation timelines force subscale players into exit or acquisition.
For Market Incumbents: Cement market position by acquiring distressed compounders in Southeast Asia to secure latex supply and vulcanization capacity, while investing in parallel BIS and CE marking infrastructure to preempt competitor geographic expansion. Modular flooring systems and poured epoxy surfaces pose substitution threats requiring defensive R&D in sensor-embedded smart matting prototypes. For New Entrants and Emerging Players: Capture white-space opportunity in India's Gujarat and Maharashtra industrial corridors by establishing local BIS-approved testing facilities ahead of PLI scheme manufacturing ramp. Greenfield electronics assembly plants offer first-mover positioning through direct procurement relationships with vendor-managed replenishment models, bypassing established distributor networks. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier European compounders possessing REACH-compliant material disclosure and EPD documentation given EU Green Deal procurement criteria weighting. Long-term viability favors suppliers with circular material flows and recycled content capabilities. Monitor BIS approval timelines and CEA electrical safety mandate enforcement as inflection signals for India market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Latex Processing | Captive rubber supply insulates margin pools from Southeast Asian climate volatility and trade disruptions. |
| Multi-Jurisdiction Certification Investment | Parallel OSHA, CE marking, and BIS approvals compress competitor geographic expansion timelines. |
| Sensor-Embedded Smart Matting Development | Pressure-sensing IoT convergence opens subscription revenue models with Japanese automotive OEMs. |
| EPD and Circular Material Documentation | EU Green Deal tender weighting advantages suppliers with verified recycled content and carbon footprint metrics. |
| Local Testing Infrastructure in India | Gujarat and Maharashtra facility placement captures PLI scheme greenfield demand before incumbent distributor lock-in. |
Research Methodology
Document review covered customs and trade flow databases, SEC and annual report filings from industrial materials conglomerates, and OSHA enforcement action records, complemented by interviews with plant engineers at German automotive OEMs, procurement directors at US e-commerce fulfillment networks, compounder technical leads in Southeast Asia, and industrial safety distributors across Europe. Secondary validation drew from IEC standards documentation, REACH substance restriction updates, and EU Machinery Directive implementation guidance. Bottom-up volume modeling and top-down value triangulation were cross-referenced against installation data from manufacturing facility expansion announcements.
Historical shipment patterns were cross-referenced against panel input from procurement officers and maintenance directors to establish baseline demand curves across the projection horizon. Segmentation modeling captured substrate type, end-use facility category, hazard classification application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and substitution threat assessments, with specific inputs from automation density indices in precision engineering clusters and ergonomic mandate enforcement intensity by OSHA region.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural rubber price volatility, REACH substance restriction expansions, and modular flooring substitution rates. Forecasts reflect documented assumptions on compliance timeline adherence and PLI scheme manufacturing ramp schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Machine Safety Market
Workplace Safety
Safety Vest Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Industrial Safety Market