
 Industrial Head Protection Market | 2026-2036
Industrial Head Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Head Protection Market Analysis
The EU Green Deal is repositioning procurement criteria across European industrial supply chains, compelling buyers to prioritize headgear with recycled content and lower carbon footprints. MSA Safety leverages its testing infrastructure to certify helmets against evolving environmental benchmarks. Honeywell anchors North American distribution through direct relationships with energy sector contractors. 3M differentiates via integrated eyewear-helmet systems that reduce SKU complexity for large construction fleets.
Industrial head protection comprises engineered helmets, caps, and accessories designed to absorb impact energy and deflect penetrating objects during workplace incidents. Most safety helmets incorporate polycarbonate or ABS shells with six-point suspension systems that distribute force across at least 450 square millimeters of cranial surface area, meeting ANSI Z89.1 or EN 397 shock-attenuation thresholds. Hard hats retain dominant volume share across construction and mining deployments where top-impact hazards predominate, while safety helmets with integrated chin straps and electrical insulation capture expanding share in utilities and oil & gas environments where workers face lateral impacts and arc-flash exposure. Accessories including visors, earmuffs, and cooling liners represent a concentrated margin pool as attach rates rise with helmet replacement cycles.
OSHA's General Industry Standard 1910.135 mandates head protection where falling object or electrical hazards exist, while ANSI Z89.1 and EN 397 define impact resistance and penetration test protocols that manufacturers must satisfy for market access. ISO 3873 provides international baseline specifications that facilitate cross-border certification, though national regulators including Germany's KBA-affiliated testing labs and France's ANSM-linked occupational health bodies impose supplementary validation requirements. Buyers should monitor convergence between sustainability disclosure rules and material certification standards, as forthcoming regulatory packages will likely embed carbon accounting into PPE qualification criteria.
Market Dynamics
The EU Green Deal's sustainable procurement mandates are compressing supplier qualification timelines as buyers demand carbon-accounted headgear with recycled shell materials and documented supply chain emissions.
Growth Catalysts
- OSHA enforcement escalation:Site inspections across US construction corridors are elevating replacement rates for non-compliant legacy hard hats, particularly in Texas and Florida energy infrastructure projects.
- India's factory safety crackdown:State-level labor departments in Maharashtra and Tamil Nadu are mandating chin-strap helmets in manufacturing zones, displacing basic cap-style protection.
- Polycarbonate shell advances:High-impact thermoforming processes now enable thinner, lighter shells that retain ANSI Z89.1 penetration resistance, reducing worker fatigue during extended wear cycles.
Market Restraints
- ABS resin supply concentration:Shell production depends on petrochemical feedstocks concentrated in Gulf Coast and Northeast Asian refining clusters, exposing margins to olefins volatility.
- Electrical insulation testing bottlenecks:Third-party arc-flash certification queues at KBA-affiliated German labs extend lead times by eight to twelve weeks for Class E helmet launches.
- Reusable exoskeleton substitutes:Powered upper-body systems for overhead work in automotive assembly are reducing top-impact exposure hours where helmets previously dominated.
Strategic Opportunities
- Vietnam's industrial corridor expansion:Northern provinces around Hai Phong and Bac Ninh are attracting electronics manufacturing investments with underdeveloped PPE enforcement, creating first-mover positioning for certified helmet suppliers.
- Smart PPE convergence:Integration of near-field communication tags and impact sensors into suspension systems enables usage-tracking contracts for large construction fleet operators.
- E-commerce procurement channels:Direct-to-site distribution platforms are disintermediating traditional safety distributor networks for mid-sized contractors in Australia's mining services sector.
Industry Challenges
- Suspension system engineering talent scarcity:Six-point force-distribution design expertise resides with a narrow cohort of occupational biomechanics specialists, constraining R&D throughput for new entrants.
- Dual certification complexity:Simultaneous ANSI Z89.1 and EN 397 testing protocols require redundant sample production and divergent documentation systems, extending product launch timelines.
- Legacy inventory integration:Construction fleet operators with mixed helmet generations face compatibility gaps between accessory mounting systems, complicating standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Head Protection Market |
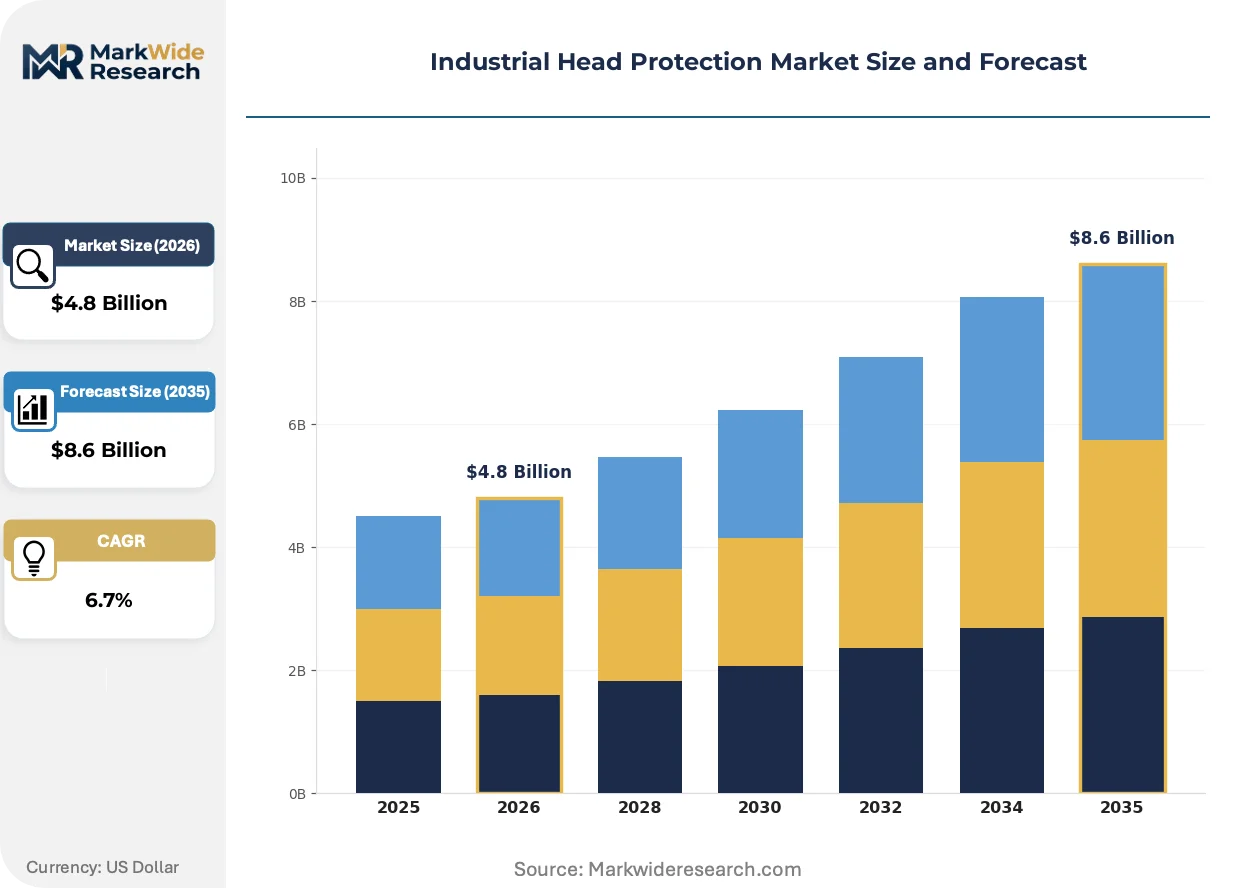
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Hats, Bump Caps, Safety Helmets, Accessories End User: Construction, Manufacturing, Oil & Gas, Mining Material: Polycarbonate, ABS, Fiberglass, Metal Standard Compliance: ANSI, ISO, OSHA, EN |
| Companies Covered | UVEX, JSP, MSA Safety, Portwest, Bullard, 3M, Delta Plus Group, Drägerwerk, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Head Protection Market Emerging Trajectories
Sensor-enabled headgear and bio-based shell materials are converging to transform industrial head protection from passive equipment into connected safety infrastructure with measurable risk-reduction outcomes.
Embedded accelerometer arrays are integrating into six-point suspension systems to detect and log impact events for incident reconstruction and predictive maintenance scheduling. Mining operators in Western Australia's Pilbara region are deploying these units at scale to correlate helmet impact data with ground control failure patterns. The technology is integrating safety management systems with real-time worker exposure analytics, compressing incident response windows from hours to minutes.
REACH substance restriction updates are phasing out certain flame-retardant additives in polycarbonate formulations, compelling reformulation of electrical-rated helmet lines. German industrial buyers are advancing procurement specifications that anticipate these chemical compliance deadlines by eighteen to twenty-four months. Shell manufacturers with in-house polymer compounding capabilities are capturing preference by certifying alternatives ahead of mandatory transition dates.
Consolidated fleet procurement is displacing project-by-project safety equipment purchasing among North American general contractors with recurring infrastructure maintenance obligations. Long-term helmet supply agreements now bundle replacement scheduling, accessory standardization, and training delivery into single-source contracts. This pattern is most visible in transmission line maintenance operations across the US Midwest, where utility-scale contractors are reducing vendor counts from twelve to three.
Industrial Head Protection Market Segmentation
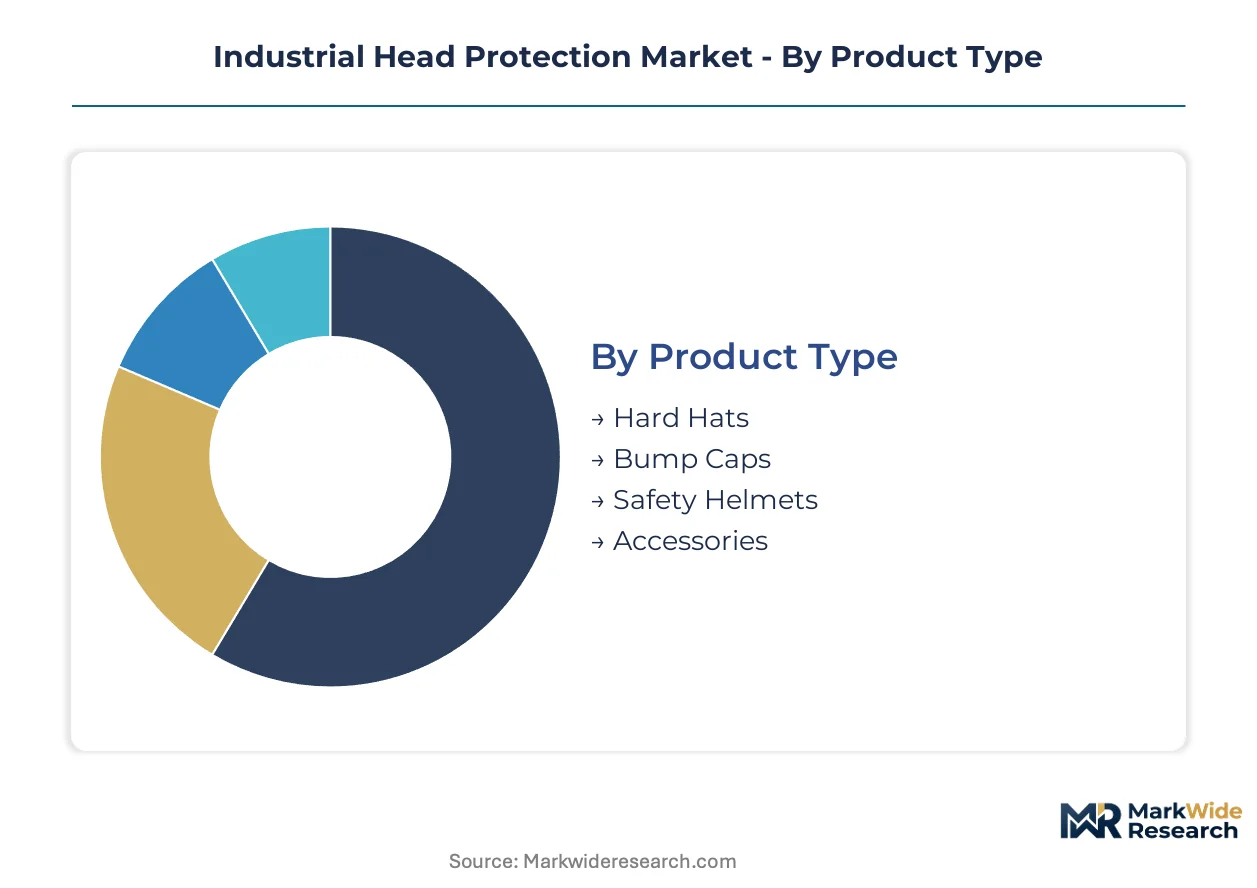
Segmentation in industrial head protection reveals how capital deployment, regulatory exposure, and material science converge to create distinct competitive arenas. Buyers optimize procurement by matching helmet specifications to hazard profiles rather than defaulting to universal protection tiers.
Product Type:
Capital intensity varies sharply across product categories, with integrated safety helmets demanding polymer compounding and electrical testing infrastructure that hard hat assemblers can bypass.
- Hard Hats:Injection-molded ABS or HDPE shells with basic suspension systems dominate construction site procurement in volume terms. Texas and Florida energy infrastructure projects are elevating replacement rates as OSHA enforcement escalates for non-compliant legacy units.
- Safety Helmets:Chin-strap designs with integrated electrical insulation and accessory mounting interfaces require six-point suspension engineering and arc-flash certification. State-level labor departments in Maharashtra and Tamil Nadu are mandating these units in manufacturing zones, displacing basic cap-style protection.
- Bump Caps:Lightweight polyethylene shells protect against stationary overhead hazards in warehousing and automotive assembly. These units absorb minimal R&D investment but face substitution risk from powered exoskeleton systems in overhead work environments.
- Accessories:Visors, earmuffs, and cooling liners attach to helmet mounting systems and concentrate margins through recurring replacement cycles. Attach rates rise with fleet standardization efforts among large contractors.
Hard hats absorb the bulk of installed capacity across construction and mining deployments; safety helmets are expanding most quickly as electrical hazard protection mandates proliferate.
End User:
Application-specific hazard profiles drive divergent procurement specifications, with oil and gas operators paying premiums for arc-flash rated units while construction buyers prioritize cost-efficient volume deployment.
- Construction:General contractors across US Midwest transmission line maintenance operations are consolidating fleet procurement into long-term supply agreements bundling replacement scheduling and training delivery.
- Manufacturing:Factory safety enforcement in India's manufacturing corridors is tightening, with underdeveloped PPE enforcement in Vietnam's northern provinces around Hai Phong and Bac Ninh creating first-mover positioning for certified suppliers.
- Oil & Gas:Lateral impact and arc-flash exposure in utilities and energy environments demands Class E electrical insulation and integrated chin straps. Third-party certification queues at KBA-affiliated German labs extend lead times by eight to twelve weeks for new launches.
- Mining:Western Australia's Pilbara region operators are deploying sensor-enabled headgear at scale to correlate helmet impact data with ground control failure patterns, compressing incident response windows.
Construction absorbs the bulk of procurement volume through fleet standardization; mining is gaining share fastest through connected safety infrastructure deployment.
Material:
Polymer chemistry capabilities determine supplier positioning, with in-house compounding operations capturing preference as REACH substance restrictions phase out legacy flame-retardant additives.
- Polycarbonate:High-impact thermoforming enables thinner, lighter shells that retain ANSI Z89.1 penetration resistance while reducing worker fatigue during extended wear cycles.
- ABS:Petrochemical feedstock dependence on Gulf Coast and Northeast Asian refining clusters exposes margins to olefins volatility, constraining pricing flexibility for shell producers.
- Fiberglass:Composite reinforcement delivers superior heat resistance for foundry and smelting applications where thermoplastic deformation risks predominate.
- Metal:Aluminum and steel shells persist in specialty welding and high-temperature environments where spark resistance overrides weight considerations.
Polycarbonate commands the steepest expansion trajectory through weight reduction advances; ABS retains dominant volume share despite feedstock exposure.
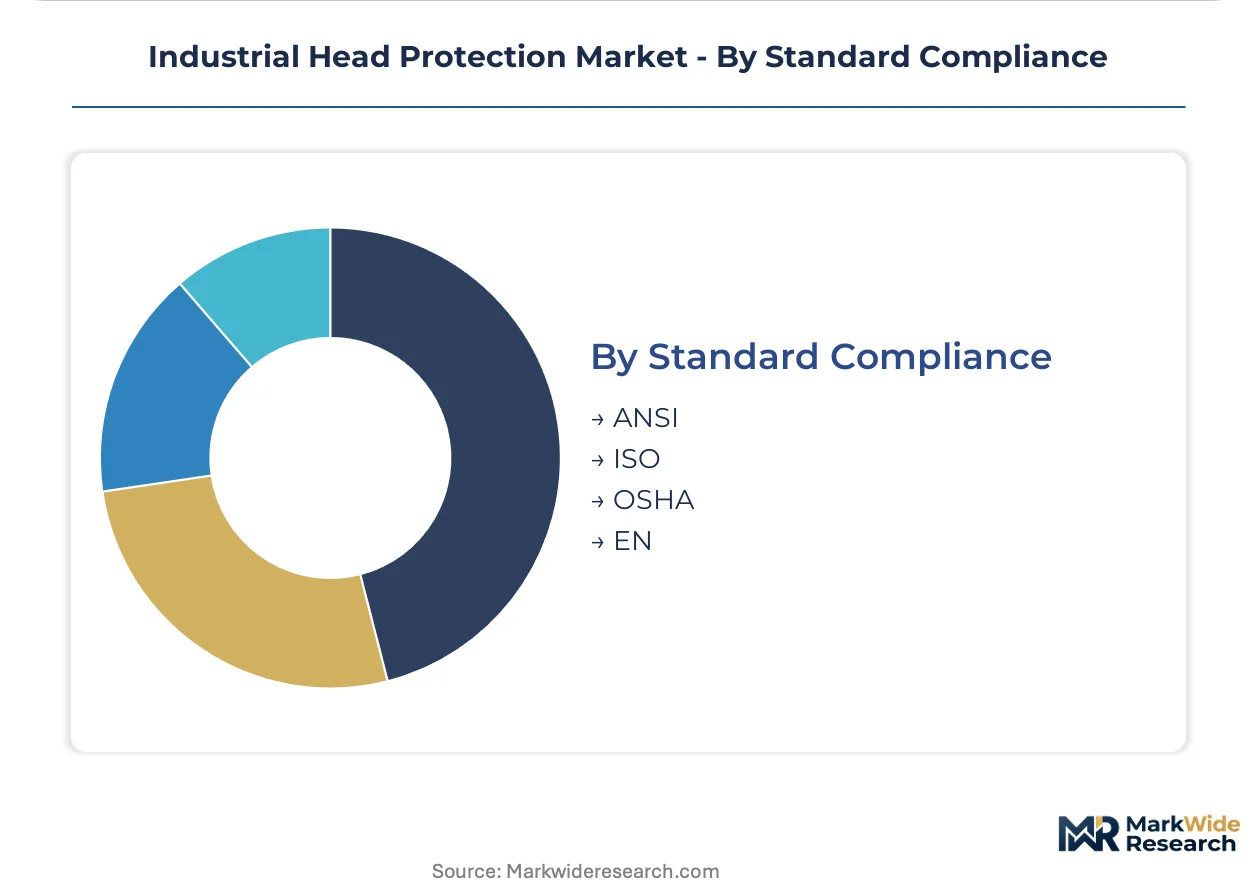
Standard Compliance:
Dual certification requirements fragment supplier economics, with simultaneous ANSI Z89.1 and EN 397 testing protocols demanding redundant sample production and divergent documentation systems.
- ANSI:US-focused impact resistance and penetration test protocols govern North American market access, with Type I top-impact and Type II lateral-impact classifications segmenting construction from utility applications.
- ISO:ISO 3873 baseline specifications facilitate cross-border certification, though national regulators impose supplementary validation requirements that complicate harmonized procurement.
- OSHA:General Industry Standard 1910.135 mandates head protection where falling object or electrical hazards exist, with enforcement escalation driving replacement demand across non-compliant legacy inventories.
- EN:EN 397 shock-attenuation thresholds and forthcoming sustainability disclosure convergence will embed carbon accounting into PPE qualification criteria under EU Green Deal procurement mandates.
ANSI and EN together absorb the bulk of certification investment; ISO is climbing fastest as emerging market regulators adopt international baselines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hai Phong anchors procurement expansion across Southeast Asia's manufacturing corridors, where electronics assembly investments are outpacing established PPE enforcement frameworks.
United States
Texas and Florida energy infrastructure projects are elevating hard hat replacement rates as OSHA escalates site inspections for non-compliant legacy units. OSHA's General Industry Standard 1910.135 mandates head protection where falling object hazards exist. Midwest transmission line maintenance operations are consolidating fleet procurement into long-term supply agreements bundling replacement scheduling and training delivery.
Germany
KBA-affiliated testing labs are extending arc-flash certification queues by eight to twelve weeks for Class E helmet launches, constraining new product timelines. REACH substance restriction updates are phasing out certain flame-retardant additives in polycarbonate formulations, compelling reformulation of electrical-rated helmet lines. German industrial buyers are advancing procurement specifications that anticipate chemical compliance deadlines by eighteen to twenty-four months.
India
Maharashtra and Tamil Nadu state labor departments are mandating chin-strap helmets in manufacturing zones, displacing basic cap-style protection. Factory safety enforcement is tightening across India's manufacturing corridors as domestic production scales. Underdeveloped PPE enforcement in Vietnam's northern provinces around Bac Ninh is creating first-mover positioning for certified helmet suppliers.
Australia
Western Australia's Pilbara region mining operators are deploying sensor-enabled headgear at scale to correlate helmet impact data with ground control failure patterns. E-commerce procurement channels are disintermediating traditional safety distributor networks for mid-sized contractors in Australia's mining services sector. Direct-to-site distribution platforms are capturing share from legacy supply relationships.
United Arab Emirates
Construction procurement across Gulf infrastructure projects is prioritizing carbon-accounted headgear with documented supply chain emissions. EU Green Deal procurement mandates are filtering into specifications for projects with European contractor involvement. Dubai and Abu Dhabi project clusters are driving volume concentration for premium-tier electrical-rated helmets.
Industrial Head Protection Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification infrastructure and polymer compounding capabilities. The vendor base organizes into three tiers: integrated safety conglomerates with in-house testing labs, regional specialists focused on single-standard markets, and contract assemblers dependent on outsourced shell supply. Dominant competitive moves include strategic partnerships with polymer compounders to secure flame-retardant formulation alternatives, and geographic expansion into Vietnam's underenforced northern provinces.
Within the integrated conglomerate tier, MSA Safety and Honeywell exemplify archetypes distinguished by testing infrastructure depth and distribution channel control. 3M occupies a position representing integrated eyewear-helmet system design. Among European specialists, UVEX and JSP sit within the premium-standard tier anchored by regional certification expertise. Portwest and Bullard represent scale-driven fabricators with construction-sector concentration.
| Leading Market Players |
|---|
| UVEX |
| JSP |
| MSA Safety |
| Portwest |
| Bullard |
| 3M |
| Delta Plus Group |
| Drägerwerk |
| Honeywell |
| Others |
Supply Flow & Price Mechanics
EU Green Deal sustainable procurement mandates gate both qualified supply and premium-tier pricing access, compressing supplier qualification timelines as buyers demand carbon-accounted headgear with recycled shell materials and documented supply chain emissions. Buyers with European contractor involvement now face bifurcated sourcing: certified suppliers command sustained premiums while uncertified competitors absorb margin compression.
Pricing Analysis
Outcome-based fleet contracts anchor pricing structures across large construction and mining operators, bundling helmet replacement scheduling with training delivery and accessory standardization into multi-year agreements. Three-tier pricing structure across premium, standard, and economy levels separates arc-flash certified Class E helmets from basic ANSI Type I hard hats and uncertified commodity units. Price differentiation hinges on certification infrastructure ownership and polymer compounding capabilities, with in-house flame-retardant formulation commanding premiums as REACH restrictions phase out legacy additives. Cost compression in economy-tier ABS hard hats is intensifying because petrochemical feedstock volatility exposes assemblers to olefins price swings. Small contractors in Vietnam's northern provinces exhibit highest price sensitivity; utility-scale transmission line operators in the US Midwest demonstrate lowest sensitivity due to bundled procurement contracts.
Supply Chain Analysis
Workforce-availability constraints in polymer compounding and six-point suspension engineering concentrate manufacturing capacity in Germany, China, and the United States. Shell production draws from polycarbonate and ABS resin feedstocks anchored in Gulf Coast and Northeast Asian refining clusters, while suspension system components source from specialty textile and elastomer suppliers. Single-source vulnerability in arc-flash certification infrastructure—particularly KBA-affiliated German labs—extends lead times and constrains new product launches. Distribution runs through direct-to-site e-commerce platforms disintermediating traditional safety distributors, alongside legacy industrial supply houses serving fleet procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story where suspension system engineering talent scarcity props pricing for certified helmet tiers and constrains R&D throughput for new entrants.
For Market Incumbents: Acquire testing infrastructure and certification queue priority to defend against emerging sensor-enabled PPE specialists. Secure backward integration into polymer compounding to capture preference as REACH substance restrictions compel flame-retardant reformulation. Consolidate distribution relationships with utility-scale contractors in the US Midwest to lock in long-term fleet procurement contracts before e-commerce platforms erode channel control. For New Entrants and Emerging Players: Begin with Vietnam's northern provinces around Hai Phong and Bac Ninh, where electronics manufacturing investments outpace established PPE enforcement and certified suppliers remain scarce. Target mid-sized mining services contractors in Western Australia's Pilbara region with sensor-enabled headgear integrating impact logging and ground control analytics. Pursue direct-to-site distribution partnerships to bypass entrenched safety distributor networks. For Investors and Strategic Acquirers: KBA-affiliated lab queue extensions exceeding eight weeks is the leading indicator that certification infrastructure scarcity will concentrate margins among integrated testing-owning suppliers. Five-to-ten year viability favors conglomerates with captive polymer compounding and multi-standard certification capabilities. Watch for REACH substance restriction enforcement acceleration as the inflection signal prompting acquisition premiums for early reformulation certifiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH restriction compliance ahead of mandatory deadlines secures German industrial buyer preference. |
| Sensor-Enabled PPE Platform Launch | Pilbara mining operators deploy impact-logging helmets to compress incident response windows. |
| Direct-to-Site E-Commerce Expansion | Australian mining services mid-sized contractors bypass legacy safety distributor markups. |
| Multi-Standard Certification Investment | Simultaneous ANSI Z89.1 and EN 397 testing reduces redundant sample production burdens. |
| Vietnam Northern Corridor Market Entry | Hai Phong and Bac Ninh electronics manufacturing investments precede enforcement maturation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with plant safety managers, procurement leads at general contractors, distribution channel partners, and occupational biomechanics specialists with validation against OSHA enforcement databases, EU Green Deal procurement specifications, and BIS factory inspection reports. Bottom-up volume modeling across product type, end user, material, and standard compliance segments triangulated against top-down macroeconomic indicators.
Granularity-level modeling distinguished hard hat, safety helmet, bump cap, and accessory categories by construction, manufacturing, oil and gas, and mining end users across polycarbonate, ABS, fiberglass, and metal material inputs, with ANSI, EN, ISO, and OSHA compliance tiers mapped to regional regulatory clusters. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions incorporating certification premium persistence and raw material cost pass-through elasticity.
Underlying measurement precision varies by segment; sensor-enabled and electrical-rated helmet categories carry tighter precision than commodity hard hat volumes due to concentrated supplier bases and disclosed fleet contract values. Forecasts reflect assumptions regarding OSHA enforcement escalation persistence, REACH substance restriction implementation timelines, and Vietnam industrial corridor enforcement maturation rates. Material deviation in olefins pricing volatility, arc-flash certification queue durations, or EU Green Deal procurement mandate adoption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Machine Safety Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Safety Vest Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Industrial Eye Protection Market