
 Safety Glasses Market | 2026-2036
Safety Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Glasses Market Outlook
Prescription safety lens subscription programs is expanding as employers shift from one-time bulk purchases to managed vision plans that cover periodic replacements and compliance tracking. 3M Company leverages its integrated distribution network to bundle protective eyewear with respiratory and hearing products across industrial accounts. Honeywell International anchors its position through in-house optical lab capabilities that reduce fulfillment times for custom prescription orders. Uvex Safety Group competes on European certification density, maintaining parallel EN 166, EN 170, and EN 172 approvals that simplify cross-border procurement for multinational manufacturers.
Safety glasses are impact-rated optical devices constructed from polycarbonate, Trivex, or chemically tempered glass, engineered to withstand high-velocity particle strikes and filter ultraviolet or infrared radiation per ANSI Z87.1 or EN 166 standards; their primary purpose is preventing occupational eye trauma in environments involving flying debris, chemical splash, or optical radiation exposure. Impact resistant glasses command the largest volume share due to universal applicability across construction and manufacturing sites, while anti-fog glasses represent the fastest-expanding category as climate-controlled indoor environments and physically demanding outdoor tasks alike generate persistent condensation challenges. Lens coating segmentation reveals scratch-resistant treatments as the baseline expectation, with anti-reflective coatings gaining share among technicians operating under artificial lighting for extended shifts.
OSHA mandates in the United States, EN 166 framework enforcement through EU member state labor inspectorates, and Japan's Industrial Safety and Health Law collectively establish minimum impact resistance, optical clarity, and coverage area requirements that disqualify uncertified imports and drive periodic replacement cycles. China's SAMR oversees GB 14866 standard compliance for domestic production and import clearance, tightening market access for manufacturers lacking in-country testing partnerships. Stakeholders must monitor evolving blue-light filtering claims and prescription integration requirements as digital manufacturing interfaces and aging workforces reshape product specification priorities.
Market Dynamics
Prescription integration into industrial eyewear programs is compressing traditional distribution layers, as employers seek consolidated vendors capable of delivering certified protection alongside vision correction without multiple supplier relationships.
Growth Catalysts
- OSHA Eye and Face Protection Standards:Updated impact resistance mandates in the United States are compelling manufacturing employers to retire non-compliant basic spectacles and procure certified high-impact models with documented traceability.
- Polycarbonate lens chemistry:Advances in optical-grade polymer formulations are reducing unit weight while maintaining ballistic-rated performance, accelerating adoption among workers in extended-wear environments.
- China factory automation:State-led industrial safety campaigns and expanding robotic assembly lines are driving volume procurement through domestic supply chains as facility managers standardize protective equipment.
Market Restraints
- Optical-grade resin supply concentration:Polycarbonate pellet production clusters in East Asian petrochemical corridors expose lens fabricators to feedstock price volatility and shipping disruptions.
- Prescription fulfillment complexity:Custom optical labs require capital-intensive surfacing equipment and certified optician staffing, creating bottlenecks for industrial accounts with dispersed workforces.
- Uncertified import displacement:Low-cost uncertified eyewear from unregulated producers continues to capture price-sensitive segments despite disqualification under ANSI Z87.1 and EN 166 frameworks.
Strategic Opportunities
- India industrial corridor expansion:Manufacturing investments in Gujarat and Tamil Nadu are outpacing established safety equipment distribution networks, creating first-mover positioning for compliant suppliers.
- Anti-fog coating convergence:Integration of hydrophilic surface treatments with blue-light filtering substrates addresses dual demands from digital manufacturing interfaces and climate-controlled environments.
- Managed vision plan channel:Subscription-based replacement programs with embedded compliance tracking are displacing one-time bulk purchasing among multinational employers seeking predictable safety budgets.
Industry Challenges
- Optical metrology skill scarcity:Certified opticians capable of verifying prescription accuracy within impact-rated frames remain concentrated in urban centers, limiting rural industrial account service.
- Multi-standard certification timelines:Simultaneous pursuit of ANSI Z87.1, EN 166, and GB 14866 approvals extends product launch cycles and strains testing laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Glasses Market |
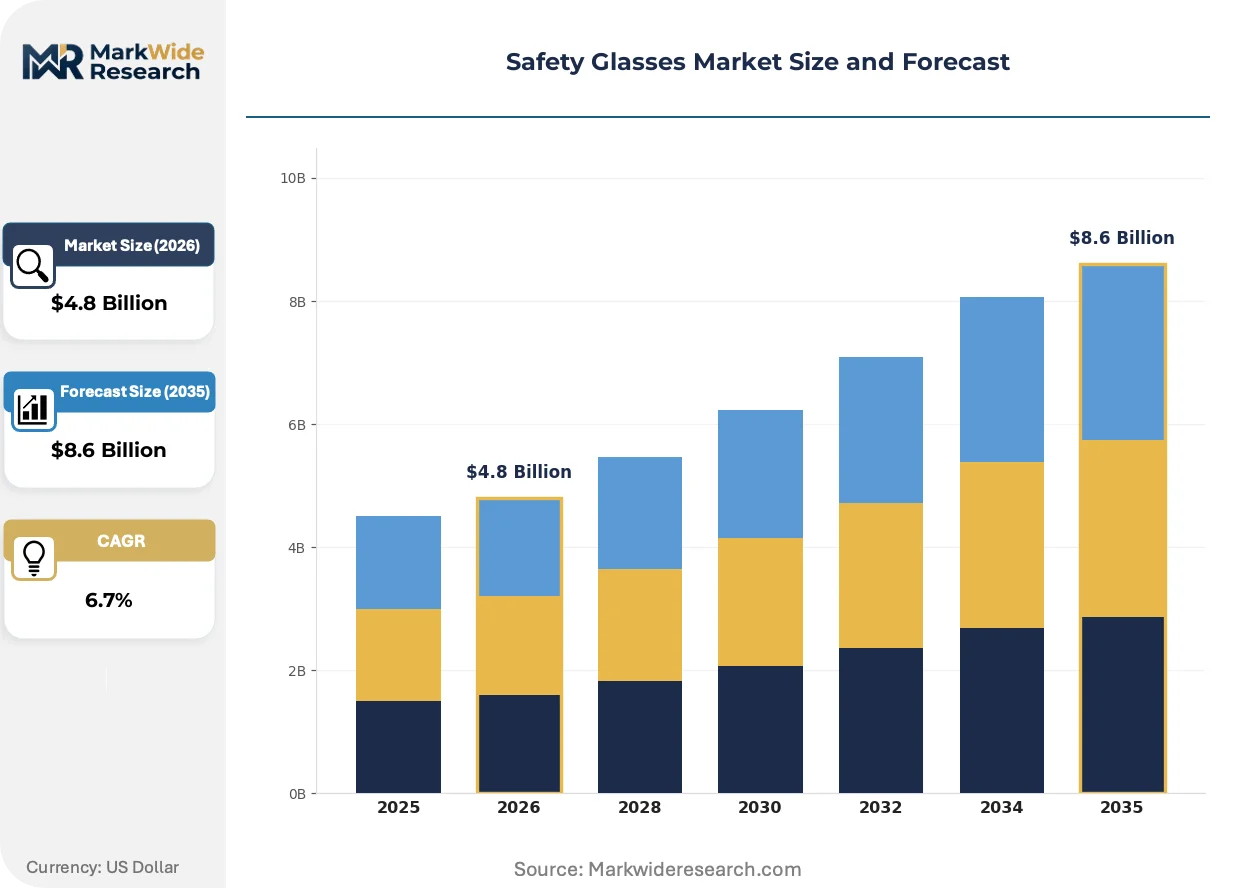
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Welding Goggles, Impact Resistant Glasses, Anti-Fog Glasses, UV Protection Glasses End User: Construction Workers, Laboratory Technicians, Medical Professionals, Manufacturing Personnel Frame Material: Polycarbonate, Metal, Nylon, Acetate Lens Coating: Scratch-Resistant, Anti-Reflective, Photochromatic, Mirror Coating |
| Companies Covered | 3M Company, Honeywell International, Uvex Safety Group, Bolle Safety, Pyramex Safety Products, Radians, Gateway Safety, MCR Safety, Edge Eyewear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Glasses Market Strategic Shifts
Smart connectivity and sensor integration are penetrating protective eyewear, while coating technologies and procurement platforms undergo parallel transformation. These developments are compressing replacement cycles and elevating performance expectations.
Photochromic lens technology is modularizing across welding and outdoor construction applications, automatically adjusting optical density in response to arc flash intensity or solar exposure. Heavy machinery operators and pipeline construction crews are adopting these units at accelerating rates. This capability is modularizing what were previously separate product lines into single-SKU inventory positions, reducing distributor carrying costs.
Japan's Industrial Safety and Health Law amendments are tightening coverage area requirements for chemical splash protection, mandating extended peripheral sealing beyond traditional spectacle designs. Pharmaceutical manufacturing and battery electrolyte handling facilities face immediate compliance deadlines. Prescription-integrated goggles with indirect ventilation systems are capturing preference in Osaka and Nagoya industrial clusters.
Employer purchasing departments are consolidating protective eyewear procurement through integrated safety suppliers capable of bundling respiratory, hearing, and vision products under unified compliance dashboards. Industrial distributors with multi-category certification expertise are displacing standalone optical specialists. This pattern concentrates most visibly in German automotive supply chains, where procurement centralization mandates favor full-service safety vendors.
Safety Glasses Market Segmentation
Protective eyewear procurement varies sharply by hazard exposure, work environment, and wearer physiology. Specification mismatches between product categories and actual workplace risks drive replacement cycles, compliance failures, and injury incidents. Understanding segment boundaries enables precise inventory positioning and customer targeting.
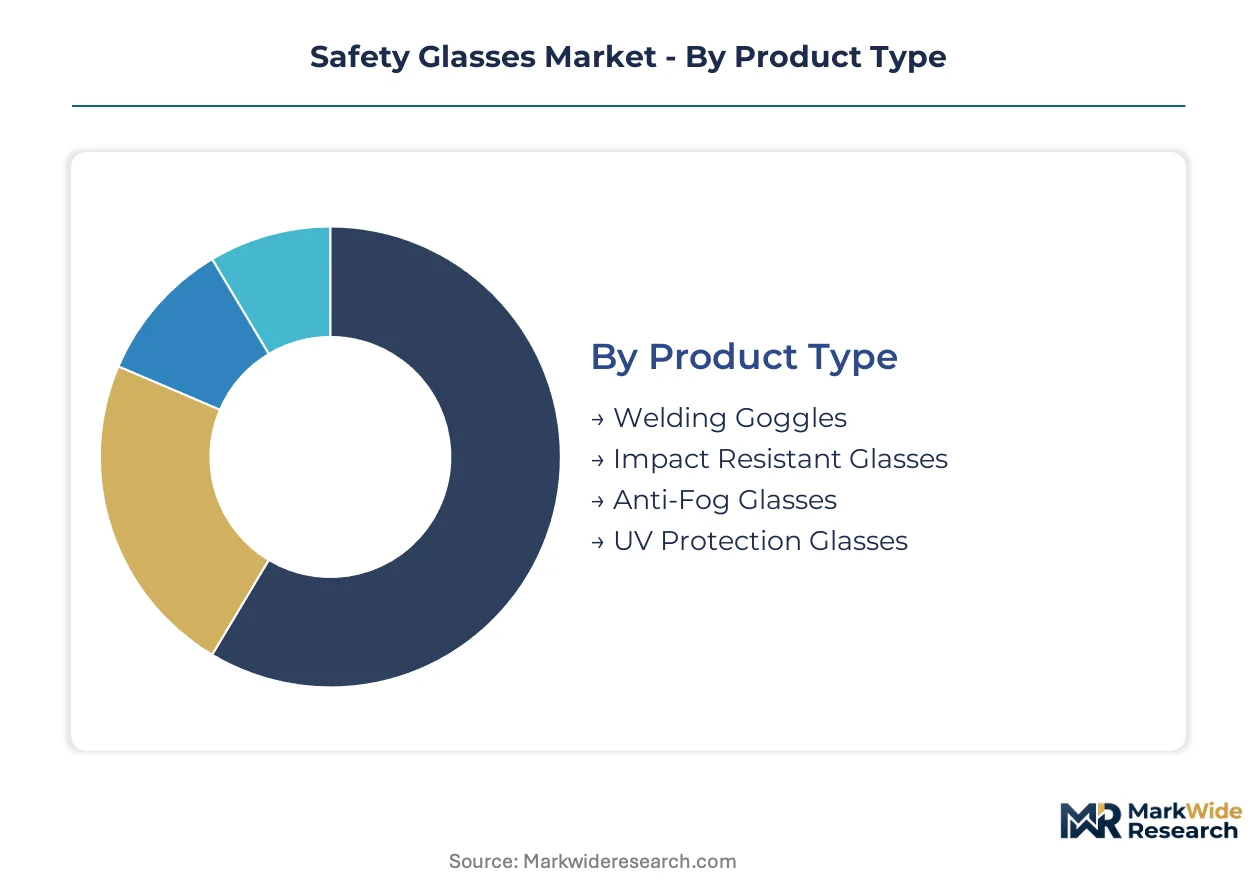
Product Type:
Impact resistance specifications and optical hazard filtration define the core technology axis across protective eyewear categories.
- Impact Resistant Glasses:Polycarbonate or Trivex lenses rated to ANSI Z87.1 high-velocity impact standards withstand projectile strikes from grinding debris and machining fragments. Construction sites and heavy machinery floors in the United States, Germany, and China account for dominant procurement volumes as OSHA, DGUV, and SAMR enforcement tightens.
- Anti-Fog Glasses:Hydrophilic surface treatments prevent condensation accumulation during temperature transitions between climate-controlled interiors and outdoor environments. Demand concentrates among logistics workers and cold-storage operators facing persistent visibility degradation that standard ventilation cannot resolve.
- Welding Goggles:Fixed or variable shade lenses filter ultraviolet and infrared radiation from arc flash exposure. Fabrication shops and pipeline construction crews require specialized optical density ratings matched to specific welding processes.
- UV Protection Glasses:Tinted or clear lenses blocking UVA and UVB radiation serve outdoor utility workers and agricultural equipment operators. Municipal road crews and forestry services in sun-intensive climates drive seasonal procurement spikes.
Impact Resistant Glasses leads on scale; Anti-Fog Glasses leads on momentum.
End User:
Occupational hazard profiles and regulatory exposure shape purchasing authority and replacement frequency across wearer categories.
- Manufacturing Personnel:Automated assembly lines and metal fabrication floors generate flying particulate hazards demanding certified high-impact protection. Industrial safety managers in automotive supply chains negotiate volume contracts with embedded prescription fulfillment.
- Construction Workers:Multi-hazard environments combining impact risks, dust exposure, and solar glare require versatile protection adaptable across task phases. Project-based procurement through general contractors creates demand lumpiness tied to contract awards.
- Laboratory Technicians:Chemical splash and optical radiation hazards in pharmaceutical and research facilities mandate sealed goggle designs with indirect ventilation. Japan's amended Industrial Safety and Health Law is accelerating replacement of basic spectacles with extended-coverage models.
- Medical Professionals:Infection control protocols and laser surgery applications drive demand for disposable and reusable protective eyewear with anti-fog and anti-reflective properties. Hospital procurement departments prioritize single-source suppliers with sterile packaging capabilities.
Manufacturing Personnel dominates volume throughput; Laboratory Technicians shows steepest specification upgrade trajectory.
Frame Material:
Weight, chemical resistance, and customization flexibility determine material selection trade-offs across industrial and healthcare applications.
- Polycarbonate:Injection-molded thermoplastic frames deliver ballistic-rated durability at minimal weight for extended-wear environments. Automotive and electronics manufacturing floors specify polycarbonate for worker comfort during 12-hour shifts.
- Nylon:Flexible, fatigue-resistant polymer withstands repeated flexing and temperature cycling. Outdoor construction crews and utility workers favor nylon for durability under physical stress and environmental exposure.
- Metal:Stainless steel and titanium alloys provide slim profiles and prescription lens stability for laboratory and medical settings where precision optics matter. Higher unit costs limit penetration in price-sensitive industrial accounts.
- Acetate:Cellulose-based thermoplastic enables rich coloration and surface finishing for fashion-conscious professional environments. Corporate safety programs with aesthetic requirements specify acetate for customer-facing technical roles.
Polycarbonate holds widest application footprint; Nylon gains fastest in outdoor and heavy-duty segments.
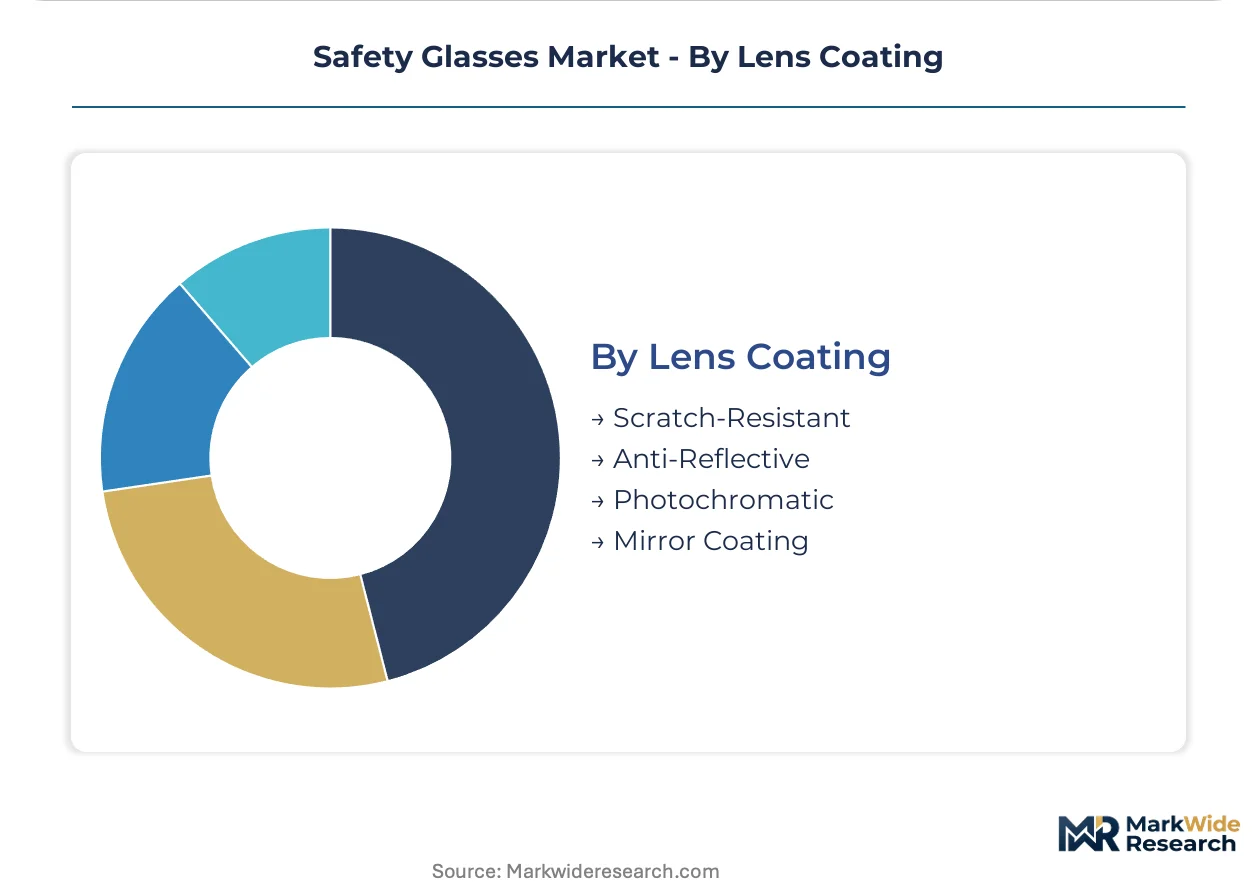
Lens Coating:
Surface treatments extend functional lifespan and optical performance under demanding wear conditions.
- Scratch-Resistant:Hardcoat treatments using silica or diamond-like carbon protect polycarbonate lenses from abrasion during cleaning and storage. Baseline expectation across all certified protective eyewear categories.
- Anti-Reflective:Multi-layer interference coatings reduce glare from artificial lighting and digital displays. Technicians operating under LED arrays and screen-intensive manufacturing interfaces specify anti-reflective treatments to reduce eye fatigue.
- Photochromatic:Silver halide or naphthopyran chemistry enables automatic darkening in response to UV intensity. Welding and outdoor construction applications benefit from single-lens solutions replacing fixed-shade inventory.
- Mirror Coating:Thin metallic oxide layers reflect intense visible light and infrared radiation. Foundry workers and glass manufacturing personnel in high-temperature environments require mirror coatings for thermal protection.
Scratch-Resistant coating commands universal adoption; Anti-Reflective treatments expand most quickly among indoor technical workforces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as lens fabricators migrate toward jurisdictions with streamlined certification pathways and concentrated feedstock access. Production clusters are consolidating where compliance costs align with proximity to optical-grade resin supply.
United States
Automotive assembly plants in Michigan and Tennessee are driving volume procurement of prescription-integrated safety eyewear. OSHA's updated impact resistance mandates are compelling employers to retire non-compliant spectacles and adopt certified high-impact models with documented traceability. Houston's petrochemical corridor is accelerating replacement cycles for chemical splash protection as facility managers standardize protective equipment.
Germany
DGUV enforcement through labor inspectorates is disqualifying uncertified imports and driving demand for EN 166-compliant high-impact models. Stuttgart's automotive supply chains are consolidating procurement through full-service safety vendors capable of bundling respiratory, hearing, and vision products. Bavarian pharmaceutical manufacturers are upgrading to extended-coverage goggles ahead of chemical splash protection deadlines.
China
State-led industrial safety campaigns and expanding robotic assembly lines are accelerating volume uptake across domestic supply chains. SAMR's oversight of GB 14866 standard compliance is tightening market access for manufacturers lacking in-country testing partnerships. Yangtze River Delta factory automation projects are standardizing protective equipment procurement as facility managers replace basic spectacles with certified models.
Japan
Amendments to the Industrial Safety and Health Law are tightening coverage area requirements for chemical splash protection beyond traditional spectacle designs. METI-aligned industrial clusters in Osaka and Nagoya are capturing preference for prescription-integrated goggles with indirect ventilation systems. Pharmaceutical manufacturing and battery electrolyte handling facilities face immediate compliance deadlines for extended peripheral sealing.
India
Manufacturing investments in Gujarat and Tamil Nadu are outpacing established safety equipment distribution networks, creating first-mover positioning for compliant suppliers. The country's national industrial safety regulator is gradually aligning workplace mandates with international impact resistance standards. Mumbai-Pune automotive corridors are standardizing protective eyewear procurement as multinational employers introduce managed vision plans with embedded compliance tracking.
Safety Glasses Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated safety suppliers capturing preference in consolidated procurement programs while standalone optical specialists retain niche prescription fulfillment roles. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with multi-category certification expertise, dedicated protective eyewear specialists with deep optical lab capabilities, and regional fabricators competing on fulfillment speed for standardized models. Competitive moves concentrate on backward integration into lens coating technologies and geographic expansion through distribution partnerships in underpenetrated industrial corridors.
Among diversified industrial conglomerates, 3M Company and Honeywell International exemplify the multi-category bundling archetype, leveraging integrated distribution networks to consolidate respiratory, hearing, and vision procurement under unified compliance dashboards. Uvex Safety Group occupies a position within the European certification specialist tier, maintaining parallel EN approvals that simplify cross-border procurement for multinational manufacturers. These three anchors illustrate how competitive positioning diverges between scale-driven platform players and certification-density specialists.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International |
| Uvex Safety Group |
| Bolle Safety |
| Pyramex Safety Products |
| Radians |
| Gateway Safety |
| MCR Safety |
| Edge Eyewear |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap lens fabricators in Germany and Japan anchor premium-tier supply, their conservative balance sheets limiting capacity expansion and sustaining pricing discipline across certified high-impact segments. Their ownership structure reinforces long-term customer relationships over volume chasing, compressing margin pressure on commodity-grade imports while preserving premium positioning for EN 166 and ANSI Z87.1 compliant models.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade safety eyewear as domestic producers scale polycarbonate injection molding. Three-tier pricing structure across premium, standard, and economy levels separates prescription-integrated custom orders from bulk industrial contracts and uncertified imports. Pricing pressure stems from feedstock volatility in East Asian petrochemical corridors. Construction contractors exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with optical-grade polycarbonate pellet production concentrated in China, South Korea, and Taiwan. Lens fabrication draws from bisphenol A feedstocks, UV stabilizer additives, and hardcoat chemical treatments. Tariff exposure on Chinese optical polymers threatens margin stability for fabricators lacking alternative sourcing. Distribution runs through industrial safety distributors with multi-category certification expertise, displacing standalone optical specialists in consolidated procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Safety Glasses Market functions as a stable compounder, with regulatory replacement cycles and prescription integration creating predictable revenue visibility. OSHA, EN 166, and GB 14866 compliance mandates ensure steady demand regardless of macroeconomic volatility.
For Market Incumbents: Extend coating technology capabilities into anti-fog and blue-light filtering substrates to capture specification upgrades from digital manufacturing interfaces. Deepen optical lab automation to reduce prescription fulfillment bottlenecks that constrain industrial account growth. Consolidate position against emerging regional fabricators in India by securing early certification partnerships with SAMR and BIS authorities. For New Entrants and Emerging Players: Capture white-space opportunity in India's Gujarat and Tamil Nadu industrial corridors where safety equipment distribution networks lag manufacturing investment. Target laboratory technician segments with extended-coverage goggles ahead of Japan's amended Industrial Safety and Health Law deadlines. Pursue managed vision plan channel partnerships as employers shift from bulk purchasing to subscription-based replacement programs. For Investors and Strategic Acquirers: Integrated safety conglomerates with respiratory and hearing product portfolios are the most active acquirers in this space, seeking prescription eyewear capabilities to complete bundled offering strategies. Acquisition targets with in-house optical surfacing equipment and multi-standard certification density offer strongest strategic fit. Watch prescription integration penetration rates in automotive supply chains as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lens Coating Technology | Captures margin from anti-fog and anti-reflective treatments demanded by climate-controlled manufacturing environments. |
| Prescription Optical Lab Automation | Reduces fulfillment times for custom safety eyewear orders from Honeywell and 3M industrial accounts. |
| Multi-Standard Certification Investment | Accelerates market access across OSHA, EN 166, and GB 14866 jurisdictions for multinational manufacturers. |
| Managed Vision Plan Channel Development | Aligns with employer shift from bulk purchasing to subscription-based replacement with embedded compliance tracking. |
| Regional Distribution Partnership in India | Establishes first-mover positioning in Gujarat and Tamil Nadu corridors outpacing established safety networks. |
Study Parameters
Multiple input streams — safety equipment procurement managers, optical lab operations directors, regulatory affairs specialists at certification bodies, and industrial distributor category managers — were reconciled against trade data from customs authorities, OSHA enforcement records, SAMR standard filings, and SEC disclosures from listed safety equipment manufacturers. Primary fieldwork with plant engineers and occupational health officers validated secondary findings. Bottom-up volume estimates triangulated against top-down market sizing from petrochemical feedstock consumption patterns.
Historical shipment data cross-referenced against expert panel assessments of prescription integration velocity and factory automation adoption curves shaped the analytical framework. Segmentation modeling spanned product type, end-user industry, lens coating technology, frame material, and regional regulatory cluster. CAGRs derived from weighted average of demand elasticity coefficients and replacement cycle frequencies. Polycarbonate resin price trajectories and labor inspectorate enforcement intensity served as industry-specific forecast inputs.
Feedstock supply disruptions, regulatory standard revision timelines, and prescription fulfillment labor shortages are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding certification harmonization progress and employer procurement centralization rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Safety Vest Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Machine Safety Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Industrial Safety Mats Market