
 US Safety Helmet Market | 2026-2036
US Safety Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
US Safety Helmet Market Intelligence
Domestic manufacturing expansion in the Southeastern US is tilting the supply chain balance for safety helmets, reducing reliance on overseas imports. Honeywell International Inc. leverages its extensive distribution network to serve large industrial accounts across the country. MSA specializes in high-performance head protection for demanding environments like mining, utilities, and firefighting. Bullard differentiates through its focus on thermal imaging integration and specialized firefighter helmet designs.
A US safety helmet is a piece of personal protective equipment designed to shield the wearer's head from impact, falling objects, and electrical shock. These devices are typically constructed from materials like High-Density Polyethylene (HDPE) or polycarbonate and must meet specific impact attenuation standards. Hard hats made from HDPE dominate the construction and manufacturing end-user segments due to their cost-effectiveness and durability. However, fiber-reinforced plastic and polycarbonate helmets are gaining share in specialized applications requiring higher impact resistance or lighter weight.
The Occupational Safety and Health Administration (OSHA) mandates the use of head protection in numerous workplace environments, creating foundational demand. Product design and performance are governed by standards from the American National Standards Institute (ANSI), specifically ANSI Z89.1. Future market development will hinge on manufacturers' ability to integrate smart technologies, like collision alerts and biometric sensors, without compromising on core safety compliance.
Market Dynamics
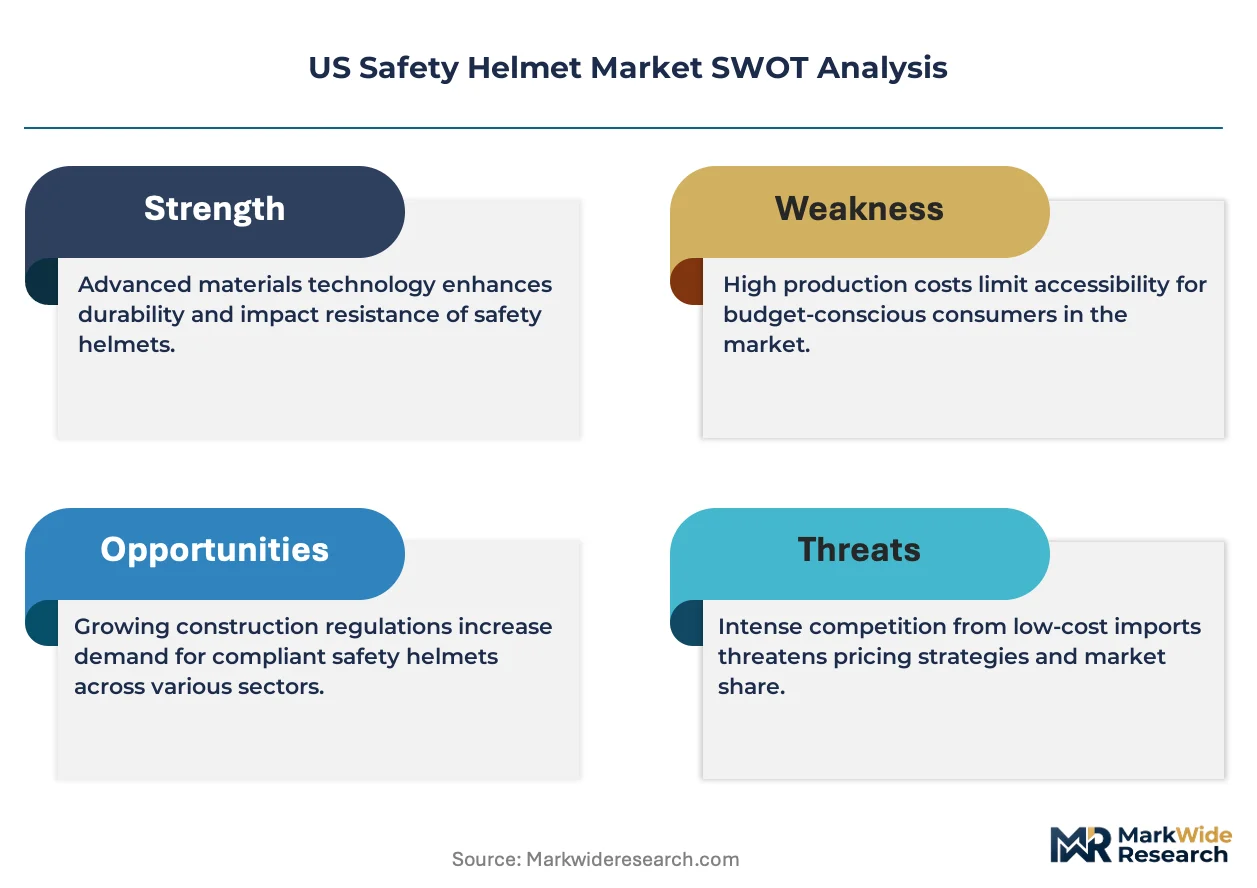
Demand for US safety helmets is concentrating around two distinct poles: high-volume, cost-sensitive procurement for general construction, and technology-rich, premium-priced systems for high-risk industrial applications. This bifurcation is driven by Occupational Safety and Health Administration (OSHA) mandates creating a universal compliance floor, while new sensor technologies create a high-performance ceiling.
Growth Catalysts
- Infrastructure Legislation:Federal and state-level infrastructure spending, particularly in Texas and Florida, directly increases the volume of workers in construction and utility maintenance, expanding the user base for mandatory head protection.
- Stringent OSHA Enforcement:The Occupational Safety and Health Administration's rigorous enforcement of head protection standards in high-hazard industries like construction and mining provides a non-discretionary, foundational source of demand.
- Sensor Miniaturization:The availability of low-cost, lightweight sensors for impact detection, proximity warnings, and biometric monitoring enables the development of smart helmets, creating a new premium product tier.
Market Restraints
- Cost Sensitivity:The higher initial purchase price of smart helmets and those made from advanced composites acts as a significant barrier for smaller contractors and businesses operating on thin margins.
- Commoditization Pressure:A persistent influx of low-cost, standard High-Density Polyethylene (HDPE) hard hats, primarily from overseas manufacturers, exerts constant downward price pressure on the market's largest volume segment.
- Connectivity Limitations:The performance of smart helmets with real-time data transmission is often compromised in GPS-denied environments like mines or dense urban construction sites, limiting their utility.
Strategic Opportunities
- Specialized Energy Sector Applications:Developing helmets tailored for the unique hazards of renewable energy maintenance, such as electrical shock protection for solar farm technicians or fall protection for wind turbine crews.
- Augmented Reality Integration:Combining head protection with AR displays to overlay schematics or remote expert guidance for technicians in complex industrial maintenance and repair applications. li>Data-as-a-Service Models: Offering subscription-based services for the data analytics platforms that process information from smart helmets, creating recurring revenue streams beyond the initial hardware sale.
Industry Challenges
- Dual-Certification Hurdles:Manufacturers of smart helmets face the challenge of securing compliance with both ANSI Z89.1 for physical protection and FCC regulations for wireless electronic components, lengthening development cycles.
- Data Interoperability:A lack of standardization in data formats and communication protocols among different smart helmet brands hinders the ability of large enterprises to deploy a unified connected-worker safety platform.
- Workforce Training Gaps:A shortage of site supervisors and safety managers trained to effectively interpret and act upon the real-time data generated by large-scale deployments of connected safety equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Safety Helmet Market |
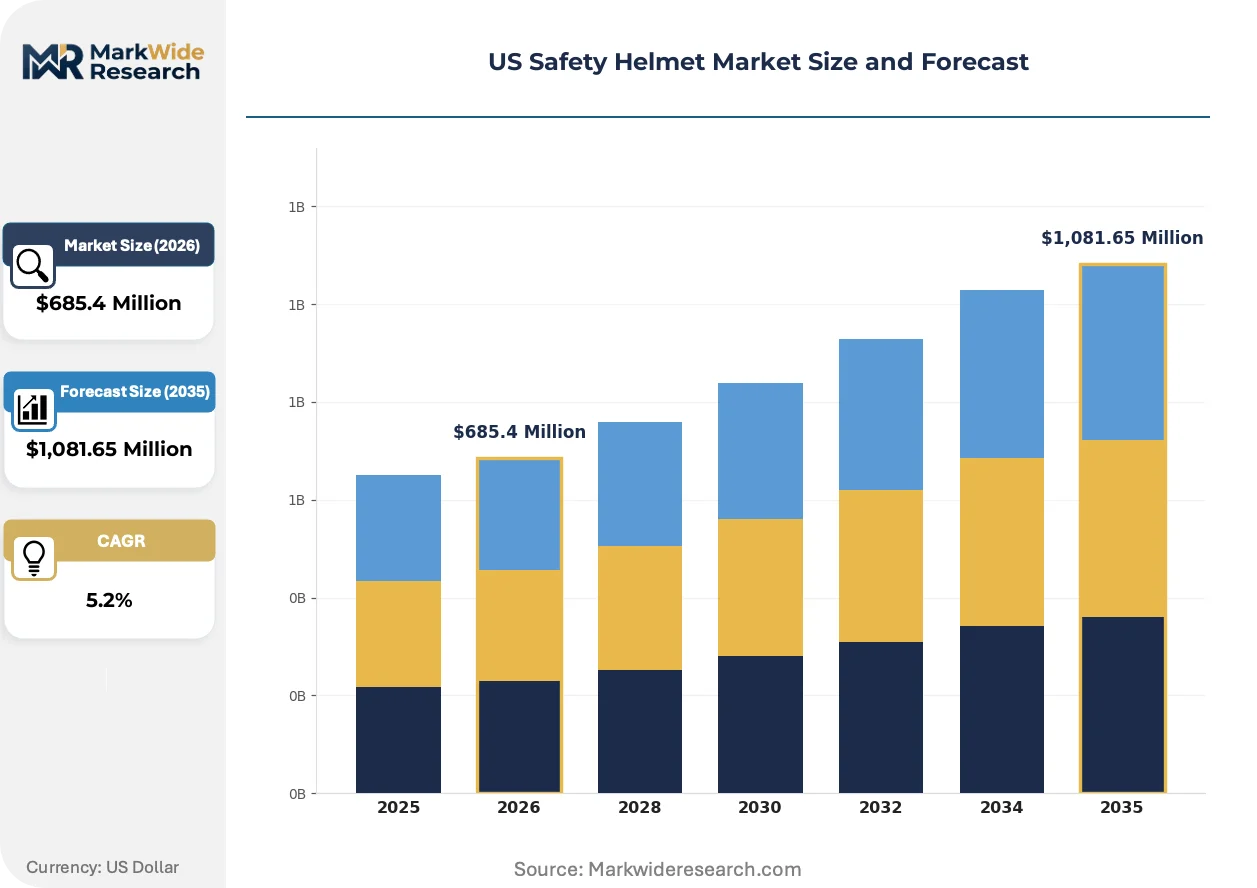
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Hats, Bump Caps, Climbing Helmets, Welding Helmets End User: Construction, Manufacturing, Mining, Sports Material: Polycarbonate, Fiber-reinforced Plastic, HDPE, ABS Feature: Impact Resistance, Ventilation, Lightweight, Noise Reduction |
| Companies Covered | Bullard, JSP Ltd., 3M, Pyramex, Drägerwerk AG & Co. KGaA, Honeywell International Inc., Delta Plus Group, OccuNomix International LLC, MSA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Safety Helmet Market Strategic Shifts & Innovations
The fundamental role of the safety helmet is expanding from a passive protective device to an active, data-collecting node within a connected worksite safety ecosystem. This evolution is driven by the integration of digital technologies that provide unprecedented visibility into worker safety and environmental hazards.
Embedded sensors and wireless transceivers are transforming helmets into intelligent devices that monitor for impacts, falls, and proximity to hazards. High-risk sectors such as mining, utilities, and heavy construction are leading the adoption for real-time worker status monitoring. This technology is virtualizing the safety manager's oversight, enabling remote supervision of an entire workforce and immediate alerts to incidents without direct line of sight.
The American National Standards Institute's revision to the ANSI Z89.1 standard now includes more explicit requirements and testing for Type II helmets, which provide protection from lateral impacts. This regulatory update is compelling a shift in product design away from traditional shells that primarily guard against top impacts. The construction and electrical utility sectors are most affected, prompting safety officers to re-evaluate their personal protective equipment standards.
A shift towards total-cost-of-ownership analysis is altering buying criteria for head protection. This approach moves the purchasing decision beyond the initial unit price, incorporating the potential financial benefits of reduced incident rates and lower insurance premiums associated with advanced or smart helmets. This behavioral change is most apparent among large, self-insured corporations in the US energy and civil infrastructure sectors.
US Safety Helmet Market Segmentation
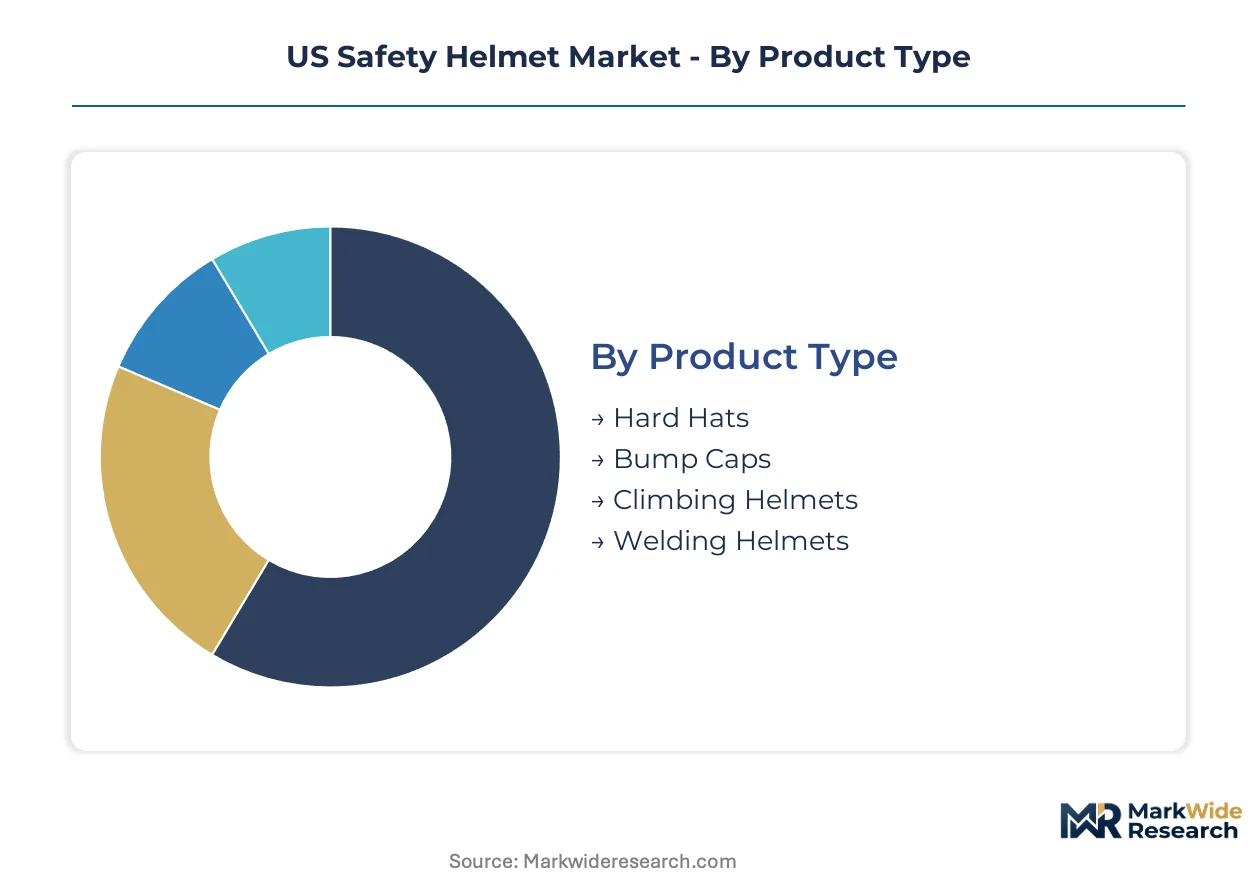
The US safety helmet market's segmentation reveals a diverse landscape driven by varying end-user requirements and technological advancements. Understanding these distinct segments is crucial for manufacturers to tailor product development and market strategies effectively. This granular view highlights areas of established demand and emerging growth.
Product Type:
The product type dimension categorizes head protection equipment by its fundamental design and intended use.
- Hard Hats:These traditional helmets primarily protect against top impacts and falling objects, often constructed from HDPE for durability. Demand concentrates in the construction and manufacturing sectors, driven by broad OSHA mandates for basic head protection.
- Welding Helmets:Specialized helmets integrate eye and face protection with head protection, featuring auto-darkening filters for arc flash safety. These are critical in fabrication and heavy industrial settings where workers face intense heat, sparks, and optical hazards.
- Bump Caps:Lightweight head coverings for minor bumps and scrapes, offering less impact protection than hard hats. These are used in environments with low risk of falling objects, such as food processing.
- Climbing Helmets:Engineered for fall protection and overhead impact in vertical work, featuring a chinstrap and lighter shell. Utility maintenance and wind turbine technicians increasingly adopt these.
Hard Hats commands the established base. The steepest expansion runs through Welding Helmets.
End User:
The market's application focus delineates demand based on specific industry operational hazards and regulatory compliance.
- Construction:This segment represents the largest consumer of safety helmets, driven by extensive infrastructure projects and stringent OSHA regulations for site safety. Helmets protect against falling debris, impacts, and electrical hazards inherent to building sites.
- Mining:Workers in underground and surface mining operations require robust head protection against rockfalls, impacts, and often integrated lighting and communication systems. The demanding environments necessitate high-performance helmets meeting specific MSHA standards.
- Manufacturing:Industrial facilities utilize safety helmets to protect workers from machinery, falling tools, and overhead hazards. Cost-effective HDPE hard hats dominate procurement.
- Sports:This segment includes helmets for recreational and professional athletic activities, focusing on impact absorption and ventilation. This differs from industrial safety but shares material science advancements.
The construction sector drives the largest volume, while specialized industrial applications like mining are gaining market share.
Material:
The compositional attributes of safety helmets dictate their protective qualities, weight, and cost-effectiveness.
- HDPE (High-Density Polyethylene):This material is cost-effective and durable, making it the most common choice for general-purpose hard hats. It dominates the construction and manufacturing end-user segments due to its balance of protection and affordability.
- Fiber-reinforced Plastic:Offering superior strength-to-weight ratios and enhanced impact resistance, these materials are preferred for specialized applications. Mining and utility workers benefit from their robust performance in demanding environments.
- Polycarbonate:Known for high impact strength and optical clarity, polycarbonate is used in visors and some helmet shells. It offers a lighter alternative for applications requiring reduced weight.
- ABS (Acrylonitrile Butadiene Styrene):A thermoplastic polymer offering good impact resistance and rigidity, often used in standard safety helmets. It provides a balance of performance and cost for various industrial applications.
HDPE materials continue to form the market's foundation, yet advanced composites are increasingly favored for enhanced performance needs.
Feature:
Performance characteristics differentiate safety helmets, addressing specific hazards and user comfort requirements.
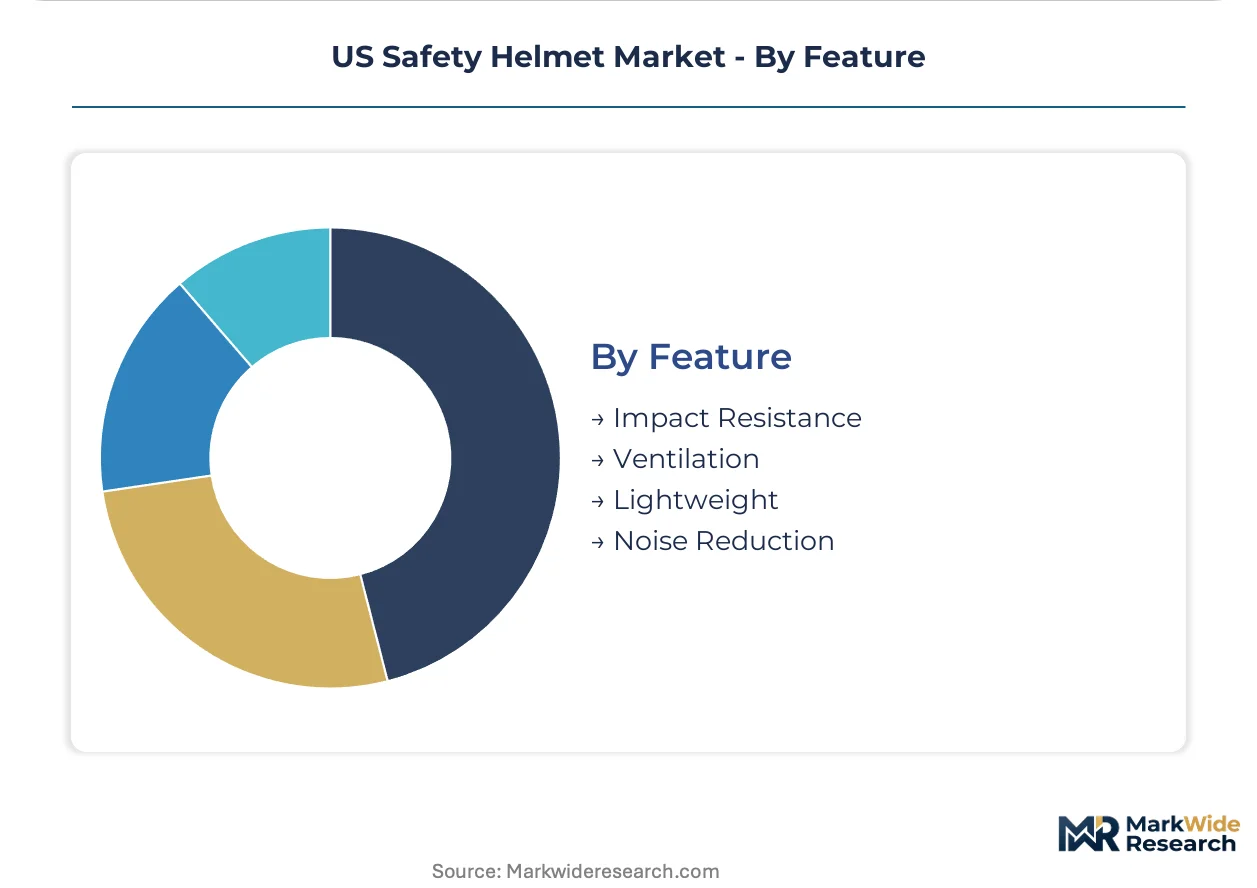
- Impact Resistance:This fundamental feature ensures head protection from falling objects, collisions, and side impacts, meeting ANSI Z89.1 standards. Enhanced impact resistance is critical in high-risk environments like heavy construction and mining.
- Lightweight:Reducing helmet weight improves wearer comfort and reduces neck strain during prolonged use, especially with integrated smart technologies. This feature is gaining importance in sectors like renewable energy maintenance and utilities.
- Ventilation:Integrated vents and channels improve airflow, reducing heat buildup and enhancing wearer comfort in hot climates or strenuous work. This is valued in outdoor construction and agricultural settings.
- Noise Reduction:Helmets with integrated hearing protection or sound-dampening shells are crucial in loud industrial environments. Manufacturing plants and heavy machinery operators benefit from this combined safety.
Core impact protection remains paramount, with enhanced comfort features like lightweight designs increasingly influencing purchasing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Occupational Safety and Health Administration (OSHA) mandates head protection across US industries, establishing a compliance floor for safety helmet demand. This regulatory environment, combined with substantial infrastructure investments, shapes distinct market dynamics across various regions. Regional economic activity and specific industry concentrations influence product adoption and purchasing patterns.
Texas
Extensive oil and gas exploration, alongside large-scale infrastructure projects, generates significant demand for robust safety helmets. Texas benefits from federal infrastructure legislation, increasing worker volume in construction and utility maintenance. The Houston and Dallas-Fort Worth metropolitan areas serve as hubs for heavy industrial and construction activity, driving procurement volumes.
Florida
Rapid population growth and ongoing residential and commercial construction projects drive substantial helmet demand in Florida. State-level initiatives for hurricane preparedness and infrastructure upgrades reinforce the need for durable head protection. The Orlando and Miami regions experience continuous construction booms, concentrating procurement for both basic and advanced safety gear.
California
Large-scale public works projects and the state's strong emphasis on worker safety regulations underpin demand for advanced safety helmets. California's strict adherence to Cal/OSHA standards encourages the adoption of higher-performance and smart helmet technologies. The San Francisco Bay Area and Los Angeles basin are centers for innovative construction practices and technology integration in safety equipment.
Northeast Corridor
Urban redevelopment projects and extensive transportation infrastructure maintenance characterize demand in the Northeast Corridor. This region's dense industrial base and aging infrastructure require constant repair and upgrade, necessitating head protection. Major cities like New York City, Boston, and Philadelphia drive consistent demand for safety helmets in diverse construction and utility environments.
US Safety Helmet Market Key Industry Players
Cost-sensitive commodity suppliers and premium technology innovators split the market for US safety helmets. This bifurcation reflects the dual demand poles of basic compliance and advanced performance requirements. Strategic archetypes include diversified industrial conglomerates, specialized safety equipment manufacturers, and emerging smart technology providers. Companies frequently engage in portfolio diversification to address various end-user needs and pursue strategic partnerships for technology integration.
Specialists in high-performance safety solutions include Bullard, known for its focus on thermal imaging and firefighter helmet designs. Honeywell International Inc. leverages its extensive distribution network to serve large industrial accounts, spanning a broad product portfolio. MSA occupies a position as a leader in high-performance head protection for demanding environments like mining and utilities, emphasizing specialized applications.
| Leading Market Players |
|---|
| Bullard |
| JSP Ltd. |
| 3M |
| Pyramex |
| Drägerwerk AG & Co. KGaA |
| Honeywell International Inc. |
| Delta Plus Group |
| OccuNomix International LLC |
| MSA |
| Others |
Cost & Logistics Intelligence
Underutilized domestic manufacturing capacity in the Southeastern US influences supplier pricing strategies, balancing import competition with regional demand fulfillment. This capacity dynamic shapes the cost structures for various helmet types.
Pricing Analysis
Regional disparities in labor costs and material sourcing create distinct geographic price spreads for safety helmets across the US. Per-unit transactional pricing dominates for standard hard hats, while value-based models emerge for smart helmets. Price differentiation stems from ANSI Z89.1 certification levels and integrated technology features. Pricing softness reflects commoditization pressure from high-volume HDPE products, making construction procurement managers highly price-sensitive compared to specialized industrial buyers.
Supply Chain Analysis
Extended payment terms for large industrial accounts characterize supplier financing within the US safety helmet market. Geographic supply concentration draws from both domestic US production, particularly in the Southeast, and imports from Asia. Raw material dependencies center on High-Density Polyethylene (HDPE), polycarbonate, and specialized electronic components for smart helmets. Regulatory shifts, such as new FCC requirements for wireless components, pose a structural risk, while distribution runs through a network of industrial safety equipment distributors and direct-to-enterprise channels for major manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a challenge in integrating advanced digital technologies with core safety compliance, creating a scarcity of engineering expertise in dual-certification processes. This gap limits rapid innovation and market penetration for smart helmet solutions.
For Market Incumbents:Pre-empt commoditization pressure in the basic hard hat segment by investing in advanced material science for enhanced impact resistance. Diversify product portfolios to include smart helmet features, mitigating the threat from specialized tech entrants. Secure long-term supply agreements for critical electronic components to maintain competitive pricing.
For New Entrants and Emerging Players:Build out specialized platforms for data-as-a-service models, leveraging the growing demand for connected worksite safety. Target the renewable energy sector due to its high-risk applications and willingness to adopt advanced safety solutions. A direct-to-enterprise sales model, emphasizing total-cost-of-ownership, will penetrate these specialized niches effectively.
For Investors and Strategic Acquirers:Long-term, this sits as a technology integration play because core safety requirements merge with digital innovation. Acquisition targets should be niche firms with proven smart helmet IP or data analytics platforms. The signal to watch is the widespread adoption of ANSI Z89.1 Type II standards across large infrastructure projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Smart Helmet Integration Platform | This initiative establishes a unified ecosystem for connected worker safety data. |
| Invest in Advanced Material R&D | This enhances impact protection and reduces helmet weight for user comfort. |
| Expand Direct-to-Enterprise Sales Channels | This reaches large industrial accounts seeking custom safety solutions efficiently. |
| Acquire Niche Biometric Sensor Developer | This integrates real-time health monitoring capabilities into next-generation helmets. |
| Pursue Dual ANSI/FCC Certification Expertise | This streamlines compliance for electronic safety equipment, accelerating market entry. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings and quantitative estimates. The analysis incorporated insights from safety managers, procurement officers, R&D engineers, and OSHA compliance specialists. Secondary validation drew from ANSI standards, OSHA enforcement data, trade publications, and company reports. Bottom-up market sizing was triangulated with top-down industry expenditure figures.
Calibration of historical market performance against macroeconomic indicators informed the forecast framework. Segmentation dimensions modeled include product type, end user, material, feature, and technology integration level. Compound Annual Growth Rates (CAGRs) were derived through regression analysis, considering market drivers and restraints across the projection horizon. Key forecast inputs included infrastructure spending projections and smart helmet adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified industrial conglomerates or specialized tech providers would shift outcomes. The analysis assumes stable regulatory environments and consistent material supply. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
Digital Camlock Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Snowmobile Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Monitoring and Dosimeter Badges Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market